
 North Sea Offshore Decommissioning Market | 2026-2036
North Sea Offshore Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
North Sea Offshore Decommissioning Market Analytics
Buyer concentration among North Sea oil and gas operators is pivoting toward a smaller cohort of supermajors and national oil companies retaining decommissioning liabilities on their balance sheets. Aker Solutions ASA leverages its integrated engineering and heavy-lift vessel fleet to dominate complex platform removal campaigns across Norwegian and UK waters. TechnipFMC PLC anchors its position through subsea infrastructure expertise, while Heerema Marine Contractors sustains competitive advantage with its semi-submersible crane vessels purpose-built for single-lift platform removals.
North Sea offshore decommissioning encompasses the engineered dismantling, removal, and environmental remediation of oil and gas platforms, subsea pipelines, and wellheads from the seabed to surface, typically requiring cutting operations at depths exceeding 100 meters using heavy-lift vessels and remotely operated vehicles. The primary purpose is to restore marine environments to pre-production conditions while recovering recyclable steel and managing hazardous hydrocarbon residues. Well plugging and structure removal command the largest service expenditure pools, reflecting the technical complexity and regulatory stringency of permanent well abandonment and topside lift operations. ROV operations and marine survey represent the fastest-growing technology segments, driven by precision requirements for seabed clearance verification and pipeline debris tracking.
The UK Petroleum Act and Norway's Petroleum Activities Act establish the legal backbone for decommissioning obligations, while the OSPAR Convention mandates complete removal of offshore installations to prevent seabed habitat disruption. The UK Oil and Gas Authority and Norway's Petroleum Safety Authority enforce compliance timelines and cost benchmarking, directly shaping contractor procurement cycles and project phasing decisions. Stakeholders must monitor regulatory shifts around liability transfer mechanisms and emerging EU marine environmental standards that could extend monitoring obligations beyond current remediation horizons.
Market Dynamics
The North Sea offshore decommissioning market is being fundamentally restructured by the OSPAR Convention's complete removal mandate, which forces operators to dismantle rather than abandon aging steel jackets and concrete gravity bases. This regulatory pressure is compressing project timelines and concentrating procurement authority among a shrinking pool of supermajors with balance sheet capacity to absorb multi-billion-pound liabilities.
Growth Catalysts
- OSPAR Decision 98/3:The convention's prohibition on derogation from full removal creates irreversible demand for platform dismantling services across UK, Norwegian, and Danish waters.
- Well abandonment campaigns:Mature reservoirs in the UK Central and Northern North Sea are triggering simultaneous plugging and abandonment programs for thousands of subsea wells.
- Heavy-lift vessel specialization:Purpose-built semi-submersible crane vessels with 5,000-tonne lift capacity are enabling single-lift topside removals that slash campaign duration.
Market Restraints
- Scarce heavy-lift vessel availability:Only five vessels worldwide possess the crane capacity and dynamic positioning systems required for integrated platform removals, creating supply bottlenecks.
- Steel price volatility:Fluctuations in scrap steel markets directly impact project economics for operators recycling platform jackets, with price swings of 40% within single fiscal years.
- Petroleum Safety Authority Norway's cost benchmarking:Mandatory cost-efficiency reviews extend procurement cycles and compress contractor margins on Norwegian continental shelf projects.
Strategic Opportunities
- UK Southern North Sea gas platforms:Hundreds of small-tonnage installations reaching end-of-life present bundled removal opportunities for mid-tier contractors lacking ultra-heavy-lift capability.
- Pipeline pre-commissioning to decommissioning pivot:Subsea engineering firms with pipeline installation heritage are repurposing pigging and flooding expertise for pipeline cleaning and abandonment.
- EU Marine Strategy Framework Directive:Emerging monitoring obligations beyond current remediation horizons create extended service contracts for environmental survey and seabed verification.
Industry Challenges
- ROV pilot and saturation diving shortages:The specialized workforce capable of operating inspection-class remotely operated vehicles at 150-meter depths is aging faster than training pipelines replenish.
- Legacy well data fragmentation:Incomplete cement bond logs and missing completion records from 1970s platform drilling campaigns force costly re-evaluation before abandonment.
- Cross-border liability allocation:Joint venture partners with divergent decommissioning timelines trigger disputes over cost-sharing when fields straddle UK-Norway median lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Sea Offshore Decommissioning Market |
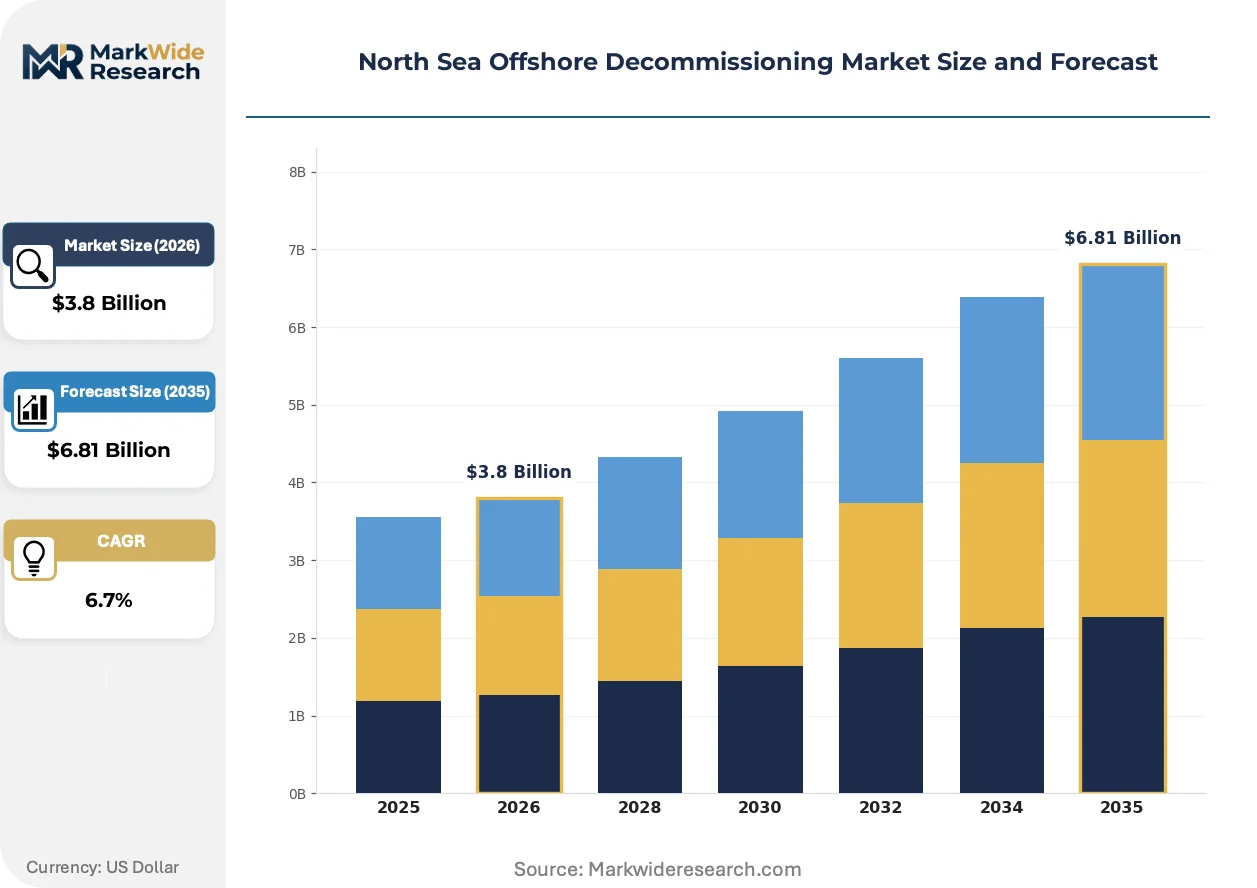
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Well Plugging, Structure Removal, Site Clearance, Waste Management Technology: Dismantling Technology, Cleaning Solutions, ROV Operations, Marine Survey End User: Oil & Gas Operators, Environmental Agencies, Contractors, Regulatory Bodies Project Phase: Planning, Execution, Monitoring, Remediation |
| Companies Covered | AF Gruppen, TechnipFMC PLC, Aker Solutions ASA, DeepOcean Group Holding BV, Able UK, Allseas Group, John Wood Group PLC, DNV GL, Heerema Marine Contractors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Sea Offshore Decommissioning Market Evolving Landscape
Digital twin technology and autonomous underwater vehicles are compressing survey timelines while regulators tighten seabed clearance verification standards. These shifts are simultaneously raising technical barriers and opening new service categories for technology-integrated contractors.
Remotely operated vehicle swarms equipped with multibeam sonar and magnetic anomaly detection are consolidating seabed survey operations previously requiring multiple vessel deployments. Norwegian operators are adopting these systems for pipeline debris tracking and clearance verification. The technology is consolidating marine survey spend around integrated contractors offering real-time data fusion from multiple sensor platforms.
The UK's Oil and Gas Authority introduced revised decommissioning cost estimates in its latest strategy, forcing operators to front-load financial provision earlier in field life. This industrial consequence is accelerating portfolio high-grading among independents unable to book future liabilities. Small-cap UKCS operators are responding by farming out equity to national oil companies with stronger balance sheets.
Integrated service contracts bundling engineering, heavy-lift, and waste management are displacing discrete procurement of individual work packages. Major operators in the Norwegian sector are consolidating vendor lists around three to four full-service decommissioning alliances. This concentration is most visible in UK Central North Sea campaigns where BP and Shell have adopted single-point-contractor models for complete platform removals.
North Sea Offshore Decommissioning Market Segmentation
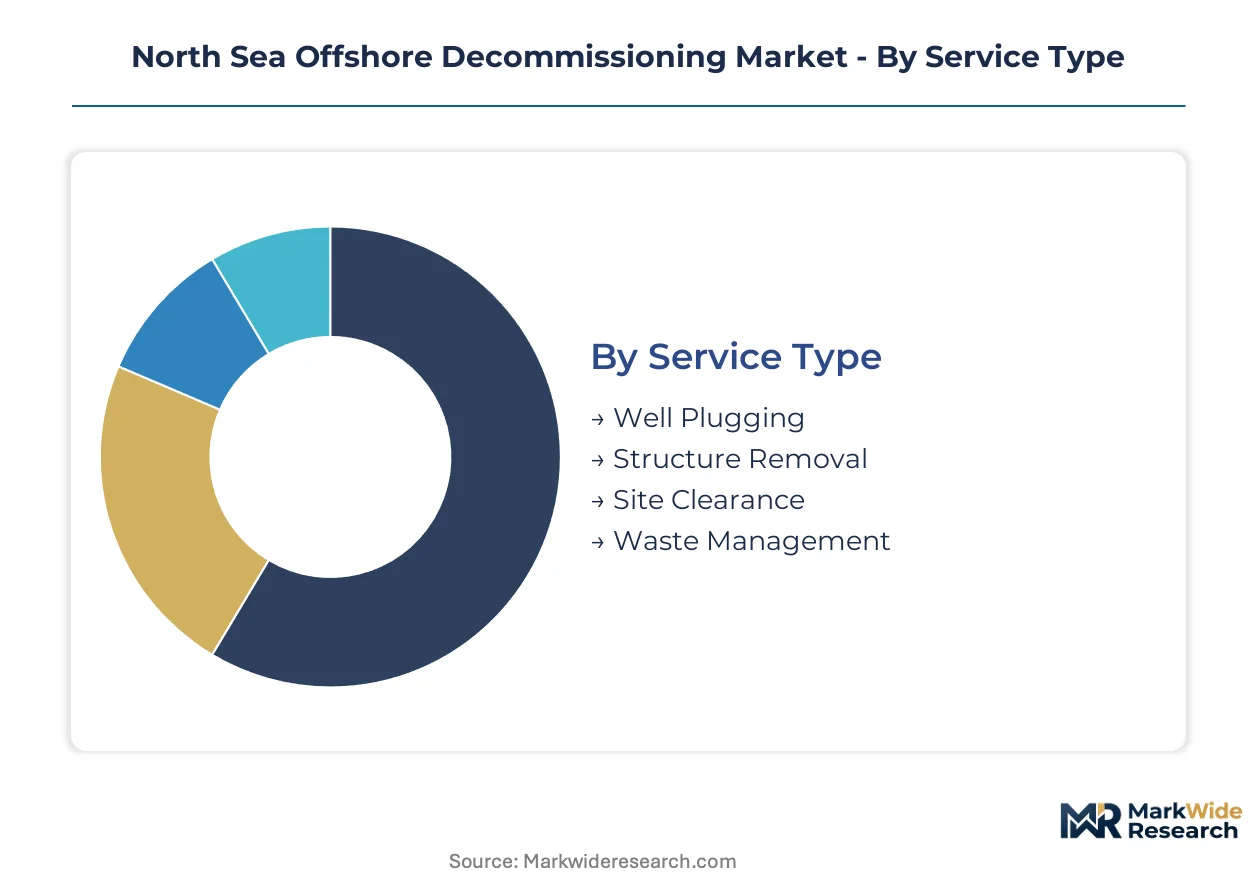
Decommissioning procurement in the North Sea splits sharply between standardized well abandonment programs and bespoke platform removal campaigns. Each segmentation dimension reveals distinct margin structures, capability requirements, and contractor specialization patterns that shape competitive positioning.
Service Type:
Standardized well plugging services contrast with heavily customized structure removal engineering across this category.
- Well Plugging:Cement barrier installation and mechanical plug deployment seal reservoir zones at depths exceeding 3,000 meters. UK Central North Sea operators concentrate demand here, driven by OSPAR-mandated permanent abandonment timelines and the Petroleum Safety Authority Norway's cost benchmarking protocols.
- Structure Removal:Single-lift topside extraction and jacket severing operations demand vessel-specific engineering for each platform's weight distribution and seabed fixation geometry. Norwegian continental shelf campaigns show steepest demand concentration, where concrete gravity bases and steel jackets require tailored cutting sequences.
- Site Clearance:Seabed debris removal and verification surveying restore marine habitats to pre-production conditions.
- Waste Management:Hydrocarbon residue processing and steel recycling coordination handles hazardous material streams from decommissioned assets.
Most installed capacity flows through Well Plugging. Expansion is steepest in Structure Removal.
Technology:
Technology selection tracks project phase maturity, with established dismantling methods giving way to precision survey and intervention systems.
- Dismantling Technology:Diamond wire cutting, explosive severing, and mechanical cold cutting systems sever platform legs and pipelines at subsea elevations. UK Southern North Sea gas platform campaigns drive demand, where bundled small-tonnage removals favor standardized cutting packages over bespoke engineering.
- ROV Operations:Work-class remotely operated vehicles with manipulator arms and tooling skids execute subsea interventions at 150-meter depths without saturation diving. Norwegian operators are expanding these systems fastest for pipeline debris tracking and clearance verification under tightening OSPAR standards.
- Cleaning Solutions:Pipeline pigging, chemical flushing, and nitrogen displacement remove hydrocarbon inventories before abandonment.
- Marine Survey:Multibeam sonar and magnetic anomaly detection map seabed conditions and verify installation removal completeness.
Most installed capacity flows through Dismantling Technology. ROV Operations are gaining share fastest as labor shortages bite and precision requirements tighten.
End User:
End user segmentation reflects liability concentration versus delegated execution across the decommissioning value chain.
- Oil & Gas Operators:Supermajors and national oil companies retain decommissioning liabilities on balance sheets and procure integrated service packages. UK and Norwegian operators dominate this segment, where the UK Petroleum Act and Norway's Petroleum Activities Act mandate full installation removal liability.
- Contractors:Heavy-lift vessel owners, subsea engineering firms, and waste management specialists execute removal campaigns under single-point or alliance contracts. Demand concentrates among integrated contractors offering bundled engineering, heavy-lift, and environmental remediation capabilities.
- Environmental Agencies:Regulatory bodies monitor compliance with seabed clearance standards and marine habitat restoration.
- Regulatory Bodies:The UK Oil and Gas Authority and Norway's Petroleum Safety Authority enforce cost benchmarking and timeline compliance.
Most installed capacity flows through Oil & Gas Operators. Contractor procurement is expanding most quickly as operators consolidate vendor lists around full-service alliances.
Project Phase:
Project phase segmentation distinguishes front-loaded engineering from execution-intensive removal operations.
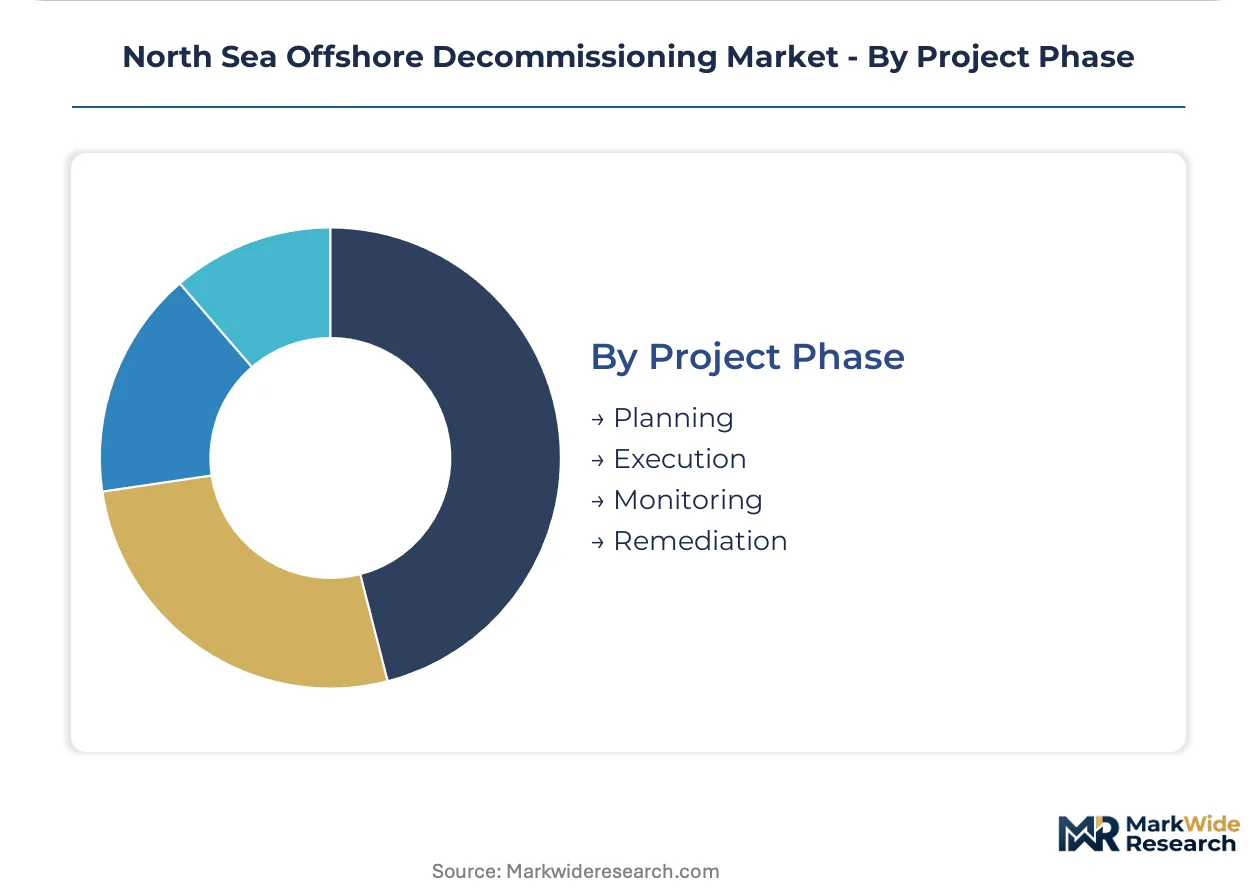
- Execution:Platform removal, well plugging, and waste processing operations consume the bulk of decommissioning expenditure. UK Central North Sea campaigns concentrate demand here, where BP and Shell have adopted single-point-contractor models for complete platform removals.
- Planning:Engineering design, procurement scheduling, and regulatory approval sequencing precedes physical removal. Norwegian projects show extended planning phase duration due to Petroleum Safety Authority Norway's mandatory cost-efficiency reviews.
- Monitoring:Seabed verification and environmental compliance tracking extends post-removal obligations.
- Remediation:Habitat restoration and extended environmental surveillance addresses residual contamination.
Most installed capacity flows through Execution. Planning is climbing the fastest as operators front-load financial provision earlier in field life under revised UK Oil and Gas Authority cost estimates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway commands the heaviest decommissioning liability burden per installation, while the United Kingdom manages the largest absolute volume of aging platforms requiring removal. Both jurisdictions operate under OSPAR-mandated complete removal obligations, yet their regulatory enforcement mechanisms and industrial capacity differ substantially.
United Kingdom
The UK Central and Southern North Sea host the greatest concentration of end-of-life steel jackets and gas platforms. The UK Petroleum Act imposes full liability for installation removal on license holders, while the Oil and Gas Authority enforces front-loaded financial provisioning through revised cost estimates. Aberdeen anchors the UK's decommissioning engineering cluster, where operators and contractors coordinate integrated removal campaigns.
Norway
Concrete gravity bases and complex steel structures in the Norwegian North Sea generate the highest per-project decommissioning expenditures. Norway's Petroleum Activities Act establishes strict removal obligations, with the Petroleum Safety Authority mandating cost-efficiency reviews that extend procurement cycles. Stavanger and Oslo concentrate engineering expertise for platform dismantling and subsea intervention planning.
Denmark
The Danish North Sea sector holds fewer installations but enforces equally stringent removal standards through the Danish Energy Agency. The DEA's decommissioning guidelines align with OSPAR Decision 98/3, requiring complete seabed clearance. Esbjerg serves as Denmark's primary offshore service hub, handling preparation for late-life field abandonments.
Netherlands
Dutch North Sea operators face overlapping EU marine environmental standards and national implementation of OSPAR obligations. The Netherlands' State Supervision of Mines oversees decommissioning compliance for aging gas production infrastructure. Rotterdam's heavy-lift and marine engineering capabilities support cross-border removal campaigns into UK and Danish waters.
Germany
Germany's limited North Sea offshore production still triggers decommissioning obligations under the Federal Mining Act and EU environmental directives. The Federal Maritime and Hydrographic Agency enforces seabed clearance standards for platform removals. Cuxhaven and Bremerhaven provide specialized vessel services and waste processing capacity for regional decommissioning demand.
North Sea Offshore Decommissioning Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the North Sea decommissioning value chain. The market structure concentrates procurement authority among integrated service providers capable of bundling engineering, heavy-lift, and environmental remediation. Three archetypes dominate: full-service decommissioning alliances, heavy-lift vessel operators with proprietary crane assets, and subsea engineering firms repurposing installation expertise for abandonment. Competitive positioning hinges on single-point-contractor models and strategic partnerships that lock in multi-campaign vessel utilization.
Within the full-service alliance tier, Aker Solutions ASA and TechnipFMC PLC exemplify integrated engineering-to-execution positioning. Heerema Marine Contractors anchors the heavy-lift vessel specialist archetype, with semi-submersible crane vessels purpose-built for single-lift platform removals. These three entities collectively represent the contracting models that supermajors and national oil companies favor for complex removal campaigns across Norwegian and UK waters.
| Leading Market Players |
|---|
| AF Gruppen |
| TechnipFMC PLC |
| Aker Solutions ASA |
| DeepOcean Group Holding BV |
| Able UK |
| Allseas Group |
| John Wood Group PLC |
| DNV GL |
| Heerema Marine Contractors |
| Others |
Value Network & Pricing Analysis
Integrated single-point procurement by UK and Norwegian supermajors is forcing heavy-lift vessel operators and subsea contractors into alliance structures that compress margins while locking in multi-campaign utilization. This buyer consolidation concentrates pricing power among operators with OSPAR-mandated removal obligations, compelling suppliers to absorb cost benchmarking pressures from Norway's Petroleum Safety Authority.
Pricing Analysis
Capacity additions in the North Sea heavy-lift vessel segment are reshaping price floors for platform removal campaigns. Project-based contracting dominates, with pricing stratifying across premium single-lift capabilities, standard modular dismantling, and economy bundled well abandonment packages. Cost compression in the mid-tier is intensifying because the Petroleum Safety Authority Norway's mandatory reviews extend procurement cycles. National oil companies exhibit lowest price sensitivity given balance sheet capacity, while small-cap UKCS independents face acute margin pressure.
Supply Chain Analysis
Steel recycling flows and hazardous waste processing create reverse-logistics complexity that tethers decommissioning economics to scrap metal volatility. Supply concentration rests on Norway, the United Kingdom, and the Netherlands for heavy-lift vessel marshalling and engineering coordination. Raw material dependencies draw from high-grade steel fabrication, dynamic positioning systems, and subsea cutting tooling. Single-source vulnerability runs through the five semi-submersible crane vessels worldwide capable of integrated platform removal. Distribution runs through Stavanger, Aberdeen, and Rotterdam as the primary offshore service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSPAR Decision 98/3 operates as a regulatory compounder, mandating complete installation removal and generating irreversible demand for dismantling services across UK, Norwegian, and Danish waters.
For Market Incumbents: Deepen vessel specialization and subsea engineering integration to defend against mid-tier contractors bundling small-tonnage removals. Lock in multi-campaign alliances with supermajors before Norway's Petroleum Safety Authority cost benchmarking compresses margins further. Prioritize captive control over ROV pilot training pipelines to offset saturation diving shortages. For New Entrants and Emerging Players: Capture bundled removal opportunities across UK Southern North Sea gas platforms where ultra-heavy-lift capability is unnecessary. Target pipeline pre-commissioning firms pivoting to abandonment services as the most penetrable entry vector. Lead with pigging and flooding expertise repurposed for pipeline cleaning under extended EU Marine Strategy Framework Directive monitoring obligations. For Investors and Strategic Acquirers: Asymmetric upside sits with subsea engineering firms possessing installation heritage and environmental survey capabilities. The five-to-ten-year viability window favors contractors with integrated data fusion from autonomous underwater vehicle swarms. Monitor Norway's Petroleum Safety Authority cost-efficiency review timelines as the critical inflection signal for margin compression acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Heavy-Lift Vessel Specialization | Heerema Marine Contractors' semi-submersible crane fleet enables single-lift topside removals that slash campaign duration. |
| Integrated Service Alliances | Aker Solutions bundles engineering, heavy-lift, and waste management under single-point contracts preferred by BP and Shell. |
| Autonomous Underwater Vehicle Swarms | Norwegian operators deploy multibeam sonar-equipped AUVs for pipeline debris tracking under tightening OSPAR clearance standards. |
| ROV Pilot Training Pipeline Investment | Work-class remotely operated vehicle operators address workforce aging faster than replenishment rates across UK and Norwegian sectors. |
| Digital Twin Technology Adoption | Real-time data fusion from multiple sensor platforms compresses seabed survey timelines while raising technical barriers for non-integrated contractors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with offshore project directors, heavy-lift vessel operators, regulatory compliance officers at the UK Oil and Gas Authority, and decommissioning procurement leads at supermajors with secondary validation against OSPAR compliance databases, Petroleum Safety Authority Norway cost benchmarking reports, and UK Petroleum Act enforcement records. Bottom-up project pipeline aggregation and top-down liability provisioning analysis triangulated market sizing.
Segment-weighting across service type, technology, end user, and project phase dimensions shaped the analytical framework across the projection horizon. CAGRs derived from installation age profiles, regulatory deadline clustering, and vessel availability constraints. Forecast inputs incorporated concrete gravity base removal complexity indices and well abandonment backlog depth by UKCS sector.
Vessel delivery delays, scrap steel price volatility, and regulatory timeline extensions are the dominant revision risks to decommissioning expenditure forecasts. Practitioners should monitor heavy-lift vessel drydock schedules and OSPAR interpretation shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Indonesia Oil and Gas Upstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Europe LNG Bunkering Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
North Sea Oil and Gas Market