
 Public Cloud System Infrastructure Service Market | 2026-2036
Public Cloud System Infrastructure Service Market Size, Share, and Industry Trends Forecast 2026-2036
Public Cloud System Infrastructure Service Market Analytics
Cloud infrastructure talent scarcity is bifurcating the competitive landscape into engineering-rich hyperscalers and specialized platform vendors. Amazon Web Services leverages its fifteen-year operational history and the broadest service catalog to sustain enterprise loyalty across regulated sectors. Microsoft Azure anchors hybrid cloud demand through deep integration with on-premises Windows Server and Office 365 estates. Google Cloud Platform differentiates on data analytics and AI-optimized silicon, competing aggressively for machine learning workloads.
Public Cloud System Infrastructure Service denotes remotely hosted compute, storage, and networking resources delivered over the internet with metered consumption, typically provisioned through virtualized multi-tenant architectures running on commodity x86 and ARM servers in geographically distributed availability zones. Its primary purpose is to replace capital-intensive on-premises data center ownership with elastic operational expenditure for variable workloads. Infrastructure as a Service commands the largest revenue share by abstracting bare-metal resources into programmatically accessible pools, while Disaster Recovery as a Service represents the fastest-expanding category as enterprises abandon secondary site construction for cloud-based failover orchestration. Platform as a Service captures disproportionate margin pools by binding developers to proprietary middleware and serverless execution environments.
US enterprises navigate overlapping compliance obligations from HIPAA for healthcare data, SEC cybersecurity disclosure rules for publicly traded firms, and state-level privacy statutes including California's CCPA that collectively mandate encryption, access logging, and geographic data residency. European operators face additional constraints from GDPR data-localization requirements and the EU AI Act's risk-classification framework for automated decision systems. Stakeholders must monitor how emerging sovereign cloud mandates in India, Brazil, and Saudi Arabia fragment previously unified global infrastructure footprints into jurisdictionally bounded operational zones.
Market Dynamics
Financial services institutions are accelerating migration of core banking workloads to cloud-native architectures, forcing infrastructure providers to rearchitect for sub-millisecond latency and multi-region failover capabilities previously reserved for proprietary mainframe environments.
Growth Catalysts
- EU AI Act risk-classification framework:Mandates for high-risk automated decision systems are compelling financial institutions and healthcare operators to adopt compliant cloud infrastructure with embedded audit trails and explainability tooling.
- ARM-based silicon proliferation:Hyperscalers deploying Graviton and Cobalt processors are reducing per-compute-hour costs for machine learning inference workloads, pulling price-sensitive enterprise buyers from on-premises GPU clusters.
- Disaster Recovery as a Service adoption:Enterprises abandoning secondary site construction for cloud-based failover orchestration are expanding addressable infrastructure spend into operational resilience budgets.
Market Restraints
- Specialized engineering talent scarcity:Cloud infrastructure operations require rare combinations of distributed systems expertise and regulated-sector compliance knowledge, constraining provider expansion velocity.
- Electricity cost volatility:Data center power consumption sensitivity to regional grid pricing creates margin compression in markets with carbon-transition-driven tariff restructuring.
- GDPR data-localization requirements:Geographic residency mandates fragment unified infrastructure footprints into jurisdictionally bounded operational zones, duplicating fixed costs across European availability regions.
Strategic Opportunities
- Sovereign cloud mandates in India and Brazil:National data localization laws are creating protected competitive arenas for compliant infrastructure providers willing to establish in-country operations.
- Serverless execution convergence with edge computing:Binding developers to proprietary middleware while distributing compute to 5G network edges opens new consumption tiers for latency-sensitive applications.
- SEC cybersecurity disclosure rules:Publicly traded firms facing mandatory incident reporting are expanding security-focused infrastructure procurement to demonstrate control environment maturity.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprise buyers demanding workload portability across AWS, Azure, and GCP environments strain provider differentiation strategies and increase integration engineering costs.
- HIPAA compliance certification timelines:Healthcare infrastructure deployments face extended validation cycles for encryption, access logging, and business associate agreement negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Cloud System Infrastructure Service Market |
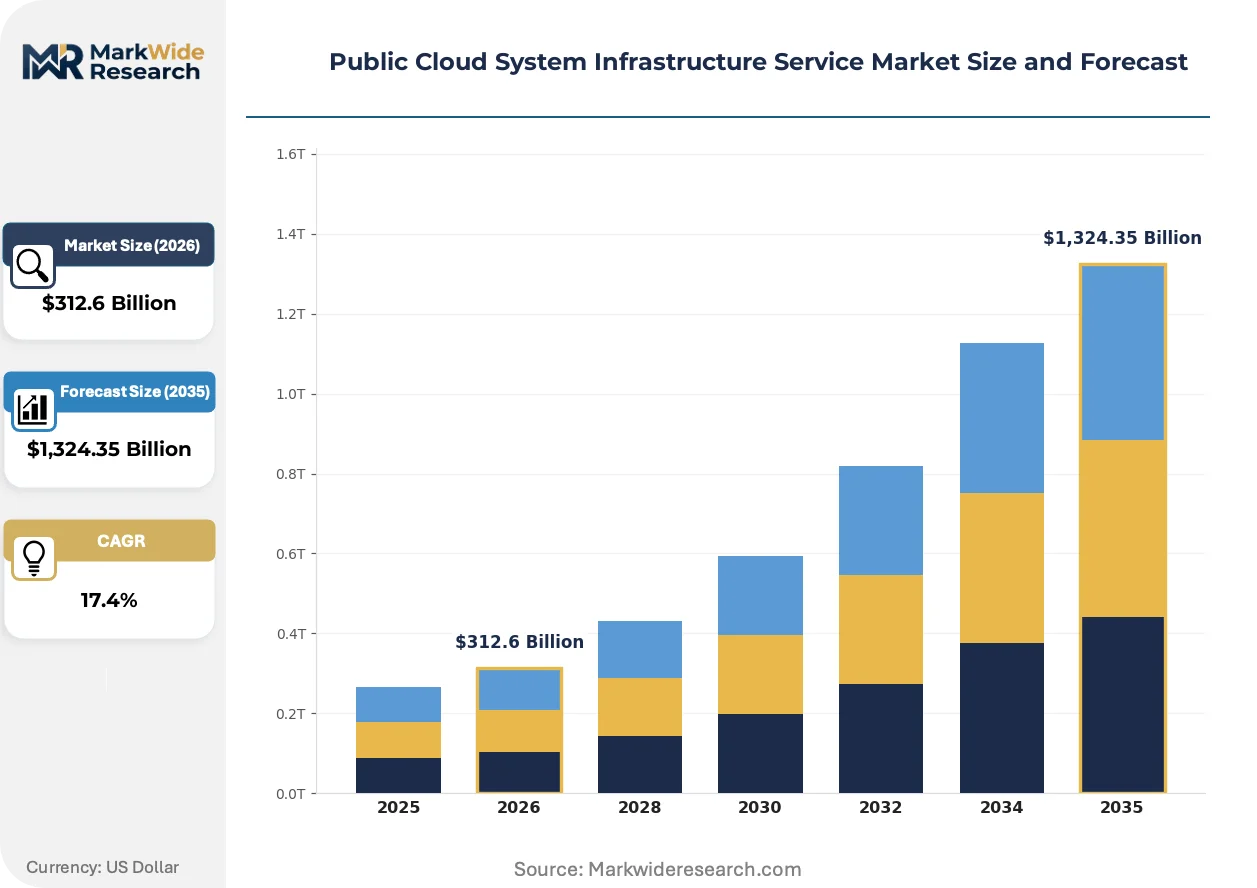
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,324.35 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Disaster Recovery as a Service Deployment Model: Multi-Cloud, Hybrid Cloud, Single-Tenant, Community Cloud End User: Startups, SMEs, Large Enterprises, Government Agencies Pricing Model: Pay-as-You-Go, Subscription-Based, Reserved Instances, Spot Pricing |
| Companies Covered | Oracle Cloud Infrastructure, Alibaba Cloud, Amazon Web Services, Huawei Cloud, Tencent Cloud, Microsoft Azure, IBM Cloud, DigitalOcean, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Cloud System Infrastructure Service Market Evolving Landscape
Cloud infrastructure is fragmenting into specialized execution environments optimized for specific workload characteristics, replacing the homogeneous virtual-machine paradigm that dominated the previous decade of enterprise adoption.
ARM-based Graviton and Cobalt processors are displacing x86 dominance in general-purpose compute tiers, with hyperscalers reporting 40% better price-performance for web serving and containerized microservices. Financial services firms are migrating batch analytics and risk modeling to these instances at accelerating velocity. The shift is compressing Intel and AMD server CPU attach rates in cloud data centers while expanding provider gross margins on equivalent compute sales.
GDPR's data-localization requirements and the EU AI Act's risk-classification framework are mandating architectural investments in geographic sovereignty controls and automated decision auditability. European operators must now maintain separate operational zones with distinct encryption key management and logging infrastructure. Healthcare and financial services segments face the steepest compliance burden, with infrastructure procurement decisions increasingly filtering through legal and risk functions rather than pure engineering evaluation.
Consumption-based pricing models are unbundling reserved capacity commitments from professional services engagement structures that previously locked buyers into multi-year relationships. Enterprise procurement teams are negotiating shorter-term contracts with granular usage transparency, replacing the three-year enterprise agreements that dominated early cloud adoption. This pattern is most visible in United States technology and media verticals, where finance departments demand monthly cost attribution to specific product lines and engineering teams.
Public Cloud System Infrastructure Service Market Segmentation
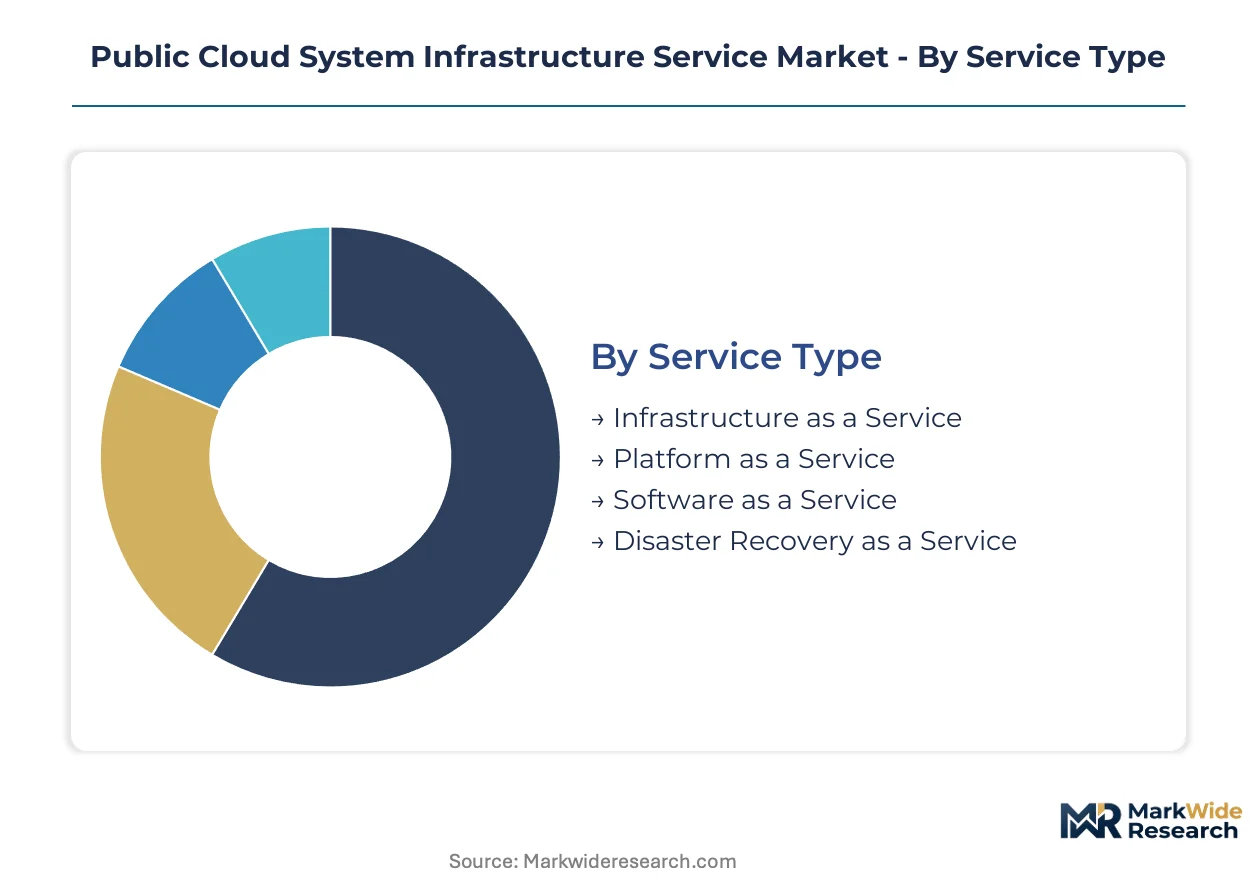
Cloud infrastructure procurement channels vary sharply by segment maturity and buyer sophistication. Enterprise sales teams, self-serve portals, and managed service intermediaries each dominate specific configuration paths. Segment boundaries are blurring as hyperscalers bundle adjacent services into unified consumption tiers.
Service Type:
Infrastructure as a Service flows primarily through direct enterprise sales and solution architect engagements, while Platform as a Service and Disaster Recovery as a Service increasingly route through channel partners and managed service providers.
- Infrastructure as a Service:Virtualized compute, storage, and networking resources provisioned through APIs and web consoles. Demand concentrates among large enterprises migrating on-premises data centers, driven by capital expenditure reduction mandates and elastic capacity requirements. By volume, Infrastructure as a Service leads. By growth pace, Disaster Recovery as a Service is climbing the fastest.
- Platform as a Service:Application development and deployment environments with embedded middleware, databases, and serverless execution runtimes. Startups and independent software vendors in North America represent the core demand pool, attracted by reduced operational overhead and accelerated release cycles.
- Software as a Service:End-user applications delivered over the internet with underlying infrastructure fully abstracted. Procurement flows through vendor-direct subscriptions and cloud marketplaces, with enterprise buyers negotiating centralized billing arrangements.
- Disaster Recovery as a Service:Automated failover orchestration and backup replication replacing secondary physical sites. Financial services institutions and healthcare operators in regulated jurisdictions are expanding procurement most aggressively as compliance deadlines tighten.
Infrastructure as a Service commands the largest revenue base. Disaster Recovery as a Service is gaining share fastest as resilience budgets shift from capital projects to operational subscriptions.
Deployment Model:
Cost tier differentiation separates commodity multi-tenant configurations from premium single-tenant and sovereign community cloud alternatives with dedicated hardware isolation.
- Multi-Cloud:Workload distribution across two or more hyperscaler environments to mitigate vendor lock-in and optimize price-performance by function. Technology and media enterprises in the United States lead adoption, driven by negotiation leverage and specialized service access.
- Hybrid Cloud:Integrated on-premises and public cloud infrastructure with unified management planes. Manufacturing and retail sectors with legacy application dependencies represent the core demand concentration, requiring seamless workload portability between owned facilities and cloud regions.
- Single-Tenant:Physically isolated infrastructure dedicated to one customer with no resource sharing. Regulated financial institutions and defense contractors mandate this configuration for sensitive workloads, accepting premium pricing for compliance assurance.
- Community Cloud:Shared infrastructure serving specific industry verticals or government constituencies with common compliance requirements. European healthcare networks and United States federal agencies are expanding procurement through certified community cloud frameworks.
Hybrid Cloud retains the largest installed footprint. Multi-Cloud configurations are expanding most quickly as enterprise architecture teams mandate portability clauses in procurement policies.
End User:
Application intensity and procurement sophistication create four distinct customer tiers with diverging support requirements and contract structures.
- Startups:Venture-backed technology firms with variable workloads and minimal legacy infrastructure. Self-service portal adoption dominates, with engineering teams provisioning resources directly through credit-card billing and programmatic API access.
- SMEs:Mid-market enterprises with steady-state workloads and limited dedicated technical staff. Managed service providers and value-added resellers capture disproportionate influence in this segment by bundling infrastructure with operational support.
- Large Enterprises:Fortune 500 and equivalent organizations with multi-region requirements and complex compliance obligations. Direct hyperscaler relationships with dedicated customer success teams and custom pricing agreements characterize this tier.
- Government Agencies:Federal, state, and municipal entities with sovereign data requirements and certified procurement vehicles. FedRAMP, StateRAMP, and equivalent national certification programs gate market access in the United States and comparable jurisdictions.
Large Enterprises generate the highest absolute revenue per account. Startups are expanding fastest by account count as cloud-native founding patterns become standard practice.
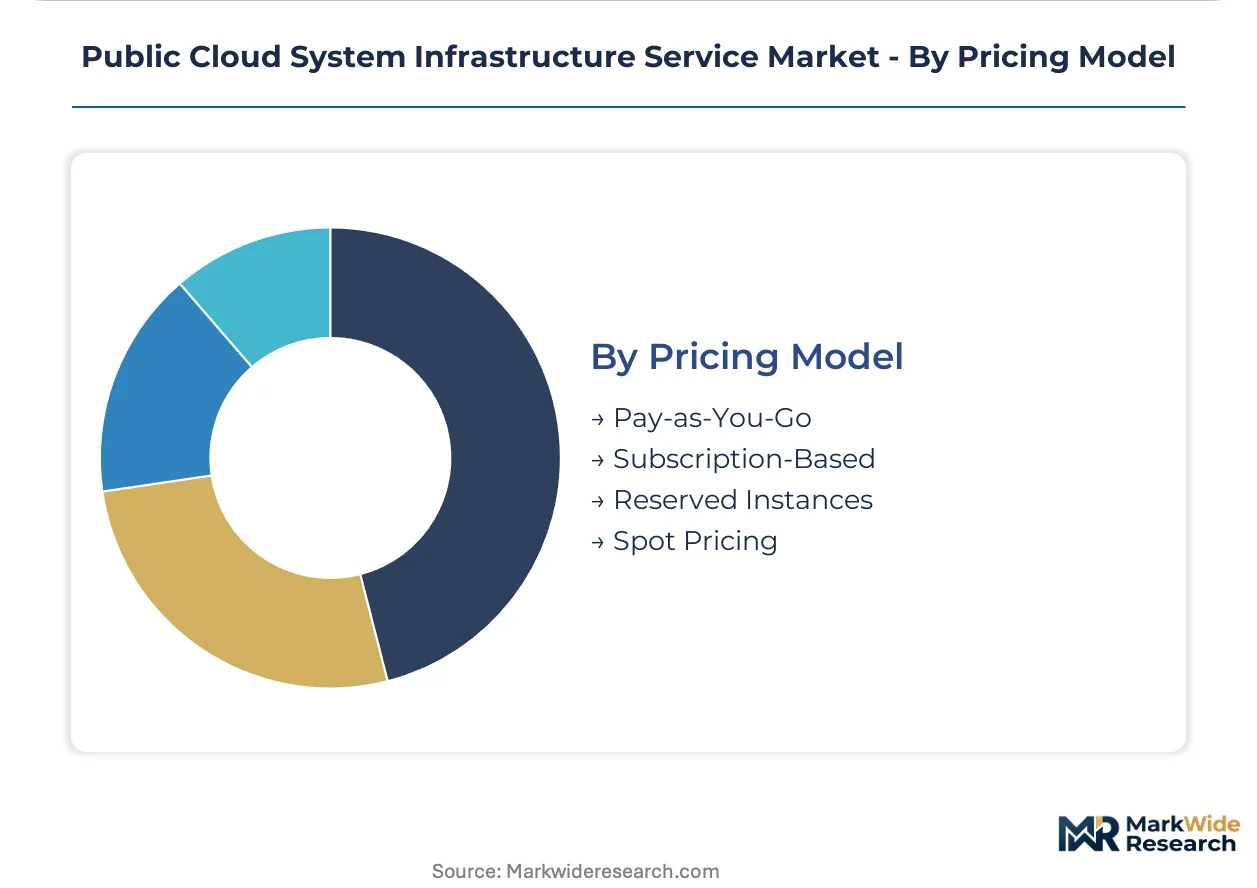
Pricing Model:
Commitment depth and predictability requirements segment buyers across a spectrum from fully variable to fully reserved consumption structures.
- Pay-as-You-Go:Metered consumption with no upfront commitment and per-hour or per-second billing granularity. Development and test environments, seasonal workloads, and experimental machine learning training jobs concentrate in this tier.
- Subscription-Based:Fixed recurring fees for bundled service packages with defined capacity limits. SMEs with predictable growth trajectories favor this structure for budget certainty and simplified forecasting.
- Reserved Instances:One to three-year capacity commitments exchanged for discounted hourly rates. Large enterprises with stable production workloads capture 30-60% cost reductions through this mechanism.
- Spot Pricing:Access to excess capacity at volatile discount rates with interruption risk. Batch processing, video rendering, and fault-tolerant analytics workloads exploit this tier for cost optimization.
Reserved Instances anchor the largest committed revenue base. Spot Pricing is expanding most quickly as automated workload orchestration matures and interruptible compute patterns proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC cybersecurity disclosure rules and HIPAA compliance mandates anchor the United States as the dominant geography, with hyperscaler regions and enterprise procurement density creating the largest revenue concentration worldwide.
United States
Financial services migration to cloud-native architectures and healthcare data expansion drive procurement intensity. SEC disclosure rules mandate incident reporting and control environment documentation for publicly traded firms. Northern Virginia's data center corridor hosts the densest concentration of hyperscale facilities globally, with Microsoft Azure and Amazon Web Services operating multiple availability zones within fifty miles.
Germany
Automotive manufacturers and industrial machinery producers require low-latency edge infrastructure for factory automation. GDPR data-localization requirements and the EU AI Act's risk-classification framework impose strict geographic residency controls. Frankfurt's financial district anchors continental Europe's primary cloud region, with compliance-certified facilities serving banking and insurance workloads.
United Kingdom
Fintech startups and established banks compete for elastic compute capacity to power real-time payment systems. The Financial Conduct Authority's operational resilience regulations mandate multi-region failover capabilities. London's Tech City cluster concentrates venture-backed cloud-native enterprises, driving self-service portal adoption and API-first procurement patterns.
India
Digital payment proliferation and e-commerce platform scaling generate explosive infrastructure demand. The RBI's data localization directive and proposed Digital Personal Data Protection Act require in-country storage for financial transaction records. Mumbai and Bangalore host the dominant hyperscaler regions, with Bangalore's Whitefield corridor emerging as the primary node for AI training workload expansion.
Japan
Manufacturing supply chain digitization and robotics integration require specialized edge computing deployments. METI's cybersecurity framework for critical infrastructure imposes stringent access logging and encryption standards. Tokyo's Otemachi financial district and Osaka's manufacturing belt concentrate enterprise procurement, with regional providers competing against hyperscaler expansion.
Public Cloud System Infrastructure Service Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscalers commanding infrastructure scale while platform vendors capture vertical-specific workloads. The competitive structure separates engineering-rich operational platforms from compliance-focused sovereign cloud operators. Three archetypes dominate: full-stack hyperscalers with fifteen-year operational histories, Asia-Pacific challengers leveraging domestic market protection, and specialized vendors targeting developer-centric segments. Market evolution proceeds through strategic partnerships with telecommunications carriers and geographic expansion into mandated sovereign zones.
Within the full-stack hyperscaler tier, Amazon Web Services and Microsoft Azure exemplify operational maturity and enterprise loyalty across regulated sectors. Alibaba Cloud and Tencent Cloud occupy positions within the Asia-Pacific challenger archetype, benefiting from data localization requirements in their domestic markets. Oracle Cloud Infrastructure represents the enterprise software extension model, anchoring database-centric workload migration patterns.
| Leading Market Players |
|---|
| Oracle Cloud Infrastructure |
| Alibaba Cloud |
| Amazon Web Services |
| Huawei Cloud |
| Tencent Cloud |
| Microsoft Azure |
| IBM Cloud |
| DigitalOcean |
| Google Cloud Platform |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for ARM-based server deployments from Taiwan semiconductor foundries concentrate pricing power with hyperscalers capable of forward capacity commitments, while spot-market buyers absorb volatility through interruptible compute tiers. This inventory dynamic binds infrastructure economics to silicon supply geography and reinforces multi-year contract premiums for guaranteed capacity.
Pricing Analysis
United States-East Asia price spreads of 15-25% for equivalent compute instances reflect electricity cost differentials and carbon-transition tariff structures. Three-tier pricing structure across reserved capacity, on-demand consumption, and spot-market interruptibility dominates enterprise procurement. Price differentiation rests on compliance certification level—FedRAMP-authorized workloads command 40-60% premiums over standard multi-tenant configurations. Pricing pressure stems from ARM silicon commoditization as Graviton and Cobalt instances compress x86 premiums. Startups and venture-backed firms exhibit highest price sensitivity, while regulated financial institutions prioritize control environment assurance over unit economics.
Supply Chain Analysis
Inventory buffers of 60-90 days for specialized networking ASICs and optical transceivers expose providers to foundry allocation constraints. Supply concentrates in Taiwan for advanced silicon, South Korea for memory components, and the United States for specialized security hardware. Raw material dependencies span rare earth elements for magnetic storage, high-purity silicon for processor fabrication, and copper for data center power distribution. Single-source vulnerability in advanced node semiconductor manufacturing creates systemic concentration risk. Distribution runs through direct hyperscaler procurement for volume buyers and managed service provider intermediaries for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—certification timelines spanning 18-36 months for healthcare and financial services workloads—locks incumbent relationships against displacement.
For Market Incumbents: Shield enterprise relationships through embedded compliance automation that pre-validates GDPR, HIPAA, and EU AI Act requirements within infrastructure provisioning workflows. Deepen vertical integration into sovereign cloud operations across India, Brazil, and Saudi Arabia before localization mandates harden. Capacity expansion in Frankfurt and Mumbai availability zones captures financial services migration velocity while constraining challenger footholds.
For New Entrants and Emerging Players: Differentiate on sovereign cloud compliance as national data localization laws fragment addressable markets into protected competitive arenas. Target European healthcare networks and United States defense contractors requiring single-tenant physical isolation as the most penetrable premium tier. Go-to-market execution through certified managed service providers bypasses direct hyperscaler sales force scale disadvantages.
For Investors and Strategic Acquirers: Carve-out targets emerge from telecommunications carriers with stranded data center assets and regional compliance expertise but lacking cloud-native platform engineering. Long-term viability accrues to providers with demonstrated multi-region operational resilience and established regulatory certification velocity. Watch ARM-based silicon cost advantages as the inflection signal—providers achieving 40% compute-hour cost reduction against x86 baselines will capture price-sensitive workload migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Establishes protected competitive position in India, Brazil, and Saudi Arabia under localization mandates. |
| ARM Silicon Migration | Captures 40% price-performance advantage for containerized workloads against legacy x86 infrastructure. |
| Multi-Region Resilience Buildout | Satisfies SEC cybersecurity disclosure and EU AI Act failover requirements for financial services buyers. |
| Compliance Automation Integration | Embeds GDPR audit trails and HIPAA logging into provisioning workflows to lock regulated sector relationships. |
| Edge Computing Convergence | Binds serverless execution to 5G network infrastructure for latency-sensitive manufacturing and robotics applications. |
Research Methodology
The analysis maps Infrastructure as a Service, Platform as a Service, Disaster Recovery as a Service, and sovereign cloud deployment models, each validated through cloud infrastructure architects, enterprise procurement officers, compliance auditors, and managed service provider executives. Primary fieldwork combined structured interviews with secondary validation against hyperscaler capex disclosures, SEC 10-K infrastructure spend filings, and regulatory certification databases. Bottom-up service-level revenue modeling triangulated against top-down enterprise IT budget surveys across financial services, healthcare, and government verticals.
Consistency checks against external benchmarks validated volume and value outputs across deployment models, pricing tiers, and geographic adoption patterns. The analytical framework segmented by service type, deployment architecture, end-user scale, and consumption commitment structure throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating workload migration velocity, compliance deadline schedules, and silicon cost trajectories. Forecast inputs included hyperscaler region expansion announcements, sovereign cloud mandate implementation timelines, and ARM processor penetration assumptions.
The analysis sits within stated boundaries; outcomes outside continued regulatory fragmentation and sustained enterprise cloud migration would require recalibration. Forecasts reflect documented assumptions regarding compliance cost trajectories, electricity price stability, and foundry capacity allocation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Rack Market
Data Center Infrastructure
New Zealand Data Center Rack Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Germany Data Center Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
Australia Data Center Rack Market