
 United Kingdom Data Center Physical Security Market | 2026-2036
United Kingdom Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Data Center Physical Security Market Insights
Steel-reinforced composite paneling is shifting cost structures for perimeter hardening as data center operators seek blast-resistant alternatives to traditional concrete tilt-up construction. Schneider Electric leverages its integrated power and security platform to anchor large-scale deployments across Slough and London Docklands. Siemens AG sustains competitive positioning through its Siveillance command suite, which dominates integrated video and access management for financial services facilities. Axis Communications specializes in thermal imaging cameras engineered for 24/7 perimeter monitoring in fog-prone coastal clusters.
United Kingdom Data Center Physical Security encompasses layered protection systems—combining video analytics, biometric access control, intrusion detection sensors, and fire suppression hardware—designed to safeguard mission-critical IT infrastructure against unauthorized physical entry, environmental threats, and deliberate attack. Typical specifications include IP67-rated camera housings for outdoor deployment, multi-factor authentication readers supporting 50,000+ credential databases, and VdS-certified smoke detection with sub-30-second alarm transmission. Video surveillance captures the largest installed base among technology segments, reflecting hyperscale operator preference for AI-enabled analytics that reduce guard staffing ratios. Access control registers the fastest expansion, driven by CPNI-mandated tiered credentialing for staff, contractors, and visitors at facilities designated critical national infrastructure. Maintenance services within the service type dimension concentrate margin pools, as SLA-driven contracts for multi-vendor environments extend average engagement durations and create switching costs.
CPNI guidelines, the UK Building Regulations Part B fire safety standards, and ISO 27001 information security management frameworks collectively shape product certification requirements and procurement specifications for data center physical security deployments. The Information Commissioner's Office enforces data protection obligations that constrain how video surveillance footage is stored, accessed, and retained, directly influencing system architecture decisions. Stakeholders must monitor evolving CPNI protective security mandate revisions and their cascading impact on supplier qualification criteria.
Market Dynamics
Steel-reinforced composite paneling is displacing traditional concrete tilt-up construction across hyperscale campuses, compressing perimeter hardening timelines while meeting CPNI blast-resistance mandates. This materials transition coincides with cloud service providers consolidating footprints in Greater Manchester and the Thames Valley corridor.
Growth Catalysts
- CPNI Protective Security Mandates:Tiered credentialing requirements for critical national infrastructure facilities are expanding procurement scope for biometric access control and integrated command suites.
- Hyperscale Colocation Concentration:Cloud service providers are consolidating facility footprints across Slough, London Docklands, and West London, driving economies of scale in security infrastructure deployment.
- AI-Enabled Video Analytics:Hyperscale operators are deploying machine learning-based perimeter monitoring to reduce guard staffing ratios while maintaining 24/7 coverage.
Market Restraints
- Steel-Reinforced Composite Input Costs:Blast-resistant paneling materials face volatile pricing tied to global steel supply chains, compressing margins for perimeter hardening contractors.
- Specialized Installation Labor Pool:VdS-certified smoke detection and IP67-rated camera housing deployment require scarce technicians familiar with data center-grade specifications.
- Information Commissioner's Office Data Retention Constraints:Video surveillance footage storage limitations under UK data protection obligations restrict system architecture flexibility and increase compliance overhead.
Strategic Opportunities
- Greater Manchester Expansion Corridor:Cloud service providers are establishing new facility footprints outside saturated London markets, creating greenfield security infrastructure demand.
- Maintenance Service SLA Extension:Multi-vendor environment contracts are lengthening average engagement durations and creating switching costs that concentrate margin pools.
- ISO 27001 Convergence with Physical Security:Information security management frameworks are integrating physical access control specifications, opening cross-selling pathways for integrated platform vendors.
Industry Challenges
- Multi-Factor Authentication Integration Complexity:Credential readers supporting 50,000+ databases must interface with legacy building management systems, extending deployment timelines.
- Sub-30-Second Alarm Transmission Certification:VdS-certified smoke detection requires specialized commissioning protocols that bottleneck project completion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Data Center Physical Security Market |
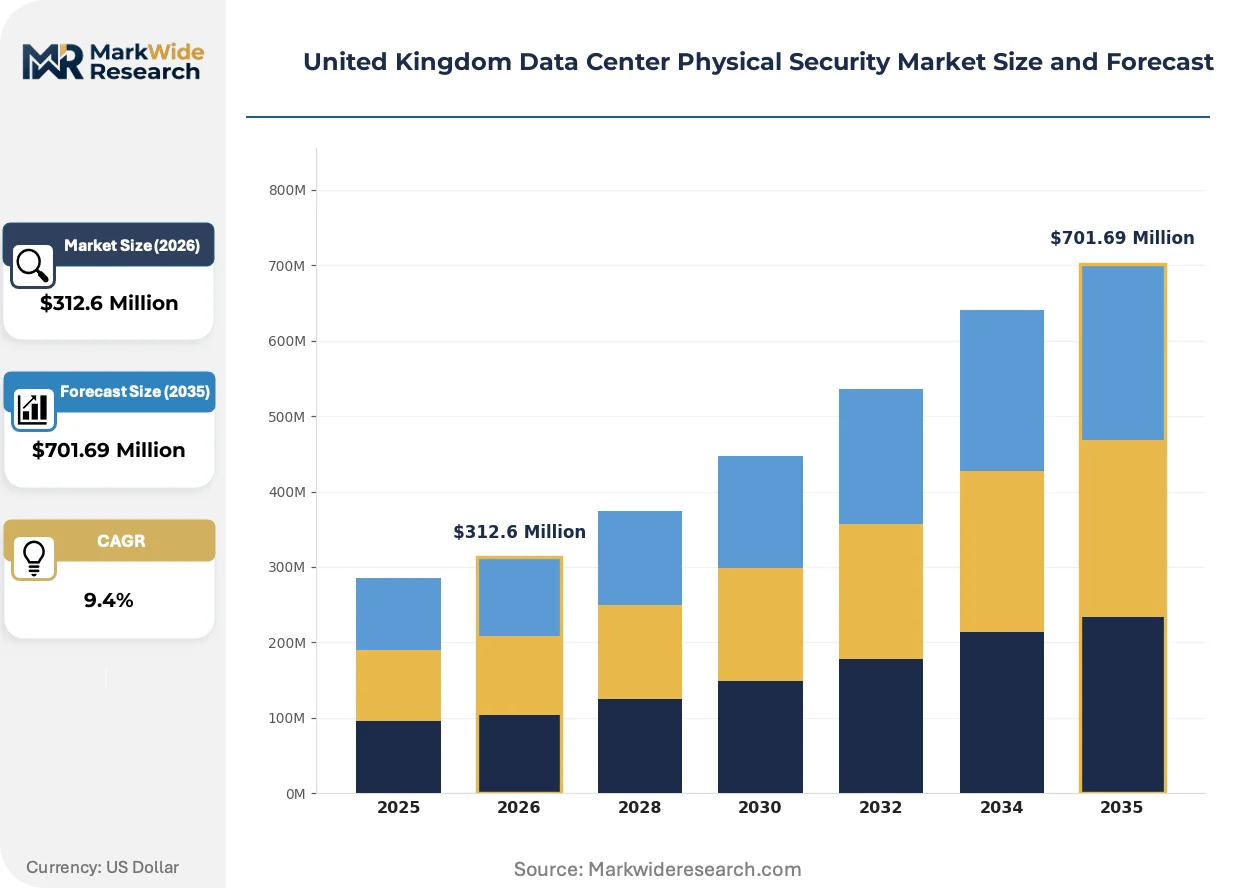
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $701.69 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Video Surveillance, Access Control, Intrusion Detection, Fire Alarm Systems Component: Cameras, Sensors, Alarms, Barriers Service Type: Consultation, Installation, Maintenance, Monitoring End User: Telecommunication, Finance, Government, Healthcare |
| Companies Covered | ABB Ltd, Siemens AG, Cisco Systems, Inc., Schneider Electric, Honeywell International Inc., Axis Communications AB, Johnson Controls, Bosch Sicherheitssysteme GmbH, Securitas Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Data Center Physical Security Market Trends and Innovations
Edge computing architectures are fragmenting security infrastructure deployment patterns across the United Kingdom. Hyperscale operators now distribute physical protection systems across metropolitan and secondary markets rather than centralizing in London corridors.
Biometric access control with multi-factor authentication is decentralizing credential verification from centralized server rooms to distributed entry points. Hyperscale colocation providers are deploying these systems at pace across Slough and London Docklands campuses. This topology is decentralizing network vulnerability profiles while reducing single-point-of-failure risks in perimeter protection.
UK Building Regulations Part B fire safety standards are tightening smoke detection response specifications for mission-critical facilities. Industrial consequence includes mandatory VdS certification for detection hardware and sub-30-second alarm transmission protocols. Financial services facilities in London Docklands are responding by accelerating replacement cycles for legacy fire suppression infrastructure.
Cloud service providers are unbundling after-sales maintenance from initial security system procurement. Traditional capital expenditure models are yielding to service-based contracts with multi-year SLA commitments. This pattern is most visible across West London hyperscale campuses where operator concentration enables vendor consolidation.
United Kingdom Data Center Physical Security Market Segmentation
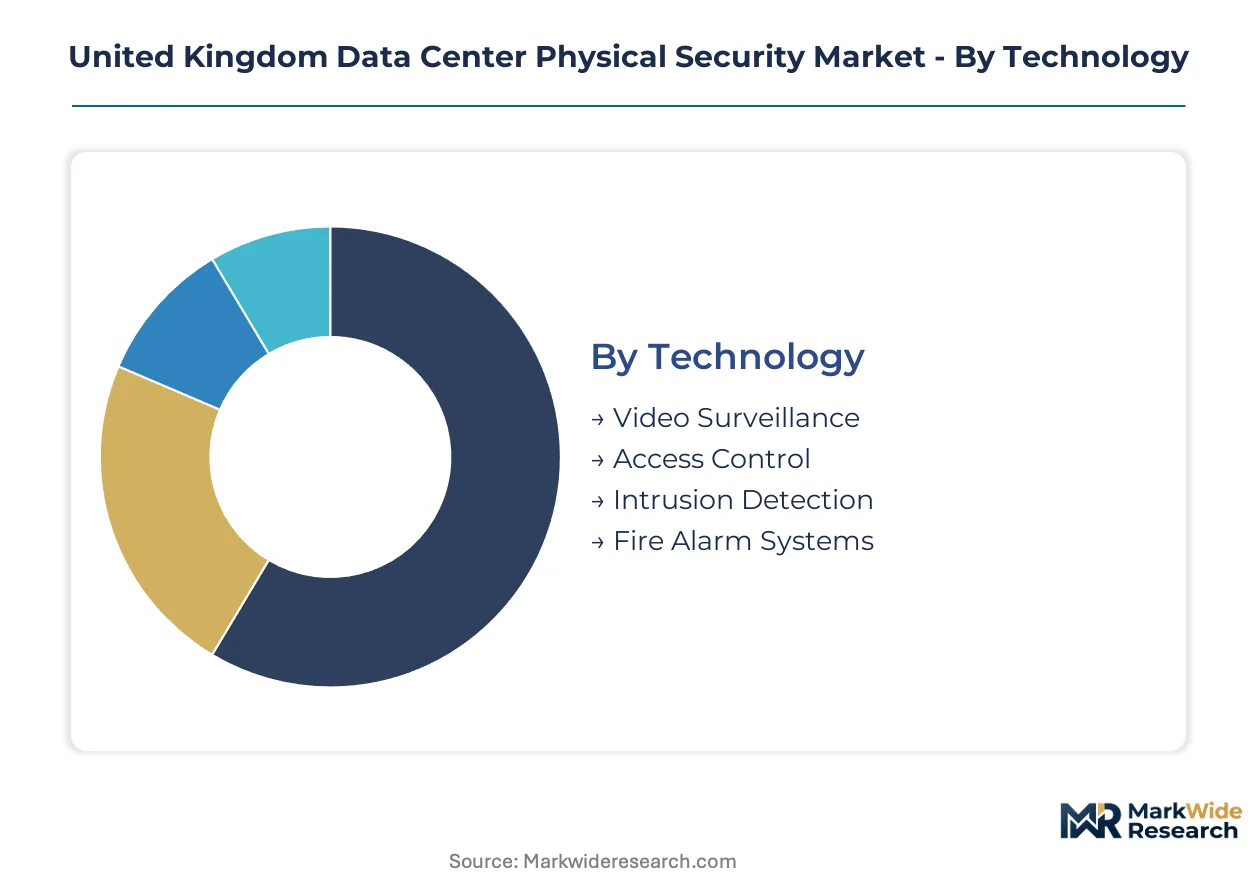
Physical security procurement in United Kingdom data centers follows distinct technology and service hierarchies. Buyers prioritize integrated platform compatibility and CPNI compliance certification over standalone feature sets.
Technology:
Hyperscale operators evaluate technology segments through total cost of ownership and guard-reduction potential.
- Video Surveillance:AI-enabled analytics platforms with thermal imaging capabilities dominate perimeter monitoring specifications. Demand concentrates across Slough and London Docklands campuses where operators deploy machine learning-based threat detection to minimize staffing ratios.
- Access Control:Biometric multi-factor authentication systems with tiered credentialing for staff, contractors, and visitors are expanding fastest. CPNI mandates for critical national infrastructure facilities drive replacement of legacy card-based systems across Greater Manchester and Thames Valley corridors.
- Intrusion Detection:Vibration and seismic sensors integrated with steel-reinforced composite perimeter barriers protect blast-resistant envelopes.
- Fire Alarm Systems:VdS-certified smoke detection with sub-30-second alarm transmission meets UK Building Regulations Part B standards for mission-critical facilities.
Volume sits with Video Surveillance; growth tilts toward Access Control.
Component:
Component selection follows environmental resilience specifications and installation labor availability.
- Cameras:IP67-rated housings with edge-processing capabilities withstand fog-prone coastal deployment conditions. West London hyperscale campuses standardize on thermal-visible fusion units for 24/7 perimeter coverage.
- Sensors:Multi-spectrum detection arrays combining infrared, microwave, and acoustic elements address layered threat profiles. Financial services facilities in London Docklands prioritize these for server room zoning.
- Alarms:Centralized notification systems with redundant communication paths integrate with CPNI command protocols.
- Barriers:Steel-reinforced composite paneling displaces concrete tilt-up construction for blast-resistant perimeter hardening.
Procurement weight favors Cameras; Sensors gain share fastest on biometric integration requirements.
Service Type:
Service procurement patterns reflect shifting capital-to-operating expenditure preferences among cloud service providers.
- Consultation:CPNI protective security compliance assessments and threat modeling for new facility designs. Demand clusters around Greater Manchester greenfield developments outside saturated London markets.
- Installation:Specialized commissioning for VdS-certified detection systems and IP67 camera housing deployment requires scarce technician labor pools.
- Maintenance:Multi-year SLA contracts with multi-vendor environment coverage concentrate margin pools and create switching costs. West London hyperscale campuses lead this service-based transition.
- Monitoring:24/7 SOC-as-a-service offerings reduce in-house security operations overhead for colocation tenants.
Revenue concentrates in Maintenance; Monitoring climbs the fastest on unbundling trends.
End User:
End user priorities diverge between regulatory compliance intensity and threat actor sophistication.
- Telecommunication:Tier-1 carriers mandate integrated command suites with redundant perimeter protection across distributed network facilities.
- Finance:Trading floors and co-location suites in London Docklands require sub-second access verification and comprehensive audit trails. CPNI designation as critical national infrastructure drives premium security specifications.
- Government:G-Cloud procurement frameworks emphasize sovereign data assurance and supply chain security vetting.
- Healthcare:NHS data centers balance patient data protection with NHS Digital infrastructure standards compliance.
Spending scale favors Finance; Healthcare shows steepest expansion trajectory on digital transformation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Kingdom data center physical security procurement clusters in hyperscale campuses across Greater London and the Thames Valley corridor, with CPNI protective security mandates driving tiered credentialing requirements at facilities designated critical national infrastructure.
London and the Southeast
Slough, London Docklands, and West London host the densest concentration of hyperscale colocation campuses. CPNI baseline protective security requirements mandate blast-resistant perimeter hardening and biometric multi-factor authentication for critical national infrastructure facilities. Cloud service providers are consolidating footprints across these corridors, driving economies of scale in integrated security platform deployment.
Greater Manchester
Cloud service providers are establishing new facility footprints outside saturated London markets, creating greenfield demand for steel-reinforced composite paneling and VdS-certified detection systems. UK Building Regulations Part B fire safety standards govern smoke detection specifications for mission-critical facilities in this expansion corridor. Manchester and Salford data center clusters are attracting security infrastructure vendors seeking to anchor regional service capabilities.
Thames Valley Corridor
Hyperscale operators are deploying AI-enabled video analytics with thermal imaging capabilities across Reading and Bracknell campuses to minimize guard staffing ratios. The Information Commissioner's Office enforces data protection obligations that constrain video surveillance footage retention architectures. Steel-reinforced composite perimeter barriers are displacing concrete tilt-up construction to meet CPNI blast-resistance mandates.
Scotland
Edinburgh and Glasgow data center developments are emerging as secondary markets with distinct regulatory considerations under Scottish building standards. NHS Scotland data centers balance patient data protection with digital transformation mandates, driving demand for ISO 27001-converged physical access control. Fog-prone coastal conditions favor IP67-rated camera housings with thermal-visible fusion capabilities.
Wales
Cardiff and Newport are attracting edge computing deployments that fragment security infrastructure patterns across secondary metropolitan markets. Welsh Government digital infrastructure investment programs are stimulating data center construction with associated physical protection requirements. Maintenance service providers are extending SLA contracts to capture multi-vendor environment margin pools in these emerging clusters.
United Kingdom Data Center Physical Security Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors commanding premium positioning in hyperscale deployments while component specialists capture volume in perimeter hardening materials. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with power and security integration capabilities, pure-play security technology developers with video analytics specialization, and regional installation and maintenance service providers. Competitive dynamics center on M&A activity to acquire VdS-certified commissioning capabilities and strategic partnerships to anchor multi-year SLA contracts.
Among diversified industrial conglomerates, Schneider Electric and Siemens AG exemplify integrated platform positioning, leveraging power infrastructure relationships to anchor security suite deployments. Axis Communications occupies a specialist position within video surveillance technology, representing the pure-play archetype focused on thermal imaging and edge-processing camera systems. These three companies illustrate the competitive structure: conglomerates compete through cross-selling integration, while specialists defend position through technology differentiation in high-specification segments.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Cisco Systems, Inc. |
| Schneider Electric |
| Honeywell International Inc. |
| Axis Communications AB |
| Johnson Controls |
| Bosch Sicherheitssysteme GmbH |
| Securitas Technology |
| Others |
Pricing and Supply Chain Analysis
Steel-reinforced composite paneling adoption across United Kingdom hyperscale campuses simultaneously compresses installation timelines and concentrates procurement leverage among blast-resistant material suppliers serving CPNI-mandated facilities. This materials transition tightens vendor relationships while shifting cost structures away from traditional concrete tilt-up construction toward specialized composite fabrication.
Pricing Analysis
Volume concentrates in standardized video surveillance hardware while margin pools accrue to integrated command suites with AI-enabled analytics. Three-tier pricing structure across premium, standard, and economy levels separates CPNI-certified biometric systems from commercial-grade access control and basic intrusion detection hardware. Cost compression in perimeter hardening materials intensifies because global steel supply volatility feeds into composite paneling input costs. Cloud service providers exhibit highest price sensitivity for commoditized camera housings, while financial services facilities in London Docklands demonstrate lowest sensitivity for sub-30-second alarm transmission certification.
Supply Chain Analysis
Reverse-logistics flows for thermal imaging camera refurbishment and VdS-certified smoke detector recalibration create secondary service revenue streams extending hardware lifecycle value. Manufacturing concentration rests on Germany, China, and the United States for IP67-rated camera housings with edge-processing capabilities. Supply chains draw from specialized steel alloys, semiconductor image sensors, and optical-grade glass substrates. Single-source vulnerability runs through German VdS certification laboratories bottlenecking smoke detection commissioning. Distribution runs through direct vendor relationships with hyperscale operators and regional installation contractors serving colocation tenants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United Kingdom data center physical security is consolidating around integrated platform vendors capable of spanning power infrastructure and security suite deployment, with CPNI compliance complexity forcing smaller component specialists toward acquisition or niche retreat.
For Market Incumbents: Extend multi-year SLA contract anchoring across West London hyperscale campuses to deepen switching cost moats against emerging platform competitors. Acquire VdS-certified commissioning capabilities to eliminate project completion bottlenecks threatening margin realization. Vertical integration into steel-reinforced composite paneling fabrication secures supply continuity against global steel price volatility eroding perimeter hardening profitability. For New Entrants and Emerging Players: Cloud marketplace and direct digital sales channels offer lower-friction entry paths than traditional specification-driven procurement relationships dominating established London corridors. Target Greater Manchester greenfield developments where operator concentration remains below critical mass for incumbent vendor lock-in. Position around ISO 27001-converged physical access control specifications opening cross-selling pathways with information security consultancies. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking integrated platform capabilities, with financial sponsor secondary buyouts viable for scaled maintenance service providers. Five-to-ten year viability favors vendors with captive VdS certification relationships and established CPNI compliance track records. Monitor CPNI protective security mandate revision timing as inflection indicator for qualification criteria tightening and supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of VdS-Certified Commissioning Capabilities | Eliminates project completion bottlenecks threatening margin realization across CPNI-mandated deployments. |
| Multi-Year SLA Contract Extension | Deepens switching cost moats against emerging platform competitors at West London hyperscale campuses. |
| Platform Integration with Power Infrastructure | Leverages Schneider Electric's cross-selling model anchoring large-scale deployments across Slough corridors. |
| Geographic Expansion to Greater Manchester | Captures greenfield demand outside saturated London markets with lower incumbent vendor concentration. |
| ISO 27001 Convergence Investment | Opens cross-selling pathways with information security consultancies serving financial services facilities. |
Research Methodology
Document review covered regulatory filings from the Centre for the Protection of National Infrastructure, UK Building Regulations Part B guidance, and Information Commissioner's Office surveillance guidance, complemented by interviews with data center security directors, physical security system integrators, and colocation procurement managers. Secondary validation drew from hyperscaler capital expenditure disclosures, CPNI protective security mandate documentation, and ISO 27001 certification body records. Bottom-up equipment deployment estimates triangulated against top-down facility construction pipeline tracking.
Historical hyperscale facility completion rates cross-referenced against panel input from security technology vendors and installation contractors informed the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, service delivery model, end-user industry vertical, and regional facility cluster. CAGRs derived from facility pipeline scaling assumptions and security content per megawatt trajectories. Forecast inputs incorporated CPNI mandate revision probability and cloud service provider consolidation patterns across Thames Valley and Greater Manchester corridors.
The model holds under continued CPNI protective security mandate enforcement and stable cloud service provider facility investment; deviation in regulatory relaxation or hyperscale demand contraction would shift trajectory. Practitioners should monitor CPNI consultation document releases and hyperscaler land acquisition announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
United Kingdom Data Center Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
Data Center Fabric Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
China Data Center Storage Market