
 Israel Data Center Market | 2026-2036
Israel Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Data Center Market Insights
A capital-intensity divergence between hyperscale builders and legacy telecom operators is reorganizing competitive dynamics in Israel's data center sector. Digital Realty Trust leverages its global platform design standards to anchor premium colocation capacity near Tel Aviv. Bezeq International competes through captive fiber backhaul and established enterprise relationships. MedOne Digital specializes in sovereign-cloud configurations for defense and public-sector clients.
Israel data centers constitute mission-critical facilities engineered to deliver redundant power, precision cooling, and sub-10-millisecond latency for enterprise IT workloads. Tier III and Tier IV designs incorporate N+1 uninterruptible power supply architectures and hot-aisle containment to sustain uptime exceeding 99.982%. Colocation services dominate current revenue pools as enterprises exit owned facilities. Liquid cooling segments are accelerating fastest, driven by GPU-density requirements from AI training clusters. Cloud services margins remain compressed by hyperscale self-build tendencies among global technology firms.
Israel's Ministry of Communications governs submarine cable licensing and cross-border data flows, while the Israel National Cyber Directorate mandates security certification for critical infrastructure operators. The National Infrastructure Plan channels state-backed financing toward greenfield campus development in peripheral zones. Stakeholders must monitor spectrum allocation for fixed wireless access as a potential last-mile disruptor to fiber-dependent site selection.
Market Dynamics
GPU-density requirements from AI training clusters are compressing legacy air-cooling designs and forcing wholesale infrastructure reinvestment across Israeli facilities. This thermal pressure is restructuring capex allocation, procurement timelines, and site selection criteria for new builds.
Growth Catalysts
- National Infrastructure Plan:State-backed financing accelerates greenfield campus development in peripheral zones like Beersheba, reducing land scarcity constraints near Tel Aviv.
- Defense workload migration:Israeli intelligence agencies are expanding classified hosting requirements, creating sovereign-cloud demand that domestic operators capture exclusively.
- Liquid cooling:Direct-to-chip and immersion systems address power densities exceeding 50 kW per rack, enabling AI cluster deployment that air-cooled facilities cannot support.
Market Restraints
- Submarine cable concentration:Mediterranean landing stations face geopolitical transit risk through the Suez Canal corridor, threatening international bandwidth redundancy.
- Grid interconnection queues:Israel Electric Corporation approval timelines for multi-megawatt connections extend 18-24 months, delaying hyperscale project commissioning.
- Construction input costs:Steel and copper price volatility, combined with specialized mechanical contractor scarcity, inflates all-in build costs for Tier III certifications.
Strategic Opportunities
- Beersheba corridor:Peripheral development zones offer land parcels at 40% discount to Tel Aviv metro pricing, with available renewable energy allocation from solar farms.
- Fixed wireless access:Ministry of Communications spectrum allocation for 5G FWA creates last-mile alternatives to fiber-dependent site selection, expanding addressable locations.
- Defense-cloud convergence:Dual-use facilities serving both military and commercial tenants achieve utilization rates above 85% through security-cleared workforce requirements.
Industry Challenges
- Certified technician scarcity:Israel National Cyber Directorate security clearance processing creates 6-9 month hiring delays for critical infrastructure roles.
- Legacy system integration:Enterprise migrations from on-premise mainframes to colocated environments require custom middleware development that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Data Center Market |
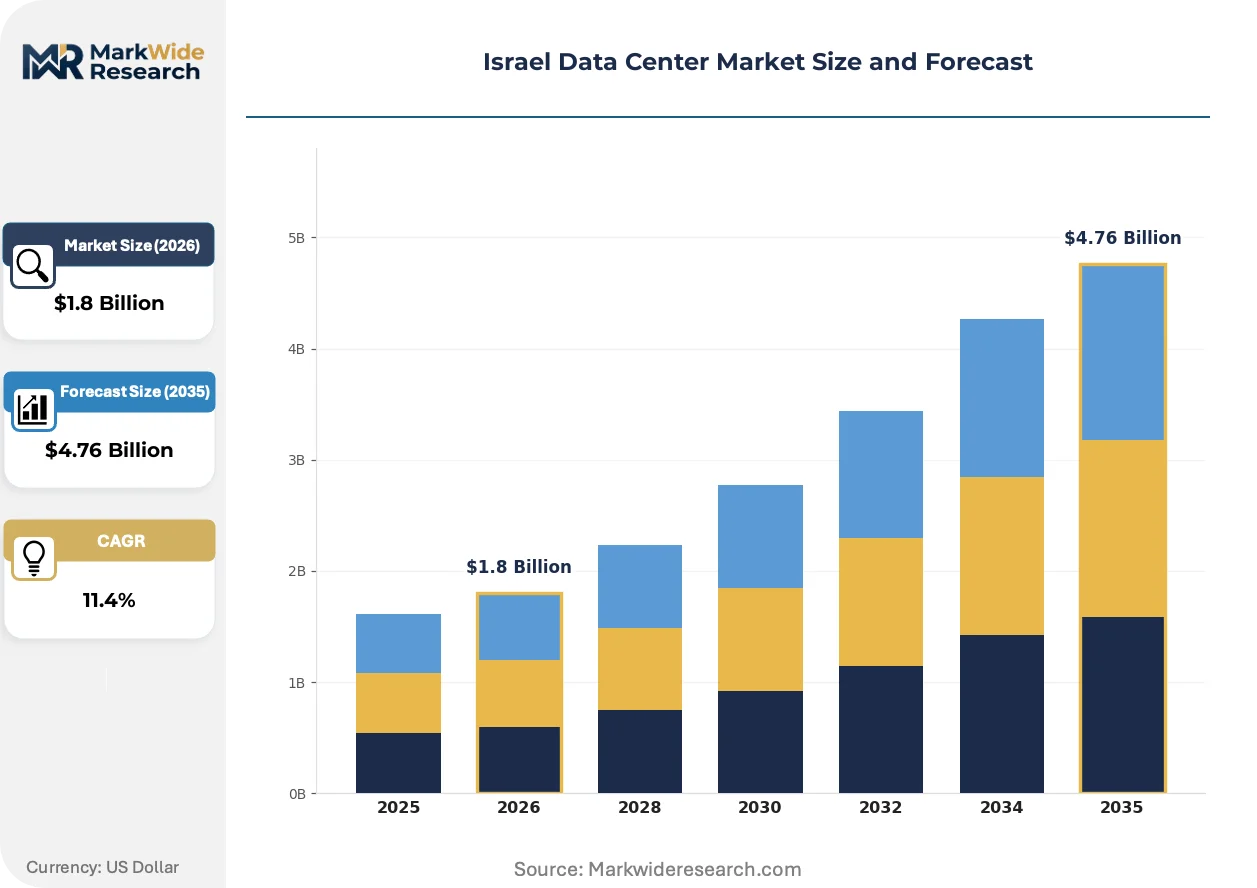
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
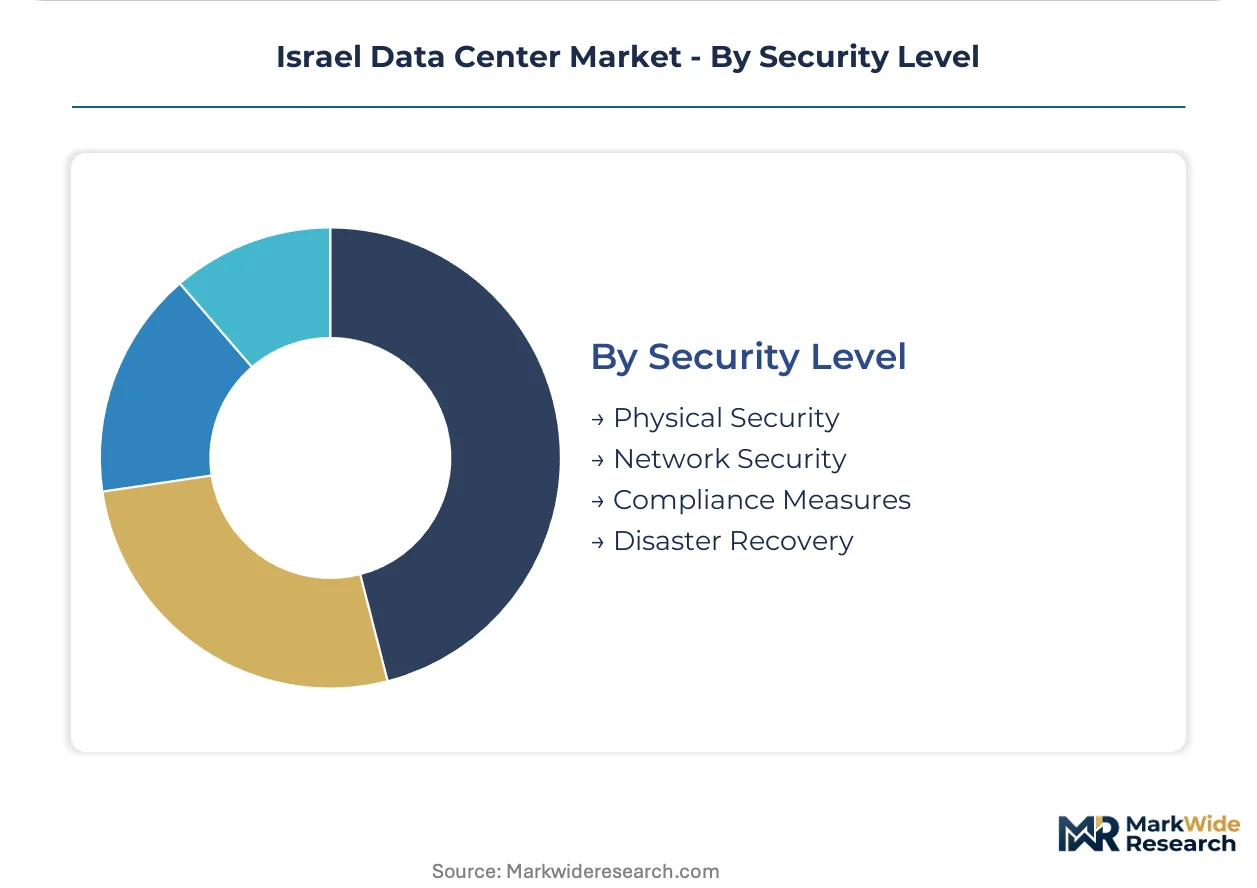
| Segmentation | Service Type: Colocation, Managed Hosting, Cloud Services, Interconnection Cooling Technology: Air Cooling, Liquid Cooling, Eco-Friendly Solutions, Advanced Cooling Systems Power Type: On-Premise Generation, Renewable Energy, UPS Systems, Grid Power Security Level: Physical Security, Network Security, Compliance Measures, Disaster Recovery |
| Companies Covered | Bezeq International, Global Technical Realty, Adgar Investments and Development, Digital Realty Trust, Serverfarm, MedOne Digital, EdgeConneX, Compass Datacenters, Bynet Data Communications, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Data Center Market Trends and Innovations
Liquid cooling architectures are supplanting conventional precision air systems as the default design standard for new Israeli facilities. This transition reflects thermal load fundamentals rather than incremental efficiency gains.
Immersion cooling using dielectric fluids is supplanting raised-floor air distribution in hyperscale designs. GPU cluster operators including AI training labs and quantitative research firms now specify direct liquid cooling as a baseline procurement requirement. This technology is supplanting traditional mechanical contractors with specialized fluid systems integrators, restructuring the vendor ecosystem for Israeli data center construction.
Israel National Cyber Directorate certification mandates for critical infrastructure operators are tightening physical and logical security requirements. The framework now requires biometric access controls, air-gapped management networks, and quarterly penetration testing for Tier III facilities. Defense contractors and financial services firms are accelerating compliance investments ahead of enforcement deadlines, creating certified capacity premiums in the Tel Aviv metro.
Colocation buyers are consolidating vendor relationships from multi-site portfolios toward single-campus commitments with expansion rights. Enterprise IT departments favor 5-7 year contracts with pre-negotiated power density upgrades over shorter terms with renegotiation exposure. This concentration is most pronounced among Israeli fintech and cybersecurity software firms scaling from seed-stage to unicorn valuations.
Israel Data Center Market Segmentation

Israel's data center market segments reveal divergent pressure points from AI infrastructure demands, sovereign security mandates, and energy transition policies. Each dimension carries distinct substitution threats that reshape competitive positioning across the value chain.
Service Type:
Colocation faces acute substitution pressure from hyperscale self-builds as global cloud operators bypass third-party facilities for captive campuses.
- Colocation:Third-party rack and cage leasing with redundant power and cross-connect fabrics. Israeli fintech and cybersecurity firms concentrate demand in Tel Aviv metro facilities as they scale from venture-backed to unicorn valuations. The segment absorbs legacy enterprise exits from owned facilities.
- Managed Hosting:Operator-administered server environments with bundled monitoring and patch management. Defense contractors and classified workload operators in Beersheba drive demand for security-cleared personnel and air-gapped network architectures. Procurement contracts now specify 5-7 year terms with pre-negotiated power density upgrade rights.
- Cloud Services:Virtualized compute and storage delivered through hyperscale platforms. Margins compress as global technology firms favor direct infrastructure ownership over wholesale resale arrangements.
- Interconnection:Cross-connect and peering fabrics enabling carrier-neutral traffic exchange. Submarine cable landing station proximity in Tel Aviv and Haifa determines facility valuations for latency-sensitive financial services clients.
Colocation retains volume leadership; Cloud Services holds the steepest expansion curve.
Cooling Technology:
Cost tier stratification separates premium liquid-cooled deployments from legacy air-cooled retrofits facing thermal obsolescence.
- Air Cooling:Precision HVAC and raised-floor distribution systems. Legacy facilities in central Tel Aviv districts face stranded asset risk as GPU cluster operators reject environments unable to sustain densities above 15 kW per rack.
- Liquid Cooling:Direct-to-chip and immersion systems using dielectric fluids. AI training labs and quantitative research firms now specify this architecture as baseline procurement requirement for new Israeli builds.
- Eco-Friendly Solutions:Free-air cooling and evaporative systems leveraging Israel's arid climate. Peripheral zone developments in Beersheba exploit available renewable energy allocation from adjacent solar farms.
- Advanced Cooling Systems:Hybrid architectures combining mechanical and passive elements. Israel Electric Corporation grid interconnection queues extending 18-24 months force operators toward modular thermal designs that reduce commissioning dependencies.
Air Cooling retains volume leadership; Liquid Cooling gains share fastest.
Power Type:
Application-driven procurement separates mission-critical defense workloads requiring guaranteed generation from commercial loads tolerating grid variability.
- On-Premise Generation:Captive natural gas or diesel gensets with N+1 redundancy. Classified facilities serving Israeli intelligence agencies mandate this architecture for sovereign continuity assurance.
- Renewable Energy:Solar PPAs and green tariff arrangements. National Infrastructure Plan financing channels state-backed capital toward peripheral campuses with direct renewable allocation.
- UPS Systems:Battery and flywheel uninterruptible power supply architectures. Tier III certifications require N+1 configurations with hot-swappable module designs.
- Grid Power:Israel Electric Corporation transmission and distribution supply. Multi-megawatt connection approval timelines create project delays that hyperscale developers mitigate through phased power procurement.
Grid Power retains volume leadership; Renewable Energy climbs the fastest.
Security Level:
Customer type segmentation separates defense-intelligence mandates from commercial compliance frameworks with divergent certification intensity.
- Physical Security:Biometric access controls, mantrap entries, and perimeter hardening. Israel National Cyber Directorate mandates now require quarterly penetration testing for Tier III facilities serving critical infrastructure operators.
- Network Security:Segmented VLAN architectures and DDoS mitigation fabrics. Financial services firms in Tel Aviv drive demand for carrier-grade scrubbing capacity with sub-50-millisecond response times.
- Compliance Measures:ISO 27001, SOC 2, and sector-specific certification maintenance. Defense contractors accelerate compliance investments ahead of enforcement deadlines, creating certified capacity premiums.
- Disaster Recovery:Geographically separated active-active and hot-standby configurations. Enterprise buyers consolidate toward single-campus commitments with expansion rights rather than multi-site portfolios.
Network Security retains volume leadership; Compliance Measures shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in peripheral zones exhibit high price elasticity to land and power costs, while defense-intelligence clients near Tel Aviv demonstrate inelastic demand for sovereign-certified capacity. This divergence shapes facility investment patterns across Israeli sub-regions.
Tel Aviv Metro
Hyperscale cloud operators and fintech unicorns drive premium colocation demand in central Tel Aviv districts. The Ministry of Communications governs submarine cable landing station licensing, with multiple Mediterranean cables terminating in the metro. Tel Aviv's financial district concentrates latency-sensitive trading infrastructure and carrier-neutral interconnection fabrics.
Beersheba Corridor
The National Infrastructure Plan channels state-backed financing toward greenfield campuses in this peripheral zone. Israel Electric Corporation grid interconnection queues shorten here relative to Tel Aviv metro, accelerating project commissioning. Adjacent solar farms provide renewable energy allocation for facilities serving AI training clusters.
Haifa Bay Area
Industrial port infrastructure and existing fiber backhaul attract disaster recovery and secondary site deployments. The Israel National Cyber Directorate mandates security certification for critical infrastructure operators across this northern concentration. Haifa's technology university ecosystem supplies specialized engineering talent for facility operations.
Jerusalem Periphery
Government and public-sector workload migration creates steady demand for Tier III certified capacity. National infrastructure financing supports campus development in surrounding development towns. Security-cleared workforce requirements limit operator competition to domestic players with defense relationships.
Southern Development Zones
Land parcels trade at discounts exceeding 40 percent versus Tel Aviv metro pricing, attracting hyperscale self-build evaluations. Fixed wireless access spectrum allocation from the Ministry of Communications creates last-mile alternatives to fiber-dependent site selection. Solar resource availability supports renewable power purchase agreement structures.
Israel Data Center Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Israel's data center sector. The market structure consolidates around three distinct tiers: global hyperscale platform operators, domestic telecom-captive providers, and specialized sovereign-cloud specialists. Strategic differentiation centers on security certification depth, fiber backhaul ownership, and renewable energy access. Competitive moves concentrate on capacity expansion in peripheral zones and portfolio diversification into managed services.
Among global platform operators, Digital Realty Trust exemplifies the premium-tier archetype through standardized facility designs. Domestic telecom-captive competition centers on Bezeq International, which leverages established enterprise relationships. MedOne Digital occupies a specialized position serving defense-intelligence clients with security-cleared operations.
| Leading Market Players |
|---|
| Bezeq International |
| Global Technical Realty |
| Adgar Investments and Development |
| Digital Realty Trust |
| Serverfarm |
| MedOne Digital |
| EdgeConneX |
| Compass Datacenters |
| Bynet Data Communications |
| Others |
Pricing and Supply Chain Analysis
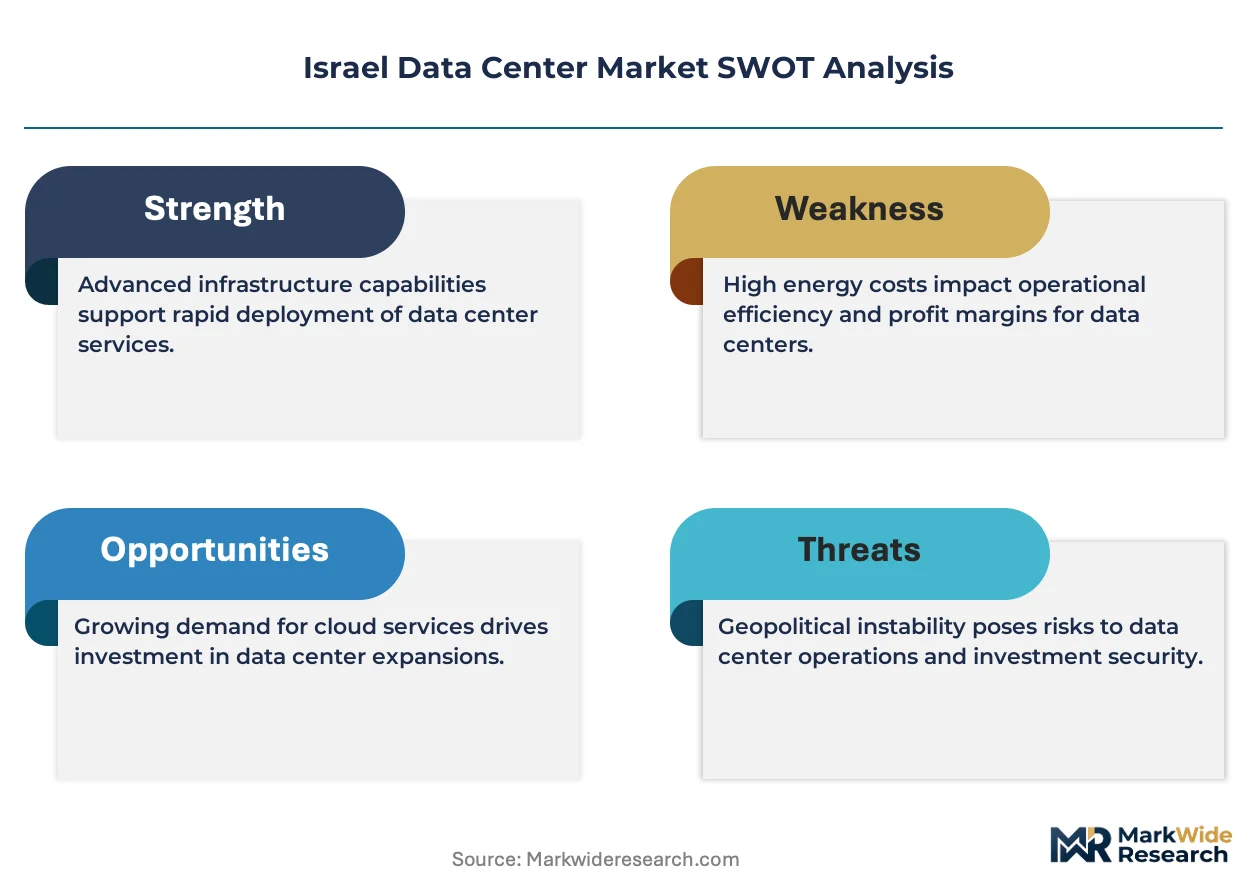
Eighteen-to-twenty-four-month Israel Electric Corporation grid interconnection queues concentrate supply-side bargaining power with pre-approved developers while compressing pricing flexibility for late entrants seeking Tel Aviv metro positioning. This lead-time asymmetry rewards operators with secured power allocations and stranded capital for competitors awaiting infrastructure clearance.
Pricing Analysis
After-sales revenue from managed hosting and security-cleared operations drives lifetime value beyond base colocation rents. Pricing stratifies across Tier III certified, Tier IV sovereign, and standard commercial tiers, with certification premiums widening as Israel National Cyber Directorate enforcement deadlines approach. Cost compression in air-cooled legacy facilities intensifies as GPU cluster operators reject thermal designs below 50 kW per rack density. Fintech and cybersecurity scale-ups exhibit highest price sensitivity, while defense-intelligence clients demonstrate inelastic demand for sovereign-certified capacity.
Supply Chain Analysis
Suez Canal transit chokepoints expose Mediterranean submarine cable landing stations to bandwidth redundancy risks that reshape facility valuation premiums. Critical mechanical and electrical equipment draws from Germany, China, and the United States, with specialized liquid cooling components resting on single-source vendor relationships for dielectric fluid systems. Steel and copper price volatility amplifies construction input cost uncertainty for Tier III certifications. Distribution runs through direct procurement contracts with hyperscale developers and domestic telecom-captive operators rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power shifts toward consolidated fintech and cybersecurity unicorns scaling from seed-stage to late-round valuations, fragmenting vendor relationships from multi-site portfolios toward single-campus commitments with pre-negotiated expansion rights.
For Market Incumbents: Shield core Tel Aviv metro positioning through accelerated liquid cooling retrofit investments that disqualify legacy air-cooled competitors from AI training cluster procurement. Deepen fiber backhaul ownership in Beersheba corridor development zones to preempt fixed wireless access disruption. Prioritize Israel National Cyber Directorate certification maintenance ahead of enforcement deadlines to sustain premium pricing power against uncertified entrants. For New Entrants and Emerging Players: Anchor in Beersheba peripheral zones where National Infrastructure Plan financing and 40 percent land cost discounts offset Tel Aviv metro proximity premiums. Target defense-cloud convergence opportunities serving dual-use military and commercial tenants with security-cleared workforce requirements. Pursue direct-to-chip cooling specialization as baseline procurement differentiator against incumbent air-cooled portfolios. For Investors and Strategic Acquirers: Carve-out targets emerge from telecom-captive operators with underutilized fiber assets and dormant enterprise relationships ripe for managed services conversion. Long-term viability centers on renewable energy allocation access and sovereign certification depth rather than commodity colocation scale. Monitor Israel Electric Corporation grid interconnection queue clearance rates as inflection indicator for development pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Direct-to-chip and immersion systems capture AI training cluster demand that air-cooled facilities cannot serve. |
| Beersheba Corridor Campus Development | National Infrastructure Plan financing and solar farm proximity reduce land and power cost structures versus Tel Aviv metro. |
| Security Certification Acceleration | Israel National Cyber Directorate compliance investments ahead of enforcement deadlines create certified capacity premiums. |
| Fixed Wireless Access Spectrum Positioning | Ministry of Communications 5G FWA allocation expands addressable locations beyond fiber-dependent site selection constraints. |
| Defense-Cloud Convergence Facilities | Dual-use campuses serving military and commercial tenants achieve utilization rates above 85 percent through clearance requirements. |
Research Methodology
Cross-validation between facility operator interviews and hyperscaler capex disclosure filings anchors the qualitative findings in observable deployment commitments. Primary fieldwork engaged data center development executives, Israel Electric Corporation grid planning officers, defense contractor IT procurement leads, and submarine cable landing station operators. Secondary validation drew from Ministry of Communications licensing records, Israel National Cyber Directorate certification registries, municipal planning authority filings, and renewable energy allocation databases. Bottom-up capacity aggregation and top-down infrastructure investment tracking triangulate market sizing.
Sensitivity analysis across power density assumptions, grid interconnection timeline scenarios, and defense workload migration rates stress-tests projection robustness. Segmentation dimensions modeled include service type, cooling technology architecture, security certification tier, and regional development zone. CAGRs derive from installed capacity build-out schedules, power procurement contract tenors, and customer concentration patterns across fintech, cybersecurity, and defense-intelligence verticals. Hyperscale self-build versus third-party colocation substitution elasticities inform demand allocation.
Decision-makers should treat outputs as directional under sustained National Infrastructure Plan financing and stable Suez Canal transit conditions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as Israel Electric Corporation queue management practices and Ministry of Communications spectrum allocation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Switzerland Data Center Construction Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
Poland Data Center Rack Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
APAC Data Center Server Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Data Center Renovation Market