
 APAC Data Center Server Market | 2026-2036
APAC Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Data Center Server Market Insights
Market Context
AI infrastructure talent scarcity across Taiwan, South Korea, and India is redrawing competitive boundaries for server vendors serving the APAC Data Center Server Market. Dell Technologies leverages its direct sales force and localized manufacturing in Penang to sustain dominant positioning across enterprise rack deployments. Huawei Technologies anchors government and telecom verticals through captive semiconductor fabrication and in-house production of Arm-based processors. Inspur Group dominates China's domestic hyperscale procurement with vertically integrated supply chains spanning Jinan and Suzhou.
Technical Definition and Segment Structure
The APAC Data Center Server encompasses compute nodes engineered to IEC 62368-1 safety standards, typically housing dual Intel Xeon or AMD EPYC processors with thermal design power ratings exceeding 200W per socket, purpose-built for continuous operation in controlled environments. Rack servers command the majority of unit shipments across colocation and on-premise deployments, though blade servers retain margin concentration in financial services clusters requiring dense virtualization. Hybrid deployment models are expanding fastest as Japanese banks and Australian healthcare networks navigate data sovereignty requirements through split workloads across private infrastructure and sovereign cloud zones.
Regulatory Environment
China's MIIT enforces PUE thresholds below 1.3 for new data center approvals, while India's BIS mandates compulsory registration for imported IT equipment under the Compulsory Registration Scheme. Singapore's IMDA sustainability standards and Australia's TGA data localization rules for healthcare records collectively shape server procurement specifications, cooling technology roadmaps, and in-country assembly requirements. Stakeholders must monitor evolving carbon disclosure obligations under Japan's METI guidelines and Korea's K-REACH substance restrictions as these frameworks tighten material compliance for server chassis and printed circuit boards.
Market Dynamics
Generative AI training clusters are compressing server refresh cycles across Southeast Asia, forcing hyperscale operators to abandon three-year depreciation schedules in favor of eighteen-month replacement timelines for high-density GPU servers.
Growth Catalysts
- Liquid Cooling Mandates:China's MIIT PUE thresholds below 1.3 are compelling data center operators to deploy direct-to-chip cooling systems for thermal loads exceeding 500W per processor.
- Sovereign Cloud Localization:India's data localization requirements under the Digital Personal Data Protection Act are accelerating in-country server assembly and certification under BIS registration schemes.
- Arm Architecture Migration:Hyperscale procurement teams are qualifying Neoverse-based processors for cloud-native workloads, diversifying beyond x86 dominance in power-constrained facilities.
Market Restraints
- Advanced Packaging Bottlenecks:CoWoS substrate shortages from Taiwan-based foundries are constraining AI accelerator card production and extending lead times for H100-class deployments.
- Import Duty Regimes:India's phased manufacturing program imposes cascading tariffs on fully assembled servers, raising landed costs for foreign OEMs against domestic assemblers.
- Power Grid Saturation:Singapore's Tuas data center zone faces hard electrical capacity limits, capping new server deployments despite unmet demand from financial services tenants.
Strategic Opportunities
- Vietnam Manufacturing Expansion:Northern provinces around Bac Ninh are attracting server chassis and power supply investments as operators diversify assembly footprints beyond China.
- Modular Edge Deployments:5G network slicing requirements from Korean telecom operators are creating demand for micro data centers with NEBS-compliant server configurations.
- Carbon Accounting Integration:Japan's METI guidelines on supply chain emissions disclosure are enabling premium positioning for servers with verified embodied carbon certificates.
Industry Challenges
- Immersion Cooling Expertise Gap:Facility engineering teams lack training in dielectric fluid management and leak detection for two-phase cooling architectures.
- Multi-Cloud Interoperability:Enterprise IT departments struggle to maintain consistent orchestration across on-premise VMware stacks and sovereign cloud zones with divergent API implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Data Center Server Market |
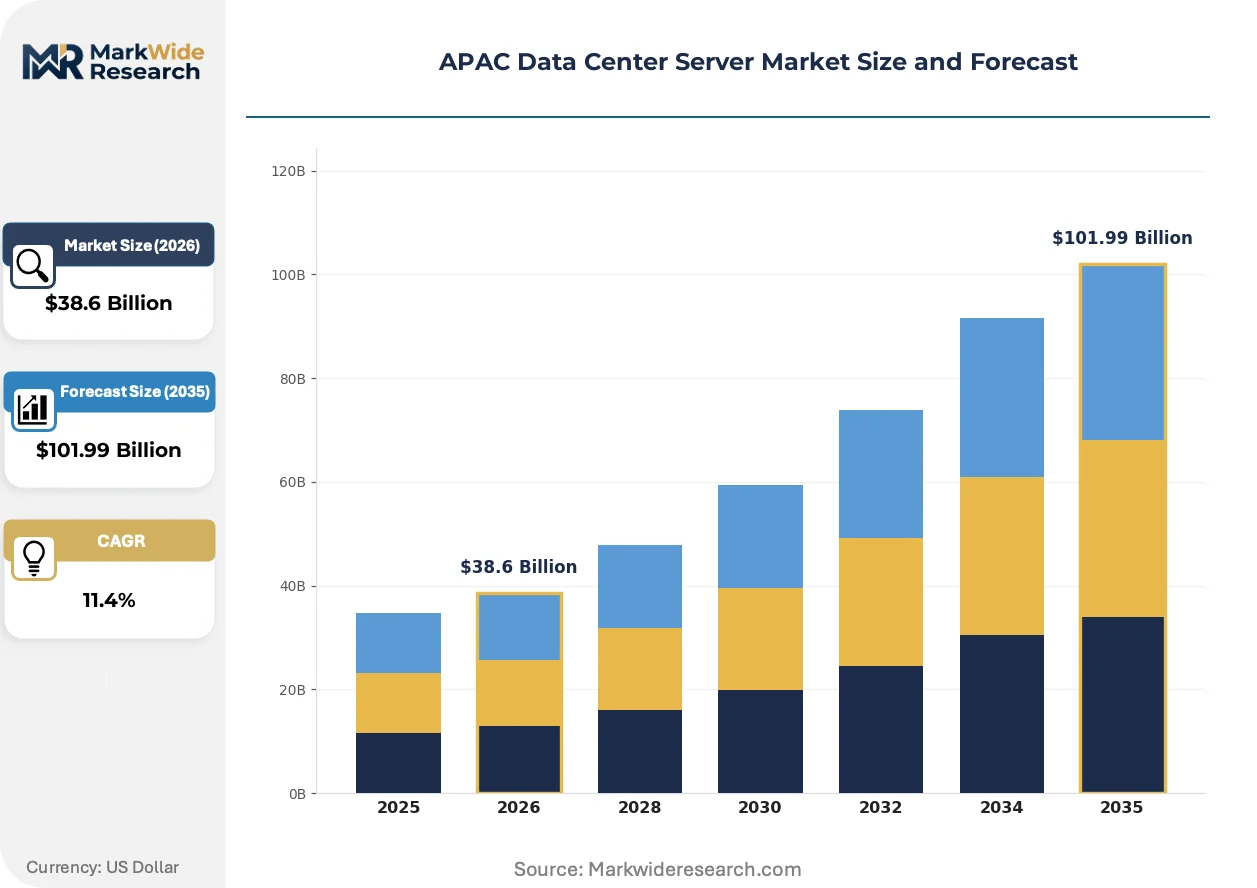
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Micro Servers Deployment Model: On-Premise, Hybrid, Colocation, Cloud End User: IT, Banking, Healthcare, Education Service Type: Managed Services, Professional Services, Technical Support, Maintenance |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, Lenovo Group Limited, Cisco Systems, Fujitsu, IBM Corporation, Huawei Technologies, Inspur Group, Super Micro Computer, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Data Center Server Market Trends and Innovations
Server architecture decisions across APAC are increasingly dictated by thermal constraints rather than raw compute benchmarks, with cooling technology selection preceding processor procurement in facility planning cycles.
Direct liquid cooling is displacing traditional air-handling units in new hyperscale builds across Singapore and Sydney, with cold plate systems now standard for deployments exceeding 30kW per rack. Australian mining technology companies and Japanese automotive simulation clusters have adopted these configurations since 2023. The shift is compressing mechanical infrastructure spend from 35% of facility capex toward 22%, reallocating budget to compute density.
China's MIIT efficiency mandates now require real-time PUE monitoring and annual disclosure for all facilities above 6MW capacity, with non-compliant operators facing construction permit denials. This regulatory architecture is accelerating retrofits in legacy Beijing and Shanghai data centers. Domestic operators are responding by procuring only liquid-cooled servers for new installations, effectively banning air-cooled architectures from 2024 onward.
Hyperscale buyers are consolidating vendor relationships around three-year total cost of ownership metrics rather than unit purchase price, with power consumption and residual value guarantees dominating selection criteria. This behavioral recalibration is marginalizing second-tier OEMs lacking localized service networks. The pattern is most pronounced in India's Mumbai-Pune corridor, where Reliance Jio and Tata Communications have reduced qualified supplier pools from twelve vendors to five.
APAC Data Center Server Market Segmentation
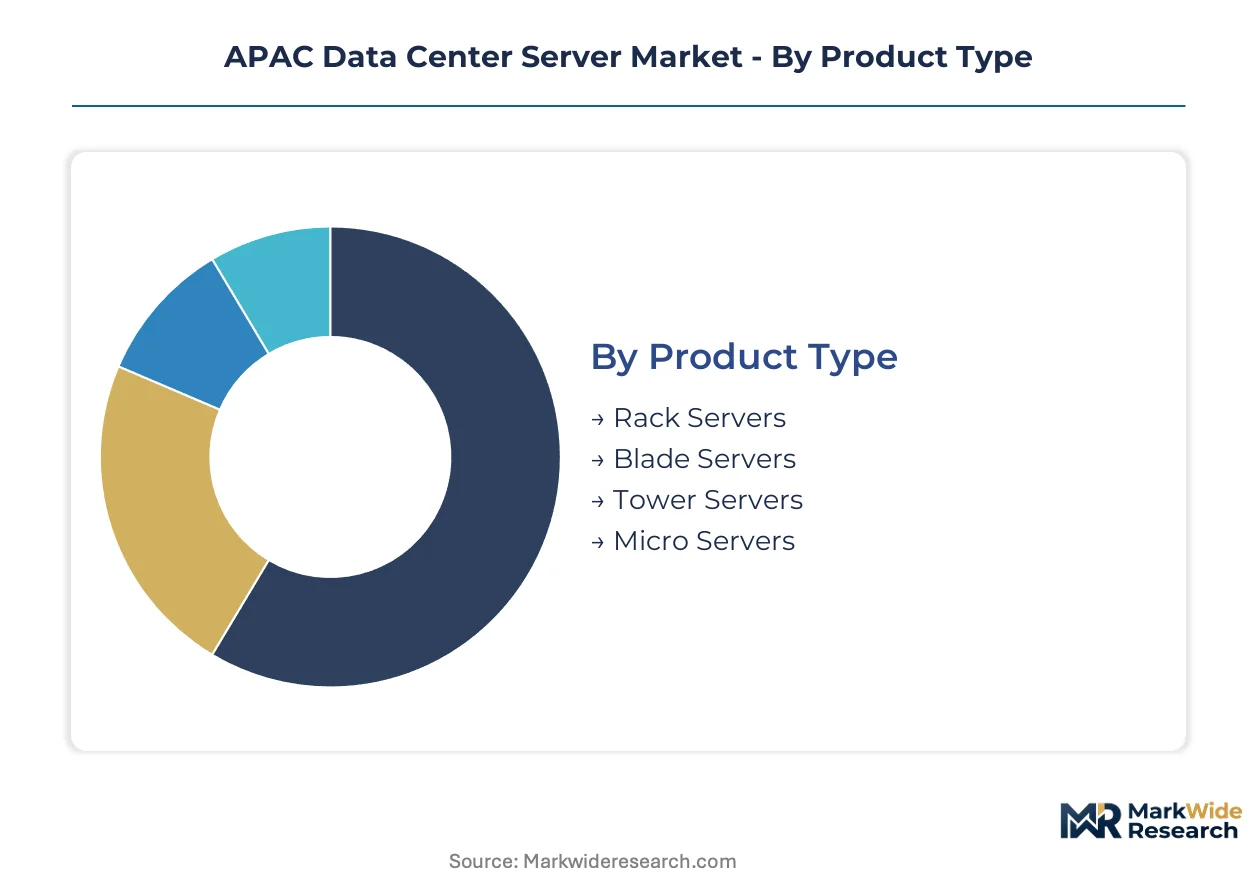
Server procurement patterns across APAC diverge sharply by deployment scale and thermal architecture, with hyperscale operators and sovereign cloud mandates pulling product mix in opposing directions. Segmentation clarity enables vendors to align cooling roadmaps and certification investments with the specific compliance and density requirements of each buyer category.
Product Type:
Blade servers face the most acute substitution pressure as liquid-cooled rack configurations achieve comparable density without proprietary chassis lock-in, eroding the traditional blade value proposition in financial services clusters.
- Rack Servers:Standard 19-inch form factors now dominate liquid-cooled retrofits across Singapore's Tuas zone and Sydney's hyperscale builds. Mumbai-Pune corridor operators are standardizing on 42U and 48U rack heights to maximize floor plate efficiency under India's escalating power costs.
- Blade Servers:Chassis-based architectures retain traction in Tokyo and Osaka financial services data centers where VMware virtualization density justifies shared power and cooling infrastructure. Regulatory pressure from Japan's METI disclosure requirements is accelerating blade-to-rack migration timelines.
- Tower Servers:Standalone vertical configurations serve distributed edge sites across Australia's mining regions and Indonesia's archipelago telco infrastructure where rack infrastructure is economically impractical.
- Micro Servers:Compact single-socket units are proliferating in Korea's 5G network slicing deployments and Vietnam's emerging colocation market for lightweight web hosting workloads.
Rack servers anchor the volume base while micro servers gain share at the steepest rate.
Deployment Model:
Cost tier stratification separates capex-intensive on-premise builds from opex-optimized cloud consumption, with hybrid architectures capturing margin concentration through orchestration complexity.
- On-Premise:Private infrastructure retains dominance in China's state-owned enterprise sector and India's defense-adjacent data centers where MIIT and BIS certification requirements mandate in-country assembly and direct operational control.
- Hybrid:Split workload architectures are expanding most quickly across Australian healthcare networks navigating TGA data localization rules and Japanese automotive simulation clusters balancing proprietary IP with burst compute needs.
- Colocation:Wholesale and retail leasing models concentrate in Singapore's Tuas zone and Hong Kong's Tseung Kwan O industrial estate, though electrical capacity constraints are capping new server deployments in the former.
- Cloud:Public cloud consumption patterns dominate Southeast Asian startup ecosystems and Taiwan's semiconductor design houses where workload unpredictability favors elastic provisioning.
Cloud deployments expand most quickly among new entrants while on-premise retains the revenue base in regulated verticals.
End User:
Application-specific thermal and certification requirements fragment procurement specifications, with banking and healthcare verticals imposing the most stringent material compliance and data sovereignty constraints.
- IT:Technology sector demand spans hyperscale cloud operators, enterprise SaaS providers, and telecommunications infrastructure across the full density spectrum from edge micro servers to AI training clusters.
- Banking:Financial services procurement prioritizes NEBS-compliant configurations for trading floor proximity and sub-millisecond latency requirements in Singapore and Hong Kong.
- Healthcare:Australian and Japanese medical data centers are retrofitting liquid cooling to accommodate genomic sequencing and medical imaging workloads under tightening localization mandates.
- Education:University and research institute procurement concentrates in Korea's K-REIT funded science parks and India's IIT network for HPC and AI research infrastructure.
IT verticals anchor procurement volume while healthcare climbs the fastest on imaging and genomics infrastructure expansion.
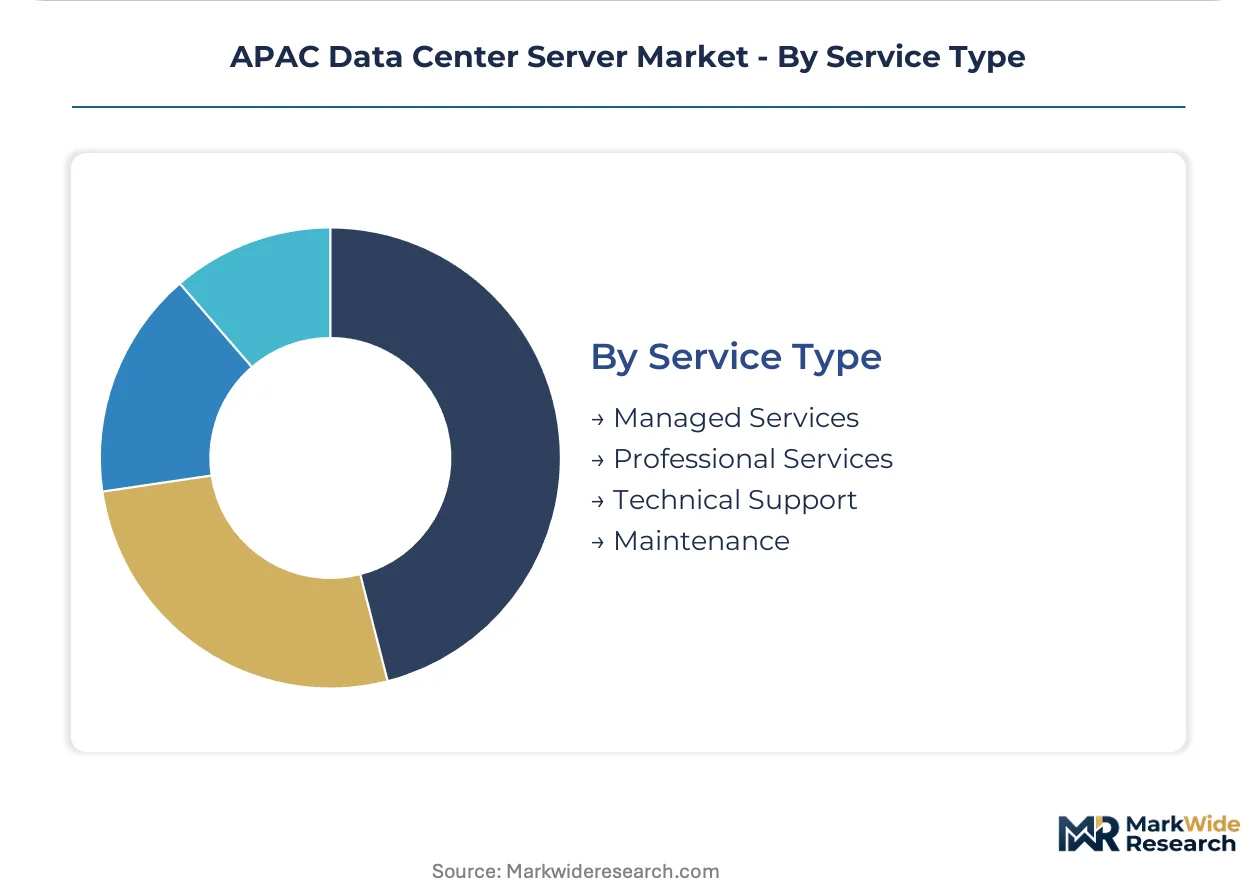
Service Type:
Customer type stratification separates asset-light operators seeking full operational transfer from capital-retentive buyers requiring discrete technical interventions.
- Managed Services:End-to-end operational outsourcing is gaining traction among Australian mid-market enterprises and Southeast Asian e-commerce platforms lacking in-house facility engineering expertise.
- Professional Services:Design and implementation consulting concentrates in China's MIIT compliance retrofit market and India's BIS certification navigation for foreign OEM market entry.
- Technical Support:Break-fix and remote monitoring contracts dominate the installed base across Japan's aging enterprise data center fleet and Taiwan's semiconductor manufacturing support infrastructure.
- Maintenance:Hardware lifecycle services face compression as eighteen-month AI server refresh cycles in Southeast Asian hyperscale facilities erode traditional four-year maintenance contract economics.
Technical support anchors the services revenue base while managed services gains share fastest on operator skill scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Server procurement patterns across APAC diverge sharply by national regulatory architecture and power infrastructure maturity. China's MIIT efficiency mandates drive liquid-cooled retrofits in legacy facilities. India's BIS certification requirements reshape import-dependent supply chains toward domestic assembly. Singapore's electrical capacity constraints cap deployment growth despite financial services demand.
China
Hyperscale cloud operators and state-owned enterprises anchor server volume under MIIT PUE thresholds below 1.3 for new facility approvals. The ministry's real-time monitoring requirements for facilities above 6MW accelerate retrofits in Beijing and Shanghai legacy data centers. Domestic operators now procure exclusively liquid-cooled servers for new installations, effectively prohibiting air-cooled architectures from 2024.
India
Reliance Jio and Tata Communications compress qualified supplier pools from twelve vendors to five under three-year total cost of ownership metrics. BIS compulsory registration schemes for imported IT equipment cascade through the Mumbai-Pune corridor, accelerating in-country assembly investments. The Digital Personal Data Protection Act's localization mandates force foreign OEMs to establish domestic manufacturing footprints.
Singapore
Tuas data center zone operators face hard electrical capacity limits that cap new server deployments despite unmet financial services tenant demand. IMDA sustainability standards shape cooling technology roadmaps toward direct liquid configurations. Wholesale colocation providers navigate split workload architectures for Australian healthcare networks and Japanese automotive simulation clusters.
Japan
Tokyo and Osaka financial services data centers retain blade server traction where VMware virtualization density justifies shared infrastructure. METI supply chain emissions disclosure guidelines enable premium positioning for servers with verified embodied carbon certificates. Automotive simulation clusters adopt direct liquid cooling for thermal loads exceeding 500W per processor.
Australia
Sydney hyperscale builds standardize on cold plate liquid cooling systems for deployments exceeding 30kW per rack. TGA data localization rules for healthcare records drive hybrid workload architectures across private infrastructure and sovereign cloud zones. Mining technology companies in Western Australia adopt tower server configurations where rack infrastructure proves economically impractical.
APAC Data Center Server Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the APAC Data Center Server Market. Dell Technologies and Huawei Technologies occupy positions of scale through localized manufacturing and captive semiconductor supply. Three archetypes dominate competitive positioning: vertically integrated domestic champions, multinational OEMs with regional assembly footprints, and specialist fabricators serving hyperscale cloud operators. Competitive moves concentrate on geographic diversification of manufacturing and qualification of Arm-based processor architectures for power-constrained facilities.
Among multinational OEMs with regional presence, Dell Technologies exemplifies the direct sales and localized manufacturing archetype through its Penang operations. Huawei Technologies anchors the integrated domestic champion position through in-house Arm-based processor production. Inspur Group occupies the hyperscale procurement specialist tier with vertically integrated supply chains spanning Jinan and Suzhou. These three represent distinct strategic postures rather than interchangeable competitors.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| Lenovo Group Limited |
| Cisco Systems |
| Fujitsu |
| IBM Corporation |
| Huawei Technologies |
| Inspur Group |
| Super Micro Computer |
| Others |
Pricing and Supply Chain Analysis
India's BIS compulsory registration scheme gates both supplier qualification and price stratification simultaneously, forcing foreign OEMs to absorb domestic assembly costs while tier-1 operators leverage volume scale for preferential pricing.
Pricing Analysis
Long-term offtake agreements dominate hyperscale procurement across Singapore's Tuas zone and India's Mumbai-Pune corridor, compressing spot-market participation to distressed inventory clearance. Three-tier pricing structure across liquid-cooled premium, air-cooled standard, and refurbished economy levels reflects certification grade and thermal architecture differentiation. Pricing pressure stems from India's phased manufacturing program tariffs, which raise landed costs for fully assembled imports against domestic assemblers. Hyperscale cloud operators exhibit lowest price sensitivity due to TCO-based selection, while Southeast Asian colocation tenants face acute cost compression.
Supply Chain Analysis
Strategic stockpiling of CoWoS substrates and high-bandwidth memory modules characterizes hyperscale procurement behavior, contrasting with just-in-time chassis assembly from Malaysian and Vietnamese facilities. Taiwan, South Korea, and China anchor critical component supply, with advanced packaging capacity concentrated in Hsinchu and Seoul. Server production draws from Penang motherboard fabrication, Bac Ninh chassis stamping, and Suzhou system integration. Single-source vulnerability in AI accelerator card production constrains deployment timelines. Distribution runs through direct OEM sales forces for enterprise accounts and distributor networks for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arm-based processor substitution threatens x86 incumbents as hyperscale buyers qualify Neoverse architectures for power-constrained facilities, forcing established vendors to defend socket share through cooling-integrated bundling.
For Market Incumbents: Compound localization investments in Penang and Bac Ninh to offset India's cascading import tariffs while qualifying direct liquid cooling configurations as standard offerings. Capture BIS certification workflows to lock out unqualified competitors. Prioritize three-year TCO guarantees against emerging Arm-based challengers. For New Entrants and Emerging Players: BIS fast-track registration for imported subassemblies opens immediate market access without full domestic manufacturing commitment. Target Australia's TGA-compliant healthcare infrastructure where liquid cooling retrofits outpace incumbent response times. Lead with carbon accounting integration under Japan's METI disclosure guidelines as differentiation wedge. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed colocation operators in Singapore's capacity-constrained Tuas zone facing hard electrical limits. Five-to-ten year viability hinges on workload migration to edge and sovereign cloud alternatives. Watch for MIIT PUE threshold relaxation in China's legacy facility retrofit market as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Footprint Expansion | BIS registration compliance unlocks India's hyperscale procurement pools for foreign OEMs. |
| Liquid Cooling Technology Licensing | Direct-to-chip IP partnerships accelerate retrofit timelines in Beijing and Shanghai legacy facilities. |
| Arm Processor Architecture Qualification | Neoverse-based designs penetrate Singapore's power-constrained financial services clusters. |
| Carbon Certification Program Development | Verified embodied carbon credentials command premium positioning under Japan's METI guidelines. |
| Edge Micro Data Center Partnership | NEBS-compliant configurations capture Korean 5G network slicing deployment demand. |
Research Methodology
Cross-validation between hyperscaler capex disclosures and vendor shipment records anchors the qualitative findings, with primary interviews of data center facility engineers, procurement directors at cloud operators, BIS certification consultants, and liquid cooling system integrators triangulated against secondary sources including MIIT facility registries, IMDA sustainability filings, and customs import manifests. Bottom-up server unit estimates by socket type and thermal architecture reconcile with top-down infrastructure investment flows across the analysis window.
Sensitivity analysis around CoWoS substrate availability and India tariff phase-in schedules shapes the projection framework, with segmentation across rack height, cooling method, deployment model, and end-user vertical modeled throughout the forecast period. CAGRs derive from unit shipment trajectories weighted by average selling price migration toward liquid-cooled premium tiers. Hyperscale GPU cluster refresh frequency and sovereign cloud localization mandates constitute key forecast inputs.
Underlying assumptions cover sustained AI training workload expansion and regulatory enforcement continuity, with deviation risk concentrated in Taiwan semiconductor supply disruptions and India BIS procedural delays. Revision becomes warranted when Arm architecture penetration in hyperscale sockets crosses threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
US Data Center Construction Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Israel Data Center Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
Thailand Data Center Power Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
DC Powered Servers Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market