
 United Kingdom Data Center Market | 2026-2036
United Kingdom Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Data Center Market Analytics
Greater London is rewriting capacity dynamics across the United Kingdom data center landscape as power-constrained development pushes operators toward satellite locations. Vantage Data Centers leverages its European platform to secure large-scale land and power allocations outside the M25 ring. Equinix anchors the interconnection ecosystem through its Telecity portfolio, sustaining premium pricing in core metro fiber nodes. Digital Realty competes on hyperscale-ready shell capacity, while VIRTUS Data Centres specializes in high-density AI workloads with direct liquid cooling architectures.
A data center constitutes a purpose-built facility housing compute, storage, and networking infrastructure with redundant power, cooling, and connectivity systems engineered to maintain availability above 99.99%. These installations process, store, and distribute digital information for enterprises, cloud providers, and telecommunications carriers requiring continuous operations. Colocation remains the dominant revenue architecture, though cloud services represent the fastest-expanding segment as multi-cloud strategies displace single-vendor dependencies. Managed hosting retains margin strength in regulated sectors where data residency requirements override pure infrastructure economics. Deployment patterns favor hybrid configurations, with on-premises retention for latency-sensitive workloads and off-premises scaling for variable demand cycles.
Ofgem's electricity grid connection queue reforms and the UK Building Regulations Part L efficiency standards directly shape facility design decisions and location viability across England, Scotland, and Wales. The Environment Agency's water abstraction permits constrain cooling system choices in southeastern catchments, favoring closed-loop designs or air-cooled alternatives. Stakeholders must monitor local authority planning interpretations of national policy statement EN-3, as inconsistent consent timelines between Slough, Newham, and Trafford councils create arbitrage opportunities for early movers.
Market Dynamics
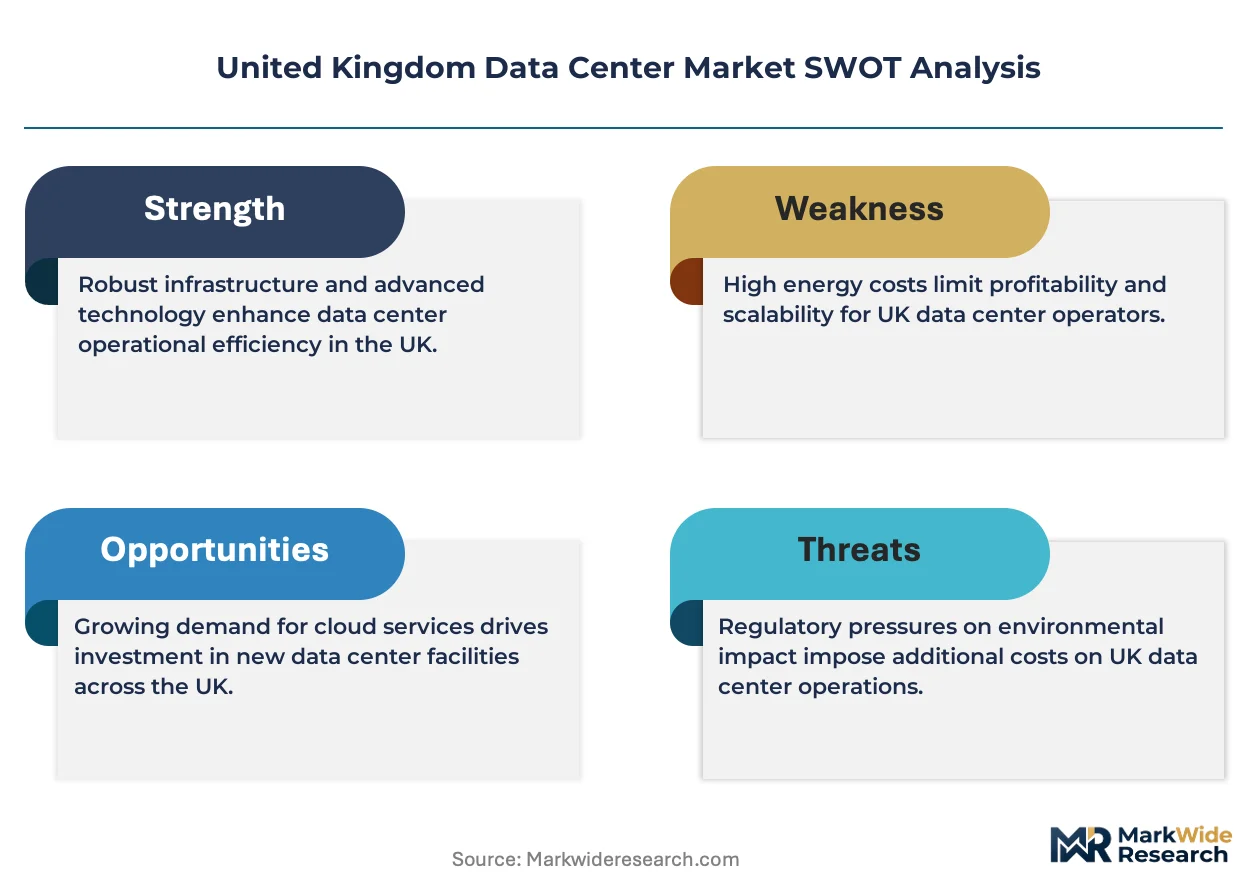
Power scarcity across Greater London is forcing operators into satellite geographies, while liquid cooling architectures are compressing facility design timelines to meet tightening efficiency mandates under Part L of the UK Building Regulations.
Growth Catalysts
- AI compute density:Generative AI training clusters require 40-100 kW per rack, driving demand for direct liquid cooling infrastructure that traditional air-cooled facilities cannot support.
- Ofgem grid reforms:Connection queue restructuring accelerates energization timelines for approved projects, reducing capital lock-up periods for speculative developments.
- Financial services migration:London-based banks and trading venues require sub-millisecond latency to matching engines, sustaining premium colocation demand in core metro fiber nodes.
Market Restraints
- Grid connection scarcity:Transmission capacity constraints in Slough and West London delay project energization by 24-36 months regardless of planning consent status.
- Copper and aluminum volatility:Busbar and cabling materials constitute 12-15% of electrical infrastructure costs, exposing margins to commodity price swings.
- Water abstraction limits:The Environment Agency's catchment-level permits restrict once-through cooling in southeastern England, forcing expensive closed-loop retrofits.
Strategic Opportunities
- Manchester and Birmingham corridors:Secondary markets offer 30-40% lower land costs and available grid capacity for hyperscale deployments outside the M25 constraint zone.
- Waste heat recovery:District heating integration with local authority heat networks converts thermal output into revenue streams under the UK Green Deal framework.
- Battery energy storage co-location:BESS assets provide grid services revenue and backup power, optimizing land use where substation capacity is fixed.
Industry Challenges
- Specialized mechanical contracting:Direct liquid cooling installation requires certified technicians in short supply, extending commissioning timelines.
- Planning consent inconsistency:Local authority interpretations of national policy statement EN-3 vary between Slough, Newham, and Trafford councils, creating approval timeline arbitrage.
- Legacy facility retrofit:Raised floor and air-cooled designs from 2015-2019 vintages face stranded asset risk as density requirements exceed original mechanical specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Data Center Market |
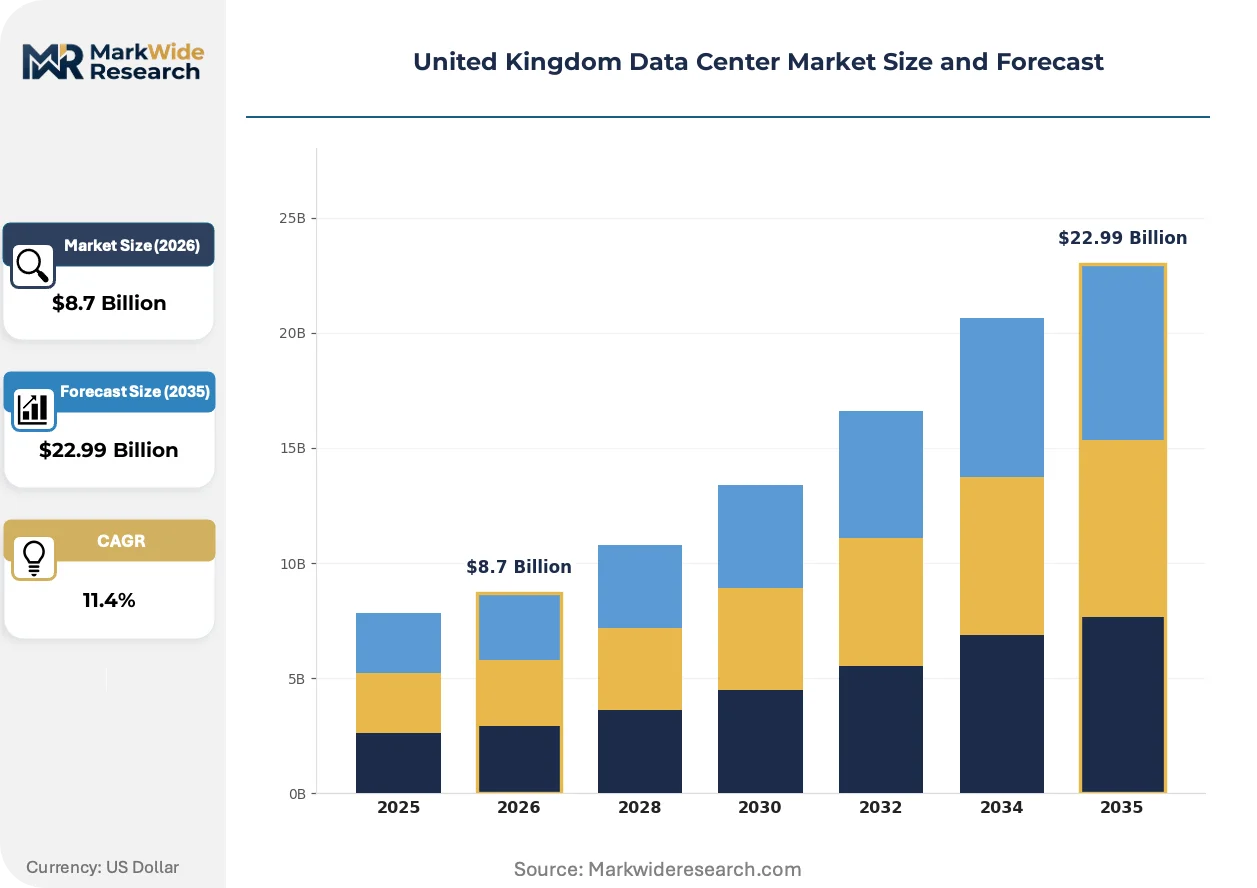
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Hosting, Cloud Services, Disaster Recovery End User: SMEs, Large Enterprises, Government, Telecom Providers Deployment: On-Premises, Off-Premises, Hybrid, Multi-Cloud Technology: Hyper-Converged, Software-Defined, Rack Servers, Networking Equipment |
| Companies Covered | Vantage Data Centers, Telehouse, VIRTUS Data Centres, Kao Data, Global Switch, Equinix, Ark Data Centres, NTT Corporation, Digital Realty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Data Center Market Evolving Landscape
Facility architecture is converging around thermal management as the primary design constraint, with power density requirements from AI workloads compressing traditional infrastructure planning horizons.
Direct liquid cooling is collapsing the distinction between high-performance computing and enterprise data center specifications. Hyperscale operators now specify 50-80 kW rack densities as standard for new builds, forcing mechanical engineers to abandon perimeter cooling entirely. This convergence is enabling modular factory-built systems that slash on-site construction timelines.
The UK Building Regulations Part L 2021 amendments mandate 15% efficiency improvements over 2013 baselines, with 2025 updates targeting net-zero ready standards. Facility designers must now model whole-life carbon alongside operational energy, favoring all-electric mechanical systems over gas-fired absorption chillers. Slough-based operators face the strictest local authority interpretations, driving specification divergence from Manchester approvals.
Enterprise buyers are consolidating vendor relationships around single hyperscale-cloud-hybrid portfolios rather than maintaining separate colocation and managed hosting contracts. Financial services firms in the City of London now procure infrastructure as integrated capacity blocks spanning on-premise, edge, and public cloud. This bundling is compressing pricing transparency and favoring operators with vertically integrated platform breadth.
United Kingdom Data Center Market Segmentation
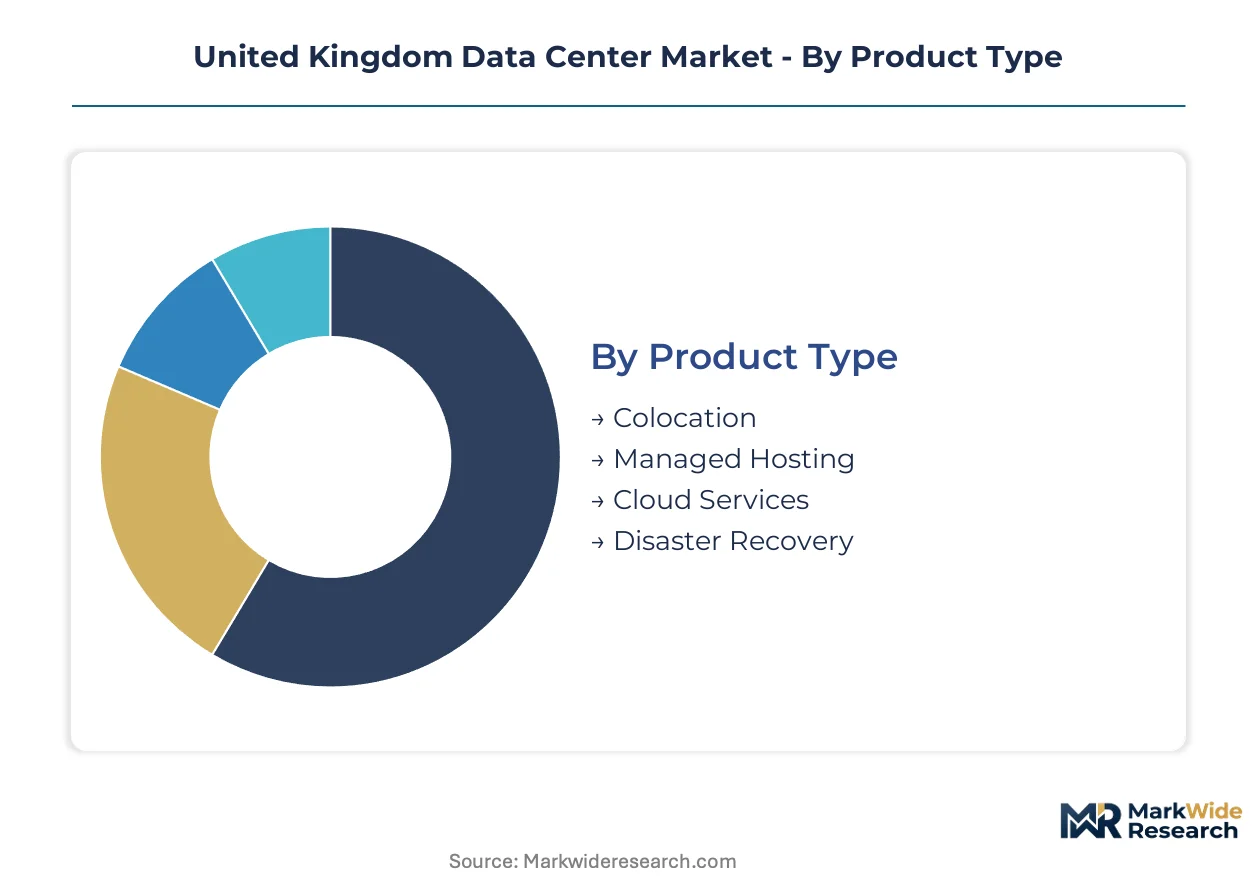
Segmentation in the United Kingdom data center market reveals how workload diversity and regulatory pressure fragment procurement patterns. Enterprise buyers now specify infrastructure across multiple deployment models simultaneously, while Ofgem grid reforms and Part L efficiency mandates reshape technology choices.
Product Type:
Colocation absorbs the majority of enterprise spend as firms exit owned facilities, though cloud services capture the steepest expansion trajectory as multi-cloud strategies displace single-vendor dependencies.
- Colocation:Third-party facilities provide redundant power, cooling, and physical security with cross-connect options to carrier hotels. London-based financial services firms sustain premium pricing in Telecity and Slough fiber nodes due to sub-millisecond latency requirements for matching engines.
- Cloud Services:Public and private cloud delivery models enable elastic capacity scaling without capital commitment. UK government cloud-first policies and G-Cloud procurement frameworks accelerate public sector migration, while enterprise buyers consolidate around hyperscale-hybrid portfolios.
- Managed Hosting:Fully outsourced infrastructure operations retain margin strength in regulated sectors where data residency requirements override pure infrastructure economics.
- Disaster Recovery:Secondary site replication and business continuity services concentrate in Manchester and Birmingham corridors where land and power costs run 30-40% below Greater London levels.
Established volume favors colocation; emerging adoption favors cloud services.
End User:
Procurement scale determines facility specification, with large enterprises driving hyperscale construction and SMEs gravitating toward standardized colocation suites.
- Large Enterprises:Banks, insurers, and pharmaceutical firms procure dedicated data halls or build-to-suit facilities with direct liquid cooling for AI training clusters. These buyers negotiate long-term power purchase agreements and demand 99.999% availability with N+2 redundancy.
- SMEs:Mid-market firms purchase rack-by-rack colocation with managed service overlays, prioritizing operational expenditure conversion over capital deployment.
- Government:Central and local authorities mandate UK-sovereign data residency, restricting vendor selection to OFFICIAL and SECRET-cleared facilities under the Government Security Classifications Policy.
- Telecom Providers:Mobile network operators and internet exchange points require edge-distributed capacity for 5G core networks and content delivery, driving micro data center deployment in secondary cities.
Contract value concentrates with large enterprises; procurement velocity runs highest among SMEs.
Deployment:
Architecture choices reflect latency tolerance, with financial trading systems anchoring on-premise retention while variable workloads migrate off-premises.
- Hybrid:Integrated on-premise and cloud capacity blocks allow firms to retain sensitive data locally while bursting compute to public cloud. City of London trading venues deploy hybrid configurations to maintain direct market access while offloading risk analytics.
- Multi-Cloud:Distributing workloads across AWS, Azure, and Google Cloud mitigates vendor lock-in and satisfies resilience requirements. Enterprise buyers now specify multi-cloud as standard procurement policy.
- On-Premises:Legacy enterprise data centers persist where data sovereignty, ultra-low latency, or specialized hardware requirements preclude third-party hosting.
- Off-Premises:Full outsourcing to colocation or cloud eliminates facility management overhead, favored by firms exiting real estate ownership.
Hybrid architectures dominate current deployment; multi-cloud configurations are gaining share fastest.
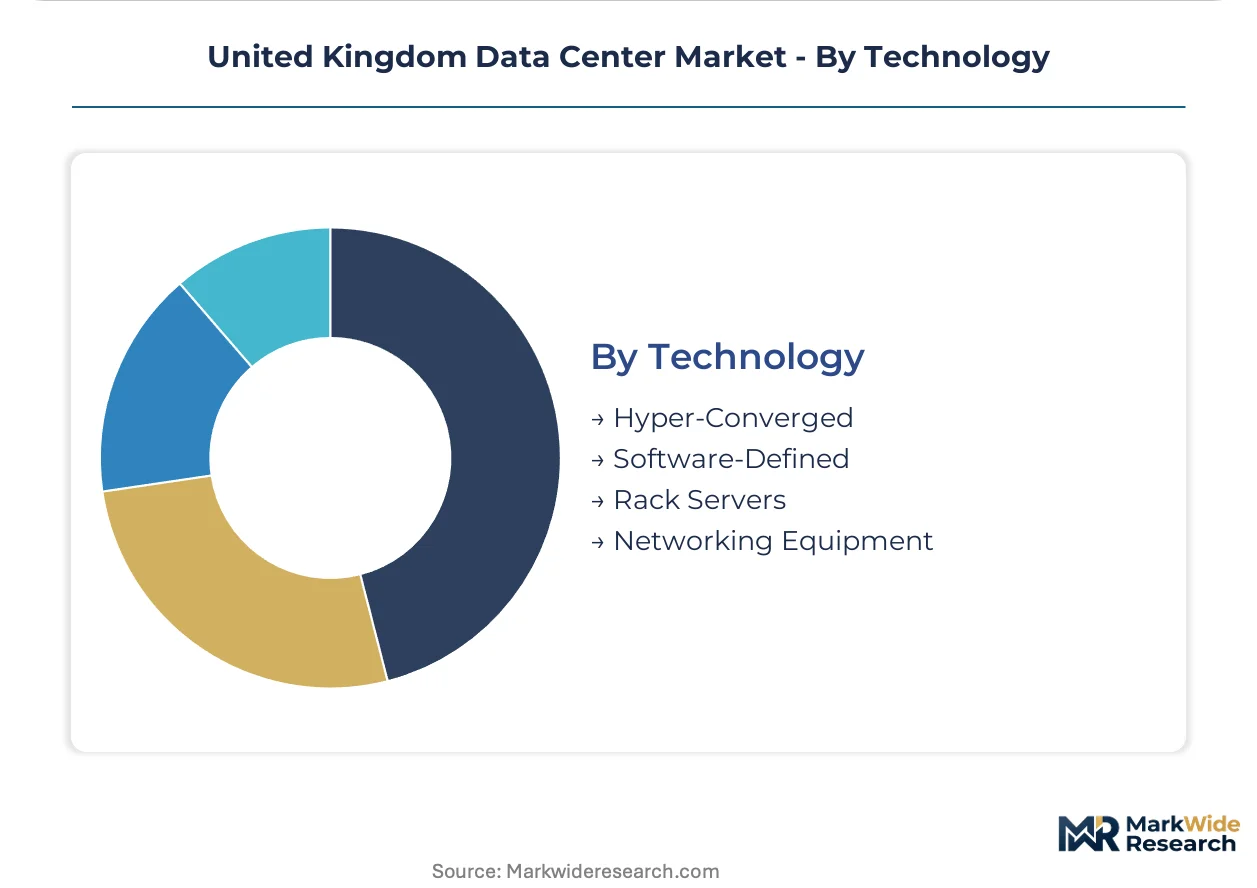
Technology:
Mechanical and compute infrastructure convergence determines facility competitiveness as rack densities climb past 50 kW.
- Hyper-Converged:Integrated compute, storage, and networking appliances collapse three-tier architecture into single-vendor stacks. These systems reduce rack footprint and cabling complexity in space-constrained London facilities.
- Software-Defined:Virtualized infrastructure management enables workload portability across physical locations, supporting disaster recovery and cloud bursting objectives.
- Rack Servers:Standard 19-inch mount equipment remains the baseline compute form factor, though air-cooled designs face stranded asset risk as AI densities exceed original mechanical specifications.
- Networking Equipment:Spine-leaf architectures and 400G optical interconnects support east-west traffic patterns in distributed computing environments.
Hardware procurement favors rack servers; architectural transformation favors hyper-converged platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ofgem anchors Greater London's data center development through grid connection queue reforms that accelerate energization timelines for approved projects. Power scarcity across the metropolitan area pushes operators toward satellite geographies with available transmission capacity.
London and the Southeast
Financial services firms sustain premium colocation demand in core metro fiber nodes due to sub-millisecond latency requirements for trading matching engines. The UK Building Regulations Part L mandates 15% efficiency improvements over 2013 baselines, with 2025 updates targeting net-zero ready standards. Slough corridor operators face strictest local authority interpretations of national policy statement EN-3, driving specification divergence from other approvals.
Midlands
Hyperscale deployments concentrate in Birmingham where land costs run 30-40% below Greater London levels and grid capacity remains available. The Environment Agency's water abstraction permits constrain cooling system choices less severely than southeastern catchments, favoring facility expansion. West Midlands local authorities interpret planning frameworks with shorter consent timelines than Slough or Newham councils.
North England
Manchester anchors secondary market growth with available substation capacity and lower development barriers for speculative builds. Ofgem's queue restructuring benefits approved projects in this corridor with reduced capital lock-up periods. Trafford council planning interpretations create arbitrage opportunities against slower-consent southern jurisdictions.
Scotland
Cooler ambient temperatures reduce mechanical cooling loads for facilities targeting AI training clusters requiring 40-100 kW per rack. Scottish local authorities apply national policy statement EN-3 with consistent timelines absent the variance seen in English jurisdictions. Edinburgh and Glasgow clusters attract operators seeking renewable energy procurement advantages.
Wales
Enterprise workloads migrate to Cardiff and Newport facilities as enterprise buyers exit on-premises infrastructure. The UK government's net-zero targets accelerate demand for sustainably powered facilities with closed-loop cooling designs. Welsh Development Agency programs support data center investment through infrastructure grant frameworks.
United Kingdom Data Center Market Competitive Landscape
Hyperscale specialists and interconnection-focused operators split the market between capacity-led and connectivity-led value propositions. The vendor base concentrates around three strategic archetypes: European platform operators with multi-country development capabilities, London-centric interconnection specialists leveraging fiber density, and domestic specialists targeting high-density AI workloads. Competitive moves center on land and power allocation contests outside the M25 constraint zone, plus direct liquid cooling capability buildout to serve generative AI training clusters.
Among platform operators with European scope, Vantage Data Centers exemplifies the land-banking archetype securing large-scale allocations ahead of grid constraints. Telehouse and Equinix occupy positions within the interconnection tier, anchoring premium pricing through carrier hotel density in core metro nodes. VIRTUS Data Centres represents the domestic specialist archetype focusing on high-density AI workloads with direct liquid cooling architectures.
| Leading Market Players |
|---|
| Vantage Data Centers |
| Telehouse |
| VIRTUS Data Centres |
| Kao Data |
| Global Switch |
| Equinix |
| Ark Data Centres |
| NTT Corporation |
| Digital Realty |
| Others |
Value Network & Pricing Analysis
Copper and aluminum concentrate in Chinese and Chilean smelting operations, concentrating margin capture with electrical infrastructure suppliers who pass commodity volatility through to UK facility operators under cost-plus contract structures. This upstream concentration compresses downstream pricing power for data center developers locked into fixed-price colocation agreements with enterprise tenants.
Pricing Analysis
Greater London commands 40-50% premiums over Manchester and Birmingham for equivalent power density specifications. Pricing stratifies across hyperscale shell capacity, premium interconnection nodes, and standard colocation tiers based on latency performance and redundancy certification. Cost compression in air-cooled legacy facilities is intensifying because AI training clusters demand direct liquid cooling retrofits that incumbent operators struggle to finance. SMEs exhibit highest price sensitivity and migrate fastest to secondary markets, while financial services firms in the City of London absorb premiums for sub-millisecond fiber access.
Supply Chain Analysis
Upstream electrical feedstock draws from Chinese cable manufacturing, German switchgear production, and Nordic renewable energy equipment. Critical inputs span copper busbar, aluminum cabling, and lithium-ion battery modules for backup power systems. Single-source vulnerability concentrates in Chinese transformer production under EU import tariff exposure. Distribution runs through specialized mechanical contractors certified in direct liquid cooling installation, creating chokepoints in facility commissioning timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom data center market is recovering from a capital deployment trough as Ofgem grid queue reforms unlock previously stalled projects. This cyclical inflection favors operators with pre-approved land and power allocations.
For Market Incumbents: Harden power security through battery energy storage co-location at constrained substations, converting grid services into revenue streams. Deepen backward integration into waste heat recovery infrastructure to capture district heating revenue under the UK Green Deal framework. Liquid cooling capability scarcity threatens margin erosion for air-cooled legacy portfolios.
For New Entrants and Emerging Players: Pursue Manchester and Birmingham corridors where planning consent timelines run shorter than Slough or Newham jurisdictions. Enterprise disaster recovery workloads offer the most penetrable segment, with buyers prioritizing cost reduction over latency performance. Lead with modular factory-built liquid cooling systems that compress construction timelines against incumbent on-site build schedules.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with European platform operators holding speculative land positions outside the M25 constraint zone. Long-term viability hinges on securing energization timelines ahead of grid saturation across the analysis window. Monitor Ofgem connection queue priority allocations as the inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Deployment | Enables 50-80 kW rack densities for AI training clusters that air-cooled facilities cannot support. |
| Grid Connection Queue Positioning | Ofgem reforms reward early applicants with accelerated energization timelines against 24-36 month delays. |
| Waste Heat Recovery Integration | District heating partnerships with local authorities convert thermal output into regulated revenue streams. |
| Battery Energy Storage Co-location | BESS assets provide grid frequency services and backup power optimization where substation capacity is fixed. |
| Secondary Market Geographic Expansion | Manchester and Birmingham offer 30-40% land cost advantages with available transmission capacity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center facility managers, hyperscale cloud procurement officers, mechanical engineering contractors, and local authority planning officers. Secondary validation drew from Ofgem regulatory filings, UK Building Regulations Part L documentation, Environment Agency water abstraction permits, and grid connection queue databases. Bottom-up capacity installation tracking and top-down enterprise IT spend analysis were triangulated to reconcile supply and demand estimates.
Calibration against historical energization timelines and planning consent databases refined the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user scale, deployment architecture, and cooling technology specification. CAGRs were derived from installed base growth rates and power density evolution curves. Forecast inputs incorporated AI compute demand trajectories and Part L efficiency mandate compliance costs.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments or construction labor availability would shift the trajectory of speculative development starts. Forecasts reflect assumptions about grid queue reform implementation pace and local authority planning consistency. Cross-checking against hyperscaler capex disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Hong Kong Data Center Construction Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Norway Data Center Networking Market
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Norway Data Center Power Market