
 Norway Data Center Market | 2026-2036
Norway Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Data Center Market Insights
Wholesale colocation channels in Norway is tilting toward hyperscale-first contracting as international cloud providers seek Nordic cooling advantages. Green Mountain leverages its fjord-cooled facilities to anchor sustainability-sensitive enterprise demand. Bulk Infrastructure competes through submarine cable ownership that extends connectivity options across the North Atlantic. Lefdal Mine Data Centers positions its underground facility to capture high-density computing requirements with minimal mechanical refrigeration.
A data center constitutes a dedicated facility housing servers, storage systems, and networking equipment operating within controlled temperature bands typically between 18°C and 27°C, designed to process, store, and distribute digital information for enterprise and consumer applications. Colocation deployment models dominate Norwegian capacity absorption as enterprises divest owned infrastructure. Edge computing segments within the technology dimension attract investment from telecommunications operators building low-latency nodes for industrial automation clients. Managed services generate recurring revenue pools that offset capital-intensive facility construction cycles.
Datatilsynet, Norway's data protection authority, enforces GDPR-aligned sovereignty requirements that restrict cross-border data flows for public sector end users. The Norwegian Water Resources and Energy Directorate regulates hydroelectric allocation, directly influencing power purchase agreement structures for facility operators. Stakeholders must monitor whether proposed EU AI Act transparency obligations will reclassify inference workloads and trigger additional compliance infrastructure investments.
Market Dynamics
Hyperscale cloud providers are compressing contract timelines and demanding renewable power guarantees that exceed standard utility offerings, forcing Norwegian operators to restructure power purchase agreements with the Norwegian Water Resources and Energy Directorate.
Growth Catalysts
- AI training workload surge:International enterprises are expanding colocation footprints to access Nordic cooling efficiencies for GPU-intensive clusters. Datacenters near submarine cable landing points capture latency-sensitive financial services demand.
- Hydroelectric power mandates:The Norwegian Water Resources and Energy Directorate enforces strict renewable allocation rules that favor facilities with direct fjord-cooling integration. This regulatory preference accelerates permit approvals for sustainable designs.
- Oslo-Stavanger corridor concentration:Submarine cable landing clusters in this corridor create natural connectivity hubs. Operators colocating here reduce cross-border latency for North Atlantic data flows.
Market Restraints
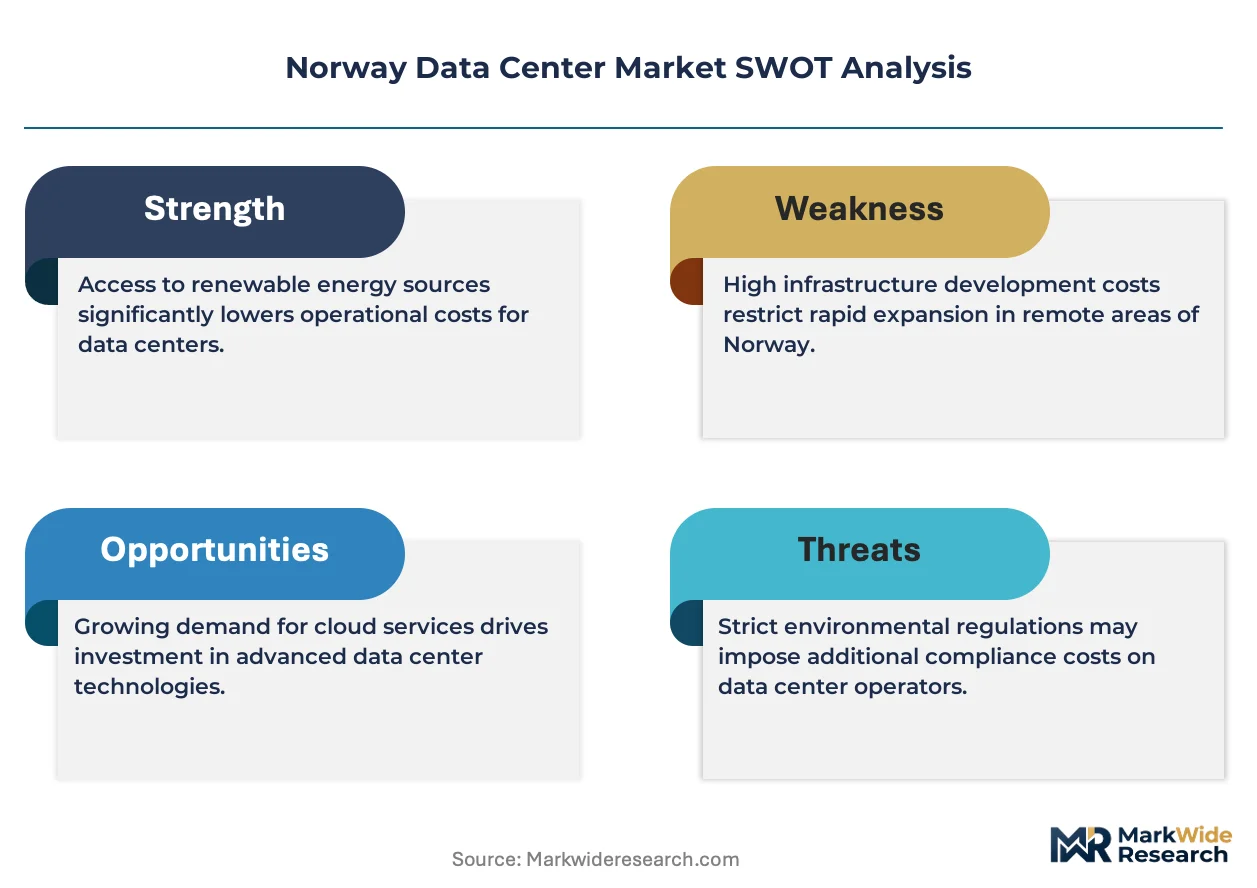
- Power allocation scarcity:The Norwegian Water Resources and Energy Directorate limits new hydroelectric connections to industrial consumers, constraining facility expansion timelines for operators without grandfathered agreements.
- Geographic supply concentration:Submarine cable landing points cluster almost exclusively along the western fjord corridor, creating single-point-of-failure risks for connectivity-dependent workloads.
- Labor specialization gaps:High-voltage electrical technicians with data center certification remain concentrated in Oslo, forcing remote facility operators to import skilled crews or extend construction schedules.
Strategic Opportunities
- Tromsø edge node development:Northern Norway's subsea cable connections to Asia-Pacific markets remain underutilized. Low-latency edge facilities here could serve Arctic research and maritime autonomous systems.
- EU AI Act compliance infrastructure:Proposed transparency obligations for inference workloads may require dedicated audit-ready facilities. Norwegian operators with existing sustainability certifications can capture this compliance-driven demand.
- Liquid cooling convergence:Integration of direct-to-chip cooling with fjord water systems enables power usage effectiveness ratios below industry averages. This technology pairing attracts density-sensitive AI training contracts.
Industry Challenges
- Datatilsynet sovereignty enforcement:GDPR-aligned restrictions on cross-border data flows for public sector clients require architectural segmentation that increases operational complexity and compliance staffing.
- Capex intensity for underground retrofits:Lefdal-style mine conversions demand specialized structural reinforcement and humidity control systems that extend payback periods beyond standard greenfield construction.
- Integration friction with legacy enterprise systems:Financial services clients migrating from on-premise infrastructure require hybrid connectivity architectures that strain colocation network engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Data Center Market |
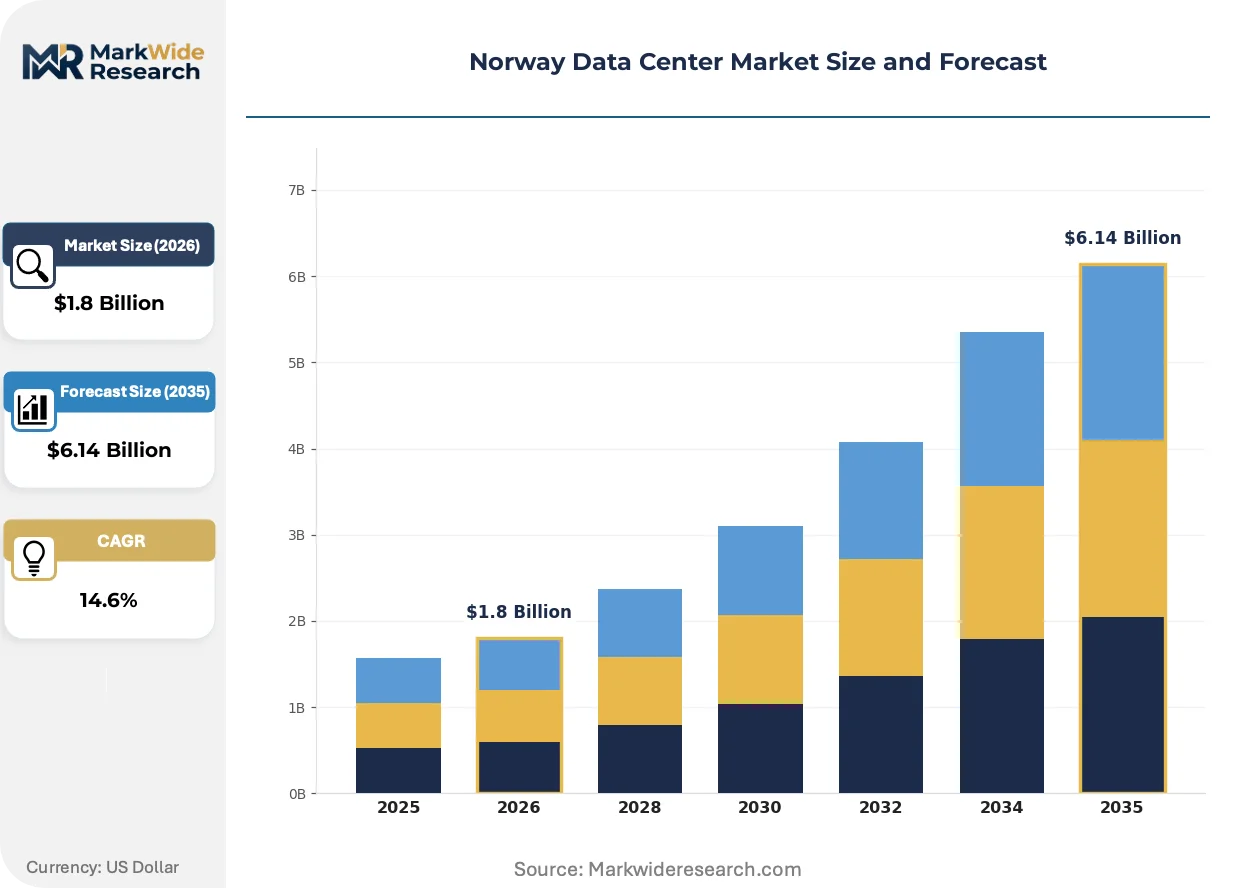
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Colocation Technology: AI, IoT, Edge Computing, Virtualization Service Type: Managed Services, Disaster Recovery, Hosting, Network Services End User: SMEs, Enterprises, Government, Healthcare |
| Companies Covered | Green Mountain, Bulk Infrastructure, STACK Infrastructure, Lefdal Mine Data Centers, AQ Compute, Orange Business, Telia, Google, Microsoft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Data Center Market Trends and Innovations
Software-defined infrastructure is displacing hardware-centric operational models across Norwegian facilities, compressing provisioning timelines and enabling dynamic workload orchestration that matches renewable power availability curves.
Software-defined power distribution is virtualizing electrical infrastructure management across hyperscale facilities. Operators are adopting intelligent rack-level monitoring to match consumption with hydroelectric generation peaks. This virtualization is enabling real-time capacity reallocation that maximizes renewable utilization without mechanical redundancy.
Datatilsynet is tightening cross-border data flow enforcement for public sector contracts, requiring architectural proof of jurisdictional containment. Facility operators must now demonstrate physical and logical segmentation that satisfies GDPR Article 44 transfer mechanism audits. Healthcare and government verticals are responding by mandating sovereign cloud zones with certified Norwegian operational control.
Enterprise buyers are unbundling managed services from colocation contracts, preferring bare-metal leasing with self-operated orchestration layers. Channel relationships with systems integrators are displacing direct facility relationships for mid-market clients. This pattern concentrates in Oslo's financial services cluster, where compliance teams demand direct control over encryption key management and access logging infrastructure.
Norway Data Center Market Segmentation
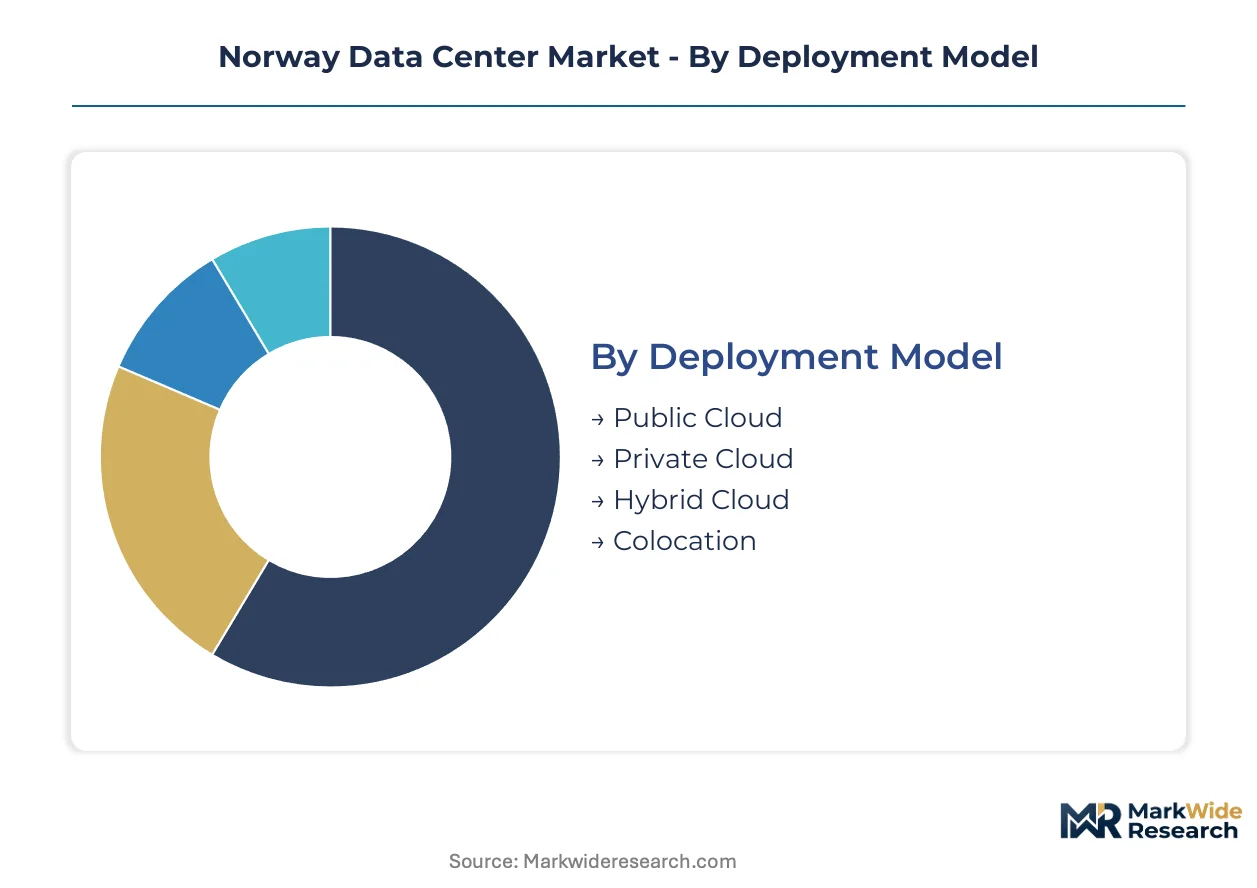
Norwegian data center procurement patterns diverge sharply across deployment models and end-user governance requirements. Datatilsynet's sovereignty enforcement creates segment-specific compliance architectures that reshape facility design and service bundling.
Deployment Model:
After-sales service intensity varies dramatically across deployment architectures, with colocation operators embedding 24/7 remote hands while public cloud providers abstract physical infrastructure entirely.
- Colocation:Enterprises lease physical rack space and power while retaining hardware ownership. Financial services clusters in Oslo demand sovereign zones with Norwegian operational control to satisfy Datatilsynet audits.
- Hybrid Cloud:Workloads split between on-premise infrastructure and third-party facilities based on sensitivity classification. Norwegian enterprises migrating from legacy systems favor this architecture for phased divestment of owned data centers.
- Private Cloud:Dedicated infrastructure serving single-tenant requirements with customized security boundaries. Healthcare verticals mandate this model for patient data processing under GDPR Article 9 special category protections.
- Public Cloud:Multi-tenant shared infrastructure with standardized service tiers. Hyperscale providers compress contract timelines here, demanding renewable power guarantees exceeding standard utility offerings.
Colocation holds the largest share; momentum sits with Hybrid Cloud.
Technology:
Application intensity determines technology adoption sequencing, with AI training workloads commanding premium facility specifications while virtualization underpins baseline operational efficiency.
- AI:GPU-intensive clusters require direct-to-chip liquid cooling integrated with fjord water systems. International enterprises expand colocation footprints specifically to access Nordic cooling efficiencies for these workloads.
- Edge Computing:Distributed nodes process data proximate to generation sources. Telecommunications operators build low-latency infrastructure for industrial automation clients along the Oslo-Stavanger corridor.
- Virtualization:Software-defined infrastructure abstracts physical compute resources into elastic pools. This technology compresses provisioning timelines and enables dynamic orchestration matching renewable power availability curves.
- IoT:Sensor networks generate continuous data streams requiring localized aggregation. Maritime autonomous systems in northern Norway drive demand for Tromsø-area edge facilities with subsea cable connectivity.
Virtualization dominates installed base; AI is expanding most quickly.
Service Type:
Margin structures differentiate service categories, with managed services generating recurring revenue pools that offset capital-intensive construction cycles while network services command premium pricing based on submarine cable proximity.
- Managed Services:Operators assume responsibility for monitoring, maintenance, and optimization. Enterprise buyers increasingly unbundle these from colocation contracts, preferring bare-metal leasing with self-operated orchestration layers.
- Network Services:Connectivity provisioning including cross-connects and internet exchange access. Facilities near submarine cable landing points capture latency-sensitive financial services demand through reduced North Atlantic transit times.
- Disaster Recovery:Geographically separated backup infrastructure ensuring business continuity. Lefdal Mine's underground facility positions for this segment through natural physical security and minimal mechanical refrigeration requirements.
- Hosting:Standardized server placement with baseline power and cooling guarantees. Channel relationships with systems integrators displace direct facility relationships for mid-market clients seeking simplified procurement.
Managed Services holds the largest share; momentum sits with Network Services.
End User:
Customer type dictates compliance architecture complexity, with government and healthcare verticals imposing sovereign cloud requirements that public sector clients avoid.
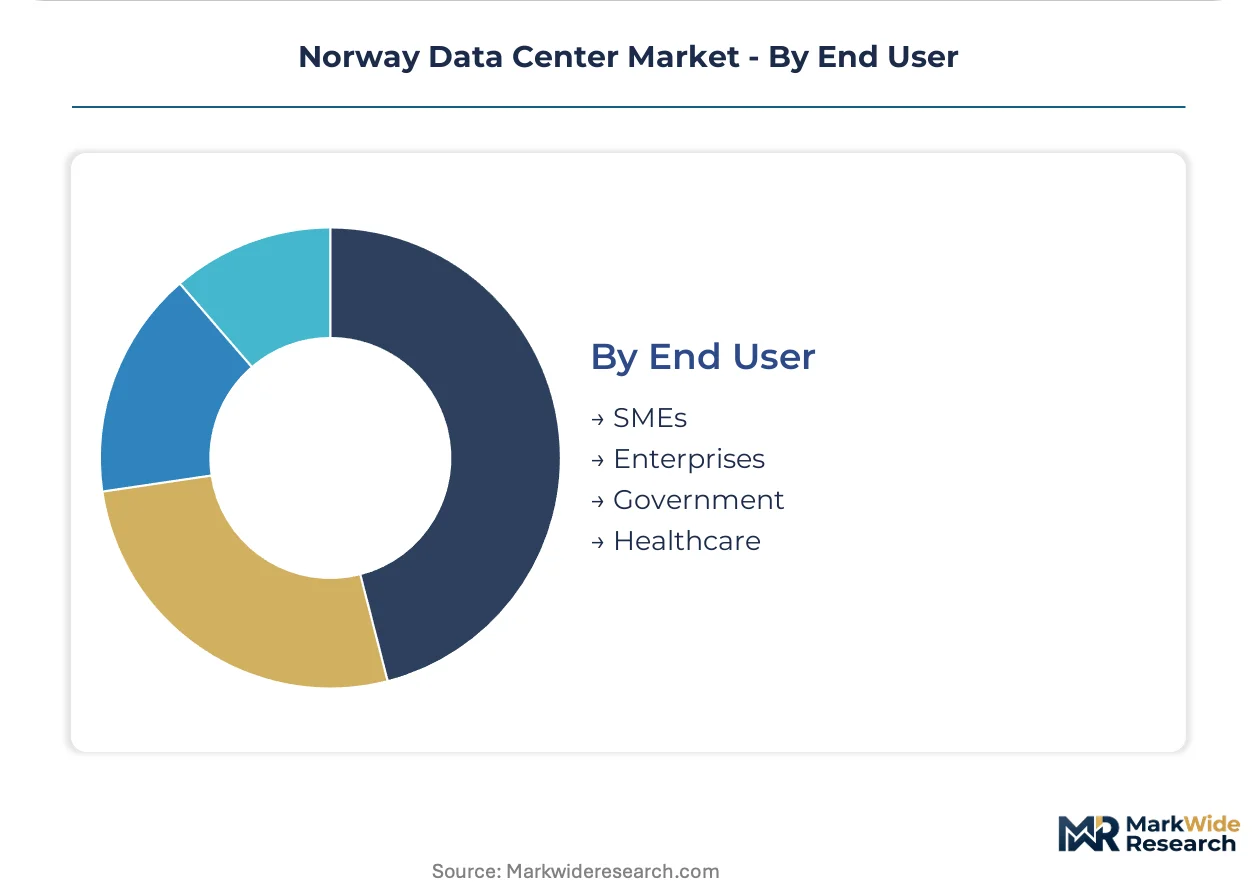
- Enterprises:Large organizations with dedicated IT infrastructure teams. This segment concentrates in Oslo's financial services cluster where compliance teams demand direct control over encryption key management.
- Government:Public sector agencies subject to Datatilsynet sovereignty enforcement. GDPR-aligned restrictions on cross-border data flows require architectural segmentation that increases operational complexity.
- Healthcare:Medical institutions processing special category personal data. These end users mandate sovereign cloud zones with certified Norwegian operational control under GDPR Article 44 transfer mechanism audits.
- SMEs:Small and medium enterprises with limited internal technical capacity. This segment responds to systems integrator channel relationships for simplified colocation procurement without direct facility negotiation.
Enterprises holds the largest share; Healthcare shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Norwegian Water Resources and Energy Directorate governs hydroelectric allocation across all facility development, creating regulatory uniformity that operators navigate through direct fjord-cooling integration and power purchase agreement restructuring.
Oslo-Stavanger Corridor
Submarine cable landing clusters concentrate connectivity infrastructure along this western axis. Datatilsynet sovereignty requirements shape facility design for financial services tenants. Green Mountain operates multiple fjord-cooled sites here, capturing latency-sensitive North Atlantic data flows.
Tromsø and Northern Norway
Subsea cable connections to Asia-Pacific markets remain underutilized in this Arctic zone. Low-latency edge facilities serve maritime autonomous systems and polar research institutions. The Norwegian Water Resources and Energy Directorate permits new hydroelectric connections more readily here than in southern load centers.
Bergen Fjord Region
Deep-water cooling access attracts high-density computing deployments. Lefdal Mine Data Centers anchors underground facility development with minimal mechanical refrigeration requirements. Bulk Infrastructure extends submarine cable ownership across the North Atlantic from this base.
Oslo Metropolitan Area
Enterprise demand concentrates here for sovereign cloud zones with certified Norwegian operational control. High-voltage electrical technicians with data center certification cluster in this labor market. STACK Infrastructure and AQ Compute position facilities to serve Datatilsynet-audited public sector clients.
Trøndelag Central Region
Industrial automation clients drive edge computing investment from telecommunications operators. Telia builds low-latency nodes here for manufacturing sector connectivity. The region offers intermediate hydroelectric allocation terms between southern scarcity and northern availability.
Norway Data Center Market Competitive Landscape
Indigenous facility operators and international hyperscale platforms split the market into distinct capability tiers. The vendor base organizes around cooling-integrated designs versus connectivity-anchored expansion. Three archetypes dominate: fjord-cooled sustainability specialists, submarine cable owners, and underground high-density operators. Competitive moves center on power purchase agreement restructuring with the Norwegian Water Resources and Energy Directorate and liquid cooling technology convergence.
Within the indigenous operator tier, Green Mountain exemplifies fjord-cooled facility development, Bulk Infrastructure anchors North Atlantic connectivity ownership, and Lefdal Mine Data Centers occupies the underground high-density position. These three represent distinct strategic responses to Norwegian regulatory and geographic constraints. International hyperscale providers including Google and Microsoft compress contract timelines while demanding renewable power guarantees exceeding standard utility offerings. STACK Infrastructure and AQ Compute sit within the emerging sovereign cloud specialist category, targeting Datatilsynet compliance requirements.
| Leading Market Players |
|---|
| Green Mountain |
| Bulk Infrastructure |
| STACK Infrastructure |
| Lefdal Mine Data Centers |
| AQ Compute |
| Orange Business |
| Telia |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in southern Norway's hydroelectric allocation zones drives facility operators toward long-term power purchase agreement restructuring with the Norwegian Water Resources and Energy Directorate, compressing margins while elevating renewable certification premiums for buyers with grandfathered connections.
Pricing Analysis
Oslo-Stavanger corridor facilities command pricing premiums against northern Norway equivalents due to submarine cable proximity and Datatilsynet-audited sovereign zone availability. Contract-based long-term offtake dominates, with price differentiation hinging on renewable certification tier and fjord-cooling integration depth. Cost compression in standard colocation tiers is intensifying because hyperscale cloud providers demand renewable guarantees exceeding standard utility offerings. SMEs exhibit highest price sensitivity through systems integrator channel relationships, while financial services enterprises absorb premiums for direct encryption key control.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for Norwegian facility operators sourcing GPU clusters and electrical infrastructure. Equipment procurement draws from Germany, China, and the United States for switchgear, cooling systems, and server hardware. Single-source vulnerability concentrates in specialized liquid cooling components and high-voltage transformers. Distribution runs through direct manufacturer relationships and systems integrator channels, with EPC contractors managing facility construction timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against cloud provider captive facility development, as Google and Microsoft expand direct renewable power contracting that bypasses indigenous colocation operators.
For Market Incumbents: Pre-empt hyperscale vertical integration by securing exclusive fjord-cooling sites with direct Norwegian Water Resources and Energy Directorate allocation agreements. Anchor sovereign cloud certifications with Datatilsynet to defend against public cloud substitution in government and healthcare verticals. Prioritize liquid cooling convergence with existing hydroelectric infrastructure to maintain density advantages for AI training workloads.
For New Entrants and Emerging Players: Pursue Tromsø-area edge facility development where subsea cable capacity to Asia-Pacific markets remains underutilized and hydroelectric permitting faces lighter southern competition. Target maritime autonomous systems and polar research institutions as anchor tenants. Lead with bare-metal leasing models that appeal to compliance teams demanding direct orchestration control.
For Investors and Strategic Acquirers: Capital is best deployed toward underground high-density operators with existing mine retrofit infrastructure and minimal mechanical refrigeration requirements. Long-term viability rests on facilities achieving power usage effectiveness ratios below industry averages through direct-to-chip cooling integration. Watch hyperscale contract timeline compression as the inflection signal indicating renewable guarantee negotiation leverage shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Restructuring | Direct Norwegian Water Resources and Energy Directorate contracting secures grandfathered hydroelectric allocation ahead of scarcity tightening. |
| Liquid Cooling Technology Convergence | Integration with fjord water systems enables sub-industry-average power usage effectiveness ratios attracting density-sensitive AI contracts. |
| Sovereign Cloud Certification Investment | Datatilsynet-audited operational control satisfies GDPR Article 44 requirements for public sector and healthcare verticals. |
| Submarine Cable Proximity Expansion | Oslo-Stavanger corridor positioning captures latency-sensitive North Atlantic financial services demand. |
| Backward Integration into Renewable Generation | Direct hydroelectric asset ownership insulates against Norwegian Water Resources and Energy Directorate allocation constraints. |
Research Methodology
A standing panel of data center facility operators, Norwegian Water Resources and Energy Directorate planning officers, hyperscale cloud procurement leads, and Datatilsynet compliance auditors provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against SEC filings from listed infrastructure REITs, Norwegian regulatory gazettes, submarine cable development databases, and hyperscaler capital expenditure disclosures. Bottom-up facility capacity tallies and top-down national electricity allocation forecasts were triangulated to establish market sizing boundaries.
Scenario-bracketing anchored the analytical framework across the projection horizon, with deployment model, technology application intensity, service type margin structure, and end-user governance requirements serving as core segmentation dimensions. CAGRs were derived from capacity absorption trajectories matched against hydroelectric allocation permit timelines. Industry-specific forecast inputs included GPU cluster deployment schedules from international enterprises and Datatilsynet enforcement pattern shifts affecting cross-border data flow restrictions.
Macroeconomic conditions sit as an overlay; deviation in European energy pricing, EU AI Act implementation timing, or hyperscale capital allocation priorities would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Rugged Servers Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Managed IT Infrastructure Services Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Hyperscale Data Center Market