
 Vietnam Data Center Physical Security Market | 2026-2036
Vietnam Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Data Center Physical Security Market Insights
Buyer concentration among cloud service providers and telecom operators is consolidating as hyperscale operators expand in Vietnam, reducing vendor fragmentation at the top tier. Schneider Electric leverages its integrated power and security portfolio to anchor large-scale deployments. Bosch Sicherheitssysteme GmbH competes through specialized video analytics and access control systems. Honeywell International Inc. sustains position via building automation convergence with physical security platforms.
Vietnam data center physical security encompasses perimeter hardening, biometric access control, surveillance systems, and intrusion detection engineered to protect critical IT infrastructure against unauthorized entry, environmental threats, and sabotage. Systems typically integrate IP-based video management with multi-factor authentication and environmental monitoring to ensure continuous facility uptime. Access control and surveillance cameras represent the largest installed base, while video analytics and biometrics command premium pricing due to AI-enabled threat detection capabilities. Installation and maintenance services capture recurring revenue streams as facility operators prioritize uptime guarantees over initial capital expenditure.
Vietnam's Ministry of Information and Communications enforces data localization and cybersecurity compliance that directly mandates physical protection tiers for certified data centers. BIS-aligned construction standards and fire safety codes from the country's building regulator further shape equipment specifications and certification requirements. Stakeholders must monitor evolving enforcement patterns around critical information infrastructure designation as these classifications will determine mandatory security investment levels and vendor qualification criteria.
Market Dynamics
Hyperscale cloud construction across northern Vietnam is compressing procurement cycles and forcing security vendors to pre-certify equipment against Vietnam's Cybersecurity Law tiers before facility commissioning begins.
Growth Catalysts
- Critical Infrastructure Designation:Vietnam's Cybersecurity Law mandates tiered physical protection standards for certified data centers, creating mandatory upgrade cycles for existing facilities.
- Biometric Authentication:Facial recognition and palm-vein systems are displacing card-based access at hyperscale campuses due to zero-trust security mandates from international cloud tenants.
- Hanoi-Ho Chi Minh City Corridor:Concentrated hyperscale construction across these two metropolitan zones generates clustered demand for integrated perimeter-intrusion-detection systems.
Market Restraints
- Import Equipment Dependency:High-grade surveillance chipsets and biometric sensors concentrate in Taiwanese and South Korean supply chains, exposing projects to lead-time volatility.
- Specialized Integration Talent:Vietnam's domestic workforce lacks certified technicians for IP-based video management and multi-factor authentication convergence, inflating deployment timelines.
- BIS Construction Compliance:Fire safety and structural codes from Vietnam's national standards body impose equipment specification constraints that limit vendor flexibility.
Strategic Opportunities
- Central Highlands Expansion:Secondary data center clusters in Da Nang and Can Tho remain underpenetrated for tier-3 physical security deployments.
- AI-Video Convergence:Machine-learning analytics layered on thermal cameras enables predictive threat detection at unmanned perimeter zones.
- Managed Security Services:Subscription-based remote monitoring and maintenance contracts address operator preference for uptime guarantees over capital expenditure.
Industry Challenges
- Multi-Vendor System Integration:Hyperscale operators demand seamless interoperability between access control, surveillance, and building automation platforms from disparate suppliers.
- Cybersecurity Law Certification Timelines:Physical security equipment must complete Ministry of Information and Communications approval processes that lag facility construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Data Center Physical Security Market |
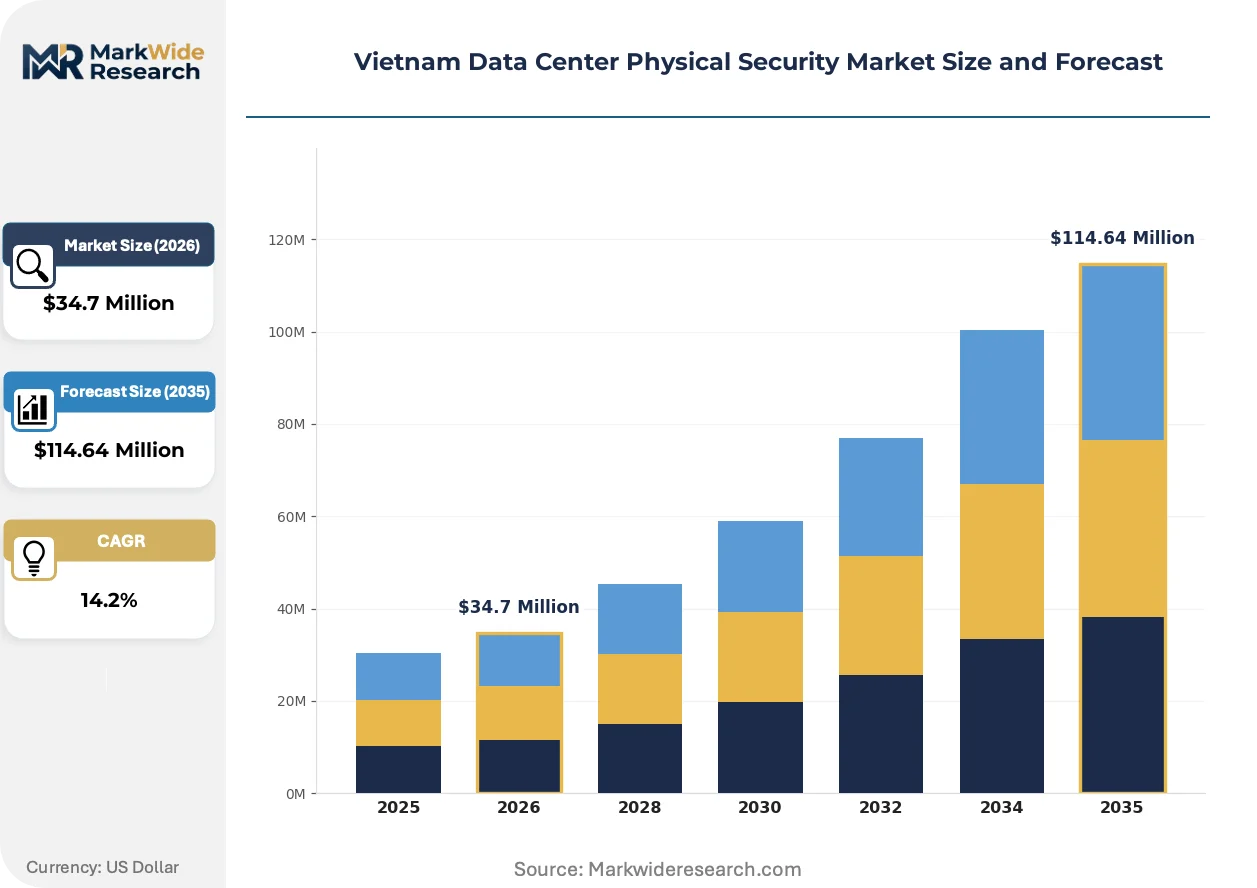
| Market Size in 2026 | $34.7 Million |
| Market Size in 2035 | $114.64 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Access Control, Surveillance Cameras, Intrusion Detection, Fire Detection Service Type: Consulting, Installation, Maintenance, Monitoring End User: Cloud Service Providers, Telecom Companies, Financial Institutions, Government Agencies Security Feature: Biometrics, Keycard Systems, Perimeter Security, Video Analytics |
| Companies Covered | ABB Ltd, Securitas Technology, Bosch Sicherheitssysteme GmbH, Honeywell International Inc., Schneider Electric, Johnson Controls, Siemens AG, Cisco Systems Inc., Dahua Technology Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Data Center Physical Security Market Trends and Innovations
Artificial intelligence is penetrating physical security architectures through edge-based analytics, while regulatory pressure and procurement centralization reshape how operators specify and source protection systems.
Edge-deployed video analytics processors are integrating machine-learning inference directly into surveillance cameras, enabling real-time anomaly detection without backhaul latency. Hyperscale operators in Hanoi are specifying these systems for unmanned perimeter zones. This convergence is integrating threat detection with automated response protocols, compressing incident response windows.
Vietnam's Ministry of Information and Communications is tightening enforcement of data localization and cybersecurity compliance that mandates physical protection tiers for certified facilities. Equipment vendors must now pre-validate biometric and surveillance systems against national standards before facility commissioning. Tier-3 and tier-4 data center classifications face the most stringent inspection schedules, forcing earlier security capital allocation in project timelines.
Facility operators are consolidating vendor relationships around single-source accountability for uptime performance. Long-term service agreements with integrated security providers are displacing fragmented procurement of cameras, access control, and maintenance contracts. This concentration is most pronounced among international cloud service providers establishing hyperscale campuses in northern Vietnam.
Vietnam Data Center Physical Security Market Segmentation
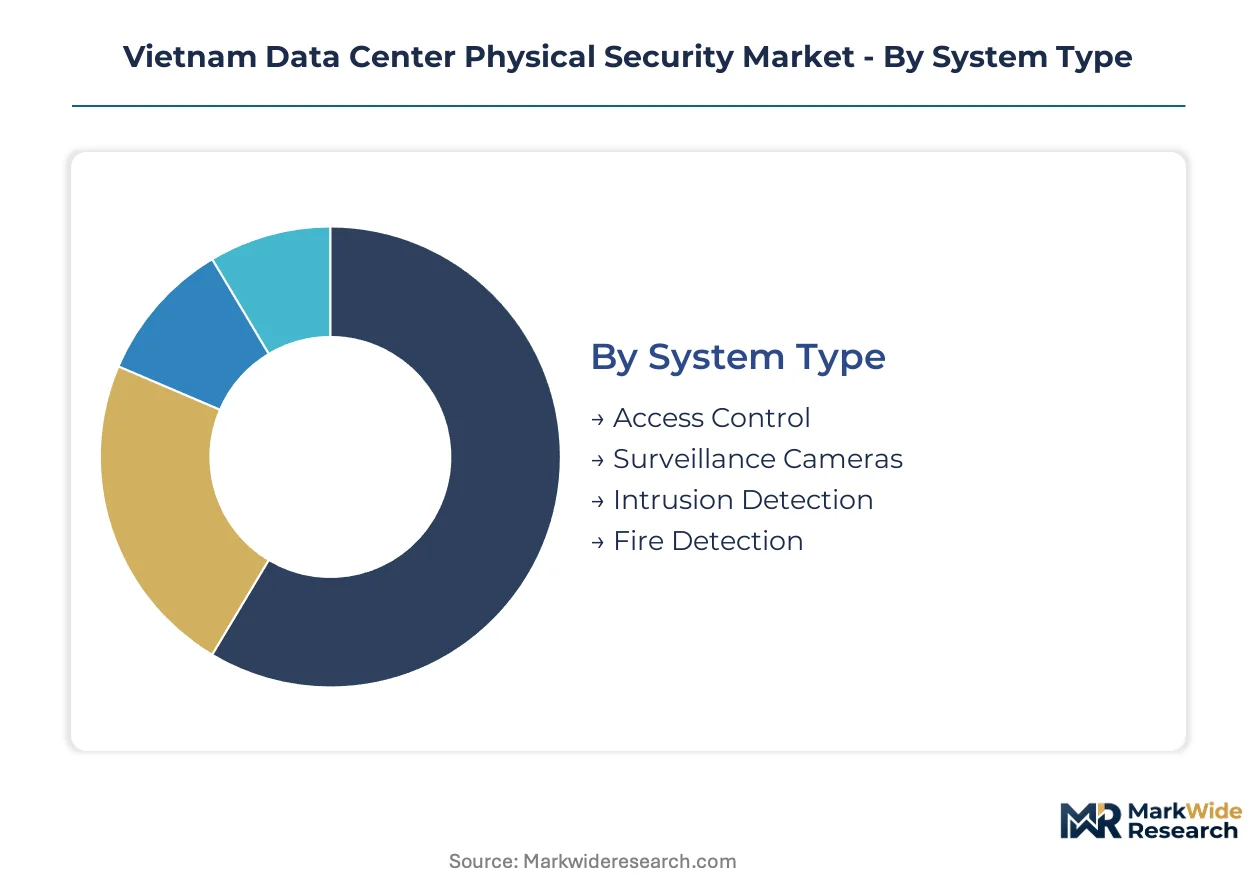
Vietnam's data center physical security market segments along four functional dimensions that reflect capital allocation priorities, operational complexity, and regulatory compliance tiers. Each segmentation axis reveals distinct procurement patterns across hyperscale campuses and enterprise facilities.
System Type:
Capital intensity varies sharply across system categories, with integrated platforms demanding substantially higher upfront investment than standalone components.
- Access Control:Multi-factor authentication platforms incorporating biometric readers, card readers, and visitor management software form the core of facility entry security. Hyperscale operators in Hanoi specify these systems first in construction timelines due to Vietnam's Cybersecurity Law tiered certification requirements. Procurement concentrates on palm-vein and facial recognition configurations that satisfy zero-trust mandates from international cloud tenants.
- Surveillance Cameras:IP-based camera networks with edge analytics capabilities represent the largest installed equipment base across Vietnamese data centers. Thermal imaging and low-light sensors dominate perimeter deployments at unmanned zones in northern Vietnam facilities. Demand clusters around AI-enabled models that support real-time threat detection without latency-heavy backhaul to central servers.
- Intrusion Detection:Perimeter sensors and motion detection arrays protect facility boundaries against unauthorized physical entry. These systems integrate with access control platforms to trigger automated lockdown protocols.
- Fire Detection:Very early smoke detection apparatus and aspirating systems safeguard critical IT infrastructure against thermal events. Equipment specifications align with BIS construction standards and national fire safety codes.
Most installed capacity flows through Surveillance Cameras. Expansion is steepest in Access Control as hyperscale operators upgrade from card-based to biometric systems.
Service Type:
Revenue recurrence distinguishes service categories, with multi-year contracts commanding premium positioning against one-time project delivery.
- Installation:System integration and commissioning services require certified technicians for IP-based video management and multi-factor authentication convergence. Deployment timelines extend due to workforce scarcity in Vietnam's domestic labor pool.
- Maintenance:Preventive service contracts and uptime guarantee agreements generate recurring revenue streams as facility operators prioritize operational continuity over capital expenditure. International cloud providers in Ho Chi Minh City favor long-term service agreements with single-source accountability.
- Monitoring:Remote surveillance and managed security services enable 24/7 threat oversight without on-site staffing. Subscription-based models address operator preference for operational expenditure structures.
- Consulting:Risk assessment and compliance advisory services support Cybersecurity Law certification processes. Pre-validation against Ministry of Information and Communications standards reduces commissioning delays.
Maintenance contracts capture the largest recurring revenue share. Monitoring services are climbing the fastest as hyperscale operators outsource round-the-clock oversight.
End User:
Procurement centralization varies by end user category, with hyperscale operators consolidating vendor relationships while fragmented buyers sustain multi-source strategies.
- Cloud Service Providers:Hyperscale operators constructing campuses across northern Vietnam drive demand for integrated perimeter-intrusion-detection systems. These buyers specify pre-certified equipment against national standards and demand seamless interoperability between security platforms.
- Telecom Companies:Domestic carriers upgrading legacy facilities face mandatory upgrade cycles under Vietnam's Cybersecurity Law tiered protection standards. Procurement concentrates on retrofitting existing infrastructure with biometric access and video analytics.
- Financial Institutions:Banks and payment processors require tier-3 and tier-4 physical protection classifications for certified data centers. Compliance-driven investment schedules force earlier security capital allocation in project timelines.
- Government Agencies:State-owned data infrastructure projects follow procurement protocols tied to critical information infrastructure designation. Vendor qualification criteria include domestic partnership requirements and technology transfer provisions.
Cloud Service Providers command the largest project scale. Financial Institutions are expanding most quickly as regulatory enforcement tightens around data localization mandates.
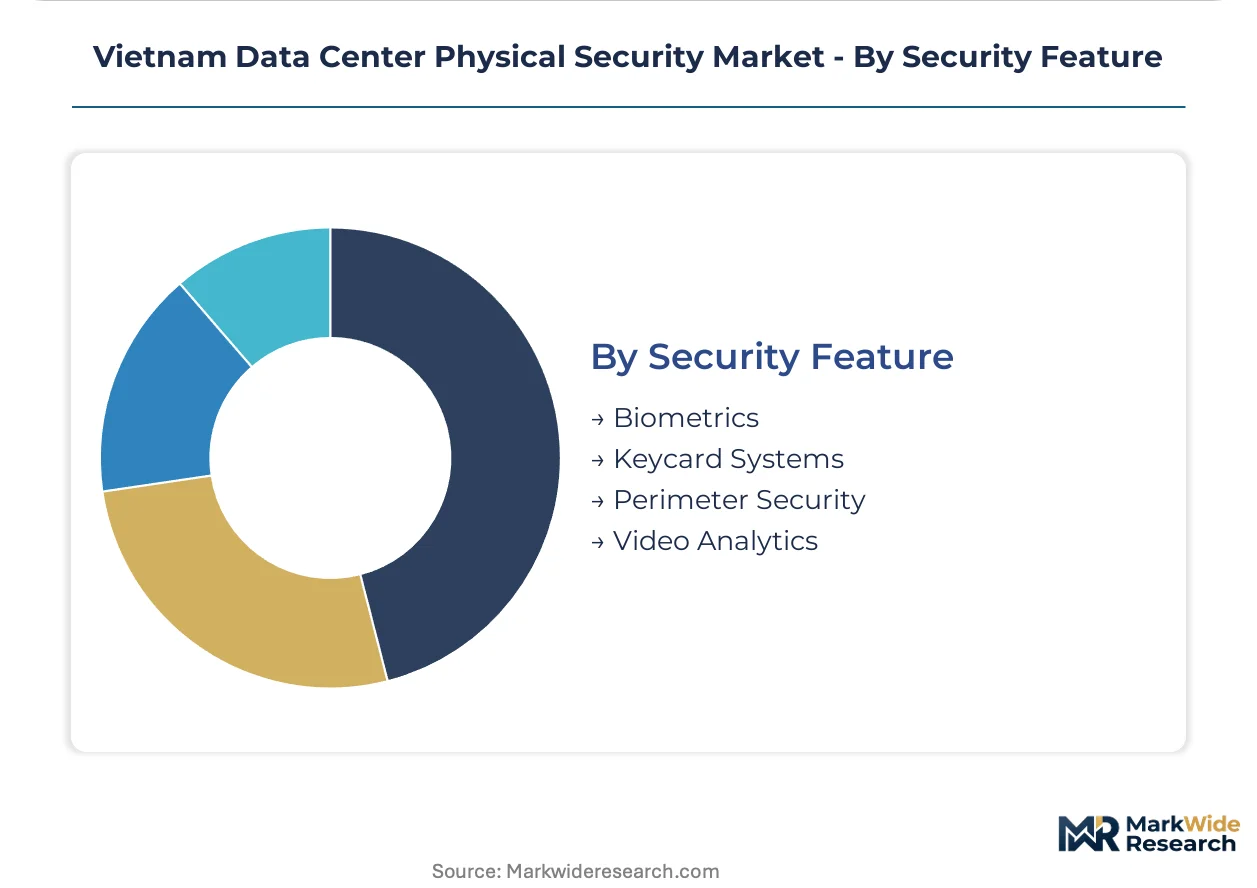
Security Feature:
Technology maturity and pricing premiums segment security features, with AI-enabled capabilities commanding substantial cost premiums over legacy alternatives.
- Biometrics:Facial recognition and palm-vein authentication systems displace card-based access at hyperscale campuses. These solutions carry premium pricing due to AI-enabled identity verification and liveness detection capabilities.
- Video Analytics:Machine-learning inference layered on surveillance feeds enables predictive threat detection at unmanned perimeter zones. Edge-deployed processors reduce backhaul latency for real-time anomaly detection in Hanoi facilities.
- Perimeter Security:Physical barriers, fencing, and vehicle control systems form the outermost layer of facility protection. These elements integrate with intrusion detection sensors for automated response protocols.
- Keycard Systems:Legacy card-based access persists in older facilities and secondary data center clusters in Da Nang and Can Tho. Replacement cycles accelerate as zero-trust security mandates propagate from international tenants.
Perimeter Security represents the most widely deployed foundation layer. Video Analytics is gaining share fastest as edge AI capabilities mature and price points compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's data center physical security expansion diverges sharply from Singapore's mature compliance environment, where tier-4 certification cycles already dominate procurement. Northern Vietnam's hyperscale construction wave compresses vendor timelines and forces earlier security capital allocation than regional peers.
United States
Hyperscale cloud operators anchor demand for integrated perimeter-intrusion-detection systems across Virginia's Data Center Alley and Oregon's Hillsboro cluster. The country's national cybersecurity agency mandates continuous monitoring standards for federal data facilities. Northern Virginia's Ashburn-Loudoun corridor concentrates the densest security deployment activity as operators retrofit existing campuses with biometric access and AI-enabled video analytics.
Germany
Frankfurt's banking and cloud infrastructure drives stringent physical protection requirements for tier-3 and tier-4 certified facilities. The country's federal data protection authority enforces critical infrastructure security baselines through the BSI IT-Grundschutz framework. The Rhine-Main metropolitan region hosts Europe's densest concentration of data center security integration specialists serving financial and automotive cloud tenants.
Singapore
Tropical climate resilience and land scarcity compress facility designs, elevating demand for compact, high-density security systems. The country's cybersecurity agency operates a multi-tier certification scheme that mandates physical protection audits for licensed data centers. The Jurong and Changi industrial zones concentrate hyperscale construction where operators specify pre-integrated access control and thermal imaging perimeter arrays.
Japan
Tokyo and Osaka metro areas sustain demand for earthquake-resistant security infrastructure with redundant failover protocols. The country's Ministry of Economy, Trade and Industry promotes data center resilience standards that incorporate physical security into business continuity planning. The Greater Tokyo Area's Chiba and Saitama prefectures host expanding cloud campuses where operators deploy palm-vein biometric systems for zero-trust access compliance.
Australia
Sydney and Melbourne anchor demand for bushfire-resistant perimeter hardening and remote monitoring capabilities across distributed facility networks. The country's national cybersecurity center issues protective security policy guidelines for critical infrastructure operators. The Western Sydney Aerotropolis corridor concentrates new hyperscale construction where security vendors pre-certify equipment against national critical infrastructure standards.
Vietnam Data Center Physical Security Market Competitive Landscape
European industrial conglomerates anchor the premium integrated systems tier; Asian electronics specialists hold dominant positions in surveillance component supply. Market structure concentrates around five to eight full-stack providers capable of delivering unified access control, video management, and building automation convergence. Two strategic archetypes define competitive positioning: diversified industrial technology groups leveraging power infrastructure cross-sell, and pure-play security specialists competing on AI-enabled video analytics. Dominant competitive moves include long-term service contract anchoring and pre-certification racing against national cybersecurity law timelines.
Within the diversified industrial tier, Schneider Electric and Siemens AG exemplify full-stack positioning through integrated power and security portfolio convergence. Bosch Sicherheitssysteme GmbH occupies a specialist position representing pure-play security technology depth. These three companies sit within distinct strategic postures: European-headquartered conglomerates with multi-industry technology platforms, and German GmbH-structured security specialists competing on biometric and video analytics differentiation.
| Leading Market Players |
|---|
| ABB Ltd |
| Securitas Technology |
| Bosch Sicherheitssysteme GmbH |
| Honeywell International Inc. |
| Schneider Electric |
| Johnson Controls |
| Siemens AG |
| Cisco Systems Inc. |
| Dahua Technology Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Vietnam's Cybersecurity Law tiered certification mandates gate qualified supply access and premium-tier pricing power for physical security equipment serving certified data centers. Equipment vendors must pre-validate biometric readers and surveillance systems against Ministry of Information and Communications standards before facility commissioning, compressing procurement timelines and concentrating pricing leverage among pre-certified suppliers.
Pricing Analysis
Capacity additions in northern Vietnam are reshaping price floors for integrated security platforms as hyperscale operators consolidate procurement around single-source accountability. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled video analytics and palm-vein biometric systems from legacy card-based access and basic IP cameras. Cost compression in standard-tier equipment is intensifying because Taiwanese and South Korean component suppliers face lead-time volatility. Cloud service providers exhibit the lowest price sensitivity due to zero-trust mandates from international tenants, while government agencies face the highest sensitivity due to domestic partnership requirements.
Supply Chain Analysis
Certified technician shortages in Vietnam and neighboring manufacturing geographies extend deployment timelines for IP-based video management and multi-factor authentication convergence. High-grade surveillance chipsets and biometric sensors draw from concentrated Taiwanese and South Korean supply chains, with very early smoke detection apparatus and aspirating systems anchored in European specialist manufacturers. Single-source vulnerability in advanced imaging sensors exposes projects to lead-time volatility when geopolitical disruptions hit East Asian semiconductor fabrication. Distribution runs through systems integrators with Ministry of Information and Communications certification credentials, linking equipment vendors directly to hyperscale construction schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam data center physical security functions as a regulatory compounder where tiered Cybersecurity Law enforcement creates mandatory upgrade cycles and pre-certification racing among equipment vendors.
For Market Incumbents: Extend long-term service contract anchoring to capture recurring revenue from uptime guarantee preferences, while deepening backward integration into edge analytics processors to reduce dependency on Taiwanese chipset suppliers. Certification investment in Ministry of Information and Communications pre-validation protocols constitutes the critical defensive lever against emerging pure-play AI video analytics specialists. For New Entrants and Emerging Players: Regional systems integrators lacking national certification credentials represent the most accessible channel partner type for market entry. Secondary data center clusters in Da Nang and Can Tho offer underpenetrated white-space for tier-3 physical security deployments, with subscription-based managed security services providing the strongest go-to-market angle against incumbent project-based models. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic Vietnamese systems integrators holding Ministry of Information and Communications certification but lacking AI-enabled product portfolios. Long-term viability over the next decade hinges on convergence capability across access control, surveillance, and building automation platforms. The signal to watch is enforcement pattern evolution around critical information infrastructure designation, which will determine mandatory security investment levels and vendor qualification criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Law Pre-Certification | Ministry of Information and Communications validation compresses vendor selection timelines and anchors premium pricing. |
| AI-Video Convergence Development | Edge-deployed machine-learning inference enables real-time anomaly detection without latency-heavy backhaul infrastructure. |
| Managed Security Services Launch | Subscription-based remote monitoring addresses operator preference for operational expenditure over capital allocation. |
| Central Highlands Geographic Expansion | Da Nang and Can Tho secondary clusters remain underpenetrated for tier-3 physical security deployments. |
| Biometric Access Control Integration | Facial recognition and palm-vein systems displace card-based access at hyperscale campuses under zero-trust mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facility operators, security systems integrators, Ministry of Information and Communications regulatory officials, and equipment procurement leads at cloud service providers with secondary validation against customs records, BIS construction standard filings, hyperscaler capex disclosures, and national cybersecurity law implementation circulars. Bottom-up equipment shipment tracking and top-down facility construction pipeline analysis triangulated market sizing across the projection horizon.
Historical reference periods anchored the forecast window through facility commissioning timelines and regulatory implementation schedules. Segmentation modeling captured system type, service delivery model, end-user category, and security feature complexity across the analysis window. CAGRs derived from facility construction pipeline trajectories, tiered certification penetration curves, and replacement cycle acceleration patterns. Edge AI adoption rates and biometric displacement timelines informed technology transition assumptions.
Revisions become necessary when Ministry of Information and Communications enforcement patterns around critical information infrastructure designation shift, or when East Asian semiconductor supply disruptions extend beyond current lead-time volatility. Forecasts reflect assumptions about regulatory implementation consistency and hyperscale construction schedule adherence. Practitioners should monitor Cybersecurity Law tier reclassification announcements and Taiwanese foundry utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
Data Center Infrastructure Management Market