
 Norway Data Center Networking Market | 2026-2036
Norway Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Data Center Networking Market Insights
A capability gap between capex-heavy integrated platform vendors and lean software-defined specialists is unwinding competitive dynamics in Norway's data center networking space. Cisco Systems Inc. leverages its end-to-end switching portfolio to anchor enterprise and government installations requiring validated interoperability. Arista Networks competes through cloud-optimized spine architectures that dominate hyperscale deployments. Juniper Networks positions its AI-native operations platform to differentiate in automated fabric management for multi-tenant facilities.
Data center networking encompasses the physical and logical infrastructure—switches, routers, optical cables, and security appliances—that interconnect compute, storage, and application resources within and between facilities, typically operating at speeds from 10 Gbps to 800 Gbps with latency budgets under 10 microseconds for east-west traffic. Its primary purpose is to enable reliable, high-throughput data movement that underpins cloud services, enterprise IT, and digital transaction processing. Ethernet switches lead product type demand as hyperscalers refresh leaf-spine architectures, while InfiniBand technology captures the fastest growth trajectory driven by AI cluster interconnect requirements. Cloud providers represent the most concentrated end-user segment, though financial services institutions in Oslo maintain distinct low-latency networking specifications for trading infrastructure.
Norwegian data center development intersects with EU Green Deal carbon neutrality benchmarks, national building energy codes administered by the Norwegian Directorate of Building Quality, and ISO 27001 security certification requirements that shape procurement eligibility for public sector contracts. The country's central bank, Norges Bank, supervises financial institution operational resilience standards that mandate redundant networking paths for critical payment systems. Stakeholders must monitor how forthcoming EU AI Act infrastructure transparency obligations will reshape compliance costs for networking equipment deployed in automated decision-making environments.
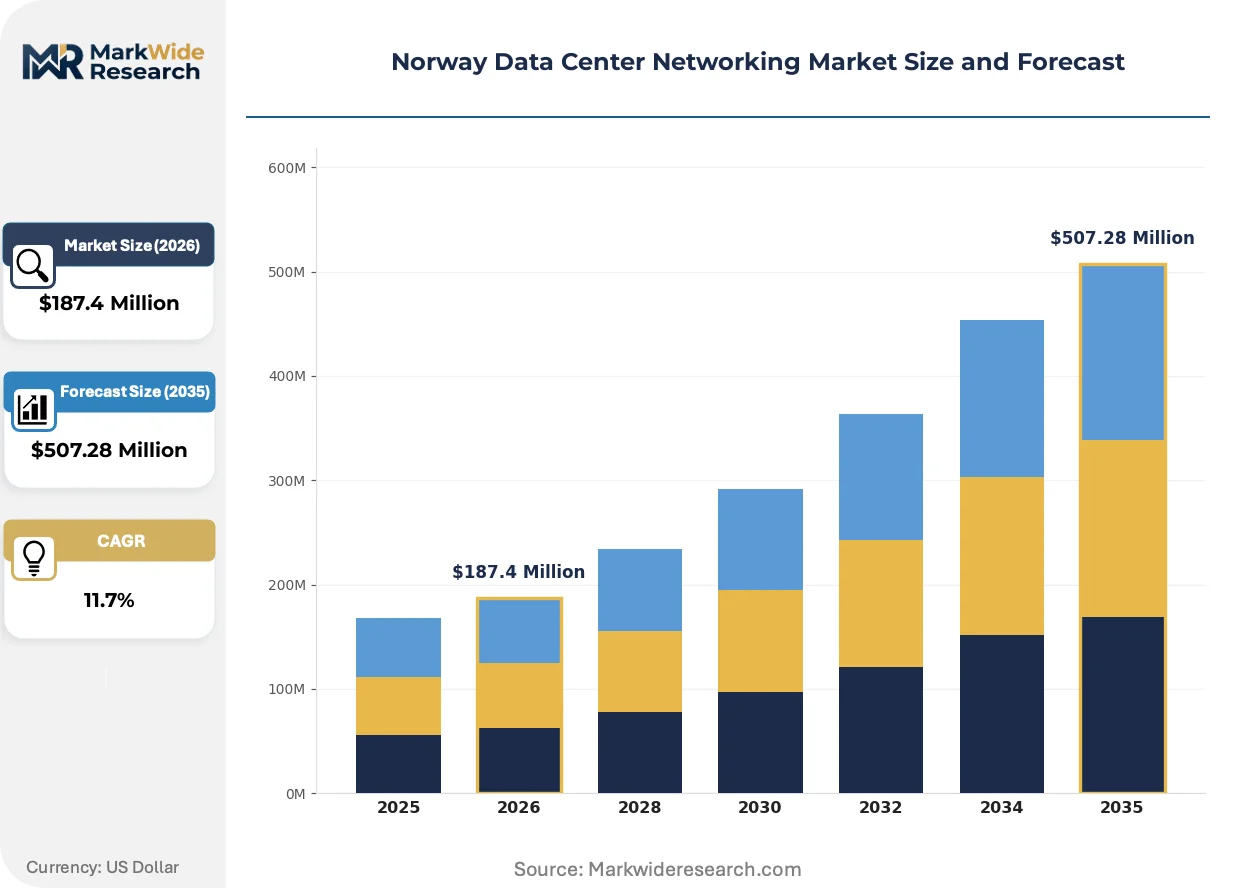
Market Dynamics
AI training cluster deployments are compressing refresh cycles for spine-leaf architectures while EU Green Deal carbon neutrality benchmarks reshape capital allocation toward hydroelectric-powered facilities in the Oslo-Stavanger corridor.
Growth Catalysts
- EU Green Deal alignment:Carbon-neutral operation mandates from Brussels steer hyperscale facility investments toward Norway's surplus renewable hydroelectric capacity, creating locational pull for networking infrastructure procurement.
- Submarine cable convergence:Low-latency fiber landings in the Oslo metropolitan corridor aggregate continental European traffic, concentrating demand for high-throughput switching equipment at these interconnection points.
- InfiniBand technology:AI cluster interconnect requirements are displacing traditional Ethernet in training workloads, opening specialized hardware procurement channels for vendors with low-latency fabric expertise.
Market Restraints
- Optical component concentration:Dependency on Asian suppliers for 800 Gbps transceivers creates supply vulnerability for domestic facility expansion timelines.
- Building energy code compliance:Norwegian Directorate of Building Quality thermal efficiency standards impose retrofit costs on legacy facilities seeking networking upgrades.
- Copper interconnect substitution:Passive optical cables are displacing copper DACs in rack-scale deployments, stranding invested capital in traditional cabling infrastructure.
Strategic Opportunities
- Stavanger secondary cluster:Underdeveloped fiber backbone capacity relative to Oslo creates first-mover positioning for vendors establishing distribution partnerships in western Norway.
- EU AI Act transparency:Forthcoming infrastructure disclosure obligations for automated decision-making systems will mandate networking equipment documentation services.
- Security-appliance convergence:Integration of zero-trust segmentation with switching silicon reduces rack-unit consumption for multi-tenant facilities.
Industry Challenges
- Optical engineering scarcity:Domestic labor pools lack sufficient 800 Gbps transceiver characterization expertise, extending deployment timelines for hyperscale projects.
- ISO 27001 certification timelines:Public sector procurement eligibility requires security management system validation that delays vendor onboarding by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Data Center Networking Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Cables, Firewalls End User: Telecommunications, Cloud Providers, Financial Services, Government Technology: Ethernet, InfiniBand, Fibre Channel, MPLS Application: Data Storage, Backup Solutions, Disaster Recovery, Virtualization |
| Companies Covered | Cisco Systems Inc., Huawei Technologies Co. Ltd., Dell EMC, HP Development Company, L.P., NEC Corporation, Extreme Networks Inc., NVIDIA (Cumulus Networks Inc.), Arista Networks, Juniper Networks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Data Center Networking Market Trends and Innovations
Networking infrastructure procurement patterns are fragmenting between capex-intensive integrated platforms and lean software-defined alternatives, with regulatory carbon accounting adding new evaluation criteria to vendor selection processes.
Ethernet switching silicon is bifurcating into distinct performance tiers optimized for either general-purpose cloud workloads or AI-specific traffic patterns. Hyperscale operators in Oslo are deploying both tiers simultaneously within unified leaf-spine fabrics. This technology stratification is compressing vendor margin structures as price-performance benchmarks diverge across application types.
EU AI Act infrastructure transparency obligations are mandating documented networking topologies for automated decision-making environments. Norwegian facilities hosting AI inference workloads must maintain auditable connection maps between compute nodes. Financial services institutions supervised by Norges Bank are accelerating compliance investments ahead of formal enforcement timelines.
Cloud providers are consolidating procurement authority at the Nordic regional level rather than maintaining separate Norwegian buying centers. Stavanger facility operators now route networking equipment decisions through Stockholm-based technical evaluation committees. This channel concentration is displacing local distributor relationships that historically managed single-country contracts.
Norway Data Center Networking Market Segmentation
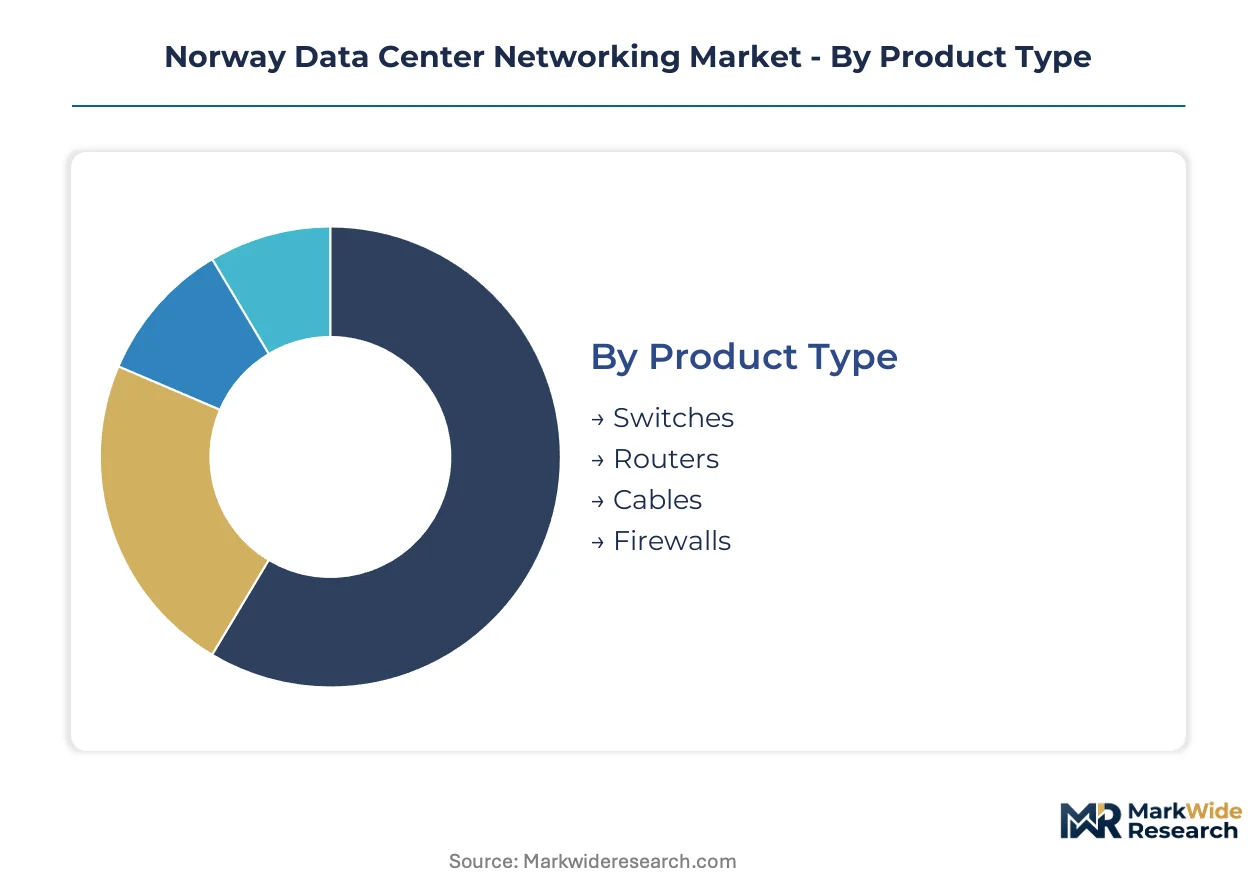
Segmentation in Norway's data center networking market reveals how procurement authority concentrates around specific workload types and compliance requirements. Vendors must align product portfolios with distinct technical specifications across each dimension to capture share in this hydroelectric-powered facility corridor.
Product Type:
Margin pools concentrate in switching equipment where hyperscale refresh cycles and AI cluster deployments create sustained procurement volume.
- Switches:Ethernet switching silicon operates at 10 Gbps to 800 Gbps speeds within leaf-spine architectures. Oslo metropolitan facilities drive demand for spine-layer chassis supporting AI training clusters with sub-10-microsecond latency budgets.
- Routers:Border and core routing platforms manage traffic between submarine cable landing points and continental European backbones. Cloud providers in the Oslo-Stavanger corridor prioritize validated interoperability for multi-vendor environments.
- Cables:Fiber-optic and copper interconnects span rack-scale to inter-facility distances.
- Firewalls:Security appliances enforce zero-trust segmentation at network edges.
Switches hold installed capacity. Firewalls are rotating up the share rankings.
End User:
Customer concentration patterns follow regulatory intensity and latency sensitivity across Norwegian economic infrastructure.
- Cloud Providers:Hyperscale operators anchor procurement volume through regional buying centers in Stockholm that coordinate Norwegian facility investments. These stakeholders mandate carbon-neutral operation documentation aligned with EU Green Deal benchmarks.
- Financial Services:Oslo-based trading infrastructure operators maintain distinct low-latency networking specifications supervised by Norges Bank operational resilience standards. Redundant networking paths for critical payment systems drive premium equipment selection.
- Telecommunications:National carriers manage fiber backbone expansion to submarine cable landings.
- Government:Public sector contracts require ISO 27001 security certification eligibility.
Cloud providers hold installed capacity. Financial services is rotating up the share rankings.
Technology:
Protocol selection bifurcates between general-purpose cloud workloads and specialized AI interconnect requirements.
- Ethernet:Dominant protocol for general-purpose cloud workloads with mature ecosystem support. Hyperscale operators deploy Ethernet switching across unified leaf-spine fabrics while refreshing spine architectures for higher throughput.
- InfiniBand:Low-latency fabric technology captures the steepest expansion trajectory as AI training clusters displace traditional interconnects. Specialized hardware procurement channels reward vendors with fabric expertise in high-performance computing environments.
- Fibre Channel:Storage-area networking protocol for enterprise data center environments.
- MPLS:Traffic engineering technology for service provider core networks.
Ethernet holds installed capacity. InfiniBand is rotating up the share rankings.
Application:
Workload criticality determines redundancy specifications and compliance documentation requirements.
- Data Storage:Networked storage infrastructure connecting compute nodes to centralized repositories. Oslo facilities prioritize throughput optimization for scale-out architectures serving multi-tenant environments.
- Disaster Recovery:Geographically distributed replication systems mandate low-latency inter-facility links. EU AI Act transparency obligations require auditable connection maps for automated failover systems in Norwegian AI inference hosting sites.
- Backup Solutions:Scheduled data protection workflows with bandwidth scheduling requirements.
- Virtualization:Software-defined compute abstraction with east-west traffic patterns.
Data storage holds installed capacity. Disaster recovery is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale buyers in Oslo demonstrate low price elasticity for carbon-verified equipment, while smaller Stavanger facilities exhibit acute sensitivity to transceiver costs. Public sector procurement across Norway maintains rigid compliance premiums regardless of budget constraints.
Oslo Metropolitan Corridor
Submarine cable landings at Lillestrøm and Fornebu aggregate continental European traffic, concentrating demand for 800 Gbps spine-layer switching. The Norwegian Directorate of Building Quality enforces thermal efficiency standards that retrofit legacy facilities. AI training clusters at Østfold data parks are displacing copper interconnects with passive optical cables.
Stavanger
Underdeveloped fiber backbone capacity creates first-mover positioning for vendors establishing western Norway distribution partnerships. EU Green Deal carbon neutrality benchmarks steer hyperscale investments toward surplus hydroelectric capacity in Rogaland. Equinor-anchored energy corridor facilities are expanding east-west latency links to Oslo.
Bergen
Financial services backup sites require redundant networking paths under Norges Bank operational resilience supervision. The Norwegian Data Protection Authority enforces GDPR-aligned infrastructure documentation for multi-tenant environments. Gulating campus developments are consolidating procurement through Stockholm-based technical evaluation committees.
Trondheim
Research computing centers at NTNU drive InfiniBand procurement for high-performance computing workloads. ISO 27001 certification timelines delay vendor onboarding for public sector contracts by six to nine months. Technology transfer partnerships with SINTEF are accelerating 800 Gbps transceiver characterization expertise development.
Tromsø
Arctic climate natural cooling reduces energy overhead for carbon-neutral operation claims. The Norwegian Environment Agency monitors EU AI Act alignment for automated decision-making infrastructure disclosure. Northern Lights industrial park developments are attracting disaster recovery replication systems with low-latency inter-facility link requirements.
Norway Data Center Networking Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated vendor ecosystem. Integrated platform specialists anchor enterprise and government installations requiring validated interoperability, while lean software-defined specialists capture hyperscale cloud deployments. Three archetypes dominate: capex-heavy end-to-end suppliers, cloud-optimized fabric architects, and AI-native automation platforms. Competitive moves concentrate on strategic partnerships for fiber backbone expansion and portfolio diversification into security-appliance convergence.
Within the integrated platform tier, Cisco Systems Inc. and Dell EMC occupy positions anchoring procurement for compliance-intensive public sector contracts. Arista Networks and Juniper Networks exemplify the cloud-optimized and AI-native archetypes respectively, with NVIDIA (Cumulus Networks Inc.) representing specialized fabric expertise for high-performance computing environments. Huawei Technologies Co. Ltd. and NEC Corporation sit within the Asia-Pacific headquartered supplier category serving multi-region hyperscale operators.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Huawei Technologies Co. Ltd. |
| Dell EMC |
| HP Development Company, L.P. |
| NEC Corporation |
| Extreme Networks Inc. |
| NVIDIA (Cumulus Networks Inc.) |
| Arista Networks |
| Juniper Networks |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Asian optical component suppliers lock in transceiver access for Oslo hyperscale operators while anchoring price visibility across multi-year deployment horizons. These arrangements tether Norwegian facility expansion timelines to supplier allocation priorities, compressing negotiating leverage for domestic buyers lacking alternative sourcing pathways.
Pricing Analysis
After-sales service contracts and extended warranty tiers generate lifetime value that exceeds initial equipment margins for spine-layer switching vendors. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with ISO 27001-validated configurations commanding substantial premiums. Cost compression in economy-tier Ethernet switching is intensifying because cloud providers are consolidating procurement through Stockholm-based regional buying centers. Financial services institutions supervised by Norges Bank exhibit the lowest price sensitivity, while Stavanger secondary facilities demonstrate acute responsiveness to transceiver cost fluctuations.
Supply Chain Analysis
Container availability constraints on Asia-North Europe trade lanes elevate inbound logistics costs for 800 Gbps transceiver shipments destined for Oslo metropolitan facilities. Manufacturing concentration in Taiwan, China, and South Korea feeds the optical component dependencies that Norwegian data center operators cannot circumvent. Single-source vulnerability for specialized InfiniBand switch silicon creates deployment timeline risk when supplier allocation tightens. Distribution runs through Nordic regional technical evaluation committees that have displaced single-country distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's data center networking market represents an early-cycle expansion story as AI training cluster deployments compress refresh cycles for spine-leaf architectures before broader European adoption curves mature.
For Market Incumbents: Fortify positions in Oslo metropolitan corridor facilities by deepening backward integration into optical component characterization capabilities, addressing the domestic engineering scarcity that extends hyperscale deployment timelines. Anchor compliance-intensive public sector contracts through accelerated ISO 27001 certification investments, creating switching vendor lock-in before EU AI Act transparency obligations formalize documentation requirements. For New Entrants and Emerging Players: Differentiate on InfiniBand fabric expertise for AI cluster interconnect requirements, where specialized hardware procurement channels reward vendors with high-performance computing credentials. Target Stavanger's underdeveloped fiber backbone capacity through distribution partnerships that establish western Norway presence before Oslo corridor saturation intensifies. Pursue security-appliance convergence positioning that reduces rack-unit consumption for multi-tenant facilities seeking zero-trust segmentation integration. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined networking specialists with lean architectures that capture hyperscale cloud deployments as integrated platform vendors cede share. Long-term viability across the projection horizon hinges on carbon-verified equipment documentation capabilities aligned with EU Green Deal benchmarks. Monitor EU AI Act infrastructure transparency enforcement timelines as the signal indicating when compliance documentation services will command premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Component Characterization | Domestic 800 Gbps transceiver expertise development addresses labor scarcity extending hyperscale timelines in Trondheim research centers. |
| Security-Appliance Convergence | Zero-trust segmentation integration with switching silicon reduces rack-unit consumption for Oslo multi-tenant facilities. |
| Stavanger Distribution Partnership Establishment | First-mover positioning in western Norway captures EU Green Deal-steered hyperscale investments toward Rogaland hydroelectric capacity. |
| ISO 27001 Certification Acceleration | Public sector procurement eligibility under Norwegian Directorate of Building Quality supervision creates six-to-nine-month vendor onboarding advantage. |
| EU AI Act Documentation Service Development | Infrastructure transparency obligations for automated decision-making systems mandate auditable networking topology services in Norwegian AI hosting sites. |
Research Methodology
A standing panel of data center infrastructure executives, cloud procurement officers, optical network engineers, and facilities compliance managers provided ongoing calibration against deployment realities. Primary interview insights combined with secondary validation from hyperscaler capex disclosures, submarine cable landing authority filings, Norwegian Directorate of Building Quality regulatory updates, and EU Green Deal implementation guidance. Bottom-up facility-level demand aggregation and top-down Nordic regional market sizing triangulated volume estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, end-user vertical, protocol technology, and application workload criticality. CAGRs derived from facility expansion pipeline analysis and equipment refresh cycle compression patterns. InfiniBand penetration assumptions and carbon-neutral operation certification timelines served as industry-specific forecast inputs.
Material uncertainties — supply chain disruption in Asian optical component manufacturing, EU AI Act enforcement timeline shifts, Norges Bank operational resilience standard revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions about hyperscale investment continuity and hydroelectric capacity availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Switzerland Data Center Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market