
 Saudi Arabia Data Center Market | 2026-2036
Saudi Arabia Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Data Center Market Insights
Wholesale colocation agreements between cloud providers and local operators is rewriting how capacity reaches enterprise buyers in Saudi Arabia. Amazon Web Services leverages its global infrastructure playbook to anchor hyperscale builds in Riyadh. Microsoft competes through sovereign cloud partnerships that satisfy data residency requirements for government clients. Damac Data Centers specializes in premium facilities targeting financial services tenants seeking Tier III certification.
A data center constitutes a purpose-built facility housing servers, storage systems, and networking equipment with redundant power supplies, precision cooling maintaining 18-27°C, and physical security protocols to ensure 99.999% uptime for digital service delivery. Hyperscale deployments dominate new capacity additions as global cloud providers commit multi-hundred-megawatt campuses to the Kingdom. Edge installations represent the fastest-growing installation category as retailers and telecom operators push latency-sensitive workloads closer to end users. Managed services capture expanding margin pools as enterprises outsource operational complexity rather than building in-house competencies.
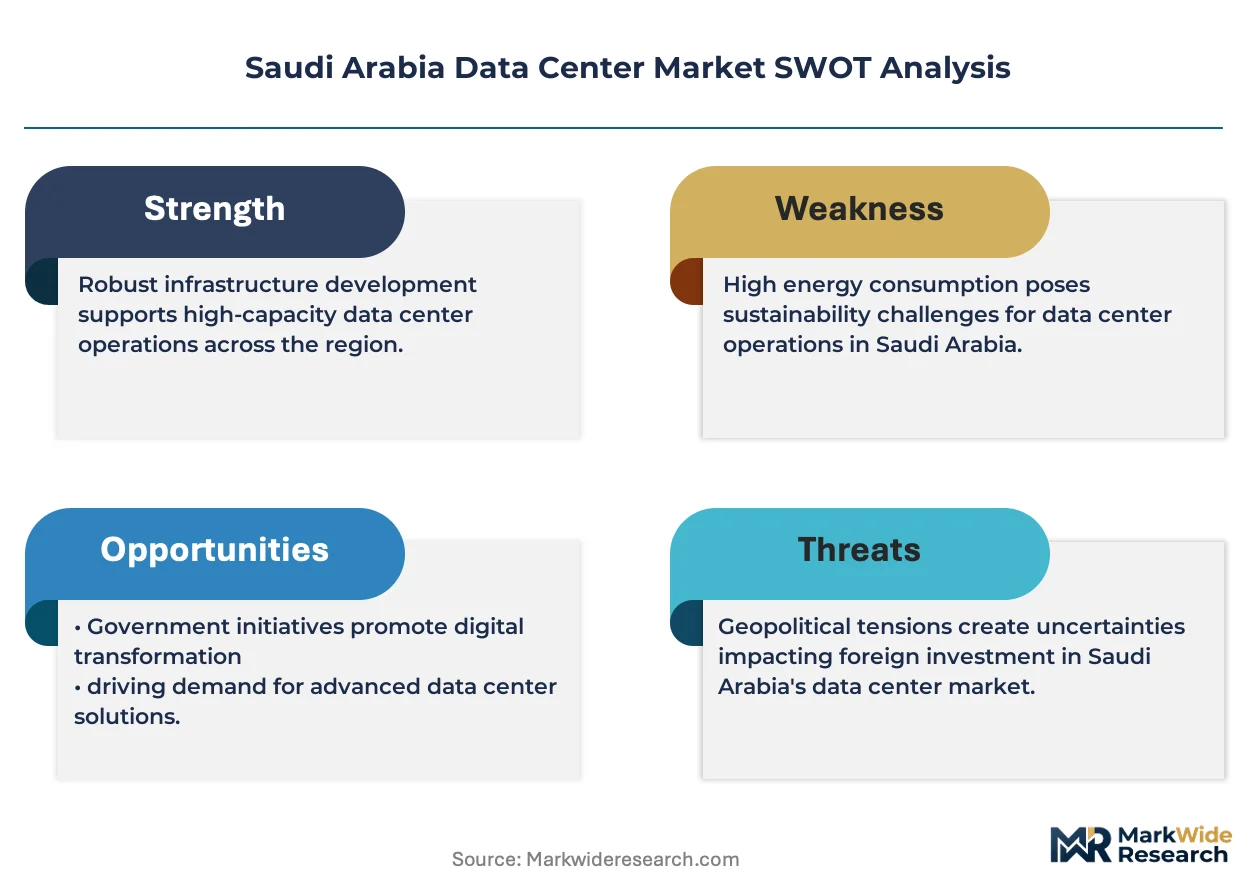
Saudi Arabia's Communications, Space and Technology Commission enforces data localization mandates that prevent certain government and healthcare data from leaving national borders, directly stimulating domestic facility construction. The National Data Management Office issues classification standards that tier storage requirements by data sensitivity, shaping how providers architect security and compliance layers. The Saudi Standards, Metrology and Quality Organization certifies energy efficiency benchmarks that increasingly favor liquid cooling and renewable-powered designs. Stakeholders must track how evolving AI training cluster requirements alter power density specifications before committing to long-term infrastructure contracts.
Market Dynamics
Hyperscale cloud providers are compressing deployment timelines through modular construction and pre-certified power architectures, fundamentally altering how capacity scales across Riyadh and Jeddah corridors.
Growth Catalysts
- Data Localization Mandates:The Communications, Space and Technology Commission enforces strict data residency requirements for government and healthcare data, compelling domestic facility construction rather than regional outsourcing.
- AI Training Clusters:Machine learning workloads demand specialized high-density cooling and power configurations, pulling investment toward liquid-cooled hyperscale campuses in the Kingdom's primary metros.
- Financial Services Certification:Banking regulators require Tier III uptime guarantees for core transaction systems, creating premium demand for fault-tolerant infrastructure with redundant substations.
Market Restraints
- Power Grid Interconnection Delays:Saudi Electricity Company approval timelines for multi-megawatt substations extend 18-24 months, constraining rapid capacity expansion in secondary cities.
- Limited Liquid Cooling Supply Base:Regional scarcity of precision immersion cooling vendors forces operators to import specialized equipment, inflating capex and extending commissioning schedules.
- Water Scarcity Constraints:Traditional evaporative cooling systems face operational restrictions in arid zones, limiting site selection to locations with guaranteed desalinated water access.
Strategic Opportunities
- Eastern Province Edge Deployment:Dammam and Khobar industrial zones lack localized compute capacity, creating first-mover advantage for latency-sensitive manufacturing automation workloads.
- Renewable Power Purchase Agreements:ACWA Power and similar developers offer solar-wind hybrid contracts that align with Saudi Standards, Metrology and Quality Organization efficiency benchmarks and reduce operational carbon intensity.
- Managed Sovereign Cloud Services:Government agencies seek outsourced operations under National Data Management Office classification tiers, opening recurring revenue streams beyond pure colocation.
Industry Challenges
- Certified Engineering Talent Gap:Uptime Institute-accredited design engineers remain concentrated in Riyadh, forcing Jeddah and Dammam projects to compete for limited mobile workforce or accept extended hiring cycles.
- Legacy System Integration Complexity:Enterprises migrating from on-premise server rooms struggle with API compatibility and data pipeline reconfiguration, delaying full workload transition to colocated environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Data Center Market |
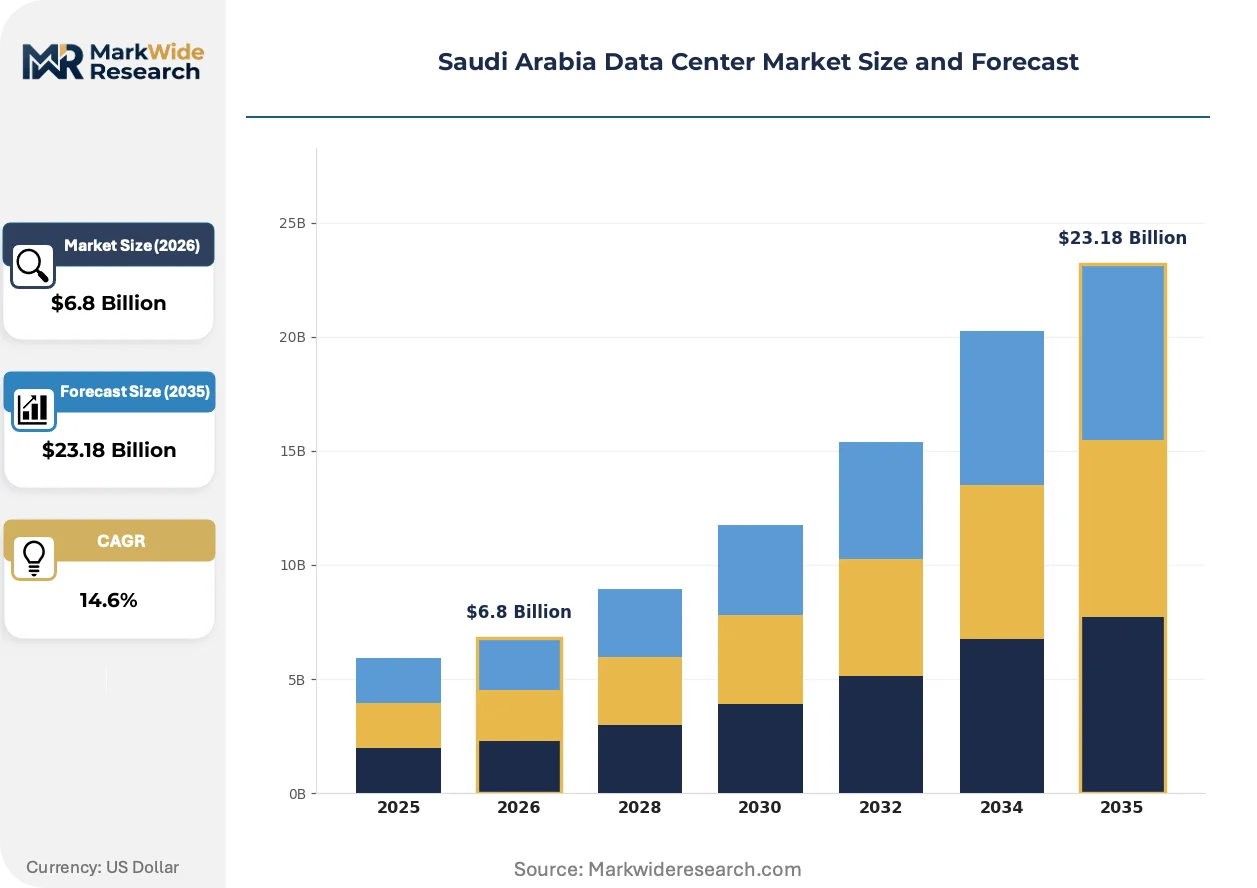
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Hyperscale, Edge, Managed Services End User: Telecommunications, Healthcare, Retail, Government Technology: Cloud, Virtualization, AI, Big Data Installation: On-premises, Off-premises, Hybrid, Modular |
| Companies Covered | Amazon Web Services (AWS), Microsoft, Oracle, Quantum Switch Tamasuk, Damac Data Centers, Center3, Gulf Data Hub, DataVolt, Mobily, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Data Center Market Trends and Innovations
Liquid cooling architectures and sovereign cloud frameworks are converging to redefine facility design standards, while procurement patterns shift toward long-term operational partnerships rather than transactional space leases.
Direct-to-chip liquid cooling is hybridizing traditional air-cooled and full-immersion approaches, allowing operators to support 50+ kW rack densities without wholesale infrastructure replacement. Financial services and AI research tenants are piloting these systems in Riyadh facilities to future-proof against thermal constraints. The technology is hybridizing capex planning by deferring full liquid cooling investment until workload densities justify the upgrade.
The National Data Management Office classification framework mandates tiered security controls based on data sensitivity levels, forcing providers to architect physically segmented zones within single facilities. Operators must now maintain separate access protocols, network isolation, and audit trails for each classification tier. Government and healthcare tenants face the steepest compliance burden, driving demand for pre-certified sovereign cloud environments.
Enterprise buyers are consolidating vendor relationships through multi-year managed service contracts that bundle colocation, connectivity, and operational support under single accountability structures. Systems integrators and telecom operators are capturing these consolidated budgets, displacing traditional pure-play facility operators in competitive tenders. This pattern is most pronounced among mid-market enterprises in Jeddah seeking to outsource operational complexity without building internal data center competencies.
Saudi Arabia Data Center Market Segmentation
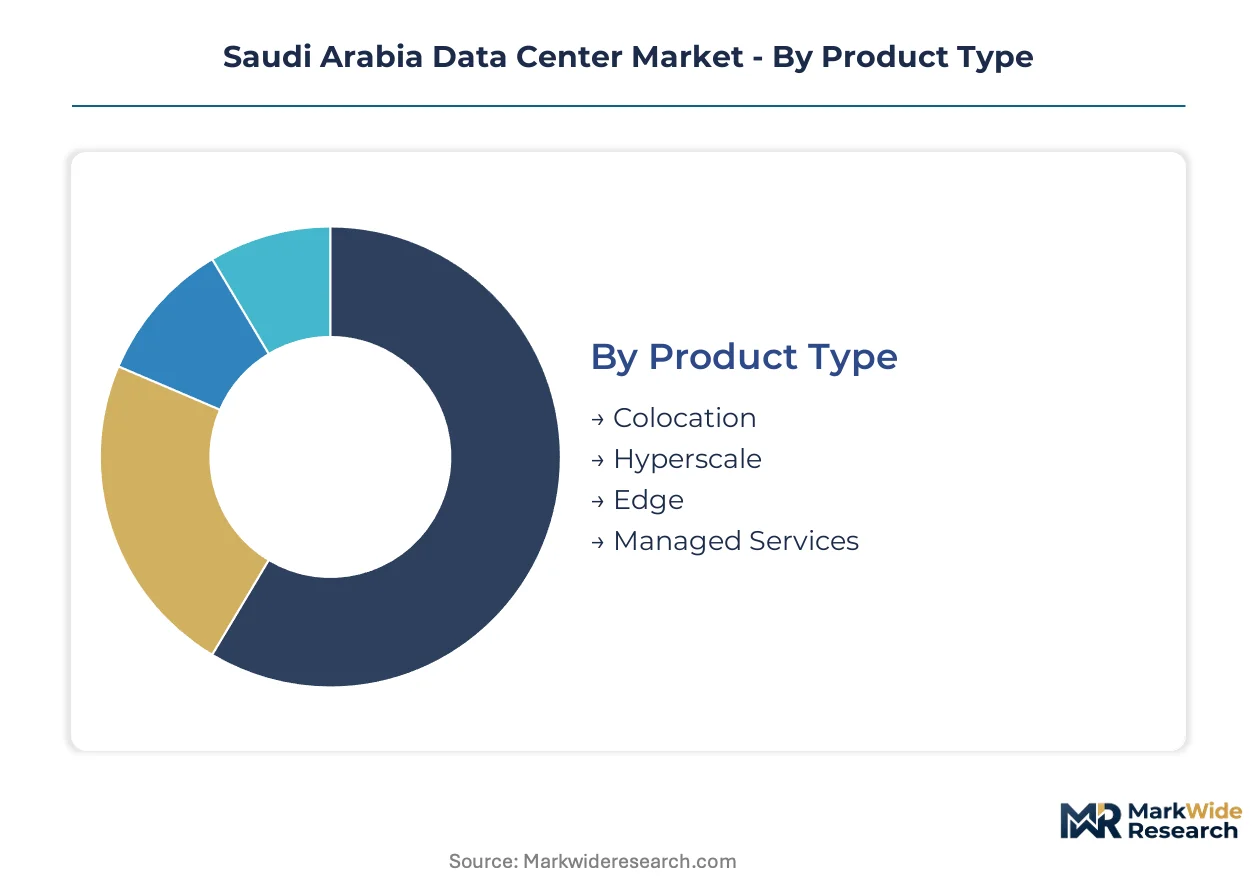
Segmentation in the Saudi Arabia data center market reveals how divergent workload requirements, compliance mandates, and infrastructure maturity shape procurement patterns across Riyadh, Jeddah, and emerging Eastern Province clusters.
Product Type:
Use cases span from sovereign government workloads requiring physical isolation to latency-sensitive retail applications demanding distributed edge nodes.
- Hyperscale:Multi-megawatt campuses with modular power architectures and liquid-ready cooling infrastructure support AI training clusters and cloud-native enterprise migrations. Riyadh concentrates these deployments as AWS and Microsoft anchor facilities under CST data localization mandates, with power densities exceeding 50 kW per rack becoming standard specification.
- Colocation:Wholesale and retail space leasing allows enterprises to outsource physical infrastructure without capital deployment. Jeddah financial services tenants drive Tier III-certified demand as SAMA regulations mandate fault-tolerant transaction systems with redundant substations and 99.982% uptime guarantees.
- Edge:Compact facilities positioned within 10 milliseconds of end users enable real-time manufacturing automation and retail analytics. Dammam industrial zones present first-mover opportunities for latency-sensitive IoT workloads in petrochemical and logistics corridors.
- Managed Services:Operational outsourcing bundles covering remote hands, network management, and security monitoring under single accountability structures. Mid-market enterprises in Jeddah favor these arrangements to bypass internal competency gaps.
The dominant share belongs to Hyperscale, while Edge is closing the gap fastest.
End User:
Regulatory intensity varies sharply across sectors, with government and healthcare facing the strictest NDMO classification tiers.
- Government:National Data Management Office standards mandate tiered security controls, physical segmentation, and audit trails for sensitive administrative data. NDMO classifications force providers to architect isolated zones within shared facilities, with sovereign cloud partnerships preferred for classified workloads.
- Telecommunications:STC, Mobily, and Zain operate captive infrastructure for subscriber data and 5G core networks while leasing excess capacity to enterprise clients. Riyadh and Jeddah host their primary facilities, with expansion into Eastern Province edge nodes for industrial connectivity.
- Healthcare:SFDA and NDMO joint requirements enforce data residency for patient records and clinical trial data. Hospital systems in Riyadh and Jeddah migrate toward colocated environments to satisfy encryption and access control mandates without self-managing facilities.
- Retail:E-commerce platforms and brick-and-mortar chains deploy edge computing for inventory optimization and customer analytics. Jeddah's Red Sea commercial corridor generates concentrated demand for low-latency transaction processing.
Government accounts for the largest committed capacity, though Healthcare is expanding most quickly as hospital digitization accelerates.
Technology:
Workload characteristics determine infrastructure specifications, with AI and Big Data forcing the steepest power density escalations.
- AI:Machine learning training clusters require specialized GPU architectures and direct-to-chip liquid cooling to sustain 50+ kW rack densities. Riyadh hyperscale campuses pilot hybrid cooling systems that defer full immersion investment until workload volumes justify conversion.
- Big Data:Distributed analytics platforms demand high-throughput storage networks and low-latency interconnects between compute nodes. Financial services and telecom operators in Jeddah deploy these for real-time fraud detection and network optimization.
- Cloud:Multi-tenant virtualized environments enable elastic resource allocation for enterprises avoiding capital-intensive infrastructure ownership. CST localization rules ensure domestic cloud regions remain physically bounded within national borders.
- Virtualization:Software-defined infrastructure abstracts compute, storage, and networking resources for dynamic workload orchestration. Legacy enterprise migrations rely on this layer to bridge on-premise and colocated environments.
Cloud holds the established revenue base, yet AI commands the steepest expansion trajectory as sovereign AI initiatives proliferate.
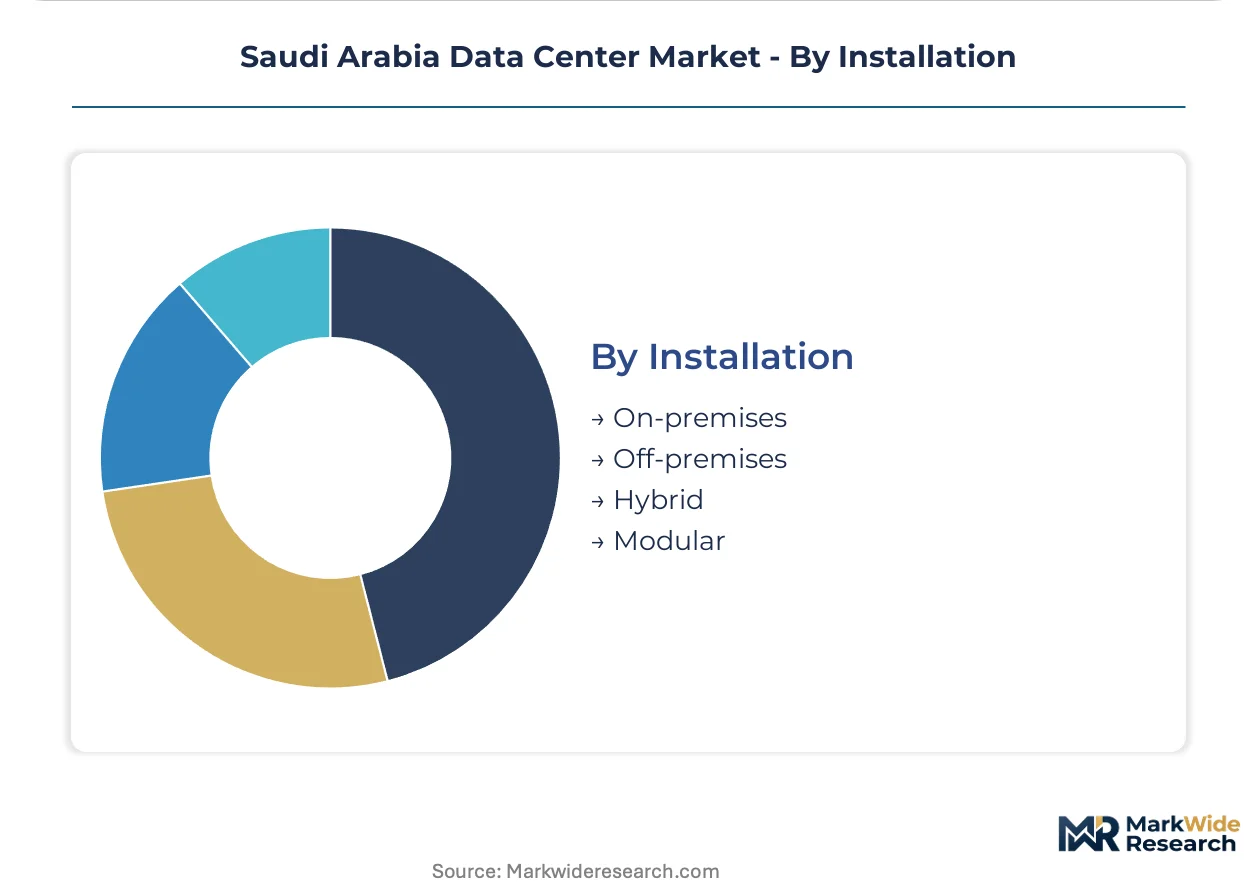
Installation:
Deployment models reflect capital availability, speed-to-market requirements, and legacy system interdependencies.
- Modular:Prefabricated data center modules compress commissioning timelines from 24 months to 12-18 months through factory-integrated power and cooling systems. Hyperscale operators in Riyadh deploy these for rapid capacity scaling under compressed cloud demand cycles.
- Hybrid:Split workloads across on-premise retention and off-premise colocation balance latency, compliance, and cost optimization. Enterprises with legacy mainframe dependencies in Jeddah favor this model for gradual cloud migration.
- On-premises:Captive facilities maintained by large enterprises with specialized security or performance requirements. Government defense and intelligence agencies maintain these for highest-sensitivity NDMO tier workloads.
- Off-premises:Third-party facility leasing eliminates capital expenditure and operational complexity. Mid-market enterprises without internal engineering competencies default to this model across all major metros.
Modular installations lead new capacity additions, though Hybrid configurations are gaining share fastest among enterprises navigating legacy transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CST's data localization mandates and NDMO classification tiers are redistributing capacity investments across Saudi Arabia's metropolitan corridors, with hyperscale operators prioritizing locations that combine grid interconnection capacity, desalinated water access, and proximity to government and financial services demand clusters.
Riyadh
AI training clusters and sovereign cloud workloads dominate Riyadh's demand profile, with hyperscale campuses exceeding 50 kW per rack densities. The National Data Management Office's tiered security standards require physically segmented zones within facilities, pushing providers toward modular liquid-cooled architectures. King Abdullah Financial District anchors financial services colocation demand as SAMA mandates Tier III certification for core banking systems.
Jeddah
Red Sea commercial corridors generate concentrated edge computing demand for retail analytics and low-latency transaction processing. Wholesale colocation agreements with global cloud providers are rewriting enterprise procurement patterns. The Western Region's desalination infrastructure supports evaporative cooling systems that face restrictions elsewhere, enabling denser server configurations than interior locations.
Eastern Province
Dammam and Khobar industrial zones present first-mover opportunities for latency-sensitive manufacturing automation and petrochemical IoT workloads. Saudi Aramco's digital transformation programs are pulling private edge deployments into the region. Limited existing compute capacity creates pricing premiums for operators that secure grid interconnection ahead of demand curves.
NEOM Northwest
The giga-project's renewable energy commitments align with Saudi Standards, Metrology and Quality Organization efficiency benchmarks, attracting carbon-neutral facility designs. ACWA Power solar-wind hybrid contracts reduce operational carbon intensity for hyperscale tenants. Regulatory sandbox provisions allow testing of immersion cooling and autonomous facility management at commercial scale.
Saudi Arabia Data Center Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: global hyperscale cloud providers anchoring multi-hundred-megawatt campuses, regional telecom operators leveraging captive infrastructure for enterprise leasing, and specialized developers targeting premium Tier III certification for financial services tenants. Competitive positioning depends on securing pre-certified power architectures and modular construction capabilities that compress commissioning timelines. Capacity expansion and sovereign cloud partnerships represent the dominant competitive moves as operators race to satisfy CST localization mandates.
Among global hyperscale providers, Amazon Web Services and Microsoft occupy positions as archetype anchors for sovereign cloud deployment, with Oracle representing the specialized enterprise database workload tier. Regional developers Damac Data Centers and Center3 exemplify the premium facility specialization vector targeting financial services certification requirements. These named entities sit within a broader ecosystem where Gulf Data Hub and Mobily anchor telecom-captive infrastructure plays, while DataVolt and Quantum Switch Tamasuk represent emerging modular deployment specialists.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft |
| Oracle |
| Quantum Switch Tamasuk |
| Damac Data Centers |
| Center3 |
| Gulf Data Hub |
| DataVolt |
| Mobily |
| Others |
Pricing and Supply Chain Analysis
Chinese precision cooling equipment manufacturers anchor upstream supply for liquid-cooled hyperscale deployments, concentrating margin capture in the specialized engineering tier rather than facility operations. Saudi operators absorb this import dependency through extended commissioning timelines and elevated capex, reshaping procurement negotiations with regional system integrators.
Pricing Analysis
Volume-discount tiering structures separate hyperscale cloud providers securing sub-$4 per kW rates from mid-market enterprises paying 40-60% premiums for retail colocation. Price differentiation hinges on power density commitments and Tier III certification status, with SAMA-regulated financial services accepting premium positioning for fault-tolerant guarantees. Cost compression in standard colocation tiers is intensifying as modular construction expands addressable supply. Government agencies show least price sensitivity, prioritizing NDMO compliance over per-kW economics.
Supply Chain Analysis
Extended payment terms from 90 to 180 days now dominate procurement contracts for precision cooling and power distribution units, easing liquidity pressure on operators facing 18-24 month Saudi Electricity Company interconnection delays. Geographic supply concentration draws from China for immersion cooling systems, Germany for switchgear components, and the United States for hyperscale-optimized server architectures. Raw material dependencies rest on copper busbars, lithium-ion battery cells, and specialized refrigerants. Single-source vulnerability runs through precision liquid cooling vendors lacking regional manufacturing presence. Distribution runs through systems integrators bundling hardware procurement with managed service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi data center market rewards operators possessing Uptime Institute-accredited engineering talent and pre-certified power architectures, with scarcity in certified design capacity creating bottlenecks that outstrip capital availability as constraints.
For Market Incumbents: Harden sovereign cloud positioning through NDMO pre-certification investments before CST localization mandates tighten further. Anchor capacity additions in Riyadh's King Abdullah Financial District to capture SAMA Tier III requirements. Defend against emerging modular specialists by locking multi-year power purchase agreements with ACWA Power that competitors cannot replicate. For New Entrants and Emerging Players: Pursue Eastern Province edge deployments in Dammam industrial corridors where latency-sensitive petrochemical automation demand outstrips existing compute supply. Target manufacturing IoT workloads seeking sub-10 millisecond response times unavailable from Riyadh-centric hyperscale campuses. Differentiate through renewable-powered facility designs aligned with SASMO efficiency benchmarks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with telecom-captive operators like Mobily and Center3 holding underutilized infrastructure in Jeddah and Riyadh metro rings. Long-term viability centers on conversion to managed sovereign cloud services under recurring revenue models rather than pure colocation yields. Watch Saudi Aramco's digital transformation capex disclosures as signal for Eastern Province demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | NDMO-certified environments capture government migration budgets under CST localization mandates. |
| Liquid Cooling Infrastructure Deployment | Direct-to-chip systems support 50+ kW AI training densities that air-cooled facilities cannot accommodate. |
| Renewable Power Purchase Agreement | ACWA Power solar-wind contracts satisfy SASMO efficiency benchmarks while reducing operational carbon intensity. |
| Modular Facility Construction | Prefabricated power and cooling modules compress commissioning from 24 months to 12-18 months. |
| Eastern Province Edge Expansion | Dammam and Khobar industrial zones present first-mover advantage for manufacturing automation workloads. |
Research Methodology
A spread of perspectives from hyperscale cloud procurement officers, data center engineering directors, CST regulatory affairs leads, and financial services IT infrastructure heads converged on the working assumptions driving capacity forecasts. Primary interview intelligence combined with secondary validation from SEC hyperscaler capex disclosures, CST regulatory filings, NDMO classification standards, and SASMO efficiency benchmark databases. Bottom-up installation tracking across Riyadh, Jeddah, and Eastern Province corridors triangulated against top-down cloud provider commitment announcements.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with hyperscale cloud absorption rates, enterprise colocation contract tenors, and edge computing latency requirements forming core segmentation dimensions. CAGRs derived from power interconnection approval timelines, modular construction deployment velocities, and AI workload density escalations. Forecast inputs incorporated Saudi Electricity Company substation commissioning schedules and ACWA Power renewable project completion patterns.
Macroeconomic conditions sit as an overlay; deviation in oil revenue allocation to digital infrastructure, foreign direct investment flows, or riyal-dollar exchange stability would shift the trajectory. Forecasts reflect documented assumptions about CST enforcement intensity and NDMO classification evolution. Regulatory reinterpretation of data localization scope, breakthroughs in ambient-temperature cooling technologies, or grid interconnection process reform would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Israel Data Center Rack Market