
 Automotive Lidar Market | 2026-2036
Automotive Lidar Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lidar Market Analysis
China is narrowing the gap between domestic lidar production capacity and global OEM qualification timelines. Hesai Technology leverages vertically integrated chip manufacturing to control transmitter costs. Luminar Technologies sustains its position through proprietary 1550-nanometer wavelength architecture for extended-range detection. RoboSense anchors its expansion in the European Tier-1 supply chain through localized technical service centers.
Automotive lidar refers to light detection and ranging systems that emit pulsed or continuous-wave laser light to construct three-dimensional point clouds of vehicle surroundings, typically operating at wavelengths of 905 nm or 1550 nm with refresh rates exceeding 10 Hz for real-time object tracking. These systems serve as the primary environmental perception layer for advanced driver assistance and autonomous navigation, converting optical time-of-flight or frequency-modulated phase shifts into spatial coordinates. Solid-state lidar dominates unit economics for highway-speed OEM programs, while mechanical scanning variants retain installed base in robotaxi fleets where 360-degree coverage remains essential. The component stack concentrates margin in receiver photodetectors and application-specific integrated circuits, where foundry partnerships determine supply security.
NHTSA in the United States, ECE R79 in Europe, and MIIT GB standards in China each impose distinct validation protocols for lidar-equipped vehicles, creating parallel certification pathways that inflate development overhead for multi-region platforms. The EU AI Act adds algorithmic transparency requirements for perception systems classified as safety-critical automated decision-making. Stakeholders must monitor how divergent wavelength approval regimes and cybersecurity mandates reshape supplier qualification criteria across their target markets.
Market Dynamics
OEM procurement of solid-state lidar for Level 3 autonomous highway systems is compressing supplier qualification timelines while NHTSA's updated occupant safety standards mandate redundant environmental sensing, creating dual pressure on component validation cycles.
Growth Catalysts
- Regulatory Mandates:NHTSA's redundant sensing requirements for automated driving features in the United States force OEM integration of multiple lidar units per vehicle platform, expanding addressable unit volume.
- Manufacturing Cluster Concentration:China's Yangtze River Delta hosts vertically integrated chip-to-system production facilities that compress transmitter cost curves and accelerate test cycles.
- Wavelength Architecture Differentiation:Proprietary 1550-nanometer systems deliver extended-range detection for highway-speed applications, opening specification windows previously closed to 905-nanometer alternatives.
Market Restraints
- Receiver Component Supply Concentration:Margin capture in avalanche photodiodes and application-specific integrated circuits depends on foundry partnerships concentrated in Taiwan and South Korea, creating single-source vulnerability.
- Parallel Certification Overhead:Divergent NHTSA, ECE R79, and MIIT GB validation protocols inflate development costs for multi-region vehicle platforms by requiring redundant test matrices.
- Mechanical Scanning Cost Structure:Robotaxi fleet demand for 360-degree coverage perpetuates mechanical spinning lidar variants with higher per-unit cost and maintenance burden versus solid-state alternatives.
Strategic Opportunities
- European Tier-1 Channel Penetration:Localized technical service centers in Germany and France enable direct specification influence with continental OEM engineering teams.
- Cybersecurity Certification Services:EU AI Act algorithmic transparency mandates for safety-critical perception systems create adjacent revenue in documentation and audit services.
- Software-Defined Lidar Convergence:Integration of perception algorithms directly onto lidar system-on-chip architectures reduces host-vehicle compute load and opens subscription feature models.
Industry Challenges
- Photonics Engineering Talent Scarcity:Design of frequency-modulated continuous-wave systems requires rare expertise in coherent detection and silicon photonics, constraining R&D velocity.
- Automotive Grade Qualification Timelines:AEC-Q100 and ISO 26262 functional safety certification cycles extend 18-24 months, misaligning with compressed OEM platform development schedules.
- Intellectual Property Licensing Complexity:Dense patent thickets around MEMS mirror actuation and optical phased arrays force cross-licensing negotiations that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lidar Market |
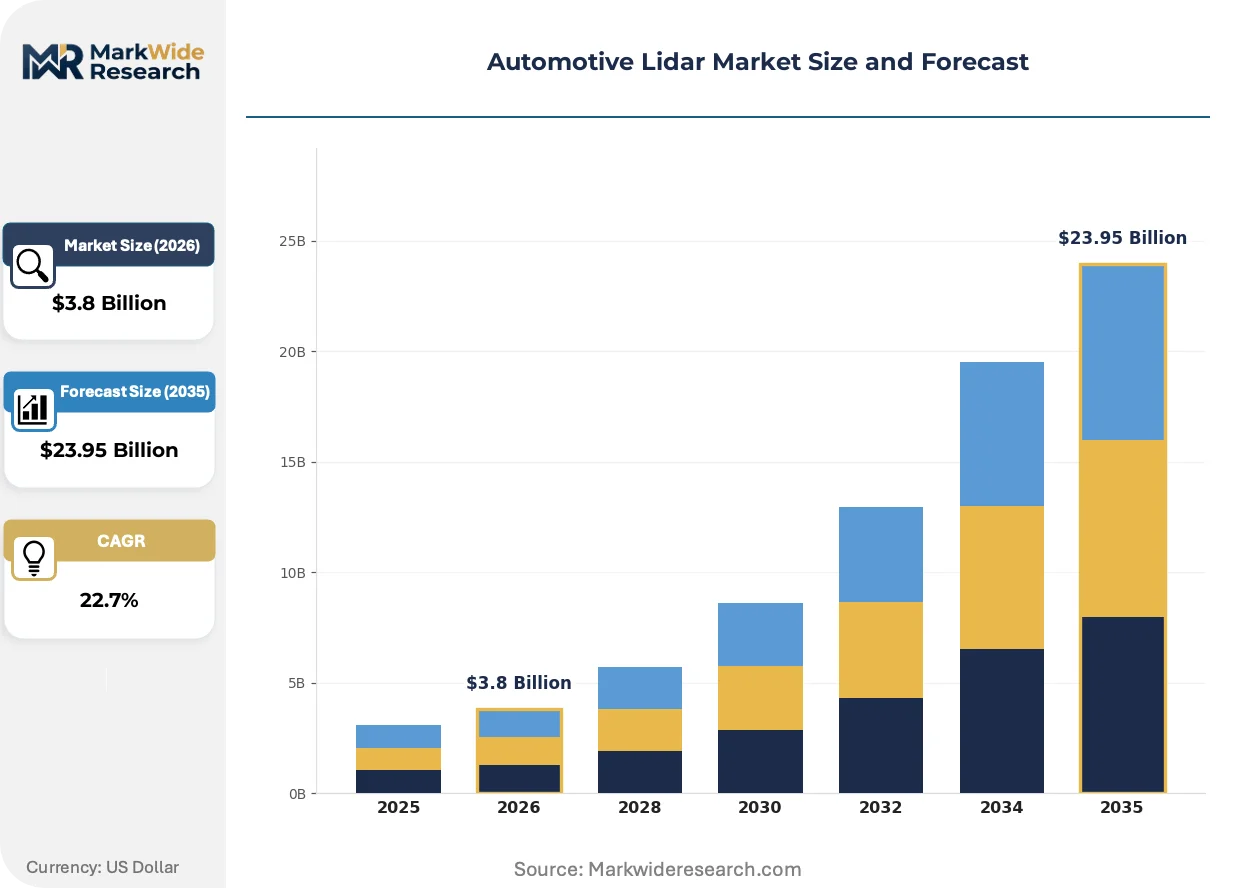
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solid-State, Mechanical, Frequency-Modulated Continuous Wave, Time-of-Flight Component: Transmitter, Receiver, Scanner, Processor Application: Advanced Driver Assistance Systems, Autonomous Vehicles, Collision Avoidance, Mapping End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Hesai Technology, RoboSense Technology, Luminar Technologies, Velodyne Lidar, Valeo, Huawei Technologies, Continental, Quanergy Systems, Innoviz Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lidar Market Emerging Trajectories
Automotive lidar architecture is converging around chip-scale integration and software-defined perception layers, collapsing traditional boundaries between hardware suppliers and algorithm developers while regulatory fragmentation forces parallel compliance investments.
Frequency-modulated continuous-wave lidar is hybridizing with silicon photonics to deliver coherent detection with shot-noise-limited sensitivity. Tier-1 suppliers in Germany and Japan are qualifying these systems for 2026 highway-speed platforms. The technology is hybridizing cost structures by eliminating discrete fiber lasers and enabling wafer-scale manufacturing.
ECE R79 in Europe and the EU AI Act together impose distinct validation protocols and algorithmic transparency requirements for lidar-equipped vehicles. Industrial consequence includes mandatory documentation of perception system decision boundaries for safety-critical automated functions. European OEMs respond by embedding interpretability modules directly into sensor firmware prior to homologation.
Fleet procurement of lidar-enabled advanced driver assistance systems is consolidating specification authority at the platform engineering level rather than distributed across Tier-2 component buyers. Direct OEM-supplier technical collaboration is displacing traditional distributor-mediated sourcing in premium vehicle segments. This pattern concentrates most visibly in China's Yangtze River Delta, where Hesai Technology and RoboSense operate co-located application engineering centers adjacent to OEM technical campuses.
Automotive Lidar Market Segmentation
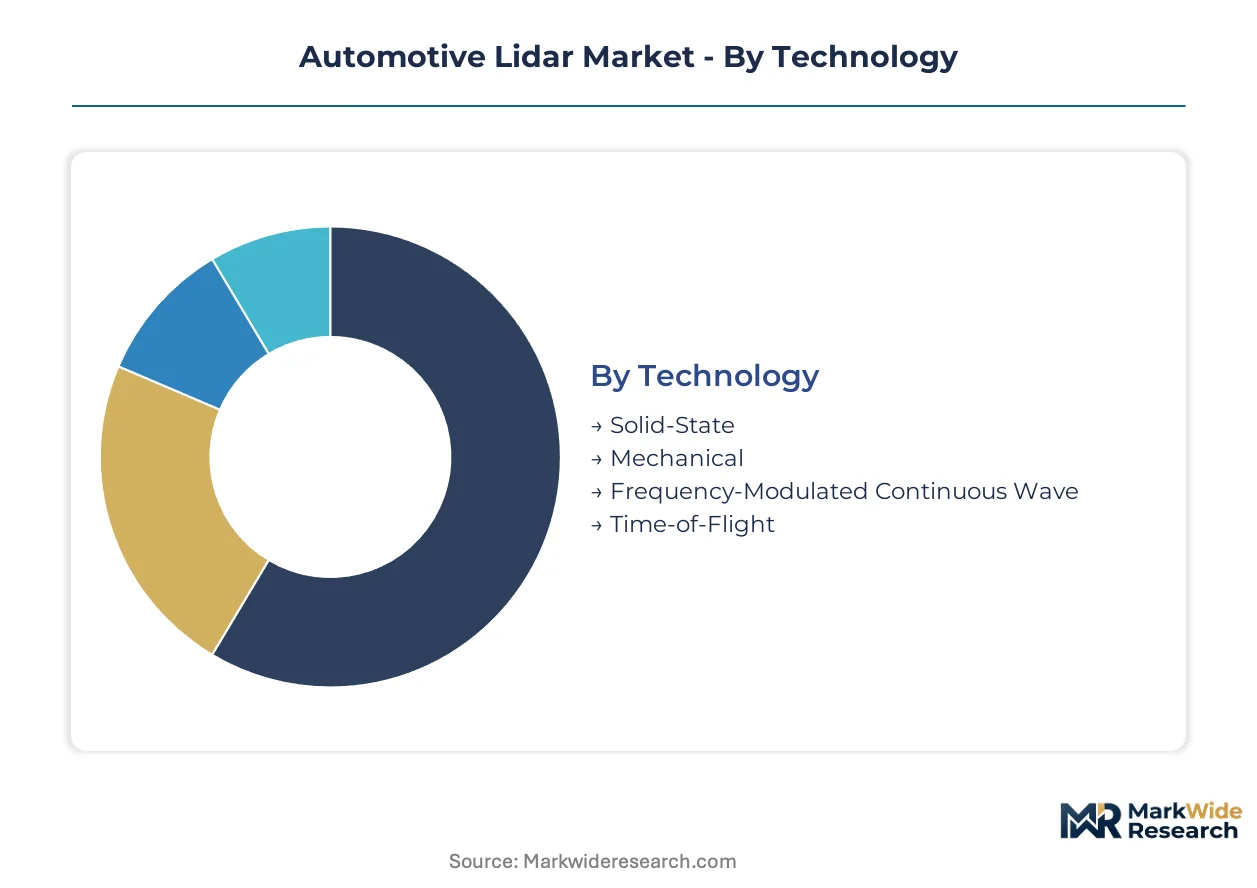
Automotive lidar segmentation reveals how technical architecture, supply chain position, and customer procurement authority fragment value capture across the value chain. Understanding these divisions exposes where margin concentrates and where qualification barriers create defensive moats.
Technology:
Mature scanning architectures now compete with emerging chip-scale alternatives as OEM highway programs drive qualification priorities.
- Solid-State:Optical phased arrays and MEMS mirror systems eliminate mechanical rotation through semiconductor-based beam steering. NHTSA redundant sensing mandates for Level 3 automation are compressing qualification timelines for these units in Detroit and Stuttgart engineering centers.
- Mechanical:Rotating assemblies with 360-degree field of view persist in robotaxi fleets where comprehensive environmental coverage outweighs unit cost concerns. Maintenance burden and per-unit economics limit penetration beyond mobility-as-a-service deployments.
- Frequency-Modulated Continuous Wave:Coherent detection architecture leveraging silicon photonics integration.
- Time-of-Flight:Pulsed laser measurement with direct photon counting.
Mechanical variants retain volume leadership in fleet deployments; solid-state holds the steepest expansion curve as highway-speed OEM programs multiply.
Component:
Cost tier differentiation separates commodity photonics from proprietary integrated circuit value capture.
- Transmitter:Vertical-cavity surface-emitting lasers and edge-emitting diodes convert electrical signals to optical pulses. Yangtze River Delta foundries in China are compressing gallium arsenide wafer costs through captive supply integration.
- Receiver:Avalanche photodiodes and single-photon avalanche diodes detect return signals with shot-noise-limited sensitivity. Taiwan and South Korea foundry partnerships determine supply security for this margin-concentrated layer.
- Scanner:MEMS micro-mirrors and optical phased arrays direct emission patterns.
- Processor:Application-specific integrated circuits executing point-cloud generation algorithms.
Receiver components command premium pricing; processors are gaining share fastest through software-defined lidar convergence.
Application:
Customer type splits between regulatory-mandated safety systems and discretionary autonomy investments.
- Advanced Driver Assistance Systems:Lane-keeping and adaptive cruise control functions requiring forward-facing perception with 200-meter range. ECE R79 validation protocols in Europe and NHTSA testing matrices in the United States impose parallel certification requirements.
- Autonomous Vehicles:Level 3 and Level 4 navigation demanding 360-degree environmental modeling with redundant coverage. Robotaxi operators in Arizona and California represent concentrated demand for high-unit-count installations.
- Collision Avoidance:Emergency braking augmentation with short-range, wide-field detection.
- Mapping:High-definition road network digitization for localization and simulation datasets.
Advanced driver assistance retains volume leadership; autonomous vehicle applications hold the steepest expansion curve.
End User:
Procurement authority is shifting from distributed Tier-2 purchasing to centralized platform engineering decisions.
- OEMs:Vehicle manufacturers specifying lidar directly for premium platform differentiation. German and Japanese OEMs are embedding technical teams within supplier facilities in China's Yangtze River Delta to accelerate co-development cycles.
- Tier-1 Suppliers:Continental and Bosch integrating lidar into packaged perception modules for resale to assemblers. These suppliers mediate specification influence in mid-market vehicle segments where direct OEM engagement is thinner.
- Aftermarket Providers:Retrofit installation for fleet safety upgrades and specialty vehicle modifications.
- Vehicle Assemblers:Contract manufacturers executing build-to-print integration without design authority.
OEM direct procurement retains volume leadership; Tier-1 channel penetration holds the steepest expansion curve as continental suppliers localize technical service centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA's redundant sensing mandates for automated driving features anchor United States demand, while divergent regulatory frameworks across Germany, China, Japan, and South Korea fragment qualification pathways for multi-region platforms.
United States
Level 3 highway automation programs at Detroit engineering centers drive solid-state lidar procurement. NHTSA updated occupant safety standards mandate redundant environmental sensing for vehicles with automated driving features. Arizona and California host concentrated robotaxi fleet deployments where mechanical scanning variants retain 360-degree coverage requirements.
Germany
Continental and Bosch specification authority shapes Tier-1 channel dynamics for mid-market vehicle segments. ECE R79 validation protocols impose distinct homologation requirements separate from United States testing matrices. Stuttgart and Munich engineering centers embed technical teams within supplier facilities to accelerate co-development cycles.
China
Domestic OEM procurement compresses supplier qualification timelines for highway-speed platforms. MIIT GB standards create parallel certification pathways alongside NHTSA and ECE regimes. Yangtze River Delta clusters host Hesai Technology and RoboSense integrated manufacturing and testing facilities with captive chip-to-system production.
Japan
Tier-1 suppliers qualify frequency-modulated continuous-wave systems for 2026 highway-speed platforms. METI industrial policy supports silicon photonics integration for coherent detection architectures. Nagoya and Tokyo engineering centers concentrate OEM technical collaboration with domestic photonics specialists.
South Korea
Foundry partnerships for avalanche photodiodes and application-specific integrated circuits determine receiver component supply security. National semiconductor industrial strategy prioritizes automotive photonics capability expansion. Seoul and Busan manufacturing clusters anchor backend packaging and test operations for lidar system-on-chip architectures.
Automotive Lidar Market Vendor Landscape
Vertically integrated specialists and wavelength-architecture innovators split the market between cost-curve compression and performance differentiation. The vendor base concentrates around three strategic archetypes: captive chip manufacturers controlling transmitter economics, proprietary wavelength developers commanding extended-range specifications, and Tier-1 integrators mediating mid-market access. Competitive moves center on foundry partnership consolidation for receiver security and localized technical service center deployment for direct OEM specification influence.
Within the vertically integrated tier, Hesai Technology and RoboSense Technology represent archetypes of captive supply chain control. Luminar Technologies occupies a distinct position through proprietary architecture specialization. These three entities exemplify how geographic concentration in China's Yangtze River Delta combines with wavelength differentiation at 1550-nanometer specifications to segment competitive positioning across highway-speed and robotaxi application vectors.
| Leading Market Players |
|---|
| Hesai Technology |
| RoboSense Technology |
| Luminar Technologies |
| Velodyne Lidar |
| Valeo |
| Huawei Technologies |
| Continental |
| Quanergy Systems |
| Innoviz Technologies |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing clusters compress transmitter cost curves through captive gallium arsenide wafer production, transferring downstream pricing power to vertically integrated suppliers while squeezing margin for module assemblers dependent on external component sourcing.
Pricing Analysis
Geographic price spreads between Chinese domestic procurement and European Tier-1 channels reflect certification overhead divergence. Three-tier pricing structure across premium, standard, and economy levels segments by AEC-Q100 grade and ISO 26262 ASIL rating. Cost compression in 905-nanometer solid-state units intensifies as Yangtze River Delta foundries expand VCSEL capacity. Fleet operators in robotaxi deployments exhibit highest price sensitivity; German premium OEMs tolerate premium positioning for 1550-nanometer extended-range specifications.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for multi-region platform suppliers. Receiver component manufacturing concentrates in Taiwan and South Korea, drawing from gallium arsenide substrate and indium phosphide foundry inputs. Single-source vulnerability in avalanche photodiode supply constrains qualification timelines for second-source validation. Distribution runs through Tier-1 integrators in Germany and direct OEM procurement channels in China's Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined lidar architectures transform hardware margins into recurring perception-service revenue, with algorithm subscription layers expanding faster than unit sales as OEMs seek to decouple feature roadmaps from hardware refresh cycles.
For Market Incumbents: Entrench position through backward integration into receiver photodetector foundry partnerships, securing supply against Taiwan and South Korea concentration risk. Accelerate AEC-Q100 and ISO 26262 certification pipelines to compress 18-24 month validation cycles. Defensive consolidation of MEMS mirror actuation IP through cross-licensing negotiations neutralizes patent thickets threatening product launch timelines.
For New Entrants and Emerging Players: Pursue white-space penetration in European cybersecurity certification services adjacent to EU AI Act algorithmic transparency mandates. Target collision avoidance retrofit segments in aftermarket fleet safety upgrades where incumbent coverage remains thin. Establish direct technical service presence in Stuttgart and Munich to bypass Tier-1 specification mediation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors frequency-modulated continuous-wave specialists with silicon photonics integration capability over mechanical scanning legacy assets. Long-term viability rests on software-defined convergence enabling subscription feature models. Watch for inflection in OEM direct procurement share displacing Tier-1 channel mediation as signal of architecture consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Consolidation | Secures avalanche photodiode supply against Taiwan and South Korea concentration risk. |
| Localized Technical Service Deployment | Enables direct specification influence with Stuttgart and Munich OEM engineering teams. |
| Software-Defined Lidar Convergence | Integrates perception algorithms onto system-on-chip architectures reducing host-vehicle compute load. |
| Cybersecurity Certification Services | Captures adjacent revenue from EU AI Act algorithmic transparency mandates for safety-critical systems. |
| Silicon Photonics Integration | Eliminates discrete fiber lasers enabling wafer-scale manufacturing for coherent detection architectures. |
Methodological Framework
The analysis maps solid-state, mechanical, and frequency-modulated continuous-wave architectures, each validated through OEM platform engineers, Tier-1 supplier procurement leads, photonics component specialists, and aftermarket fleet operators. Primary fieldwork combined with secondary validation from NHTSA regulatory filings, ECE R79 homologation databases, MIIT GB standard disclosures, and vehicle production registries. Bottom-up unit economics triangulate against top-down market sizing across technology, component, application, and end-user segmentation dimensions.
Assumption sets held regulatory mandate timelines and foundry capacity expansion fixed while varying OEM platform launch schedules and robotaxi fleet deployment rates. Volume and value outputs reflect segmentation by technology architecture, component layer, application intensity, and procurement channel authority across the projection horizon. CAGRs derive from fitted growth curves incorporating content-per-vehicle trajectories and regional adoption pattern differentials. Industry-specific inputs include AEC-Q100 qualification pipeline data and wavelength-specific detection range specifications.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or automotive production volumes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and foundry partnership stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Robotaxi Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
India Autonomous Navigation Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
US Autonomous Car Market