
 Saudi Arabia Oil and Gas Midstream Market | 2026-2036
Saudi Arabia Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Oil and Gas Midstream Market Analytics
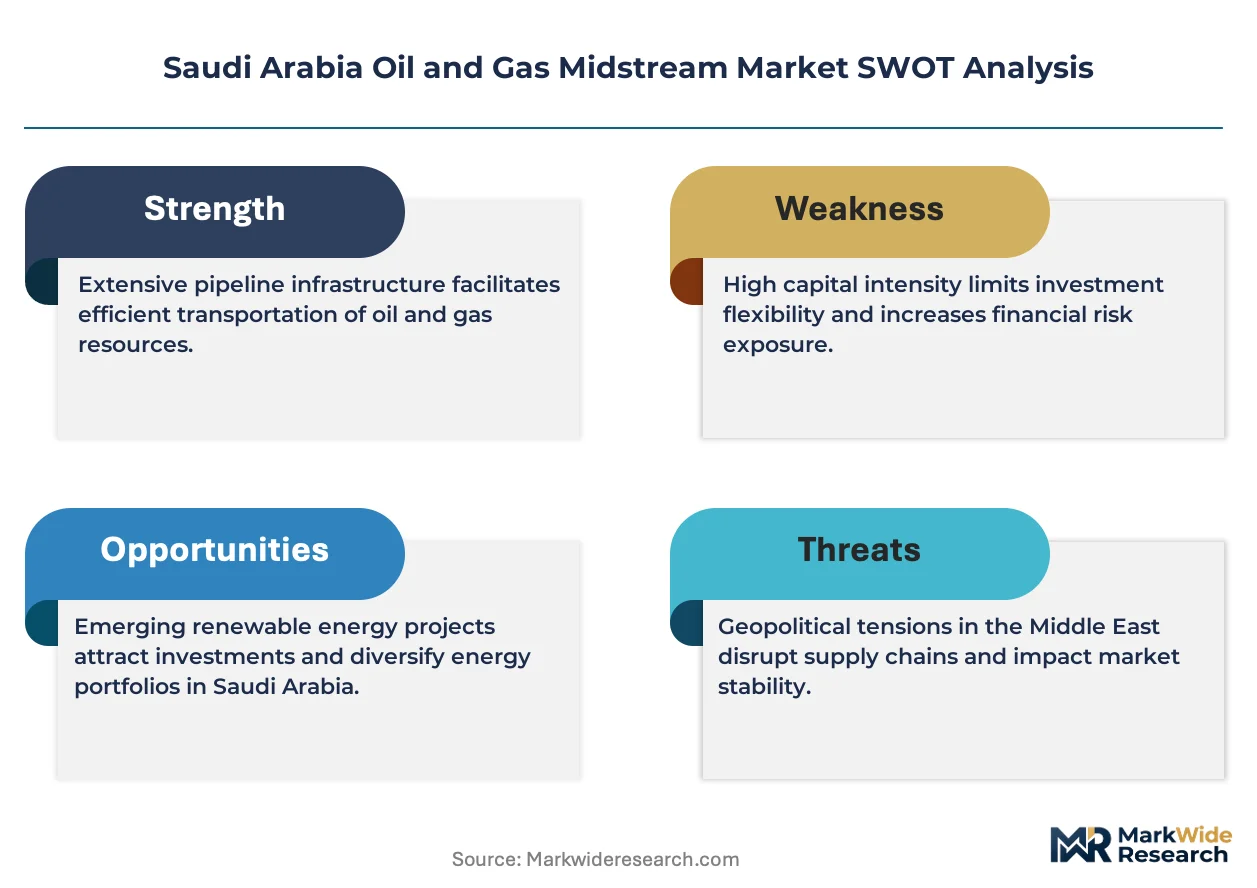
Carbon steel is repositioning product economics across pipeline construction as operators balance cost against corrosion resistance in sour gas service. Saudi Arabian Oil Company leverages its integrated upstream-downstream control to dominate domestic trunk line development. SLB anchors its midstream technology leadership through advanced pipeline inspection and integrity management systems. Chevron Corporation competes in select processing and terminal joint ventures where its heavy oil expertise differentiates service offerings.
The Saudi Arabia Oil and Gas Midstream sector encompasses the transportation, storage, and processing infrastructure that bridges extraction points with downstream refineries and export terminals, operating across pipelines exceeding 20 inches in diameter, pressurized storage tanks, and cryogenic LNG facilities designed for methane containment at minus 162 degrees Celsius. Its primary commercial purpose centers on maintaining continuous hydrocarbon flow while minimizing inventory holding costs and transit losses across vast desert terrain. Pipeline infrastructure commands the dominant share of capital deployment given its role in moving crude from Ghawar and Safaniya fields to coastal terminals, while LNG facilities represent the fastest-growing technology segment as Saudi Aramco pursues blue hydrogen and gas export diversification. Storage tanks and terminal services concentrate margin pools where throughput fees and strategic inventory management generate stable revenue streams independent of commodity price cycles.
SFDA oversees environmental and safety standards for hydrocarbon handling facilities, while MEE implements the Kingdom's dual carbon goals through emissions intensity benchmarks that shape new infrastructure permitting. SAMR enforces GB-aligned technical standards for pressure vessels and pipeline materials, effectively gatekeeping market access for equipment suppliers lacking certified manufacturing protocols. Stakeholders must monitor how Saudi Vision 2030 localization mandates alter procurement rules for midstream engineering and construction services.
Market Dynamics
SFDA environmental compliance protocols and MEE-aligned emissions standards are tightening construction specifications for new pipeline infrastructure across the Kingdom, forcing operators to recalculate capital deployment timelines and material selection criteria for sour gas service.
Growth Catalysts
- Blue hydrogen export mandates:Saudi Vision 2030 prioritizes gas-to-hydrogen conversion infrastructure, accelerating LNG terminal and cryogenic storage investments at Ras Tanura and Jubail Industrial City.
- Petrochemical feedstock security:Domestic ethane and NGL demand from Sadara and SABIC complexes sustains midstream throughput expansion independent of crude price cycles.
- Eastern Province cluster density:Proximity of Ghawar, Safaniya, and Khurais fields to coastal processing hubs minimizes transport distances and inventory holding costs.
Market Restraints
- Carbon steel corrosion susceptibility:Sour gas service with elevated hydrogen sulfide content accelerates pipeline degradation, elevating lifecycle maintenance outlays versus stainless alternatives.
- Specialized welding contractor scarcity:SAMR-certified fabrication capacity concentrates among Jeddah and Dammam-based shops, creating construction bottlenecks during concurrent project waves.
- Water scarcity for hydrotesting:Desert terrain limits freshwater availability for pipeline commissioning, forcing costly desalination or treated effluent sourcing.
Strategic Opportunities
- Carbon capture integration:MEE emissions intensity benchmarks incentivize CO2 pipeline networks linking gas processing plants with EOR fields in the Empty Quarter.
- Red Sea corridor development:Yanbu and Jeddah port complexes remain underpenetrated versus Eastern Province, offering greenfield terminal and storage buildout potential.
- Digital twin deployment:Convergence of IoT sensor networks with predictive analytics platforms enables real-time integrity management across aging trunk line infrastructure.
Industry Challenges
- ASME Section IX welder certification gaps:Qualified pressure vessel and pipeline welders require 18-24 month training cycles, lagging project award velocity.
- Legacy SCADA integration friction:Brownfield pipeline systems built on proprietary protocols resist seamless connection with modern centralized monitoring architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Oil and Gas Midstream Market |
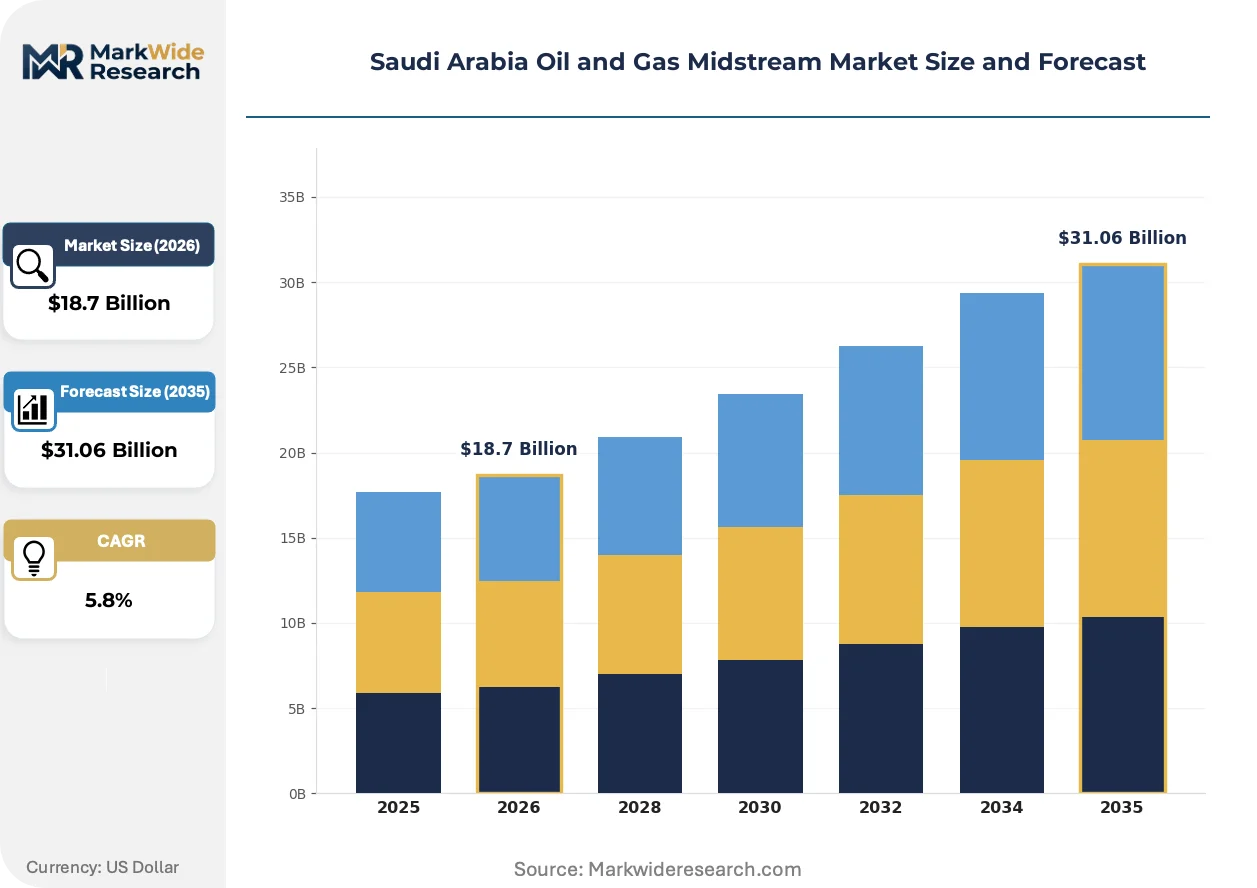
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Terminal Services, Processing Technology: Pipelines, LNG Facilities, Storage Tanks, Pump Stations End User: Government, Private Companies, Multinationals, Suppliers Application: Crude Oil, Natural Gas, Refined Products, Petrochemicals |
| Companies Covered | Chevron Corporation, Arabian Petroleum Supply Company (APSCO), Saudi Arabian Oil Company, SLB, Saipem, TotalEnergies SE, Medra Arabia, Linde, Shell PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Oil and Gas Midstream Market Evolving Landscape
Pipeline integrity management systems are automating defect detection and predictive maintenance workflows, compressing inspection cycles from manual quarterly surveys to continuous monitoring architectures.
Robotic inline inspection tools equipped with magnetic flux leakage and ultrasonic sensors now traverse 56-inch trunk lines without flow interruption. Saudi Aramco and joint venture operators deploy these systems across Ghawar-to-Ras Tanura corridors, reducing excavation and direct assessment frequency. The technology is automating anomaly classification and repair prioritization, shifting engineering resources from field verification to intervention planning.
SFDA hazardous materials handling regulations now mandate quantitative risk assessment for all new pressurized storage installations above 50,000 cubic meters. Engineering contractors must submit consequence modeling for vapor cloud dispersion and thermal radiation scenarios before construction permits issue. Tank farm developers in Jubail Industrial City respond by integrating blast-resistant control rooms and secondary containment systems that exceed prior specifications.
Long-term throughput contracts with take-or-pay structures are displacing spot-based terminal access for petrochemical producers. SABIC and downstream affiliates now secure dedicated storage capacity through 15-20 year agreements, insulating midstream operators from commodity volatility. This preference shift concentrates in methanol and derivative export chains where inventory reliability outweighs marginal price savings.
Saudi Arabia Oil and Gas Midstream Market Segmentation
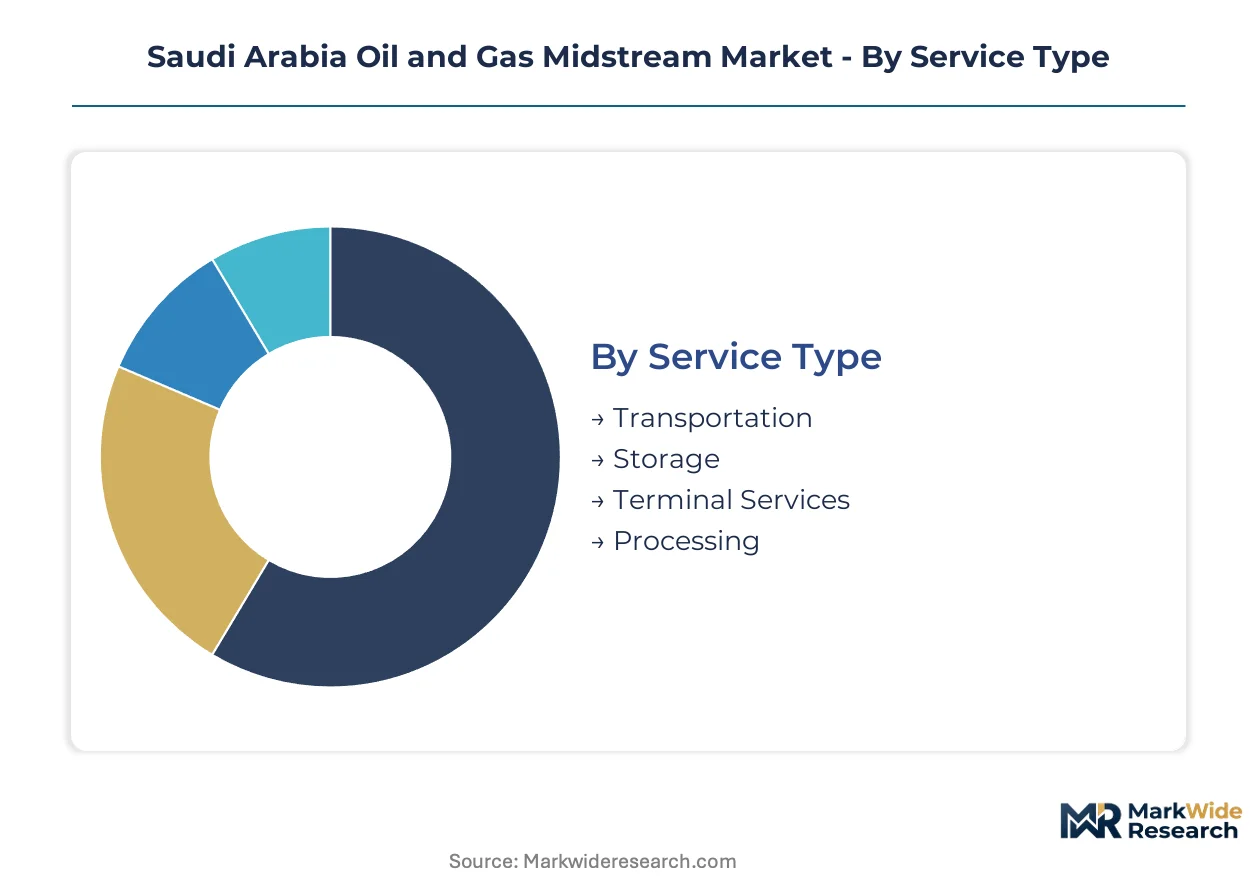
Midstream segmentation in Saudi Arabia reflects the Kingdom's strategic pivot from crude export dependency toward integrated gas and petrochemical value chains. Infrastructure investment patterns diverge sharply between legacy crude corridors and emerging hydrogen-ready systems.
Service Type:
Transportation commands the dominant capital allocation, while terminal services extract premium margins through long-term throughput contracts.
- Transportation:Trunk pipelines exceeding 20 inches in diameter move crude from Ghawar and Safaniya fields to Ras Tanura and Jubail terminals. SFDA pipeline integrity mandates now require continuous monitoring systems across all new construction, elevating capital intensity versus historical norms.
- Storage:Pressurized tank farms and cryogenic LNG facilities anchor inventory security for petrochemical producers. Demand concentrates at Jubail Industrial City where SABIC affiliates secure dedicated capacity through 15-20 year take-or-pay structures.
- Terminal Services:Throughput fees at coastal export facilities generate stable revenue independent of commodity cycles.
- Processing:Gas treatment and NGL fractionation bridges upstream production with downstream feedstock requirements.
Today's leader: Transportation. Tomorrow's challenger: Storage.
Technology:
Pipeline infrastructure absorbs the majority of engineering procurement, though LNG facilities are climbing fastest as blue hydrogen export mandates reshape capital planning.
- Pipelines:Carbon steel trunk lines remain the default specification for crude service, though sour gas corridors increasingly specify corrosion-resistant alloys. Eastern Province cluster density minimizes construction logistics costs versus Greenfield desert routes.
- LNG Facilities:Cryogenic storage at minus 162 degrees Celsius enables methane containment for export diversification. Ras Tanura expansion projects anchor the Kingdom's gas-to-hydrogen conversion infrastructure under Saudi Vision 2030.
- Storage Tanks:Above-ground floating roof and dome designs dominate terminal architecture.
- Pump Stations:Compression infrastructure maintains flow assurance across extended desert terrain with limited intermediate power grid access.
Current volume anchor: Pipelines. Steepest expansion trajectory: LNG Facilities.
End User:
Government-directed procurement dominates project awards, while private operators concentrate in specialized maintenance and integrity services.
- Government:Saudi Aramco and joint venture structures control trunk line development, leveraging integrated upstream-downstream positioning to dictate infrastructure specifications. SAMR certification requirements for pressure vessel fabrication concentrate qualified contractor pools in Jeddah and Dammam.
- Private Companies:Domestic engineering firms capture secondary construction and commissioning work.
- Multinationals:Technology providers supply inspection systems and predictive analytics platforms.
- Suppliers:Equipment vendors face localization mandates altering procurement rules for midstream engineering services.
Procurement concentration: Government. Emerging competitive opening: Private Companies.
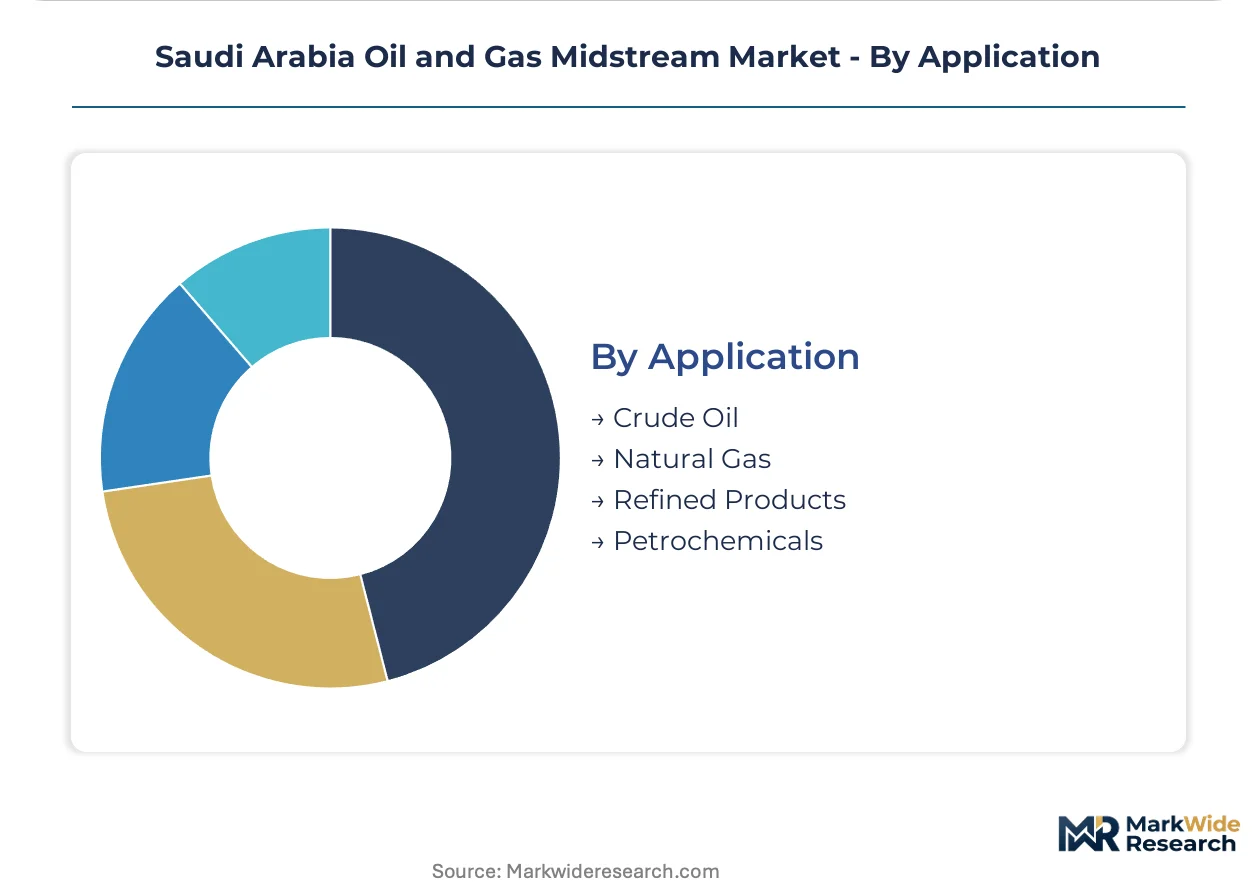
Application:
Crude oil infrastructure represents mature installed base, while petrochemical feedstock security is redirecting midstream investment toward NGL and ethane service.
- Crude Oil:Existing pipeline corridors from Ghawar to coastal terminals require integrity management upgrades rather than Greenfield construction. Robotic inline inspection tools now traverse these routes without flow interruption.
- Natural Gas:Sour gas processing with elevated hydrogen sulfide content accelerates material specification shifts toward corrosion-resistant alloys. MEE emissions intensity benchmarks incentivize CO2 pipeline networks linking gas plants with EOR fields.
- Refined Products:Product pipelines serve domestic distribution networks with lower capital intensity than crude trunk systems.
- Petrochemicals:Ethane and NGL demand from Sadara and SABIC complexes sustains throughput expansion independent of crude price volatility.
Established revenue base: Crude Oil. Fastest share gain: Petrochemicals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eastern Province anchors midstream capacity concentration through Ras Tanura and Jubail Industrial City complexes, with infrastructure investment patterns diverging between legacy crude corridors and emerging hydrogen-ready systems across the Kingdom's sub-regions.
Eastern Province
Ghawar, Safaniya, and Khurais field proximity drives pipeline and terminal demand from petrochemical producers. SFDA hazardous materials handling regulations mandate quantitative risk assessment for pressurized storage installations above 50,000 cubic meters. Jubail Industrial City hosts SABIC affiliates securing dedicated storage capacity through long-term take-or-pay structures.
Riyadh
Central administrative functions concentrate procurement and engineering oversight for nationwide trunk line development. SAMR enforces GB-aligned technical standards for pressure vessels and pipeline materials, gatekeeping market access for uncertified equipment suppliers. The capital's engineering contractor pools coordinate construction logistics for Eastern Province project waves.
Western Region
Yanbu and Jeddah port complexes remain underpenetrated versus Eastern Province infrastructure density. MEE emissions intensity benchmarks shape new infrastructure permitting across Red Sea corridor development. Greenfield terminal and storage buildout potential attracts midstream operators seeking geographic diversification beyond established crude corridors.
NEOM Northwest
Blue hydrogen export mandates under Saudi Vision 2030 accelerate LNG terminal and cryogenic storage investments. MEE-aligned dual carbon goals incentivize CO2 pipeline networks linking gas processing plants with EOR fields. Ras Tanura expansion projects anchor gas-to-hydrogen conversion infrastructure serving future export corridors.
Saudi Arabia Oil and Gas Midstream Market Competitive Landscape
Global majors compete with regional champions across integrated upstream-downstream control, with market structure consolidating around state-directed procurement and specialized technology licensing. Saudi Aramco leverages captive field access to dominate domestic trunk line development, while international service providers capture secondary construction and integrity management contracts. Two archetypes prevail: integrated national oil companies controlling infrastructure specifications, and technology specialists supplying inspection systems and predictive analytics platforms. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as operators seek SAMR-certified fabrication capacity and SFDA compliance capabilities.
Within the integrated NOC tier, Saudi Arabian Oil Company anchors domestic midstream development through field-to-terminal infrastructure control. Chevron Corporation and SLB occupy positions exemplifying contrasting competitive approaches—Chevron through heavy oil processing joint ventures, SLB through pipeline inspection and integrity management technology deployment. These three entities represent the spectrum from state-captive infrastructure dominance to specialized service provision.
| Leading Market Players |
|---|
| Chevron Corporation |
| Arabian Petroleum Supply Company (APSCO) |
| Saudi Arabian Oil Company |
| SLB |
| Saipem |
| TotalEnergies SE |
| Medra Arabia |
| Linde |
| Shell PLC |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers anchor Saudi Arabia's midstream infrastructure ownership, compressing procurement cycles for SAMR-certified fabrication while enforcing disciplined long-term contract pricing that insulates terminal operators from spot commodity volatility.
Pricing Analysis
Input-cost pass-through dominates midstream economics as carbon steel and corrosion-resistant alloy prices feed directly into pipeline construction quotes. Contract-based long-term offtake structures with 15-20 year take-or-pay terms separate premium tier anchor tenants from standard tier spot users, with petrochemical feedstock security commanding least price sensitivity. Pricing pressure stems from water scarcity forcing costly desalination for hydrotesting, while specialized welding contractor scarcity elevates labor premiums.
Supply Chain Analysis
Freight costs from Jeddah and Dammam fabrication shops to Eastern Province construction sites concentrate logistics spend among domestic SAMR-certified contractors. Raw material flows draw from South Korean steel mills, German valve manufacturers, and Japanese inspection equipment suppliers. Single-source vulnerability sits with qualified ASME Section IX welders. Distribution runs through state-directed procurement channels with Saudi Aramco controlling trunk line specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's oil and gas midstream market functions as a stable compounder, with petrochemical feedstock security and blue hydrogen export mandates under Saudi Vision 2030 generating throughput visibility across multi-decade contract horizons.
For Market Incumbents: Lock in SAMR-certified fabrication capacity through exclusive partnerships with Jeddah and Dammam-based shops before concurrent project waves strain qualified welder availability. Deepen backward integration into corrosion-resistant alloy sourcing to offset carbon steel price volatility and sour gas service degradation risks.
For New Entrants and Emerging Players: Capture digital twin deployment opportunities across aging Ghawar-to-Ras Tanura trunk lines where legacy SCADA integration friction creates white-space for IoT-enabled predictive analytics platforms. Target Western Region terminal services at Yanbu and Jeddah port complexes where infrastructure density lags Eastern Province.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized integrity management technology providers lacking scale to compete with SLB's inspection system dominance. Five-to-ten year viability hinges on carbon capture integration mandates materializing into CO2 pipeline network awards. Watch MEE emissions intensity benchmark revisions as the signal for infrastructure permitting acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Throughput Contracting | SABIC affiliates secure dedicated storage capacity through 15-20 year take-or-pay structures at Jubail Industrial City. |
| Carbon Capture Integration | CO2 pipeline networks linking gas processing plants with EOR fields respond to MEE dual carbon goals. |
| Digital Twin Deployment | IoT sensor convergence with predictive analytics enables real-time integrity management across aging trunk lines. |
| SAMR Certification Investment | Pressure vessel and pipeline material standards gatekeep market access for fabrication contractors. |
| Western Region Terminal Buildout | Greenfield storage capacity at Yanbu and Jeddah diversifies geographic exposure beyond Eastern Province clusters. |
Research Methodology
Multiple input streams — structured interviews with pipeline engineering directors, terminal operations managers, and EPC procurement leads; secondary validation through Saudi Aramco infrastructure disclosures, SFDA regulatory filings, and MEE emissions benchmark documentation; plus customs data on alloy and equipment imports — were reconciled through bottom-up project pipeline enumeration and top-down macroeconomic alignment.
Data-stream reconciliation across service type, technology, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from capacity expansion timelines, contract award velocities, and localization mandate implementation schedules. Modeled outputs incorporate SFDA integrity management mandates and SAMR certification requirement evolution as industry-specific forecast inputs.
Regulatory enforcement variance, hydrogen export mandate acceleration, and carbon steel price volatility are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in MEE emissions intensity benchmark stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Algeria Oil and Gas Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Geothermal Drilling Market
Oil & Gas
Well Cementing Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Planned LNG Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Copper Mining Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Malaysia Oil and Gas Midstream Market