
 Intelligent Well Completion Market | 2026-2036
Intelligent Well Completion Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Well Completion Market Outlook
Direct sales channels between service companies and national oil companies is narrowing as integrated project delivery models gain favor. Schlumberger Ltd dominates deepwater intelligent completion tenders through its technology leadership in permanent downhole monitoring systems. Halliburton Company anchors its position by leveraging in-house manufacturing of multi-zone frac pack systems for unconventional reservoirs. Baker Hughes Company competes through specialized digital twin integration that couples downhole sensors with surface control networks.
Intelligent well completion refers to the integration of remotely actuated downhole valves, permanent sensors, and surface control systems that enable real-time zonal flow management without well intervention. These systems typically operate at pressures exceeding 10,000 psi and temperatures above 150°C, using hydraulic or electric actuation to regulate production from multiple reservoir zones through a single wellbore. Smart Wells command the largest revenue share among product types due to their capital intensity and long deployment cycles in subsea environments. Data Analytics represents the fastest-expanding technology segment as operators deploy machine learning models to convert downhole sensor streams into actionable production optimization decisions.
The US Bureau of Safety and Environmental Enforcement mandates blowout preventer and well control system certifications that directly shape intelligent completion design specifications for Gulf of Mexico deployments. Norway's Petroleum Safety Authority enforces functional safety standards for subsea production control systems, creating compliance barriers for non-specialist entrants. Stakeholders must monitor how evolving methane detection regulations across multiple offshore jurisdictions reshape sensor deployment requirements and retrofit timelines.
Market Dynamics
The US EPA's methane emissions regulations are compressing deployment timelines for real-time downhole monitoring technologies, forcing operators to retrofit legacy wellbores with permanent sensor networks that enable continuous zonal flow control without well intervention.
Growth Catalysts
- Subsea Deepwater Expansion:Offshore operators in the US Gulf Coast are mandating intelligent completion architectures for new deepwater projects requiring zonal isolation across multiple reservoir zones through single wellbores.
- Permanent Downhole Monitoring:Real-time pressure and temperature sensing systems are eliminating intervention costs while extending well life cycles in high-temperature reservoirs exceeding 150°C.
- Machine Learning Integration:Data analytics platforms are converting continuous sensor streams into automated production optimization decisions, reducing response time to reservoir behavior changes.
Market Restraints
- Specialized Alloy Supply Concentration:High-nickel alloys and corrosion-resistant metals for downhole valves concentrate among a limited supplier base, creating input cost volatility and delivery risk.
- Functional Safety Certification Barriers:Norway's Petroleum Safety Authority mandates IEC 61508 compliance for subsea production control systems, extending qualification timelines for non-specialist component manufacturers.
- Electrical Submersible Pump Substitution:Artificial lift systems in marginal fields compete with intelligent completions for capital allocation, particularly in onshore unconventional reservoirs with shorter payback requirements.
Strategic Opportunities
- Middle East Carbonate Reservoirs:Saudi Arabia and Kuwait are expanding intelligent completion pilots in fractured carbonate formations where multi-zone flow control addresses water coning challenges.
- Digital Twin Convergence:Coupling downhole sensor networks with surface control systems and predictive analytics platforms is creating integrated asset management offerings that command service premiums.
- Integrated Project Delivery:Direct operator-service company alliances are displacing traditional tender-based procurement, enabling co-development of customized completion architectures.
Industry Challenges
- Subsea Controls Engineering Talent Scarcity:The specialized skill set combining hydraulic actuation, high-pressure sealing, and subsea electronics faces limited training pipeline capacity relative to deployment demand.
- Legacy Wellbore Retrofit Complexity:Installing permanent monitoring systems in existing completions requires tubing retrieval and re-completion, multiplying execution risk and downtime exposure.
- Multi-Vendor System Integration:Interoperability gaps between valve actuators, sensors, and surface control networks from different suppliers create commissioning delays and operational reliability concerns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Well Completion Market |
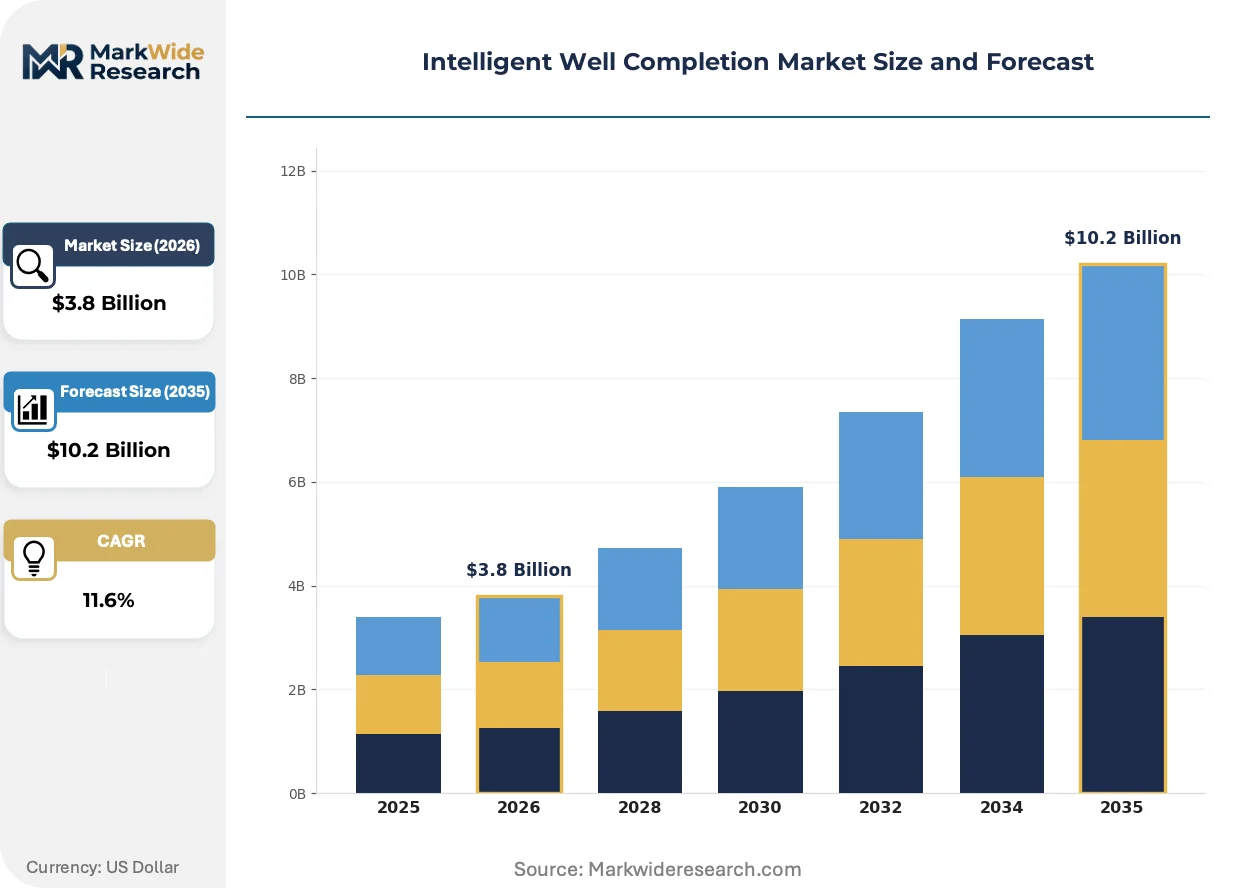
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Wells, Multi-Phase Flow Meters, Downhole Sensors, Control Systems End User: Oil & Gas Operators, Engineering Firms, Service Providers, Corporations Technology: Artificial Lift Systems, Wireless Communication, Data Analytics, IoT Application: Enhanced Oil Recovery, Reservoir Management, Production Optimization, Monitoring |
| Companies Covered | Schlumberger Ltd, Halliburton Company, Baker Hughes Company, Weatherford International plc, National-Oilwell Varco Inc, Schoeller-Bleckmann Oilfield Equipment AG, Packers Plus Energy Services Inc, Omega Well Intervention Ltd, Welltec A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Well Completion Market Strategic Shifts
Digital infrastructure is virtualizing physical well intervention workflows, compressing the traditional service-company revenue model while enabling operator self-sufficiency in production optimization. Three developments are restructuring competitive positioning.
Downhole fiber-optic sensing is virtualizing traditional well testing and production logging operations. North Sea operators are deploying distributed temperature and acoustic sensing systems that eliminate wireline intervention for zonal flow profiling. This virtualization is collapsing the historical separation between completion hardware and diagnostic services into unified platform offerings.
The US Bureau of Safety and Environmental Enforcement is tightening blowout preventer and well control system certification requirements for Gulf of Mexico deployments. These mandates are accelerating qualification cycles for intelligent completion components rated above 10,000 psi operating pressure. Subsea control system manufacturers are responding by pre-certifying valve actuator designs to reduce project-specific engineering overhead.
Integrated project delivery models are displacing transactional equipment procurement in deepwater developments. National oil companies are contracting directly with service providers for full-field intelligent completion architectures spanning design, installation, and lifecycle monitoring. This shift is most visible in Brazil's pre-salt developments where Petrobras mandates single-point accountability for subsea production system performance.
Intelligent Well Completion Market Segmentation
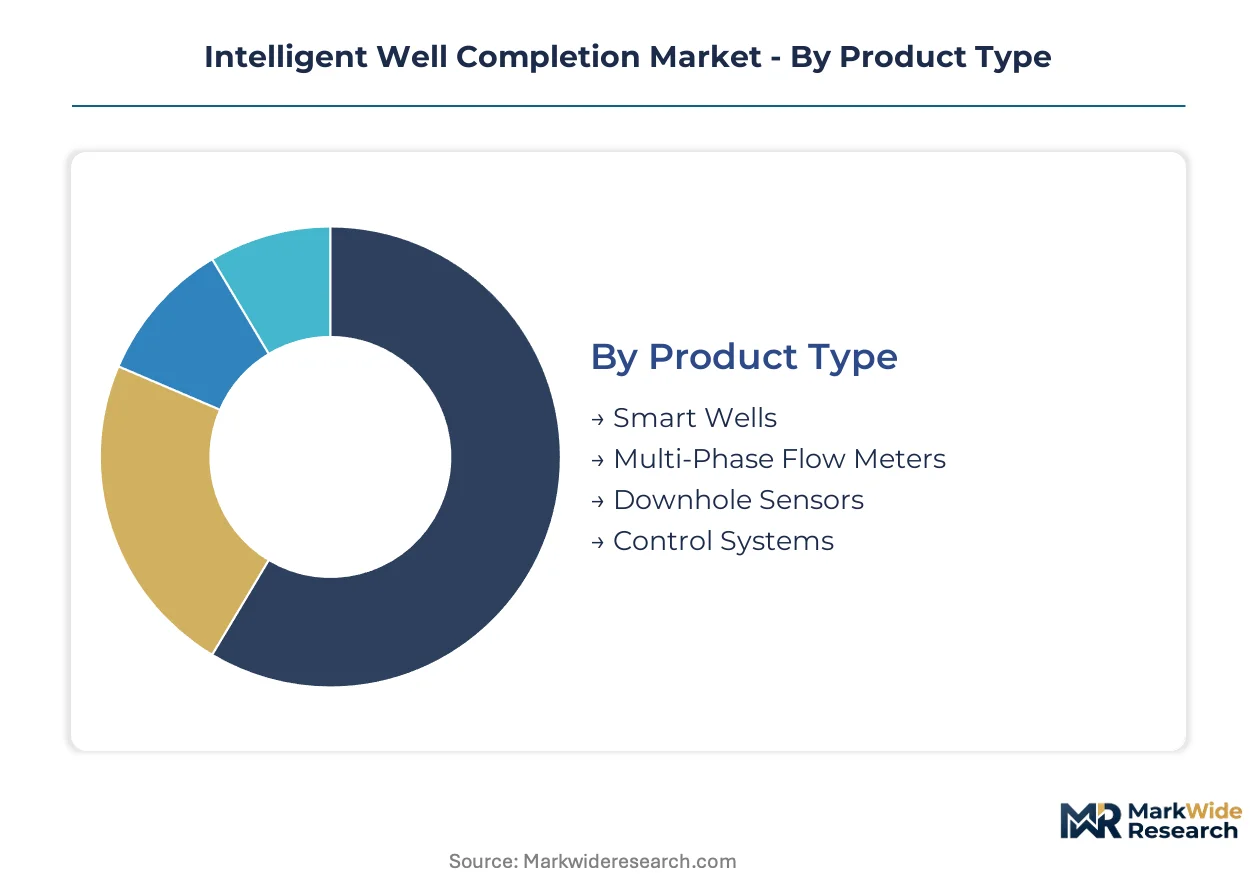
Intelligent well completion systems require sustained field service presence across decades-long deployment cycles. Segmentation reveals how after-sales intensity varies by product complexity, technology integration depth, and operator technical capabilities.
Product Type:
After-sales service intensity concentrates in subsea-rated hardware requiring periodic calibration, seal replacement, and control system firmware updates throughout multi-decade field life.
- Smart Wells:Integrated architectures combine remotely actuated downhole valves with permanent monitoring networks operating above 10,000 psi and 150°C. Gulf of Mexico deepwater developments mandate these systems for zonal isolation across multi-zone reservoir sections, with Petrobras pre-salt contracts requiring single-point vendor accountability for lifecycle performance.
- Downhole Sensors:Fiber-optic and electronic pressure-temperature arrays enable continuous reservoir surveillance without well intervention. North Sea operators deploy distributed acoustic sensing for virtual production logging, collapsing traditional wireline service revenue models into unified platform offerings.
- Multi-Phase Flow Meters:Subsea-rated measurement systems separate oil, gas, and water streams at the wellhead for allocation metering.
- Control Systems:Surface and subsea electronics packages translate operator commands into hydraulic or electric valve actuation.
By volume, Downhole Sensors lead. By growth pace, Smart Wells is ahead.
End User:
Procurement sophistication separates integrated national oil companies with in-house petroleum engineering capabilities from independents relying on external technical support.
- Oil & Gas Operators:Supermajors and national oil companies deploy capital directly, with Saudi Aramco and Kuwait Oil Company expanding intelligent completion pilots in fractured carbonate reservoirs to address water coning. These operators increasingly mandate integrated project delivery models that compress traditional tender cycles.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes bundle hardware installation with lifecycle monitoring contracts. Brazil's pre-salt regulatory framework requires single-point accountability for subsea production system performance, favoring vertically integrated service company consortia.
- Engineering Firms:Design contractors specify intelligent completion architectures for operator clients without assuming installation risk.
- Corporations:Diversified energy conglomerates allocate capital across upstream portfolios with varying technical sophistication.
By contract value, Oil & Gas Operators dominate. By deal velocity, Service Providers is expanding most quickly.
Technology:
Technology segmentation tracks the shift from mechanical actuation toward digitally native architectures that reduce well intervention frequency.
- Data Analytics:Machine learning platforms convert continuous downhole sensor streams into automated production optimization decisions. US Gulf Coast operators deploy predictive models to compress response time to reservoir behavior changes, with EPA methane regulations accelerating real-time monitoring requirements.
- Wireless Communication:Acoustic and electromagnetic telemetry eliminates hydraulic control lines, reducing subsea infrastructure weight and installation complexity.
- Artificial Lift Systems:Electrical submersible pumps and gas lift compete with intelligent completions for capital in marginal fields with shorter payback requirements.
- IoT:Industrial internet platforms integrate downhole sensors with surface control networks and enterprise asset management systems.
By installed base, Artificial Lift Systems holds the largest footprint. By investment growth, Data Analytics climbs the fastest.
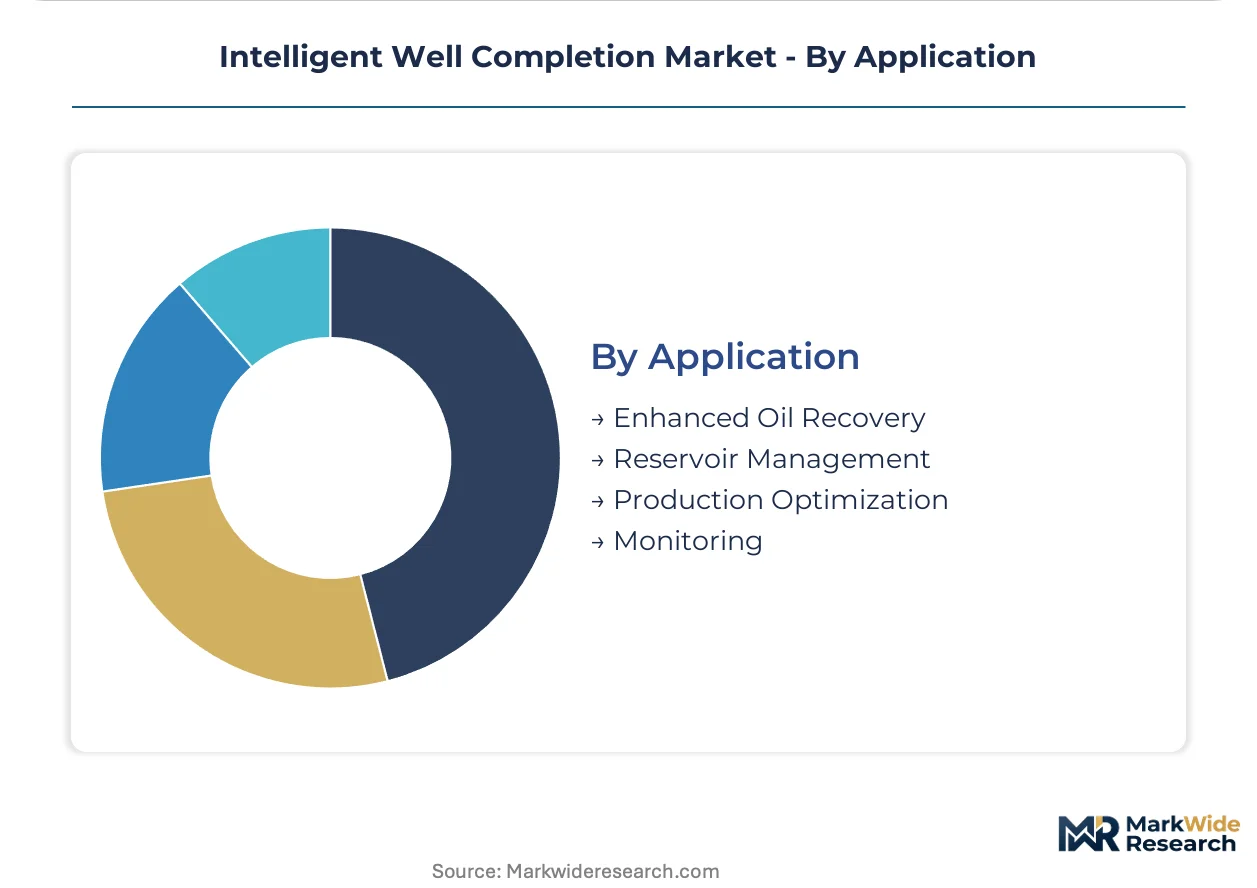
Application:
Application segmentation reflects the progression from diagnostic monitoring toward closed-loop autonomous reservoir management.
- Production Optimization:Real-time zonal flow control maximizes recovery factors by adjusting valve positions in response to pressure drawdown and water breakthrough. Norway's Petroleum Safety Authority mandates IEC 61508 functional safety compliance for these automated control loops.
- Reservoir Management:Permanent monitoring networks build subsurface understanding without production interruption, with distributed temperature sensing virtualizing traditional well testing operations.
- Enhanced Oil Recovery:Intelligent completions enable targeted injection and production profiling for waterflood and chemical EOR projects.
- Monitoring:Baseline surveillance applications satisfy regulatory reporting requirements without active intervention capability.
By deployment frequency, Monitoring remains most common. By value capture, Production Optimization gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater project economics in Norway command pricing premiums that Gulf of Mexico operators cannot replicate, compressing margin structures across North American service providers while concentrating value capture in the North Sea basin.
United States
The US Gulf Coast generates concentrated demand for subsea-rated intelligent completions as deepwater developments in the Gulf of Mexico mandate zonal isolation architectures. The US Bureau of Safety and Environmental Enforcement enforces blowout preventer and well control system certifications that shape component design specifications above 10,000 psi operating pressure. Houston anchors the domestic supplier ecosystem, with engineering clusters along the Texas-Louisiana coastline executing retrofit programs for EPA methane compliance.
Norway
North Sea operators deploy capital-intensive smart well architectures across high-pressure, high-temperature reservoirs requiring IEC 61508 functional safety compliance. The Petroleum Safety Authority mandates subsea production control system certifications that extend qualification timelines and create compliance barriers for non-specialist entrants. Stavanger and Bergen host integrated project delivery consortia delivering single-point accountability contracts for Equinor and Aker BP developments.
Brazil
Pre-salt carbonate formations drive adoption of multi-zone flow control systems addressing reservoir complexity below thick salt layers. Petrobras mandates single-point vendor accountability for subsea production system performance, favoring vertically integrated service company alliances over transactional procurement. The Santos Basin development corridor concentrates deployment activity, with Rio de Janeiro engineering centers specifying completion architectures for ultra-deepwater wells.
Saudi Arabia
Carbonate reservoir complexity in the Ghawar and Safaniya fields accelerates intelligent completion pilots targeting water coning challenges in fractured formations. Saudi Aramco expands direct contracting with service providers for full-field architectures spanning design through lifecycle monitoring. Dhahran-based petroleum engineering centers coordinate deployment timelines across the Eastern Province oil corridor.
United Kingdom
Mature North Sea assets require permanent monitoring retrofits to extend well life cycles without production interruption. The North Sea Transition Authority shapes decommissioning timelines that influence sensor deployment economics for late-life field management. Aberdeen maintains subsea controls engineering talent pools despite pipeline constraints relative to deployment demand across the UK continental shelf.
Intelligent Well Completion Market Competitive Environment
Integrated energy service conglomerates and specialized subsea technology developers split the market along capital intensity and technical specialization vectors. Three archetypes dominate: vertically integrated majors bundling hardware with lifecycle monitoring contracts; mid-tier specialists concentrating on discrete component manufacturing; and digital-native entrants coupling sensor hardware with predictive analytics platforms. Competitive dynamics center on pre-certification of valve actuator designs to reduce project-specific engineering overhead, and direct operator alliances displacing traditional tender-based procurement channels.
Within the integrated service tier, Schlumberger Ltd, Halliburton Company, and Baker Hughes Company occupy positions as archetype anchors. Schlumberger represents technology leadership in permanent downhole monitoring systems through its deepwater tender dominance. Halliburton exemplifies in-house manufacturing integration for multi-zone frac pack systems targeting unconventional reservoirs. Baker Hughes sits within the digital convergence archetype, coupling downhole sensor networks with surface control infrastructure. These three entities collectively shape certification standards, pricing benchmarks, and procurement modality shifts across offshore jurisdictions.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| National-Oilwell Varco Inc |
| Schoeller-Bleckmann Oilfield Equipment AG |
| Packers Plus Energy Services Inc |
| Omega Well Intervention Ltd |
| Welltec A/S |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in high-nickel alloy forging capacity across Houston and Stavanger engineering clusters compresses supplier pricing power while extending delivery timelines for subsea-rated valve actuators above 10,000 psi. This utilization squeeze forces operators to accept longer procurement cycles or premium expediting fees, reshaping total cost of ownership calculations for Gulf of Mexico and North Sea developments.
Pricing Analysis
The customization-premium spread between configured-to-order intelligent completion architectures and standard multi-zone frac pack systems spans project-based contracting with lifecycle monitoring bundles versus per-unit transactional hardware procurement. Price differentiation rests on IEC 61508 certification tier and after-sales service intensity, with Petrobras-mandated single-point accountability contracts commanding substantial premiums over transactional Gulf of Mexico tenders. Pricing pressure stems from artificial lift substitution in marginal onshore fields, compressing margins for standardized downhole sensor deployments. Independent operators in US unconventional basins exhibit highest price sensitivity, while Saudi Aramco and Equinor demonstrate lowest sensitivity given full-field architecture mandates.
Supply Chain Analysis
Export-control regimes limiting high-pressure sealing technology flows constrain supplier mobility across US, Norway, and UK subsea engineering centers. Geographic supply concentration centers on Germany for precision-machined valve components, Japan for high-temperature electronics, and US Gulf Coast for integrated system assembly. Raw material dependencies draw from Indonesian nickel for corrosion-resistant alloys, German specialty steels for downhole housings, and US-sourced fiber-optic sensing cables. Single-source vulnerability concentrates in IEC 61508-certified control system firmware providers. Distribution runs through direct operator-service company alliances displacing traditional tender channels, with integrated project delivery models capturing growing share of Brazil and Middle East contract value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent well completion markets face high-growth disruption as EPA methane regulations and Norway Petroleum Safety Authority mandates force real-time monitoring retrofit cycles across legacy offshore infrastructure. This regulatory inflection compresses deployment timelines while elevating certification barriers.
For Market Incumbents: Entrench position through backward integration into high-nickel alloy supply and captive certification capacity for IEC 61508 functional safety compliance. Expand Stavanger and Houston engineering clusters to address subsea controls talent scarcity threatening execution timelines. Defend against digital-native entrants coupling sensor hardware with predictive analytics by pre-bundling lifecycle monitoring contracts with hardware installation.
For New Entrants and Emerging Players: Carbonate reservoir pilots in Saudi Arabia and Kuwait represent the most penetrable entry point, with water coning challenges in fractured Ghawar formations creating demand for multi-zone flow control specialization. Wireless telemetry systems eliminating hydraulic control lines offer differentiated go-to-market positioning against established electric-hydraulic incumbents. Target direct contracting relationships with Saudi Aramco petroleum engineering centers bypassing integrated service company procurement channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across data analytics platforms converting sensor streams into automated production optimization. Long-term viability over the next decade favors acquisition targets with machine learning integration capabilities and existing Petrobras or Equinor reference contracts. Monitor EPA methane compliance retrofit timelines as inflection signal for sensor deployment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Investment | IEC 61508 valve actuator pre-qualification reduces project-specific engineering overhead for BSEE-mandated Gulf of Mexico deployments. |
| Digital Twin Integration | Coupling downhole sensors with surface control networks creates unified platform offerings collapsing wireline service revenue models. |
| Integrated Project Delivery | Direct Petrobras alliances displace transactional procurement, enabling co-development of customized pre-salt completion architectures. |
| Wireless Telemetry Development | Acoustic and electromagnetic control line elimination reduces subsea infrastructure weight and installation complexity. |
| Carbonate Reservoir Specialization | Water coning expertise in fractured formations addresses Saudi Aramco and Kuwait Oil Company expansion priorities. |
Study Parameters
Operator-level perspectives from subsea project engineers, petroleum reservoir managers, procurement leads at national oil companies, and subsea controls specialists anchored the qualitative base. Primary interviews with Schlumberger, Halliburton, and Baker Hughes technical directors combined with secondary validation through BSEE certification databases, Norway Petroleum Safety Authority filings, Petrobras pre-salt contract disclosures, and EPA methane regulation compliance timelines. Bottom-up unit deployment estimates across smart well architectures and downhole sensor arrays triangulated against top-down capital expenditure forecasts from operator budget disclosures.
Scenario-bracketing framed analytical approaches across the projection horizon, modeling intelligent completion demand through product type segmentation by pressure rating and temperature tolerance, technology segmentation by actuation mechanism and communication protocol, and application segmentation by intervention frequency requirements. CAGRs derived from regression analysis against deepwater project sanctioning rates and regulatory compliance retrofit schedules. Industry-specific forecast inputs incorporated high-nickel alloy price volatility indices and subsea controls engineering talent pipeline constraints.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories or offshore development cost inflation would shift the trajectory of deepwater sanctioning decisions and associated intelligent completion procurement. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Middle-East Enhanced Oil Recovery Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
North America Proppants Market
Oil & Gas
South America Oil and Gas Storage Tank Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
Tight Gas Market
Oil & Gas
Well Testing Services Market
Oil & Gas
Egypt Oil and Gas Market