
 Oil and Gas Electrification Market | 2026-2036
Oil and Gas Electrification Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Electrification Market Analysis
Project finance tied to emissions-reduction benchmarks is narrowing the field of viable competitors in offshore electrification. SLB Ltd. leverages its integrated technology portfolio to capture power-from-shore integration contracts. Chevron Corp. anchors its position through proprietary microgrid deployments at Gulf of Mexico production facilities. TotalEnergies differentiates via renewable-powered offshore platform pilots that reduce diesel dependency.
Oil and gas electrification encompasses the substitution of mechanical and thermal energy derived from combustion with electric power systems, typically operating at medium voltage (11-36 kV) for offshore distribution and incorporating variable frequency drives for compressor and pump loads. Its primary purpose is to eliminate onsite fossil fuel combustion, cut methane and CO2 emissions, and enable integration with lower-carbon grid or renewable sources. Power Supply services currently dominate contracted value, though Battery Storage installations are expanding fastest as operators seek spinning reserve replacement and peak shaving at remote facilities. Upstream electrification occupies the largest application share, while Grid Solutions command premium margins where subsea cable infrastructure links platforms to onshore renewable generation.
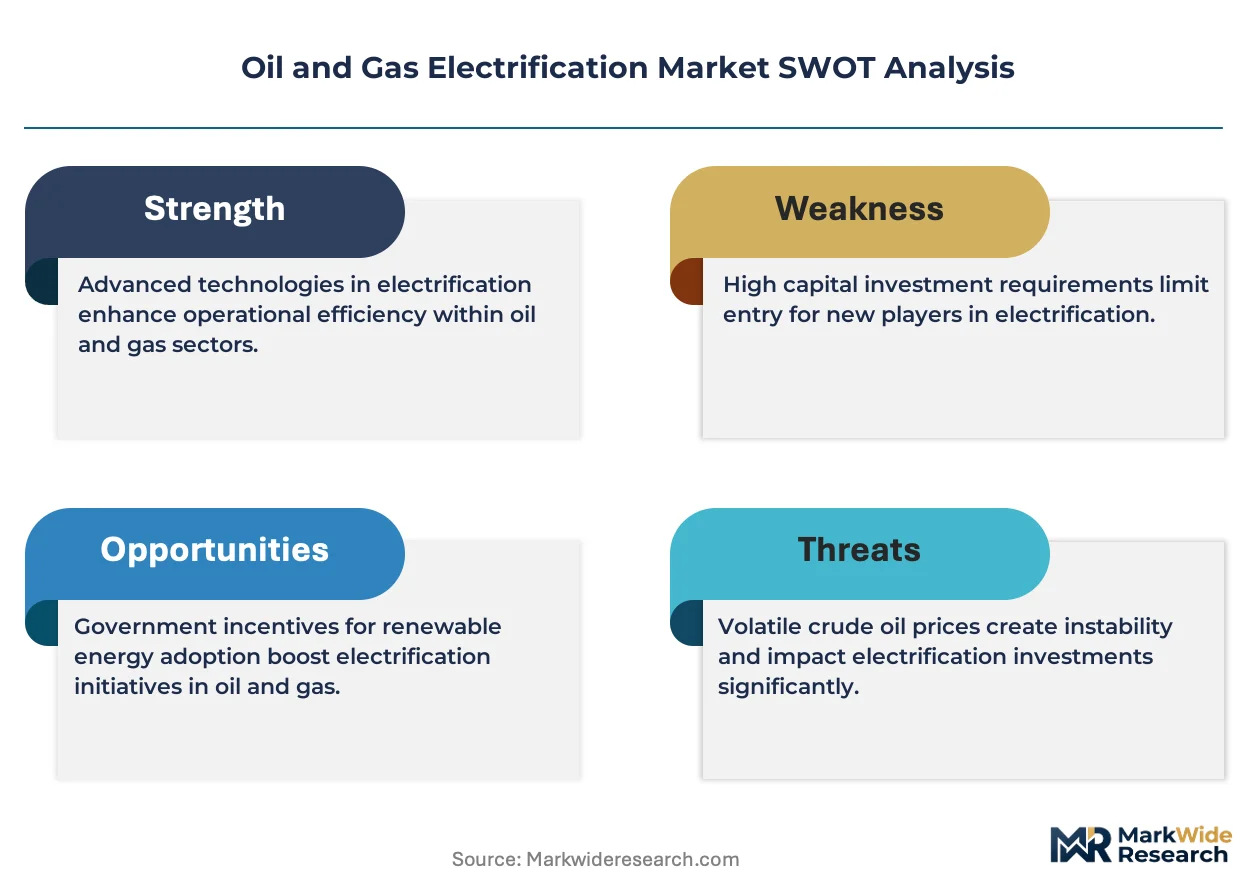
The EU F-Gas Regulation, Norway's petroleum regulator requirements for offshore emissions intensity, and the United Kingdom's North Sea Transition Deal collectively mandate progressive electrification of offshore assets and restrict new unmanned gas-turbine installations. These frameworks reshape procurement criteria, favoring vendors with certified grid-integration capabilities and documented lifecycle carbon accounting. Stakeholders must monitor evolving connection-queue priorities for offshore wind-to-platform power and assess whether captive renewable generation or shore-based grid access offers lower delivered cost per barrel equivalent.
Market Dynamics
Grid-connected offshore electrification is compressing the addressable market for localized gas-turbine generation as North Sea operators face binding emissions-intensity caps under Norway's petroleum regulator and the United Kingdom's North Sea Transition Deal.
Growth Catalysts
- EU F-Gas Regulation:Mandatory phase-out of high-global-warming-potential refrigerants in offshore HVAC and gas-compression systems forces platform operators toward electrically-driven heat pumps and sealed compressor architectures.
- Subsea cable infrastructure:Expanded high-voltage direct current links from onshore renewable generation clusters to offshore installations enable displacement of diesel and gas-turbine baseload power.
- Upstream electrification mandates:Norway's petroleum regulator now requires emissions-intensity benchmarking for new field developments, favoring projects with documented power-from-shore integration plans.
Market Restraints
- Copper and rare-earth price volatility:Medium-voltage switchgear and permanent-magnet motor supply chains face input cost pressure from concentrated Chinese processing capacity.
- Grid connection queue congestion:Offshore wind-to-platform interconnection requests in the United Kingdom face multi-year delays as transmission system operators prioritize larger offshore wind farms.
- Technical limitation in brownfield retrofit:Aging platform structural load limits constrain the added weight of battery storage enclosures and high-voltage transformer modules.
Strategic Opportunities
- Floating offshore wind-to-platform power:Norway's deepwater fields beyond fixed-foundation wind zones present first-mover opportunities for tethered floating wind arrays dedicated to single-platform supply.
- Electrification of well intervention vessels:Battery-hybrid offshore support vessels reduce diesel consumption during dynamic positioning operations at platform locations.
- United Kingdom carbon pricing floor:Escalating carbon cost under the UK ETS improves the relative economics of imported grid power versus onboard gas-turbine generation.
Industry Challenges
- High-voltage commissioning expertise shortage:Qualified technicians for 33 kV offshore switchgear energization and protection relay configuration remain scarce in the North Sea contractor pool.
- Legacy platform electrical load documentation:Incomplete as-built drawings from 1980s installations complicate accurate power-demand profiling for shore-connection sizing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Electrification Market |
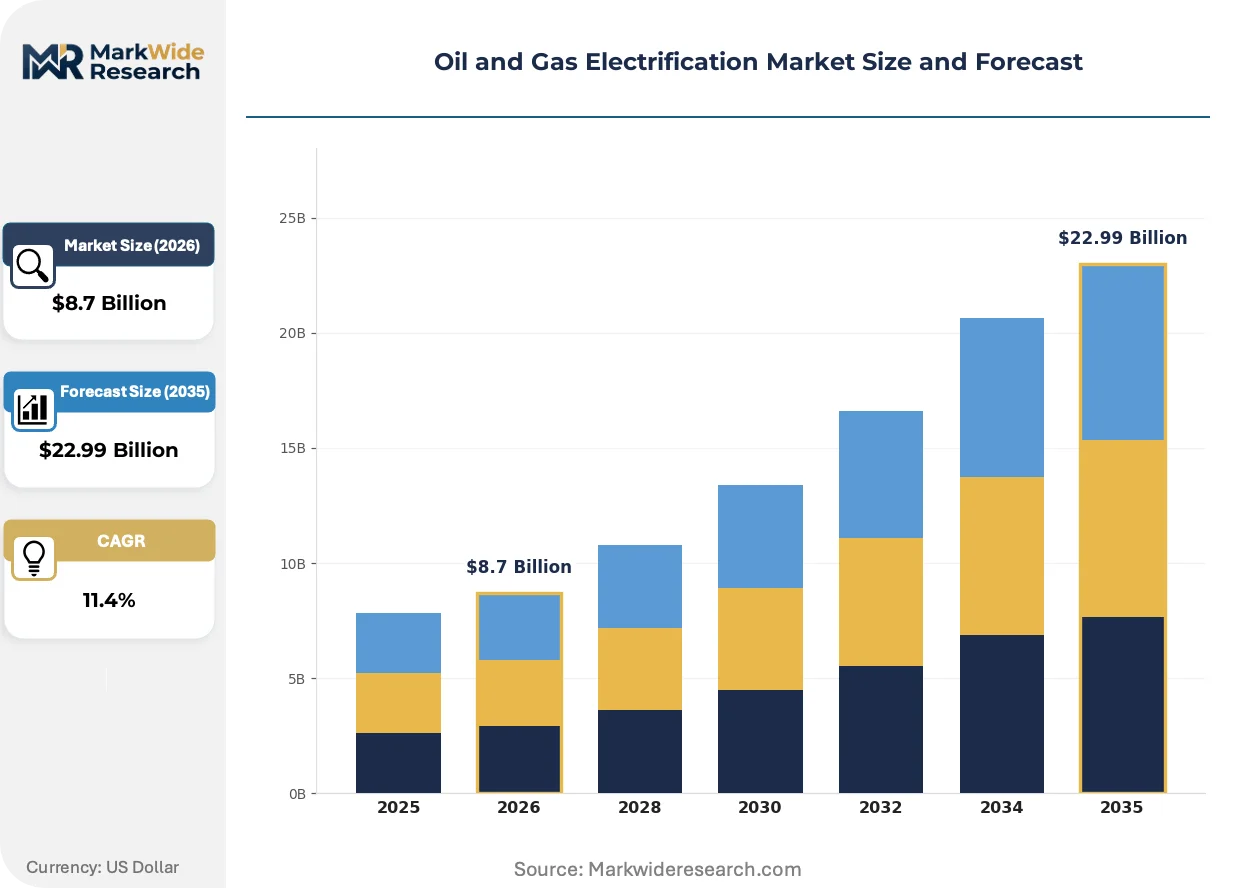
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Power Supply, Energy Management, Integration Services, Grid Solutions Application: Upstream, Midstream, Downstream, Refining Technology: Renewable Energy, Battery Storage, Microgrid, Smart Grids End User: Exploration Companies, Production Facilities, Distribution Networks, Oil Refineries |
| Companies Covered | Occidental Petroleum Corp., TotalEnergies, Exxon Mobil Corp., Cheniere Energy Inc., Williams Cos. Inc., Chevron Corp., SLB Ltd., ConocoPhillips, BP PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Electrification Market Emerging Trajectories
Electrification architectures are hybridizing multiple power sources as operators seek to eliminate single-fuel dependency while maintaining spinning reserve for safety-critical loads.
Variable frequency drive systems for large compressor and pump loads are hybridizing with battery energy storage to provide ride-through capability during grid voltage disturbances. Offshore platform operators in Norway are retrofitting existing motor control centers with integrated DC bus connections for lithium-ion modules. This hybridizing architecture reduces the required spinning reserve from gas turbines and enables deeper renewable penetration in power-from-shore configurations.
The United Kingdom's North Sea Transition Deal mandates measurable emissions-reduction pathways for existing producing assets, with electrification recognized as the primary compliance mechanism. Operators must submit electrification feasibility studies to the North Sea Transition Authority for license extensions beyond 2030. Platforms in the Central and Northern North Sea sectors face the most compressed timelines for grid-connection completion.
Integrated service contracting is displacing discrete equipment procurement as operators seek single-point accountability for power-system availability. Engineering-procurement-construction firms now bundle subsea cable installation, platform electrical upgrade, and long-term operations contracts. This bundling concentrates in the United Kingdom sector where project finance tied to emissions benchmarks requires lifecycle performance guarantees.
Oil and Gas Electrification Market Segmentation
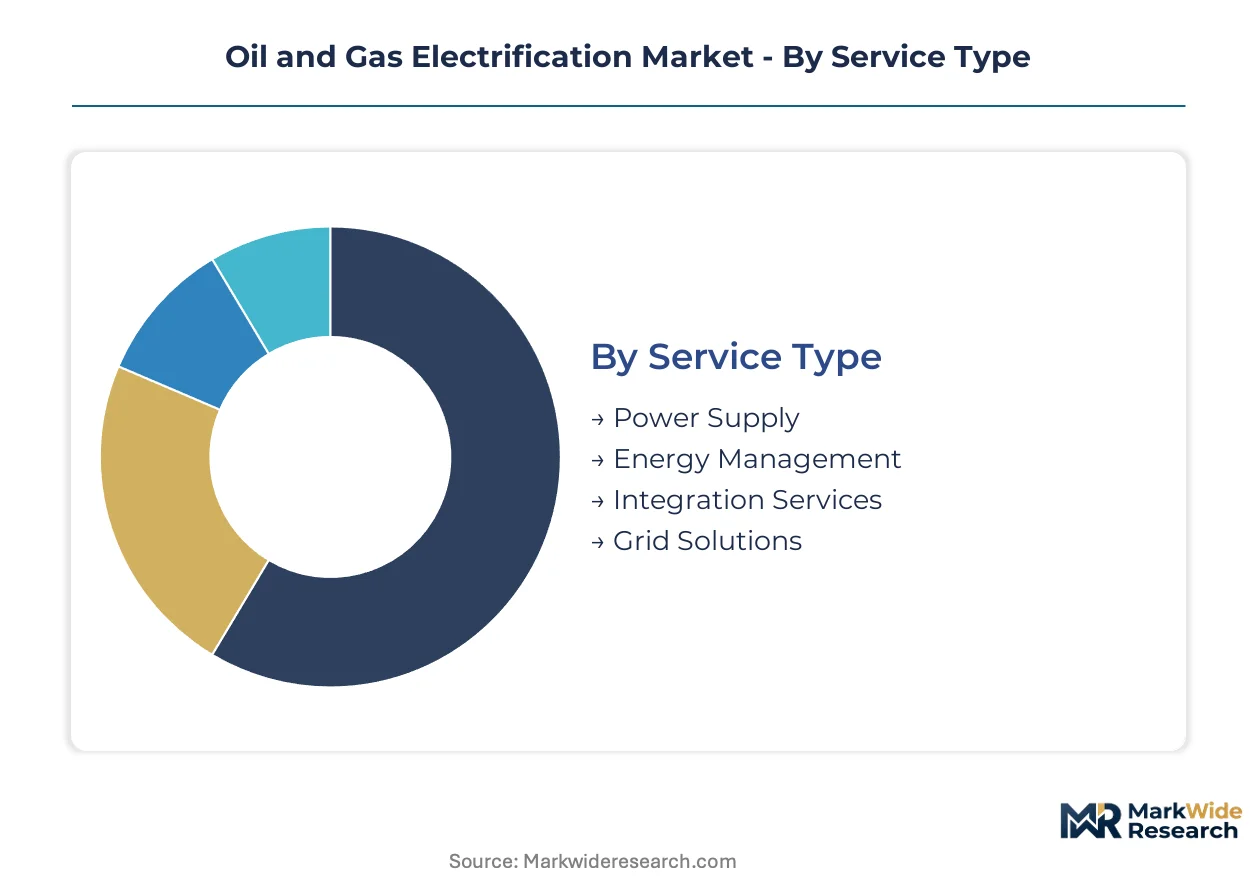
Electrification procurement patterns diverge sharply across service tiers, facility types, and technology readiness levels. Understanding where capital concentrates versus where pilot budgets flow clarifies vendor positioning and partnership priorities.
Service Type:
Cost tier determines contract structure, with bundled lifecycle agreements commanding premium pricing over discrete equipment supply.
- Power Supply:Medium-voltage distribution infrastructure (11-36 kV switchgear, transformers, subsea cables) delivering shore-based or renewable generation to platform loads. Norwegian North Sea developments under emissions-intensity mandates drive contract concentration here, with integrated power-from-shore packages replacing localized gas-turbine baseload.
- Energy Management:Load forecasting, demand-response orchestration, and real-time optimization platforms that synchronize variable renewable injection with compressor and pump duty cycles. UK offshore installations facing North Sea Transition Deal deadlines concentrate procurement of these software-layer services to maximize grid-import utilization.
- Integration Services:Engineering-procurement-construction management for brownfield electrical retrofits.
- Grid Solutions:High-voltage direct current links and reactive power compensation for long-distance transmission.
Power Supply commands the established base. The steepest expansion runs through Energy Management.
Application:
Facility lifecycle stage dictates electrification architecture, with greenfield developments integrating electric drive from design versus brownfield retrofits constrained by structural load limits.
- Upstream:Offshore production platforms and subsea processing facilities where electric submersible pumps, electrically-actuated Christmas trees, and power-from-shore connections eliminate diesel and gas-turbine combustion. Norway's petroleum regulator emissions benchmarks accelerate investment here, particularly at Johan Sverdrup and similar grid-linked developments.
- Downstream:Refinery and petrochemical complex electrification of fired heaters, compressors, and cracking units. EU F-Gas Regulation phase-out of high-global-warming-potential refrigerants drives electrically-driven heat pump adoption at Rotterdam and Antwerp corridor facilities.
- Midstream:Pipeline compressor stations and storage terminal electrification.
- Refining:Distillation unit electric heater replacement and cogeneration displacement.
Upstream anchors capital deployment. Downstream exhibits the fastest technology refresh cycle.
Technology:
Maturity gradient separates proven grid-connection solutions from emerging hybrid architectures still in pilot validation.
- Battery Storage:Lithium-ion modules integrated at platform motor control centers to provide spinning reserve replacement, voltage ride-through, and peak shaving that reduces gas-turbine runtime. Norwegian operators retrofitting 1980s installations concentrate demand here as weight-constrained platforms seek maximum emissions reduction per kilogram added.
- Microgrid:Islandable power systems combining diesel, battery, and renewable generation with synchronized control for remote facilities without shore connection. Gulf of Mexico independent producers deploy these at unmanned platforms where grid extension remains uneconomic.
- Renewable Energy:Offshore wind, solar, and hybrid renewable generation dedicated to platform supply.
- Smart Grids:Digitalized distribution with predictive maintenance and automated fault isolation.
Microgrid holds the installed base. Battery Storage is climbing the fastest.
End User:
Customer scale and regulatory exposure determine procurement sophistication, with integrated majors driving standards that tier-2 operators later adopt.
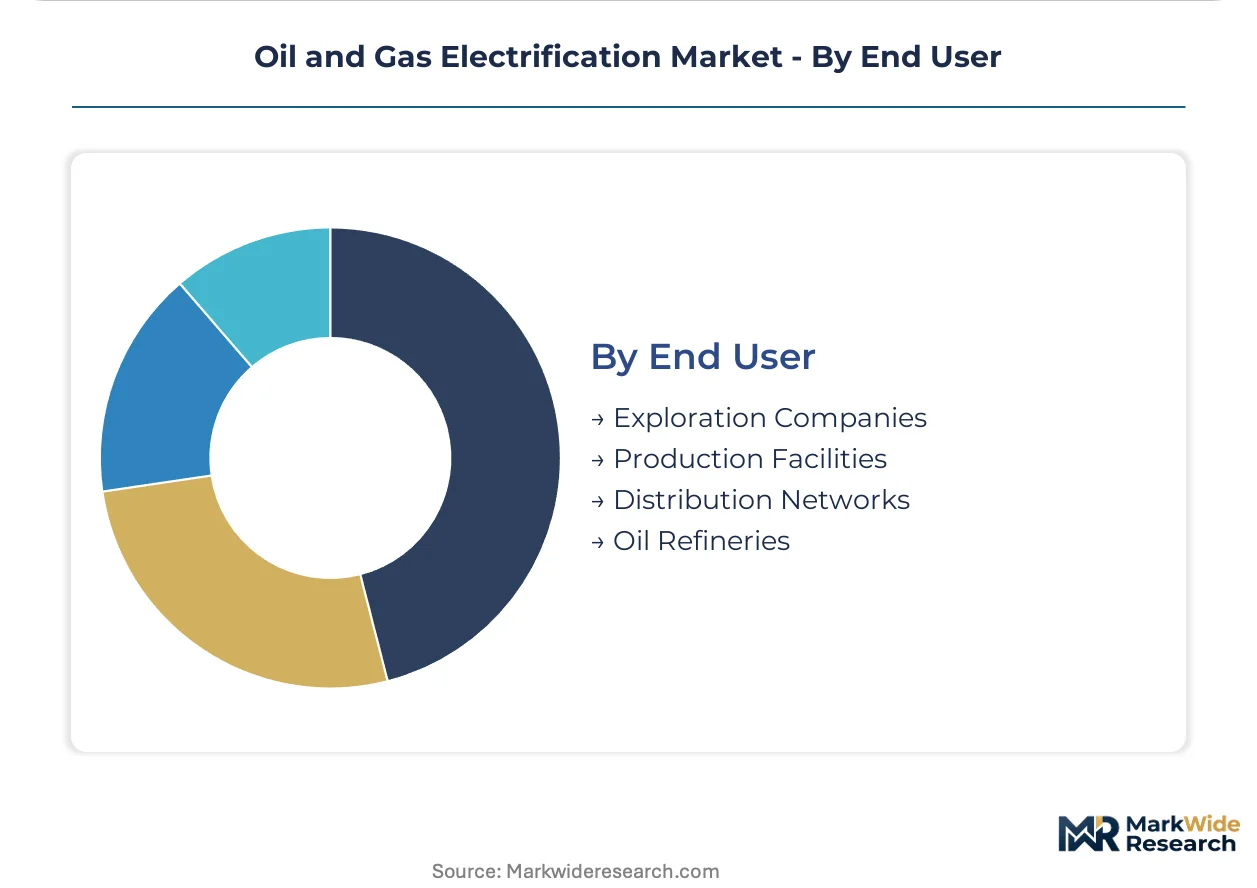
- Production Facilities:Manned and unmanned offshore platforms, onshore processing plants, and integrated production hubs with dedicated electrical engineering teams capable of managing complex power-from-shore integration. UK and Norwegian operators facing binding emissions-intensity caps concentrate electrification procurement here.
- Exploration Companies:Early-phase field developers evaluating electrification feasibility during front-end engineering design to secure license extensions and project finance tied to emissions benchmarks.
- Oil Refineries:Downstream processing complexes with continuous-duty electrical loads and carbon pricing exposure.
- Distribution Networks:Pipeline and terminal operators with dispersed, lower-power electrification requirements.
Production Facilities represent the core revenue pool. Exploration Companies are gaining share fastest as pre-sanction project pipelines electrify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's petroleum regulator emissions-intensity benchmarks and the United Kingdom's North Sea Transition Deal are redirecting capital toward grid-connected offshore platforms. These frameworks compress project timelines and reshape vendor qualification criteria across the North Sea basin.
Norway
Johan Sverdrup and similar grid-linked developments anchor North Sea electrification investment. The country's petroleum regulator mandates emissions-intensity benchmarking for all new field developments. Stavanger-based engineering clusters concentrate power-from-shore integration expertise.
United Kingdom
Central and Northern North Sea platforms face compressed timelines for grid-connection completion before 2030 license extensions. The North Sea Transition Authority requires electrification feasibility studies for continued operations. Aberdeen engineering centers coordinate bundled EPC contracts tying project finance to emissions benchmarks.
United States
Gulf of Mexico independent producers deploy microgrids at unmanned platforms where shore connection remains uneconomic. EPA offshore emissions guidelines and state-level carbon pricing in California influence procurement priorities. Houston-headquartered operators anchor proprietary microgrid deployments across deepwater production facilities.
Netherlands
Rotterdam-Antwerp corridor refineries electrify fired heaters and cracking units under EU F-Gas Regulation refrigerant phase-out mandates. The country's national energy regulator prioritizes grid connection queues for industrial decarbonization projects. Eindhoven-region electrical engineering firms supply medium-voltage switchgear for platform retrofits.
Brazil
Pre-salt field operators evaluate floating offshore wind-to-platform architectures for deepwater developments beyond fixed-foundation zones. ANP regulatory frameworks for offshore emissions monitoring shape front-end engineering design requirements. Rio de Janeiro engineering clusters pilot tethered renewable arrays for single-platform supply.
Oil and Gas Electrification Market Vendor Landscape
On the supply side, the industry is consolidating around integrated technology portfolios capable of delivering bundled lifecycle performance guarantees. Tier-1 vendors capture power-from-shore integration contracts through documented grid-connection expertise, while specialized engineering firms compete on brownfield retrofit execution speed. Two strategic archetypes dominate: integrated oilfield service conglomerates with subsea cable installation capabilities, and renewable-energy engineering specialists with offshore wind interconnection experience. Competitive intensity centers on M&A activity targeting high-voltage commissioning expertise and strategic partnerships linking battery storage vendors with platform electrical upgrade contractors.
Within the integrated service tier, SLB Ltd. and Chevron Corp. exemplify divergent electrification strategies. SLB Ltd. leverages its technology portfolio to anchor power-from-shore integration contracts requiring single-point accountability. Chevron Corp. occupies a position emphasizing proprietary microgrid deployments at production facilities where grid extension remains uneconomic. TotalEnergies represents the renewable-powered platform pilot archetype, reducing diesel dependency through offshore wind-to-platform architectures. These three entities collectively illustrate how vendor positioning stratifies across grid-connected versus islanded electrification pathways.
| Leading Market Players |
|---|
| Occidental Petroleum Corp. |
| TotalEnergies |
| Exxon Mobil Corp. |
| Cheniere Energy Inc. |
| Williams Cos. Inc. |
| Chevron Corp. |
| SLB Ltd. |
| ConocoPhillips |
| BP PLC |
| Others |
Supply Flow & Price Mechanics
Chinese rare-earth processing concentration for permanent-magnet motors and copper smelting capacity anchors upstream cost structures, directing margin capture toward integrated vendors with captive high-voltage switchgear production and documented grid-connection track records in the North Sea.
Pricing Analysis
Certification level for offshore electrical equipment creates the primary spread between premium and standard tiers. Project-based contracting dominates, with lifecycle performance guarantees commanding substantial premiums over discrete equipment supply. Price differentiation rests on documented grid-integration capabilities and emissions-accounting transparency. Cost compression in battery storage modules is intensifying because of lithium carbonate oversupply, though high-voltage commissioning expertise retains pricing power. Exploration companies facing pre-sanction deadlines exhibit highest price sensitivity, while Norwegian majors under binding emissions caps prioritize availability over unit cost.
Supply Chain Analysis
Copper cathode feedstock draws from Chilean and Indonesian smelting capacity, with rare-earth oxide separation concentrated in Chinese processing facilities. Permanent-magnet motors, medium-voltage switchgear, and subsea cable insulation compounds constitute critical component dependencies. Single-source vulnerability in dysprosium and terbium separation creates structural risk for variable-frequency drive manufacturers. Distribution runs through engineering-procurement-construction contractors bundling installation with long-term operations contracts, particularly in the United Kingdom sector where project finance requires single-point accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Norway's petroleum regulator and the United Kingdom's North Sea Transition Authority have created switching costs that favor incumbents with documented compliance histories and established grid-interconnection relationships.
For Market Incumbents: Insulate market position by deepening captive high-voltage commissioning capabilities through targeted capability acquisition in the Aberdeen-Stavanger engineering corridor. Secure long-term offtake agreements for copper and rare-earth feedstocks before commodity volatility resurges. Emerging renewable-energy engineering specialists with offshore wind interconnection experience represent the primary competitive threat to traditional oilfield service positioning.
For New Entrants and Emerging Players: Establish a beachhead in floating offshore wind-to-platform power architectures for Norway's deepwater developments beyond fixed-foundation zones. Target electrification feasibility study contracts for United Kingdom exploration companies seeking license extensions under North Sea Transition Deal deadlines. Battery-hybrid well intervention vessel retrofits offer a penetrable entry point with lower capital intensity than platform-scale integration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed electrical engineering firms holding North Sea grid-connection expertise but lacking balance sheet scale for integrated EPC contracting. Long-term viability centers on regulatory compliance service revenues rather than equipment margins. Watch offshore wind-to-platform interconnection queue priority shifts as the inflection signal for vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Power-from-Shore Integration | Captures premium margins in Norwegian developments under emissions-intensity mandates. |
| Battery Storage Retrofit | Enables spinning reserve replacement at aging platforms with structural load constraints. |
| Floating Wind-to-Platform Pilot | Opens deepwater Norway fields beyond fixed-foundation wind zones to renewable supply. |
| High-Voltage Commissioning Acquisition | Addresses acute technician scarcity for 33 kV offshore switchgear energization. |
| Lifecycle Performance Guarantee | Satisfies project finance requirements tied to emissions-reduction benchmarks in UK sector. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, project development databases, and commodity trade data. Primary interviews engaged platform electrical engineers, EPC procurement leads, offshore wind project developers, and transmission system operator planning officers. Secondary sources included Norway's petroleum regulator emissions reports, United Kingdom North Sea Transition Authority licensing records, and subsea cable installation contractor disclosures. Bottom-up project pipeline assessment triangulated against top-down market sizing from equipment supplier revenue aggregation.
Forecast inputs incorporate service type segmentation across power supply, energy management, integration services, and grid solutions, alongside technology tiers spanning battery storage, microgrid, renewable energy, and smart grid architectures. Application splits between upstream, downstream, midstream, and refining dictate differential electrification investment trajectories. CAGRs derive from project sanctioning timelines, regulatory compliance deadlines, and grid-connection queue progression. Offshore wind capacity buildout rates and carbon pricing floor escalation curves inform power-from-shore adoption modeling.
Sensitivities concentrate around rare-earth export restriction scenarios, subsea cable manufacturing capacity constraints, and offshore wind interconnection priority shifts. Forecasts reflect documented project pipelines and disclosed regulatory frameworks rather than speculative technology breakthroughs. Cross-checking against IEA offshore energy investment benchmarks and national regulator electrification progress reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Well Test Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Oil and Gas Downhole Cables Market