
 North and South America Mineral Supplement Tablets Market | 2026-2036
North and South America Mineral Supplement Tablets Market Size, Share, and Industry Trends Forecast 2026-2036
North and South America Mineral Supplement Tablets Market Intelligence
Aftermarket service revenue in personalized nutrition counseling is fragmenting across the value chain as brands compete for recurring consumer relationships. Bayer leverages its pharmaceutical heritage to sustain premium positioning in clinical-grade mineral formulations. Nature's Bounty Co. anchors its North American presence through broad retail distribution and private-label partnerships. NOW Foods specializes in clean-label mineral tablets, competing on transparency and third-party certifications.
North and South America mineral supplement tablets are solid oral dosage forms containing one or more essential minerals in defined elemental amounts, typically manufactured through direct compression or wet granulation to achieve specified dissolution profiles and tablet hardness. These products serve preventive health maintenance, addressing documented dietary gaps in calcium, magnesium, iron, and zinc across diverse population cohorts. The adult end-user segment occupies the largest volume share, reflecting sustained preventive health expenditure among working-age consumers, while the online retail distribution channel is accelerating fastest as pharmacy-adjacent platforms capture subscription-driven replenishment cycles. Calcium tablets lead product-type revenue due to established osteoporosis prevention protocols, though iron formulations for prenatal applications command higher per-unit margins.
FDA cGMP regulations and USP dietary supplement verification programs govern manufacturing quality and label accuracy across the United States, while Brazil's ANVISA imposes parallel stability and bioavailability requirements that shape import compliance costs. Health Canada and PMRA standards in the Canadian market add another certification layer for cross-border suppliers. Stakeholders must monitor evolving monograph updates from USP and potential harmonization pressures between FDA and Latin American regulators to anticipate reformulation investments and market access timelines.
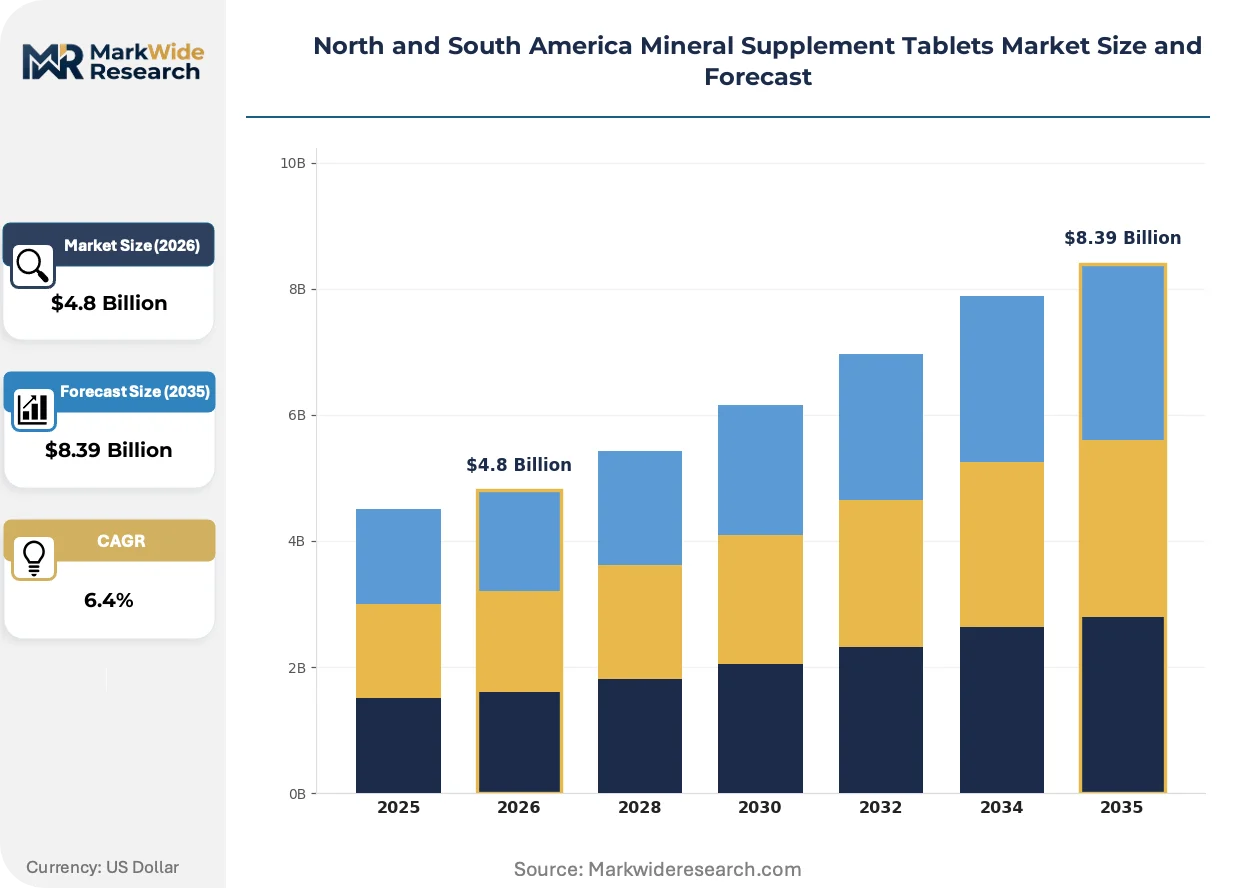
Market Dynamics
FDA cGMP enforcement and USP verification standards are compressing manufacturing margins while elevating quality barriers, forcing reformulation investments across North and South American production facilities. This regulatory tightening intersects with raw material concentration in specific mineral supply corridors, reshaping competitive positioning toward vertically integrated players.
Growth Catalysts
- Senior nutrition programs:Brazil's federally funded elder-care initiatives expand mineral tablet distribution through public health networks, creating institutional demand channels.
- Pharmacy-adjacent platforms:Subscription-driven replenishment cycles through online retail accelerate consumer lock-in and recurring revenue capture.
- USP verification programs:Third-party certification adoption by major retailers elevates consumer trust premiums and shelf placement priority.
Market Restraints
- Excipient cost volatility:Microcrystalline cellulose and magnesium stearate prices fluctuate with pharmaceutical sector demand, compressing tablet manufacturing margins.
- Import compliance costs:Brazil's ANVISA stability and bioavailability requirements create documentation burdens for North American suppliers entering Latin American markets.
- Elemental iron substitution:Liquid mineral formulations and functional food fortification capture prenatal and pediatric segments previously served by tablets.
Strategic Opportunities
- Mexico metropolitan corridors:Guadalajara and Monterrey health clusters show underpenetrated pharmacy distribution relative to per-capita supplement expenditure.
- Clean-label convergence:Non-GMO and allergen-free mineral tablets command retail premiums as third-party certifications reshape shelf differentiation.
- Telehealth integration:Remote diagnostic platforms in the United States create prescription-adjacent mineral recommendation pathways.
Industry Challenges
- Formulation scientist scarcity:Wet granulation and direct compression expertise concentrates among legacy pharmaceutical contractors, limiting in-house capability buildout.
- Cross-border certification timelines:Health Canada and PMRA parallel review processes delay product launches by 8-14 months for US-based manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North and South America Mineral Supplement Tablets Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium, Magnesium, Iron, Zinc End User: Adults, Children, Athletes, Seniors Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Food Stores Formulation: Tablets, Capsules, Powders, Gummies |
| Companies Covered | Pfizer, Bayer, Nature’s Bounty Co., GNC Holdings, Abbott Laboratories, NOW Foods, Amway Corp, Herbalife International of America, Nature Made, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North and South America Mineral Supplement Tablets Market Strategic Shifts & Innovations
Tablet manufacturing is migrating toward continuous processing technologies that compress batch cycle times and reduce in-process material waste. This shift intersects with evolving USP dissolution testing protocols and changing retail channel power structures.
Continuous manufacturing is migrating from pilot-scale pharmaceutical applications into mid-volume mineral supplement production. Contract manufacturers in the United States adopt twin-screw granulation and direct compression lines to serve private-label brands demanding shorter lead times. This technology is migrating from batch-dependent quality control toward real-time release testing, compressing inventory holding costs and enabling just-in-time supply to pharmacy chains.
FDA's evolving dietary supplement cGMP guidance on elemental impurity limits tightens acceptable lead, arsenic, and cadmium thresholds in mineral raw materials. Manufacturers must source certified-low-toxicity mineral salts or invest in additional purification steps. Calcium carbonate and magnesium oxide suppliers serving the US market face the steepest compliance investments, with some reformulating toward citrate and glycinate chelates that naturally carry lower heavy metal burdens.
Subscription replenishment models are displacing sporadic retail purchasing among working-age preventive health consumers. Pharmacy-adjacent platforms and specialized supplement e-commerce sites capture auto-ship commitments that reduce customer acquisition costs and improve lifetime value metrics. This behavioral shift concentrates demand volume in the United States and Canadian urban corridors where same-day or next-day delivery infrastructure supports just-in-time consumption patterns.
North and South America Mineral Supplement Tablets Market Segmentation
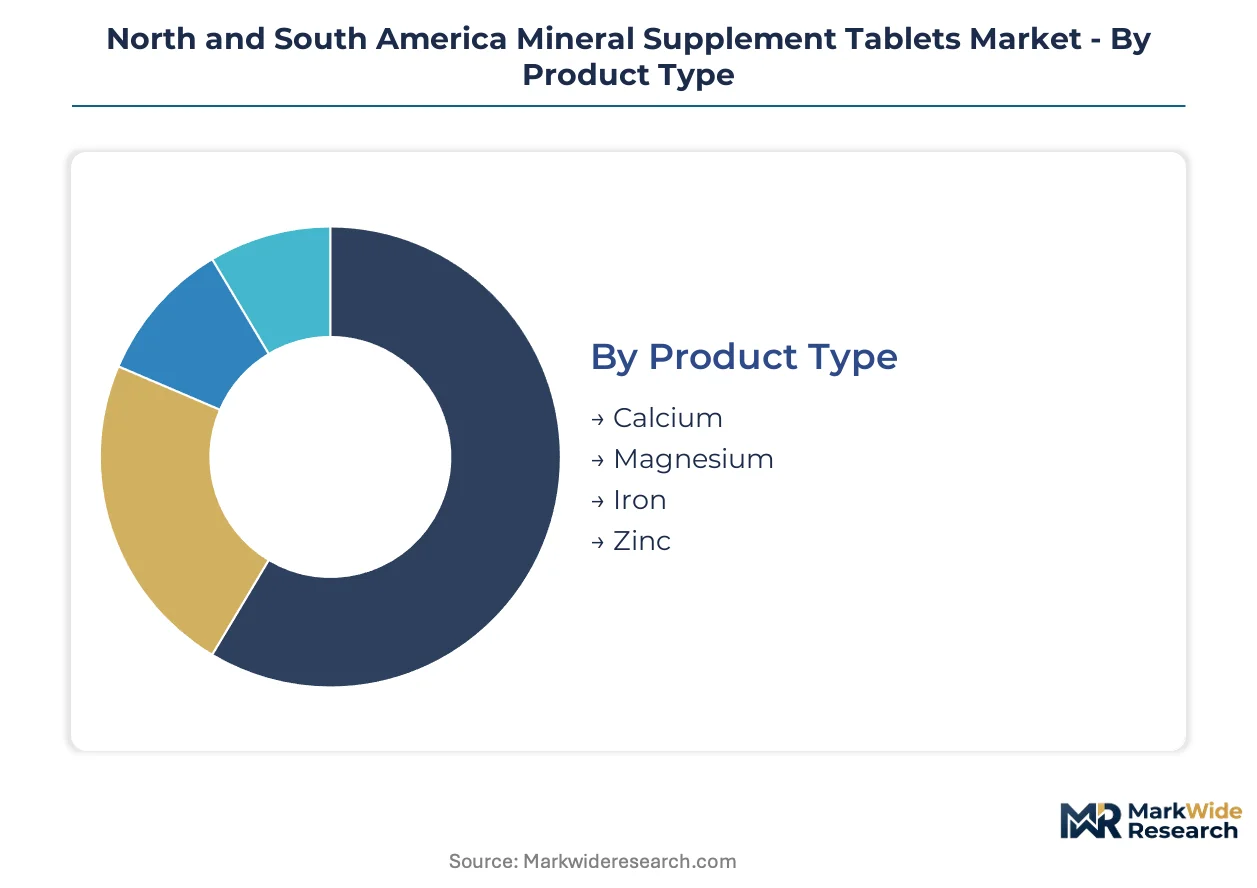
Segmentation in the North and South America mineral supplement tablets market reveals how formulation choices, channel strategies, and demographic targeting separate premium clinical-grade products from mass-market alternatives. Manufacturers align R&D investment and certification pathways with specific segment durability requirements and margin profiles.
Product Type:
Mature formulations dominate prescription-adjacent channels, while emerging mineral combinations capture functional wellness positioning.
- Calcium:Carbonate and citrate salts formulated for bone density maintenance occupy the largest production volume across North American facilities. Demand concentrates in United States metropolitan health corridors where osteoporosis screening protocols drive physician recommendations alongside pharmacy-adjacent subscription platforms.
- Magnesium:Oxide, glycinate, and malate variants address sleep quality and muscle recovery applications with higher per-unit margins than commodity minerals. Brazilian senior nutrition programs distribute magnesium oxide tablets through public health networks, creating institutional procurement volumes distinct from retail channels.
- Iron:Ferrous sulfate and bisglycinate formulations serve prenatal and anemia correction protocols with stringent heavy metal testing requirements under FDA cGMP guidance.
- Zinc:Gluconate and picolinate tablets target immune support positioning, competing with lozenge and liquid delivery formats in pediatric and athletic segments.
Calcium retains volume leadership; magnesium holds the steepest expansion curve.
End User:
Customer type segmentation separates preventive maintenance expenditure from condition-specific therapeutic use, with channel strategy diverging accordingly.
- Adults:Working-age consumers aged 25-55 drive subscription replenishment cycles through online retail, with auto-ship commitments reducing customer acquisition costs for pharmacy-adjacent platforms.
- Seniors:Federally funded elder-care initiatives in Brazil expand mineral tablet distribution through institutional procurement, while United States Medicare Advantage plans increasingly cover clinically verified formulations.
- Athletes:Magnesium and zinc combinations target recovery and immune resilience, competing with sports nutrition powders and functional beverages for share of supplementation wallet.
- Children:Iron and zinc requirements for developmental support face substitution pressure from gummy formats and fortified food products, compressing tablet volume in pediatric segments.
Adults command the largest revenue base; seniors are climbing the fastest as population aging accelerates across both continents.
Distribution Channel:
Channel power has shifted toward platforms controlling replenishment data and same-day fulfillment infrastructure.
- Online Retail:Pharmacy-adjacent platforms and specialized supplement e-commerce sites capture auto-ship commitments with next-day delivery in United States and Canadian urban corridors. Subscription models reduce churn through just-in-time consumption pattern alignment.
- Pharmacies:Chain drugstores and independent pharmacies retain clinical credibility for first-time mineral purchases, though replenishment volume migrates online. USP verification seals determine shelf placement priority in this channel.
- Supermarkets:Mass-market mineral tablets compete on price-per-unit with limited clinical positioning, facing margin compression from private-label expansion.
- Health Food Stores:Clean-label and third-party certified products command retail premiums, with non-GMO and allergen-free positioning differentiating assortment from conventional retail.
Online retail is gaining share fastest; pharmacies defend the highest-margin initial purchase occasions.
Formulation:
Format competition reflects consumer preference for convenience, taste masking, and perceived absorption efficiency.
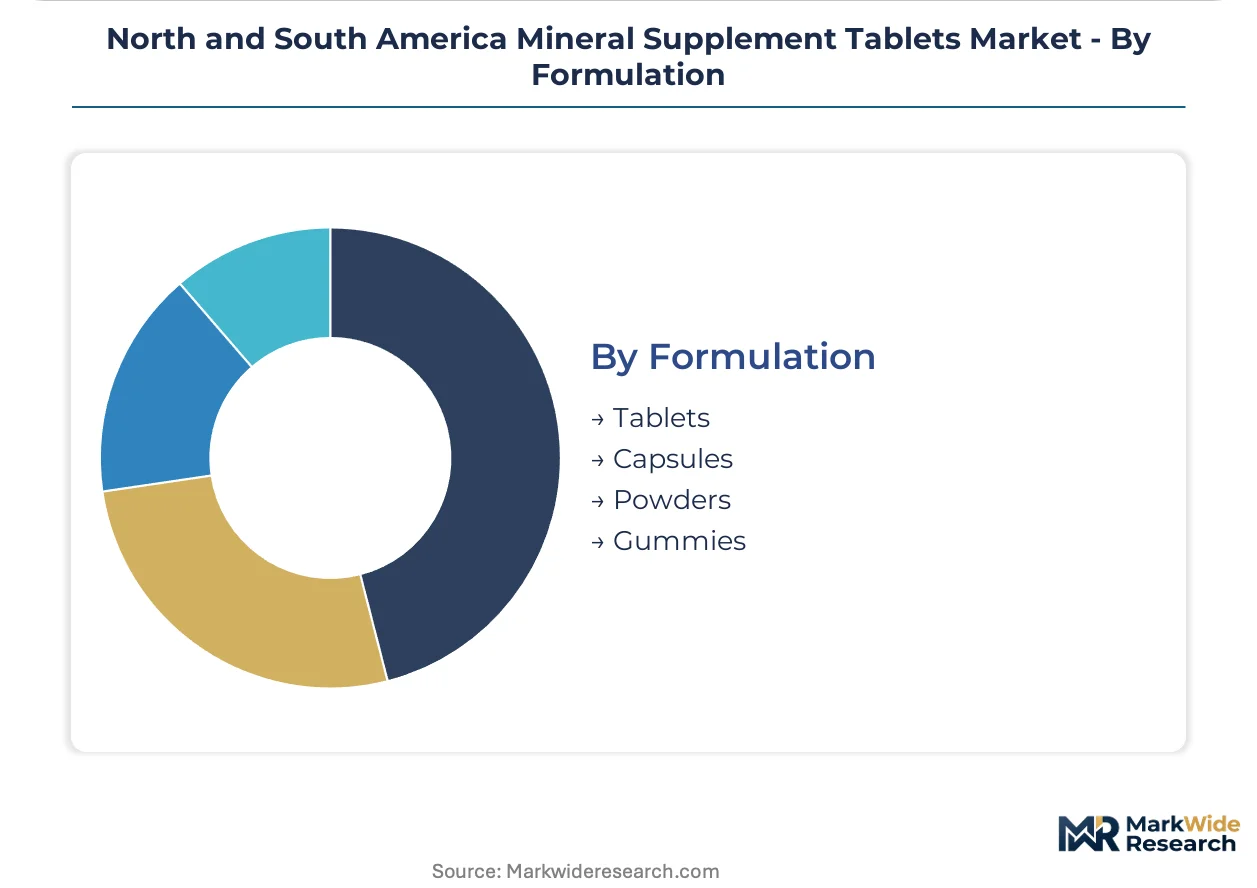
- Tablets:Direct compression and wet granulation manufacturing achieves specified dissolution profiles with lowest unit cost, dominating calcium and magnesium volume production.
- Capsules:Gelatin and vegetable cellulose shells accommodate mineral combinations and sensitive ingredients, capturing premium positioning in United States functional wellness segments.
- Powders:Bulk mineral salts allow dose customization, competing in athletic and clinical nutrition applications where tablet size limits intake.
- Gummies:Sugar-alcohol and pectin-based matrices displace tablets in pediatric and senior compliance-challenged segments, though mineral stability and bioavailability testing requirements add formulation complexity.
Tablets maintain cost leadership; gummies show the steepest trajectory as taste-driven compliance gains priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North and South America diverge sharply by channel preference and institutional procurement intensity. The United States drives subscription-based replenishment through pharmacy-adjacent platforms, while Brazil's federally funded senior nutrition programs create bulk institutional demand distinct from retail channels. Mexico and Canada occupy intermediate positions with hybrid public-private distribution models.
United States
Working-age adults aged 25-55 dominate preventive health expenditure through auto-ship commitments on pharmacy-adjacent platforms. FDA cGMP enforcement and USP verification programs elevate quality barriers and compress manufacturing margins. Demand concentrates in metropolitan health corridors including Greater New York, Los Angeles Basin, and Chicago Metro where same-day delivery infrastructure supports just-in-time consumption.
Brazil
Federally funded elder-care initiatives expand mineral tablet distribution through public health networks, creating institutional procurement volumes. ANVISA imposes parallel stability and bioavailability requirements that shape import compliance costs for North American suppliers. São Paulo and Rio de Janeiro anchor manufacturing and distribution infrastructure, with emerging demand clusters in Belo Horizonte and Porto Alegre.
Mexico
Metropolitan health corridors in Guadalajara and Monterrey show underpenetrated pharmacy distribution relative to per-capita supplement expenditure. COFEPRIS regulatory alignment with FDA standards facilitates cross-border supply chains from United States contract manufacturers. Mexico City Metro serves as the primary logistics hub for domestic distribution and re-export to Central American markets.
Canada
Health Canada and PMRA standards add certification layers that delay product launches by 8-14 months for United States-based manufacturers. Ontario and Quebec house the majority of domestic formulation capacity, with British Columbia showing fastest subscription platform adoption. Cross-border e-commerce channels capture replenishment volume from consumers seeking United States product variety.
North and South America Mineral Supplement Tablets Market Key Industry Players
Capability concentration sits with pharmaceutical heritage players; scale advantage sits with broad retail distributors. The market structures around three tiers: clinical-grade formulators with USP verification, mass-market brands with private-label partnerships, and clean-label specialists competing on third-party certifications. Dominant competitive moves include backward integration into mineral salt sourcing and strategic partnerships with subscription platform operators.
Within the pharmaceutical heritage tier, Bayer leverages its clinical formulation expertise to sustain premium positioning. Nature's Bounty Co. anchors mass-market scale through broad retail distribution networks. NOW Foods exemplifies the clean-label specialist archetype, competing on transparency certifications and non-GMO positioning. These three players represent distinct capability vectors reshaping competitive dynamics.
| Leading Market Players |
|---|
| Pfizer |
| Bayer |
| Nature's Bounty Co. |
| GNC Holdings |
| Abbott Laboratories |
| NOW Foods |
| Amway Corp |
| Herbalife International of America |
| Nature Made |
| Others |
Cost & Logistics Intelligence
ANVISA stability documentation requirements for Brazil-bound shipments compress contract-structure flexibility for North American suppliers, forcing longer-term offtake commitments that widen pricing spreads between verified and unverified mineral salt tiers while concentrating procurement decisions among vertically integrated formulators with captive regulatory affairs capacity.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement for Brazil's senior nutrition programs, while spot purchasing persists in United States health food retail. Three-tier pricing structure across USP-verified, retailer-certified, and unverified mineral tablets separates clinical-grade premiums from mass-market compression. Pricing pressure stems from excipient cost volatility as microcrystalline cellulose and magnesium stearate compete with pharmaceutical sector demand. Working-age subscription buyers show lowest price sensitivity; supermarket private-label shoppers exhibit highest elasticity.
Supply Chain Analysis
Upstream mineral salt production concentrates in China, India, and domestic United States facilities for calcium carbonate and magnesium oxide. Wet granulation expertise draws from legacy pharmaceutical contractors in New Jersey and North Carolina. Single-source vulnerability runs through certified-low-toxicity mineral salt suppliers facing FDA cGMP elemental impurity thresholds. Distribution runs through pharmacy-adjacent platforms capturing auto-ship replenishment in metropolitan United States corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pharmacy-adjacent platforms and subscription operators, fragmenting brand relationships and forcing suppliers to trade margin for volume commitments.
For Market Incumbents: Harden USP verification moats against clean-label specialists by accelerating third-party certification adoption across retail pharmacy networks. Deepen backward integration into mineral salt sourcing to offset excipient volatility and ANVISA documentation burdens. Lock in 3-5 year offtake agreements with Brazil's federally funded elder-care distributors before new entrants secure institutional shelf space. For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure targeting magnesium and zinc combinations in United States metropolitan health corridors underserved by same-day delivery. Mexico's Guadalajara and Monterrey pharmacy clusters offer white-space penetration with COFEPRIS-aligned import pathways. Lead with telehealth-integrated mineral recommendations to bypass incumbent retail shelf dominance. For Investors and Strategic Acquirers: FDA's evolving cGMP guidance on elemental impurities reshapes the acquisition landscape toward mineral salt purifiers with certified-low-toxicity supply contracts. Five-to-ten year viability favors formulators with continuous manufacturing capability and real-time release testing infrastructure. Watch for ANVISA-Brazilian Health Regulatory Agency harmonization signals as the inflection indicator for Latin American market access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Program Adoption | Retailer shelf placement priority at CVS and Walgreens hinges on third-party certification seals. |
| Continuous Manufacturing Scale-Up | Twin-screw granulation adoption by United States contract manufacturers compresses private-label lead times. |
| Telehealth Platform Partnership | Remote diagnostic integration with Hims and Roman creates prescription-adjacent mineral recommendation pathways. |
| Backward Integration into Mineral Salts | Captive citrate and glycinate chelate production hedges FDA cGMP elemental impurity compliance costs. |
| Subscription Replenishment Infrastructure | Auto-ship commitments through Amazon Pharmacy and Thrive Market reduce customer acquisition costs. |
Research Approach
Operator-level perspectives from formulation scientists at contract manufacturers, regulatory affairs directors at supplement brands, pharmacy procurement managers at chain drugstores, and subscription platform operators anchored the qualitative base. Secondary validation drew from FDA cGMP guidance documents, USP dietary supplement monographs, ANVISA stability protocols, Health Canada Natural Health Product regulations, and customs import data for mineral salt trade flows. Bottom-up volume estimates triangulated against top-down expenditure benchmarks from national health accounts.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated regulatory enforcement trajectories over the analysis window. Segmentation modeling incorporated product type, end-user cohort, distribution channel, and formulation format dimensions. CAGRs derived from mineral-specific consumption elasticity coefficients applied to demographic and expenditure trend inputs. Iron substitution risk from liquid formulations and functional food fortification informed prenatal segment trajectory bounds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated pharmaceutical heritage players or telehealth-integrated direct-to-consumer entrants would shift outcomes. Cross-checking against Nielsen retail audit data and IQVIA consumer health expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Calcium Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Fat Powders Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Tongkat Ali Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
Vegetable Capsules Market
Nutritional Supplements
Sleep Gummies Market
Nutritional Supplements
Middle East and Africa Feed Antioxidants Market
Nutritional Supplements
Smart Nutrition Scale Market