
 Health Supplementary Food OEM and ODM Market | 2026-2036
Health Supplementary Food OEM and ODM Market Size, Share, and Industry Trends Forecast 2026-2036
Health Supplementary Food OEM and ODM Market Insights
China is rewriting capacity dynamics across the health supplementary food OEM and ODM landscape as contract manufacturers expand mega-facilities to serve both domestic and export orders. Cosmax Inc. leverages integrated R&D-to-production campuses to anchor its position in skin-health crossover supplements. Kolmar Korea sustains formulation leadership through dedicated biotech fermentation capabilities. Sirio Pharma Co., Ltd. dominates softgel and gummy formats for European and North American brand clients.
Health supplementary food OEM and ODM services encompass third-party manufacturing of nutraceuticals, functional foods, and dietary supplements under client branding or co-developed specifications, with processes spanning powder blending, tableting, encapsulation, and aseptic liquid filling for shelf-stable delivery. The primary commercial purpose is enabling brand owners to access specialized production infrastructure, regulatory compliance pathways, and scaled output without capital-intensive facility ownership. Nutritional powders and ready-to-drink shakes command the largest revenue pools as sports nutrition and meal-replacement brands outsource volume production, while dietary capsules retain margin concentration due to complex enteric-coating requirements and potency validation protocols. Organic and vegan formulation types are gaining fastest as clean-label positioning becomes a non-negotiable retail access criterion.
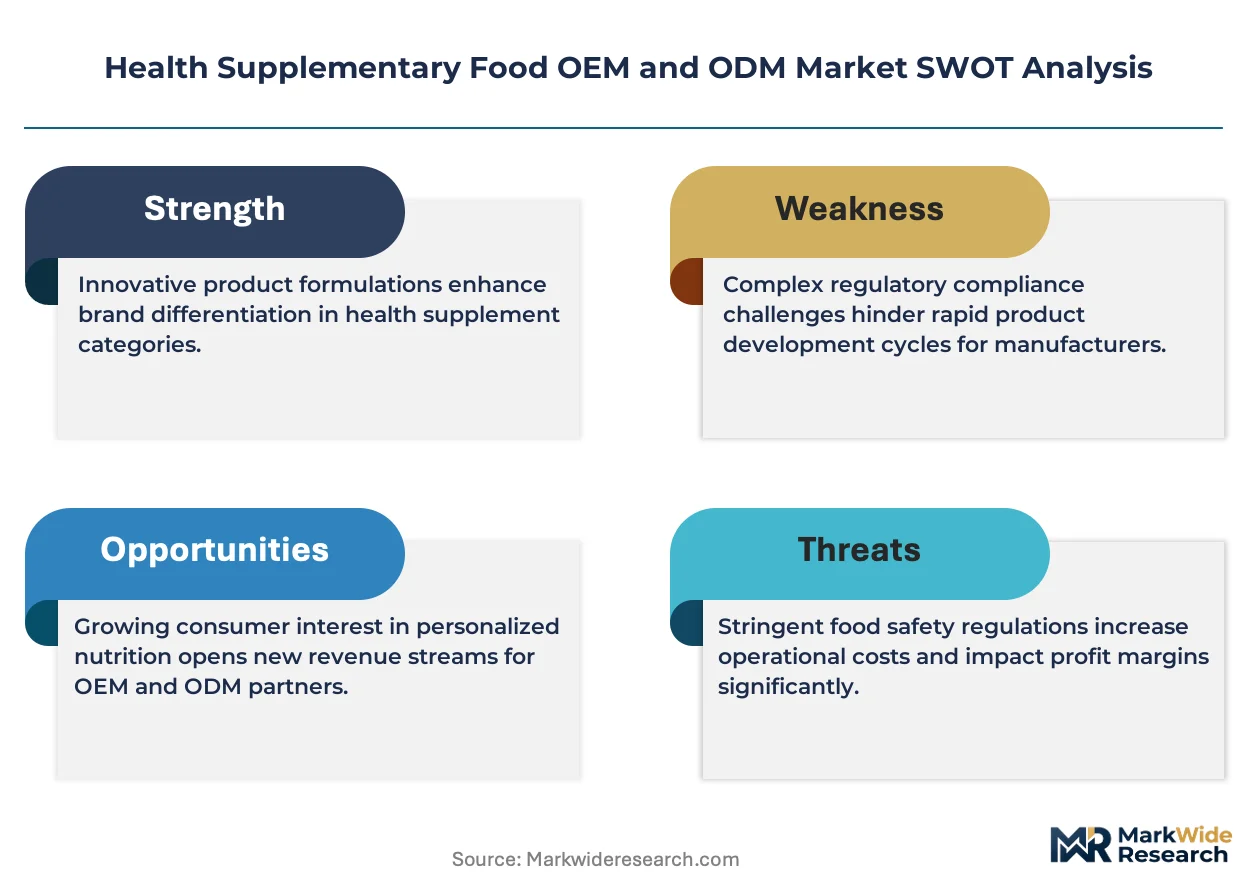
FDA's Current Good Manufacturing Practice enforcement and EFSA's novel food safety assessments create dual compliance burdens for cross-border OEM suppliers, with China's NMPA and SAMR adding domestic registration requirements for imported ingredient dossiers. ISO 22000 and HACCP certifications function as baseline market-access credentials rather than differentiators in mature procurement channels. Stakeholders must monitor evolving pre-market notification timelines and adapt their quality management systems to jurisdiction-specific audit protocols.
Market Dynamics
Contract manufacturing capacity is concentrating in China as domestic brands scale private-label production, while FDA and EFSA novel ingredient scrutiny forces reformulation cycles that reshape supplier selection criteria across the health supplementary food OEM and ODM landscape.
Growth Catalysts
- EFSA novel food safety assessments:European regulatory clarity accelerates dossier preparation services, creating specialized revenue streams for contract manufacturers with in-house toxicology capabilities.
- Sports nutrition outsourcing:Athletic performance brands divest owned production assets, transferring volume commitments to OEM partners with ISO 22000-certified powder blending lines.
- Clean-label positioning:Organic and vegan formulation requirements from retail buyers pull investment into allergen-segregated facilities and plant-based capsule shell technologies.
Market Restraints
- Dual carbon goals compliance:China's MEE enforcement raises energy costs for fermentation-based ingredient suppliers, compressing margins on probiotic and postbiotic formulations.
- Capsule shell supply concentration:Bovine gelatin sourcing dependence on South American renderers exposes softgel manufacturers to input volatility and religious dietary certification complications.
- Enteric-coating technical limitations:pH-dependent release validation failures in gastric simulation testing delay time-to-market for delayed-release omega-3 products.
Strategic Opportunities
- India's PLI scheme for nutraceuticals:Domestic manufacturing incentives attract contract manufacturers to establish tablet and capsule facilities serving export markets with FSSAI-compliant output.
- Personalized nutrition convergence:At-home microbiome testing kits intersect with OEM powder sachet production, enabling lot-size-one manufacturing at scaled unit economics.
- SAMR cross-border e-commerce channels:China's regulatory pathway for imported supplements via bonded zones opens direct-to-consumer fulfillment without NMPA registration for qualifying product categories.
Industry Challenges
- Regulatory affairs talent scarcity:Qualified professionals capable of navigating simultaneous FDA, EFSA, and NMPA submission timelines command premium compensation, constraining mid-tier OEM expansion.
- Legacy ERP integration:Batch record digitization for 21 CFR Part 11 compliance requires capital deployment into validated software systems, disadvantaging smaller contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health Supplementary Food OEM and ODM Market |
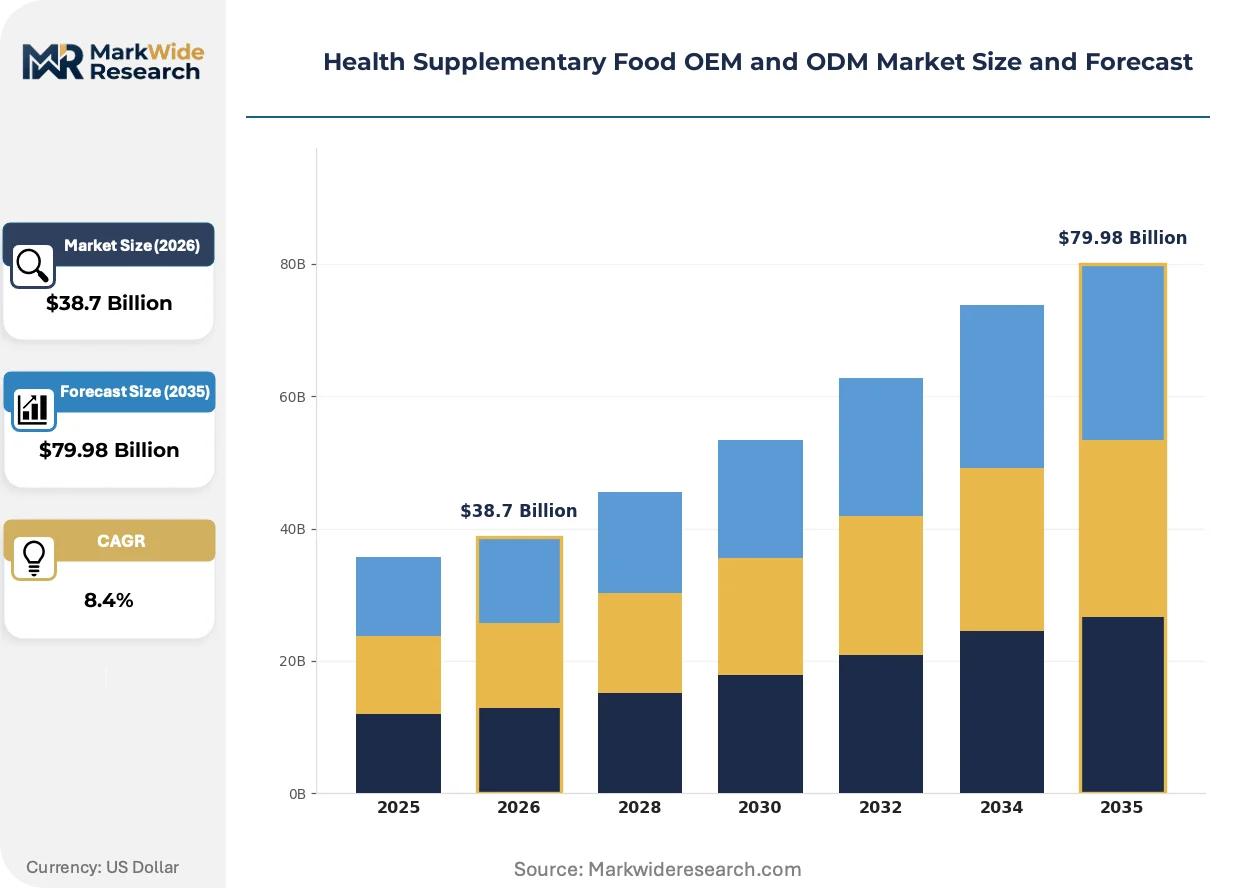
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Nutritional Powders, Ready-to-Drink Shakes, Dietary Capsules End User: Athletes, Seniors, Children, Health Enthusiasts Delivery Mode: Online Retail, Health Food Stores, Supermarkets, Pharmacies Formulation Type: Organic, Non-GMO, Gluten-Free, Vegan |
| Companies Covered | Cosmax Inc., Kolmar Korea, Japan Supplement Foods Co., Ltd., Health Sources Nutrition Co., Ltd., Goerlich Pharma GmbH, API Co., Ltd., Syngen Biotech Co., Ltd., Sirio Pharma Co., Ltd., Robinson Pharma, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health Supplementary Food OEM and ODM Market Trends and Innovations
Fermentation-derived actives and continuous manufacturing platforms are reconfiguring how contract manufacturers compete on speed-to-clinic and sustainability credentials.
Precision fermentation for recombinant proteins and bioactive peptides is hybridizing traditional extract-based supply chains with cell-culture alternatives. Sports nutrition brands with climate commitments are adopting these ingredients at pilot scale. This technology is compressing lead times for novel muscle-protein synthesis compounds while raising capital intensity barriers for facility entry.
REACH substance registration requirements for novel botanical extracts are forcing European OEM customers to demand full supply chain transparency from Asian ingredient suppliers. The industrial consequence is a shift toward pre-registered, catalog-available actives rather than custom wild-harvest sourcing. Botanical softgel specialists serving EU markets are responding by consolidating supplier panels and investing in in-house phytochemical standardization labs.
Brand procurement teams are consolidating vendor relationships from fragmented regional supplier bases toward single-source global OEM partnerships with multi-site redundancy. Direct-to-consumer supplement brands are displacing traditional distributor-dependent models with vertically integrated e-commerce fulfillment. This concentration is most visible in North American and Western European markets where customer acquisition cost economics favor inventory centralization at third-party logistics nodes.
Health Supplementary Food OEM and ODM Market Segmentation
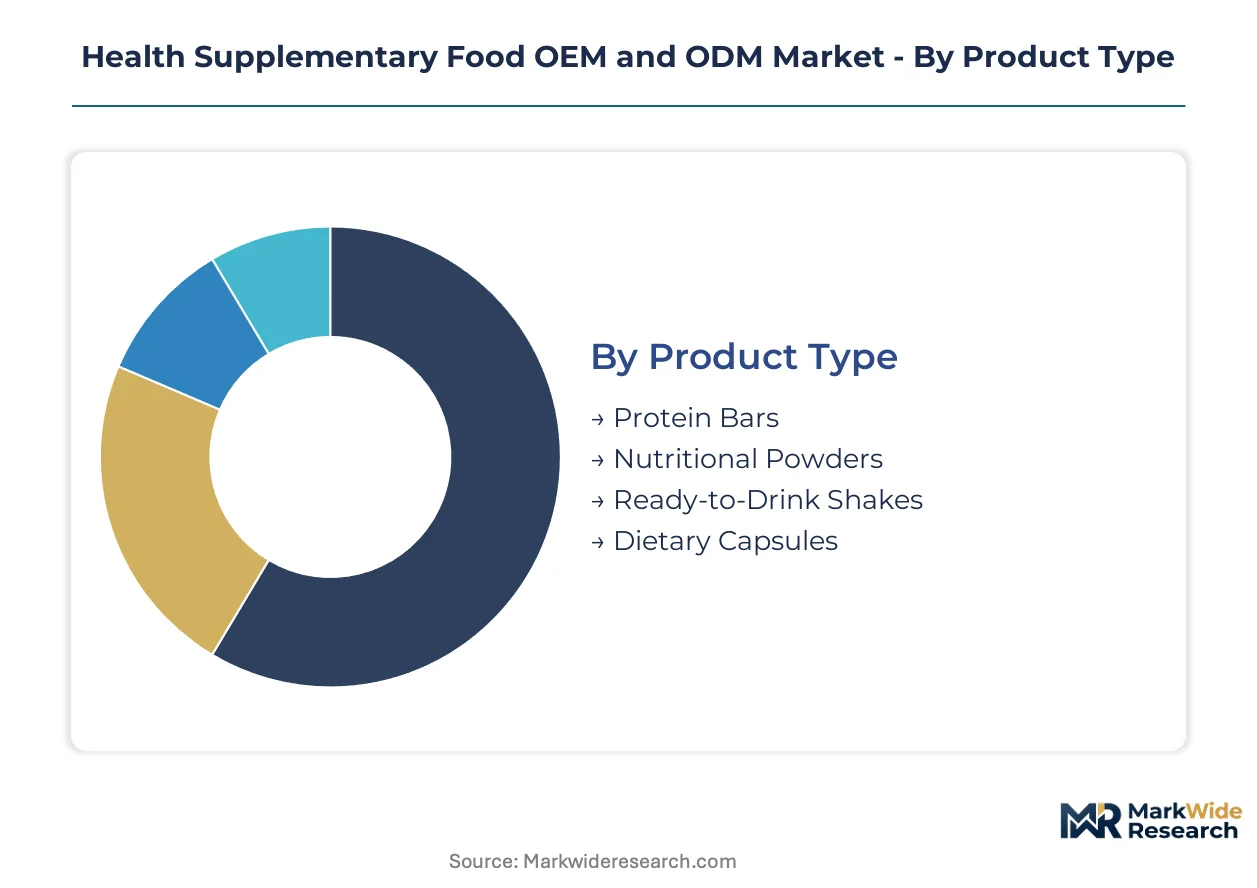
Segmentation in health supplementary food OEM and ODM services reveals where contract manufacturers concentrate capacity investments versus where formulation complexity commands premium pricing. Production cycle times vary dramatically across product formats, with powder blending lines turning inventory weekly while encapsulated specialty products require multi-week coating and validation protocols.
Product Type:
Nutritional Powders move through production fastest with continuous blending and automated filling, while Dietary Capsules sit longest in quality hold pending dissolution and potency verification.
- Nutritional Powders:Bulk whey, plant-protein, and meal-replacement blends processed through ISO 22000-certified ribbon mixers and auger fillers. Sports nutrition brands in the US and Germany outsource volume production here to avoid capital-intensive powder handling infrastructure. Clean-label positioning drives demand for allergen-segregated lines and organic certification.
- Dietary Capsules:Hard-shell and softgel formats requiring enteric-coating, beadlet technology, or lipid-based delivery systems. Complex gastric simulation testing and potency validation extend lead times. European and North American brands concentrate procurement with manufacturers holding multi-jurisdiction drug master files.
- Protein Bars:Cold-formed extrusion and enrobing operations with shorter runs and frequent changeovers for flavor rotation.
- Ready-to-Drink Shakes:Aseptic liquid filling and retort processing with extended shelf-life validation requirements.
Nutritional Powders anchors the volume base while Dietary Capsules gains share at the steepest rate.
End User:
Cost tiers separate commodity production for mass-market Health Enthusiasts from premium-positioned formulations for condition-specific Seniors and performance-optimized Athletes.
- Athletes:NSF Certified for Sport and Informed Sport accreditation requirements dominate procurement criteria. Pre-workout, intra-workout, and recovery formulations with precise amino acid ratios and banned-substance testing. Brands serving competitive athletes in the US, UK, and Australia demand batch-level certificates of analysis.
- Seniors:Bone health, cognitive support, and muscle maintenance formulations with enhanced bioavailability technologies. Joint health supplements with collagen peptides and vitamin D3 complexes show concentration in Japanese and European contract manufacturing.
- Children:Palatability-focused gummy and liquid formats with stringent heavy metal and microbiological specifications.
- Health Enthusiasts:General wellness multivitamins and adaptogenic blends with flexible minimum order quantities for direct-to-consumer brands.
Health Enthusiasts generates the highest order frequency while Athletes commands the steepest per-unit pricing premium.
Delivery Mode:
Volume concentration tracks inventory centralization economics, with Online Retail pulling lot-size-one manufacturing capabilities and Pharmacies demanding validated cold-chain documentation.
- Online Retail:Direct-to-consumer fulfillment requiring flexible batch sizes, variable labeling for subscription models, and bonded-zone warehousing for cross-border e-commerce. China's SAMR cross-border channels concentrate demand with contract manufacturers offering pick-and-pack integration.
- Pharmacies:Behind-the-counter and pharmacist-recommended positioning with drug-level GMP compliance and stability data packages. European markets require EMA-style quality documentation even for food-supplement classifications.
- Health Food Stores:Regional and specialty retail with shorter lead times and frequent promotional packaging changeovers.
- Supermarkets:Mass-market placement with price-competitive bulk production and retail-ready case packing.
Supermarkets anchors absolute volume throughput while Online Retail expands most quickly as brand disintermediation accelerates.
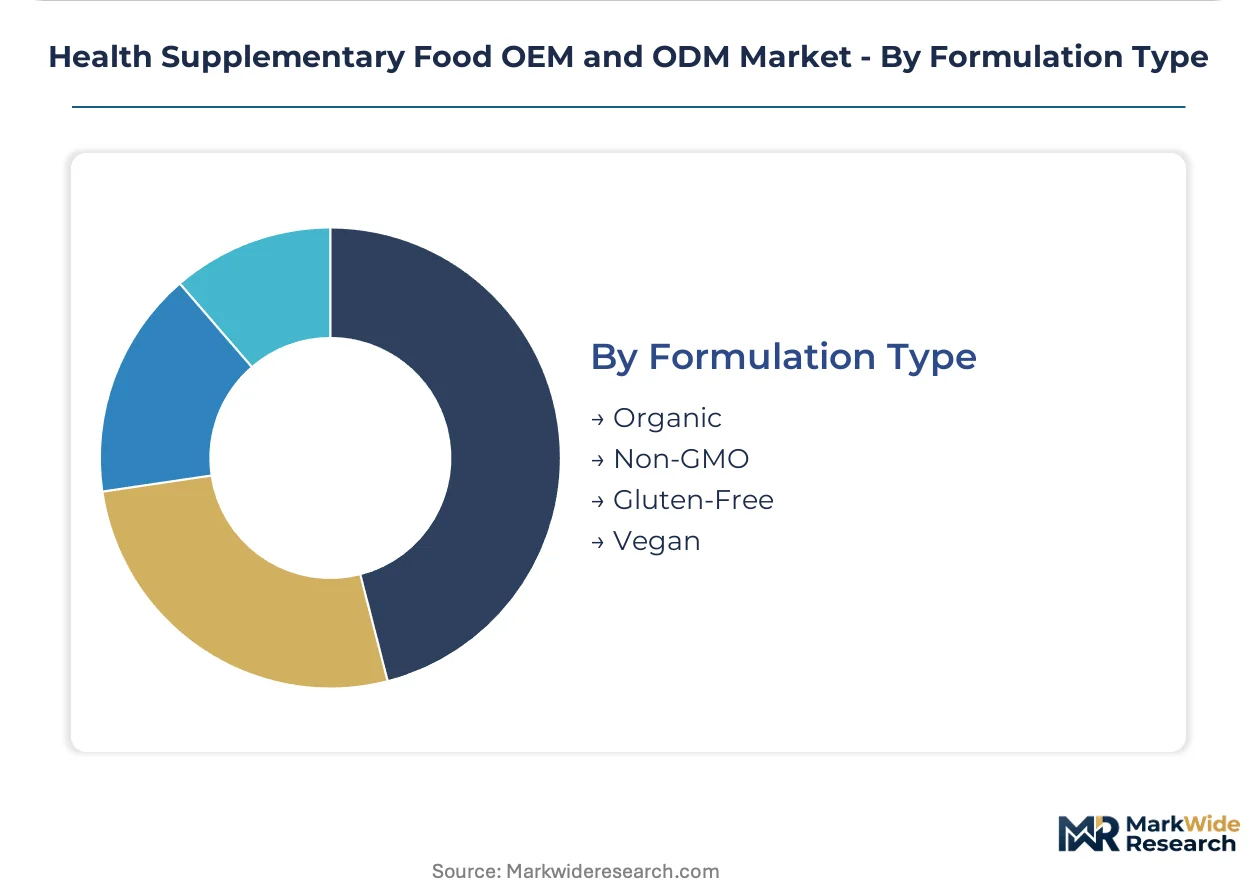
Formulation Type:
Supply concentration for certified inputs creates margin stratification, with Organic commanding dedicated facility segregation and Vegan requiring gelatin-alternative capsule shell technologies.
- Organic:USDA NOP and EU Organic Regulation compliance with full supply chain traceability from agricultural input to finished product. Certification body audits and residue testing extend qualification timelines. US and German brands concentrate procurement with manufacturers holding dual-continent organic handler status.
- Vegan:Plant-based protein sources, non-animal vitamin D3 from lichen, and pullulan or HPMC capsule shells. Religious dietary certification and climate-commitment positioning drive demand from Northern European and North American markets.
- Non-GMO:Project Verified and TRU-ID testing protocols with identity preservation through supply chain.
- Gluten-Free:ELISA testing and allergen-segregated production lines with GFCO or equivalent third-party certification.
Non-GMO holds the broadest addressable base while Vegan climbs the fastest as clean-label positioning hardens into retail access requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of Current Good Manufacturing Practice standards shapes procurement patterns for North American brands, while EFSA novel food assessments and China's SAMR cross-border e-commerce pathways create distinct compliance environments that OEM suppliers must navigate simultaneously.
United States
Sports nutrition brands drive contract manufacturing demand through NSF Certified for Sport requirements. FDA 21 CFR Part 111 inspections enforce documentation standards for powder blending and encapsulation facilities. Utah's Wasatch Front corridor hosts concentrated softgel and tablet production capacity serving direct-to-consumer supplement brands.
China
Domestic health food brands scale private-label production through NMPA-registered facilities. SAMR cross-border e-commerce bonded zones enable imported supplement fulfillment without full registration for qualifying categories. Yangtze River Delta mega-facilities combine R&D campuses with scaled output for European and North American clients.
Germany
Clean-label positioning and vegan formulation requirements pull investment from Central European retail buyers. EFSA novel food safety assessments enforce dossier preparation standards for botanical extracts. Bavaria's supplement manufacturing clusters specialize in enteric-coated capsules and organic-certified powder blends.
South Korea
Beauty-from-within supplements and skin-health crossover products anchor biotech fermentation capabilities. MFDS health functional food standards regulate label claims and efficacy substantiation. Seoul-Incheon corridor facilities integrate precision fermentation with finished dosage production for export markets.
India
Export-oriented tablet and capsule manufacturing expands through FSSAI-compliant facilities serving Middle East and African markets. PLI scheme incentives for nutraceuticals attract capacity investment from domestic and foreign contract manufacturers. Gujarat and Maharashtra industrial zones concentrate spray-drying and granulation infrastructure for protein and herbal extracts.
Health Supplementary Food OEM and ODM Market Competitive Landscape
Capability concentration sits with integrated R&D-to-production campuses; scale advantage sits with multi-site powder handling networks. The vendor base separates into three functional tiers: fermentation-derived active specialists, format-specific technology leaders, and regional full-service providers. Strategic moves cluster around capacity consolidation in China and certification stacking for multi-jurisdiction compliance.
Within the fermentation-technology tier, Kolmar Korea and Syngen Biotech Co., Ltd. exemplify biotech-forward positioning. Among format specialists, Sirio Pharma Co., Ltd. occupies a position in softgel and gummy delivery systems. Cosmax Inc. anchors the integrated campus model spanning skin-health supplements. These archetypes represent how contract manufacturers translate technical differentiation into procurement relationships with brand owners.
| Leading Market Players |
|---|
| Cosmax Inc. |
| Kolmar Korea |
| Japan Supplement Foods Co., Ltd. |
| Health Sources Nutrition Co., Ltd. |
| Goerlich Pharma GmbH |
| API Co., Ltd. |
| Syngen Biotech Co., Ltd. |
| Sirio Pharma Co., Ltd. |
| Robinson Pharma, Inc. |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta mega-facilities concentrate powder blending and encapsulation capacity, translating scale economics into pricing power for contract manufacturers serving European and North American brand clients. China's NMPA registration requirements and SAMR cross-border pathways create compliance-cost stratification that OEM suppliers pass through to downstream pricing tiers.
Pricing Analysis
China-to-Europe price spreads on bulk nutritional powders exceed those for validated dietary capsules by a factor reflecting certification stacking costs. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport production from ISO 22000 baseline and uncertified commodity runs. Pricing pressure stems from China's MEE dual carbon enforcement raising energy input costs for fermentation-based actives. Direct-to-consumer brands show highest price sensitivity, while pharmacy-channel buyers absorb premium tiers for drug-level GMP documentation.
Supply Chain Analysis
Extended payment terms from North American sports nutrition brands now stretch sixty to ninety days, forcing working-capital intensity onto Asian contract manufacturers. Supply concentrates in China, South Korea, and India, with bovine gelatin sourcing dependence on South American renderers exposing softgel producers to input volatility. Distribution runs through bonded-zone warehousing for SAMR cross-border e-commerce channels, concentrating inventory risk at Yangtze River Delta logistics nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health supplementary food OEM and ODM services function as a service-attach play where regulatory dossier preparation and ongoing compliance monitoring expand faster than baseline manufacturing revenue. Recurring certification maintenance and toxicology validation contracts deepen customer switching costs beyond unit production economics.
For Market Incumbents: Entrench position through backward integration into precision fermentation capacity, securing captive supply of recombinant proteins and bioactive peptides that emerging biotech specialists threaten to commoditize. Stack multi-jurisdiction certifications—FDA drug master files, EFSA novel food dossiers, NMPA registrations—to create procurement friction for mid-tier challengers lacking regulatory affairs depth.
For New Entrants and Emerging Players: India's PLI scheme corridors in Gujarat and Maharashtra offer underpenetrated white-space for FSSAI-compliant tablet and capsule production serving Middle East and African export markets. Target personalized nutrition convergence opportunities where lot-size-one powder sachet manufacturing intersects with at-home microbiome testing kits, bypassing incumbent scale advantages in bulk runs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-derived active specialists over format-commoditized softgel producers, as precision fermentation compresses lead times for novel muscle-protein synthesis compounds. Acquisition screens should prioritize contract manufacturers with in-house toxicology capabilities and validated 21 CFR Part 11 ERP systems. The signal to watch is EFSA novel food approval velocity—accelerating timelines would validate premium valuations for dossier-ready suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Secures captive supply of recombinant proteins for climate-committed sports nutrition brands. |
| Multi-Jurisdiction Certification Stacking | Creates procurement friction through simultaneous FDA, EFSA, and NMPA compliance pathways. |
| Regulatory Dossier Service Expansion | Captures recurring revenue from EFSA novel food safety assessment preparation and maintenance. |
| Bonded-Zone Logistics Integration | Enables SAMR cross-border e-commerce fulfillment without full NMPA registration overhead. |
| Personalized Nutrition Platform Partnership | Intersects OEM powder sachet production with at-home microbiome testing kit providers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA warning letters, EFSA novel food opinions, NMPA registration databases, and SAMR cross-border e-commerce policy circulars. Interviews with contract manufacturing executives, regulatory affairs directors at sports nutrition brands, quality assurance leads at encapsulation facilities, and procurement managers at direct-to-consumer supplement companies inform demand-side validation. Bottom-up capacity modeling triangulates against top-down trade flow analysis.
Forecast inputs incorporate product type segmentation across nutritional powders, dietary capsules, protein bars, and ready-to-drink shakes; end-user differentiation between athletes, seniors, children, and health enthusiasts; and formulation type stratification across organic, vegan, non-GMO, and gluten-free certifications. CAGRs derive from regression analysis against historical outsourcing intensity, regulatory approval velocity, and clean-label certification penetration across the projection horizon. Fermentation technology adoption curves and personalized nutrition platform integration rates inform scenario weighting.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed contract manufacturers or rapid EFSA novel food approval acceleration would shift outcomes. Macroeconomic contraction in North American direct-to-consumer supplement spending, regulatory restriction on precision fermentation-derived ingredients, or technological breakthrough in continuous manufacturing platforms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
South America Meal Replacement Products Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
India Whey Protein Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Global Vitamin Supplements Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Throat Lozenges Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Dhea Supplement Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market