
 Sleep Gummies Market | 2026-2036
Sleep Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Gummies Market Analytics
Contract manufacturers across North America are pivoting toward dedicated gummy production lines to capture share of the expanding sleep supplement category. Olly leverages its brand strength in mass retail channels to sustain shelf presence against private-label encroachment. Nature Made anchors its positioning through USP verification, a quality marker that differentiates its melatonin formulations in pharmacy settings. Church & Dwight competes through broad distribution control, extending its reach across multiple retail banners.
Sleep gummies are chewable dietary supplements formulated with active ingredients such as melatonin, L-theanine, or hemp-derived compounds, typically dosed at 1–10 mg per serving and manufactured through starch molding or deposited candy processes to achieve precise ingredient homogeneity and controlled release profiles. Their primary commercial purpose is to provide accessible, palatable alternatives to pills and capsules for consumers managing occasional sleeplessness or circadian disruption. Melatonin-based formulations occupy the largest revenue pool due to established clinical familiarity and permissive regulatory status in most jurisdictions, while CBD variants face fragmented acceptance that creates margin premiums in permitted markets. The sugar-free formulation segment leads growth among health-conscious adults, though organic positioning commands higher unit economics in specialty retail channels.
The FDA oversees melatonin and CBD ingredient claims through its dietary supplement and drug classification frameworks, while the FTC monitors advertising substantiation for sleep benefit assertions; together these agencies constrain formulation flexibility and marketing language. State-level hemp regulations add a secondary compliance layer that fragments market access for CBD-inclusive products. Stakeholders must monitor pending federal CBD rulemaking and evolving international Novel Food approvals to calibrate portfolio and geographic priorities.
Market Dynamics
FDA scrutiny of melatonin dosage accuracy and evolving CBD classification rules are compressing formulation flexibility while concentrating compliance burdens on smaller contract manufacturers.
Growth Catalysts
- Direct-to-consumer wellness platforms:Subscription-based sleep gummy programs bypass pharmacy gatekeepers and capture recurring revenue from working adults seeking convenience.
- USP verification protocols:Third-party quality certification programs reduce consumer skepticism toward over-the-counter melatonin products in pharmacy and mass retail channels.
- Sugar-free formulation chemistry:Advances in polyol-based gummy matrices enable palatable zero-sugar positioning without compromising texture or shelf stability.
Market Restraints
- Active ingredient cost volatility:Pharmaceutical-grade melatonin supply concentrates among Chinese API manufacturers, exposing formulators to tariff and logistics disruptions.
- CBD regulatory fragmentation:The FDA's refusal to establish a clear dietary supplement pathway for hemp-derived cannabinoids forces state-by-state compliance architectures.
- Clinical efficacy skepticism:Systematic reviews questioning melatonin dose-response consistency dampen physician endorsement and limit pharmacy recommendation rates.
Strategic Opportunities
- Menopausal sleep disruption:Hormone-transitioning women represent an underserved segment with distinct formulation needs combining melatonin with phytoestrogenic compounds.
- Travel retail channels:Airport convenience stores and hotel minibars offer impulse-purchase positioning for jet lag-focused single-serve sleep gummy packs.
- EU Novel Food authorization:Successful CBD novel food approvals in select member states create beachhead positions for compliant brands ahead of broader harmonization.
Industry Challenges
- Stability testing bottlenecks:Accelerated shelf-life validation for novel gummy matrices stretches analytical laboratory capacity and extends product launch timelines.
- Cross-contamination protocols:Contract manufacturers serving both THC and non-THC clients face escalating insurance and facility segregation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Gummies Market |
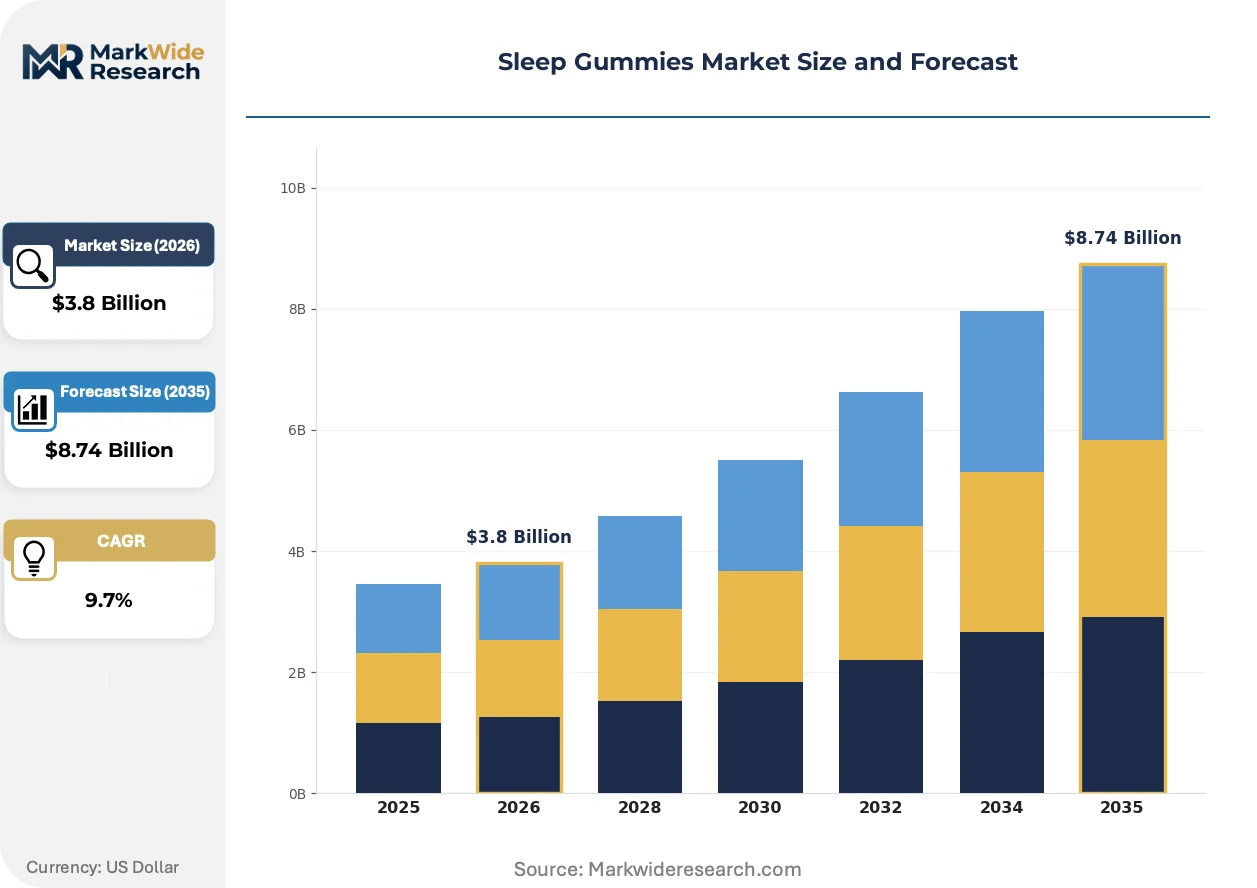
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Melatonin, Herbal, CBD, Vitamin Formulation: Organic, Sugar-Free, Vegan, Gluten-Free Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores End User: Adults, Seniors, Children, Athletes |
| Companies Covered | Olly, Nature Made, Nature's Bounty, Jamieson, CVS Health, Church & Dwight, Vicks, 3Z Brands, Natrol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Gummies Market Evolving Landscape
Formulation science and channel architecture are converging to reshape how sleep gummies reach consumers and how their functional claims are substantiated.
Microencapsulation technology is expanding into sleep gummy production to protect melatonin from degradation during thermal processing and enable extended-release profiles. Precision nutrition startups are adopting these systems to differentiate their portfolios against commodity melatonin offerings. The technology is expanding into premium positioning by supporting claims of sustained sleep maintenance rather than sleep onset alone.
The FDA's pending guidance on CBD enforcement discretion is forcing brands to bifurcate their product architectures between melatonin-only and hemp-inclusive lines. This regulatory uncertainty is accelerating investment in clinical trials for non-CBD alternatives such as L-theanine and magnesium glycinate. European markets with established novel food frameworks are absorbing R&D investment that might otherwise target US market entry.
Working adults are abandoning multi-pill sleep stacks in favor of single-product solutions that combine sleep onset and anxiety reduction functions. This consolidation preference favors gummy formats capable of incorporating multiple actives without compromising taste or texture. Urban professional segments in high-stress employment clusters are driving the fastest adoption of these combination formulations.
Sleep Gummies Market Segmentation
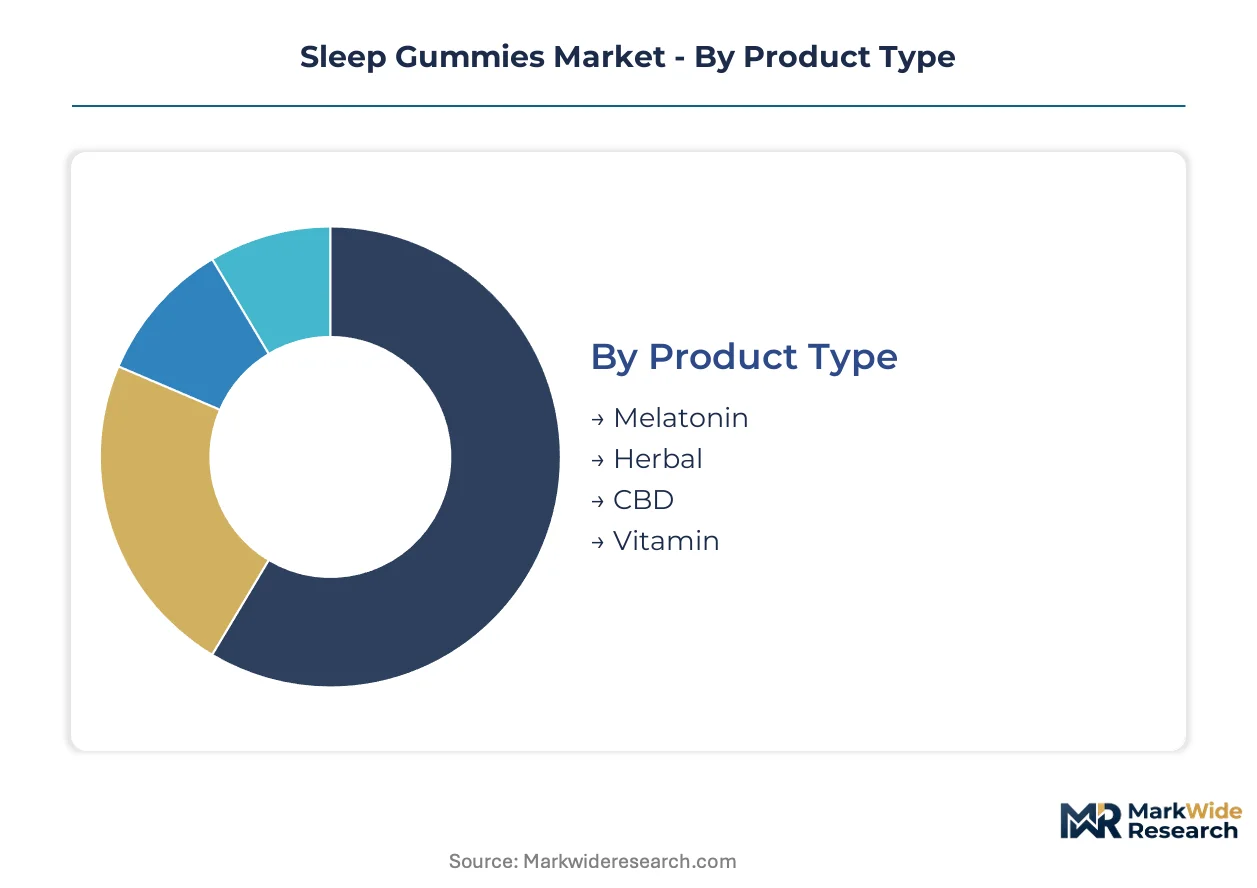
Sleep gummies fragment across four distinct category axes, each commanding different capital commitments and margin profiles. Formulation chemistry and regulatory compliance requirements create divergent investment thresholds that reshape competitive entry barriers across segments.
Product Type:
Melatonin formulations demand the heaviest upfront investment in pharmaceutical-grade API sourcing and stability testing infrastructure. CBD variants require parallel legal compliance architectures across state jurisdictions.
- Melatonin:Synthetic or pineal-derived hormone dosed at 1–10 mg per serving, requiring controlled-release microencapsulation to prevent thermal degradation during starch molding. Demand concentrates among working adults in the United States seeking non-prescription circadian regulation, though FDA dosage accuracy scrutiny elevates analytical validation costs.
- Herbal:Valerian root, chamomile, and passionflower extracts formulated through ethanol or CO2 extraction methods, with standardization challenges around marker compound consistency. European pharmacy channels favor these formulations where melatonin faces stricter prescription thresholds.
- CBD:Hemp-derived cannabinoid isolates or broad-spectrum extracts requiring THC-free certification and novel food authorization in permitted jurisdictions. State-by-state regulatory fragmentation in the United States forces redundant compliance spending.
- Vitamin:B6, magnesium, and tryptophan combinations positioned as gentler alternatives with lower regulatory scrutiny but reduced clinical familiarity among physicians.
Most installed capacity flows through Melatonin. Expansion is steepest in CBD where margin premiums offset compliance burdens in permitted markets.
Formulation:
Ingredient sourcing intensity and certification overhead separate cost tiers rather than manufacturing scale. Organic positioning commands the steepest premium due to supply chain traceability requirements.
- Organic:USDA-certified or equivalent agricultural inputs with full batch traceability, requiring segregated processing lines and third-party audit cycles. Health Stores in California and New York absorb premium pricing for certified organic positioning.
- Sugar-Free:Polyol-based matrices using maltitol, erythritol, or allulose to achieve glycemic neutrality without compromising chew texture. Advances in polyol chemistry enable palatable zero-sugar positioning that expands fastest among diabetic and keto-adherent adults.
- Vegan:Pectin or agar-agar gelling agents replacing porcine-derived gelatin, with modified setting temperatures and moisture barriers to prevent syneresis. European markets with established vegan certification frameworks drive formulation standardization.
- Gluten-Free:Starch molding processes using tapioca or potato-derived carriers rather than wheat-based alternatives, with cross-contamination protocols that add facility segregation costs.
Organic commands the highest unit economics. Sugar-Free is gaining share fastest as health-conscious adults abandon sucrose-based alternatives.
Distribution Channel:
Customer acquisition economics and working capital intensity diverge sharply between direct-to-consumer platforms and brick-and-mortar gatekeepers. Shelf slotting fees and inventory carrying costs concentrate investment in mass retail penetration.
- Online Retail:Subscription-based wellness platforms capturing recurring revenue through algorithmic replenishment and personalized dosing recommendations. Working adults in high-stress employment clusters drive adoption of auto-ship programs that bypass pharmacy gatekeepers.
- Pharmacies:USP-verified products positioned through pharmacist recommendation and insurance-adjacent purchasing, requiring cold chain compliance and dating discipline that elevates distribution costs.
- Supermarkets:Impulse-purchase placement in sleep and wellness aisles, with slotting fee structures that favor established brands over emerging entrants.
- Health Stores:Specialty retail channels emphasizing organic, vegan, or CBD-inclusive positioning with educated staff recommendation driving conversion.
Pharmacy channels absorb the most working capital. Online Retail is expanding most quickly as subscription economics reshape customer lifetime value calculations.
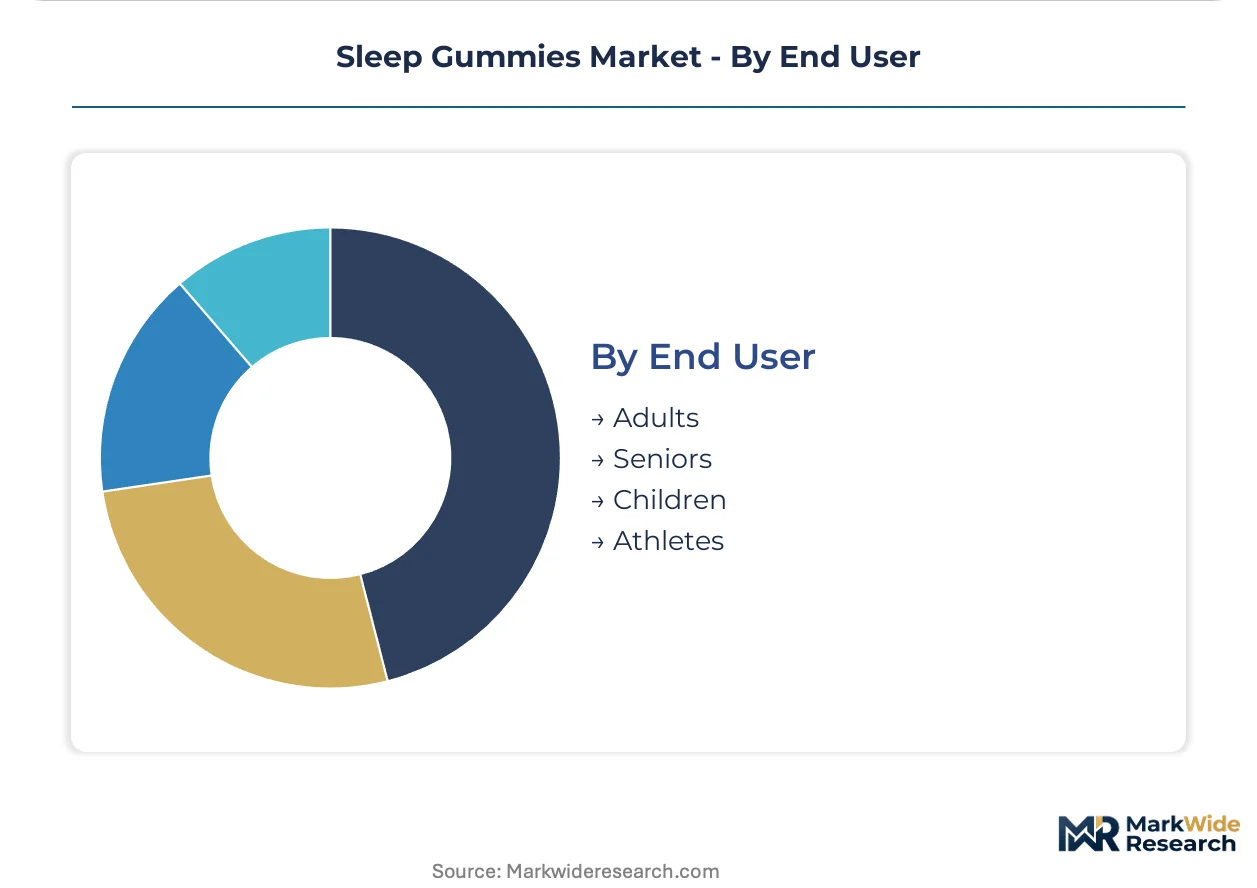
End User:
Age-appropriate dosing protocols and palatability requirements create distinct formulation specifications. Pediatric and senior segments demand specialized manufacturing controls around choking hazard mitigation and swallowing ease.
- Adults:Working professionals aged 25–55 seeking single-product solutions combining sleep onset and anxiety reduction, favoring combination formulations with L-theanine or magnesium glycinate. Urban professional clusters in the United States drive fastest adoption of these consolidated offerings.
- Seniors:Lower-dose melatonin positioning with enhanced moisture content for easier mastication, addressing polypharmacy concerns through physician-preferred USP verification.
- Children:Micro-dosed formulations with strict heavy metal and contaminant testing, facing pediatrician skepticism that limits pharmacy recommendation rates.
- Athletes:NSF Certified for Sport or Informed Sport verification to ensure banned substance absence, with batch testing protocols that add 15–20% to production costs.
Adults represent the largest addressable base. Athletes show the steepest expansion trajectory as sports nutrition brands extend into recovery positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting manufacturing investment toward jurisdictions with clearer dietary supplement pathways, as the FDA's pending CBD guidance forces brands to maintain parallel compliance architectures across state lines.
United States
Working adults in urban professional clusters drive subscription-based sleep gummy adoption through direct-to-consumer wellness platforms. The FDA's evolving stance on melatonin dosage accuracy elevates analytical validation costs for domestic formulators. California and New York health stores absorb premium pricing for certified organic positioning, while Texas and Florida concentrate mass retail distribution infrastructure.
Germany
European pharmacy channels favor herbal sleep gummy formulations where melatonin faces stricter prescription thresholds than in North America. EFSA novel food frameworks create compliance beachheads for CBD-inclusive products ahead of broader EU harmonization. The Bavaria and Baden-Württemberg regions host specialized contract manufacturers serving both domestic pharmacy chains and export markets.
United Kingdom
Urban professionals in London and the Southeast abandon multi-pill sleep stacks in favor of single-product gummy solutions combining melatonin with L-theanine. The UK's Medicines and Healthcare products Regulatory Agency maintains distinct classification boundaries between food supplements and medicinal products. Greater Manchester and the Midlands concentrate sugar-free formulation capacity serving diabetic and keto-adherent consumer segments.
Canada
Health Canada oversight of natural health products creates a structured compliance pathway that attracts US brands seeking regulatory clarity unavailable domestically for CBD variants. The Ontario and Quebec corridors dominate gummy manufacturing capacity serving both domestic pharmacy chains and cross-border export. Vancouver and Toronto anchor direct-to-consumer brand headquarters leveraging favorable e-commerce logistics.
Australia
TGA scheduling of melatonin as a pharmacy-only medicine constrains over-the-counter availability but elevates perceived quality among physician-influenced consumers. The Sydney and Melbourne metropolitan areas concentrate specialty retail channels emphasizing USP-verified and NSF Certified for Sport positioning. Queensland's agricultural base supplies organic ingredient traceability for premium export formulations targeting Asian markets.
Sleep Gummies Market Competitive Landscape
United States producers anchor the mass retail and direct-to-consumer tiers; European specialists hold pharmacy-channel positioning through stricter quality certification protocols. The vendor base fragments across three tiers: established consumer health conglomerates with shelf-slotting leverage, mid-scale wellness brands with subscription economics, and private-label contract manufacturers serving retail banners. Three strategic archetypes dominate: USP-verified pharmacy players, organic-specialty health store suppliers, and algorithmic subscription platforms. Competitive moves concentrate on portfolio bifurcation between melatonin-only and hemp-inclusive lines, plus accelerated investment in clinical trial substantiation for non-CBD alternatives.
Within the established consumer health tier, Olly and Nature Made occupy positions exemplifying divergent channel strategies—mass retail shelf presence versus pharmacy-quality verification. Church & Dwight represents the conglomerate archetype with broad distribution control across multiple retail banners. These companies illustrate how brand equity and regulatory compliance infrastructure function as mutually reinforcing barriers against private-label encroachment in a category where FDA scrutiny elevates quality assurance costs.
| Leading Market Players |
|---|
| Olly |
| Nature Made |
| Nature's Bounty |
| Jamieson |
| CVS Health |
| Church & Dwight |
| Vicks |
| 3Z Brands |
| Natrol |
| Others |
Value Network & Pricing Analysis
Working adult preference for subscription-based auto-ship programs is compressing traditional distributor markups and forcing contract manufacturers to absorb inventory carrying costs or cede margin to direct-to-consumer platforms. This demand-side channel shift elevates pricing power for brands with captive e-commerce infrastructure while squeezing intermediaries dependent on pharmacy and mass retail slotting fees.
Pricing Analysis
Retailer markup layers in pharmacy and supermarket channels absorb 35–50% of shelf price, while direct-to-consumer subscription models bypass these gatekeepers entirely. Three-tier pricing structure across USP-verified premium, standard melatonin, and private-label economy levels separates quality-assured formulations from commodity alternatives. Pricing pressure stems from FDA dosage accuracy scrutiny elevating analytical validation costs for smaller formulators. Price-sensitive mass retail buyers favor private-label alternatives, while pharmacy-channel consumers demonstrate lower sensitivity due to physician recommendation influence.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through dedicated production lines, while fragmented health store distribution relies on regional distributors with higher per-unit logistics costs. Active ingredient supply concentrates in China for pharmaceutical-grade melatonin API, with secondary sourcing from India and limited domestic US fermentation capacity. Gummy matrix production draws from tapioca starch suppliers in Thailand and Indonesia, plus polyol sweetener manufacturers in the United States. Tariff exposure on Chinese API imports creates margin volatility for formulators without long-term supply agreements. Distribution runs through three parallel channels: direct-to-consumer fulfillment centers, regional distributor networks serving pharmacy chains, and broadline distributors supplying supermarkets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sleep gummies offer margin expansion through sugar-free formulation chemistry advances that command premium pricing without proportional input cost increases, plus subscription economics that extend customer lifetime value beyond transactional retail.
For Market Incumbents: Cement USP verification dominance through accelerated batch testing infrastructure investment, locking in pharmacy channel preference before FDA melatonin scrutiny elevates compliance costs for smaller competitors. Capture direct-to-consumer subscription share through algorithmic replenishment platforms that bypass retail gatekeeper margin extraction. Vertical integration into melatonin microencapsulation technology protects against API supplier concentration risk while supporting sustained-release premium positioning. For New Entrants and Emerging Players: Menopausal women seeking hormone-transition sleep support represent an underserved buyer archetype with formulation white space and limited incumbent targeting. Travel retail channels—airport convenience stores and hotel minibars—offer impulse-purchase positioning with lower slotting fee barriers than mass retail. EU Novel Food authorization for CBD-inclusive products creates beachhead positioning ahead of broader harmonization, with Germany and the United Kingdom as initial target markets. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale wellness brands possessing subscription platform infrastructure and clinical trial substantiation for non-CBD alternatives such as L-theanine or magnesium glycinate. Long-term viability hinges on regulatory clarity trajectory rather than near-term revenue scale. Acquisition targets should demonstrate novel food compliance progress in European jurisdictions or USP verification completion for pharmacy channel access. Watch FDA CBD enforcement discretion guidance as the critical inflection signal determining portfolio bifurcation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Investment | FDA scrutiny of melatonin dosage accuracy elevates third-party certification as pharmacy channel prerequisite. |
| Sugar-Free Formulation Expansion | Polyol chemistry advances enable glycemic-neutral positioning that commands premium pricing among diabetic and keto-adherent adults. |
| Subscription Platform Development | Auto-ship algorithms bypass retail gatekeepers and capture recurring revenue from working adult convenience seekers. |
| EU Novel Food Authorization | EFSA compliance creates beachhead positioning for CBD-inclusive brands ahead of broader European harmonization. |
| Microencapsulation Technology Adoption | Thermal protection during starch molding enables sustained-release claims that differentiate premium melatonin offerings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with contract manufacturing executives, pharmacy chain category buyers, direct-to-consumer brand operators, and regulatory affairs specialists with secondary validation against FDA warning letters, EFSA novel food submission databases, USP verification registries, and Nielsen retail audit data. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from trade flow analysis.
Segment-weighting approaches applied differential growth assumptions across melatonin, herbal, CBD, and vitamin formulation types, with additional stratification by sugar-free, organic, vegan, and conventional positioning tiers. Distribution channel splits between online retail, pharmacy, supermarket, and health store channels incorporated distinct customer acquisition economics. CAGRs derived from regression analysis of historical subscription platform growth rates, adjusted for FDA regulatory clarity scenarios and EU novel food approval timelines.
Underlying measurement precision varies by segment; melatonin formulations with established clinical familiarity carry tighter precision than CBD variants subject to regulatory fragmentation. Forecasts reflect documented assumptions regarding FDA enforcement discretion evolution and EFSA harmonization progress. Periodic stress-testing of base assumptions is recommended given tariff exposure on Chinese API imports and pending federal CBD rulemaking uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
Human Milk Oligosaccharides (HMO) Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Cod Liver Oil Market