
 South America Dietary Supplement Market | 2026-2036
South America Dietary Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
South America Dietary Supplement Market Analytics
Plant-based protein isolates is hardening cost structures as manufacturers shift from whey and casein toward pea and rice protein blends. Abbott Laboratories leverages its clinical nutrition heritage to anchor hospital and pharmacy channels across Brazil. Herbalife Nutrition Ltd. sustains a direct-sales footprint that dominates person-to-person distribution in Colombia and Peru. Glanbia PLC specializes in sports nutrition ingredients, supplying whey and plant protein to regional contract manufacturers.
Dietary supplements encompass vitamins, minerals, botanical extracts, amino acids, and other bioactive compounds formulated in pills, powders, liquids, or gummies to supplement daily nutritional intake and support physiological functions. These products typically contain standardized active ingredient concentrations, undergo dissolution and stability testing, and target specific deficiencies, performance goals, or life-stage requirements. Vitamins and minerals occupy the largest revenue share due to established consumer familiarity and broad retail availability, while herbal extracts capture accelerating interest from consumers seeking natural alternatives to synthetic actives. Gummies represent the fastest-growing form segment as palatability improvements expand adoption among children and seniors who resist traditional pill formats.
ANVISA in Brazil, the Argentine national food and drug regulator, and Chile's Ministry of Health enforce distinct registration, labeling, and good manufacturing practice standards that determine which products reach pharmacy and supermarket shelves. Brazil's updated supplement legislation reduces registration timelines, enabling faster product launches and intensifying competitive pressure on incumbent brands. Stakeholders must monitor regulatory divergence across Mercosur members, as harmonization failures force duplicative compliance investments and create arbitrage opportunities for brands with flexible manufacturing footprints.
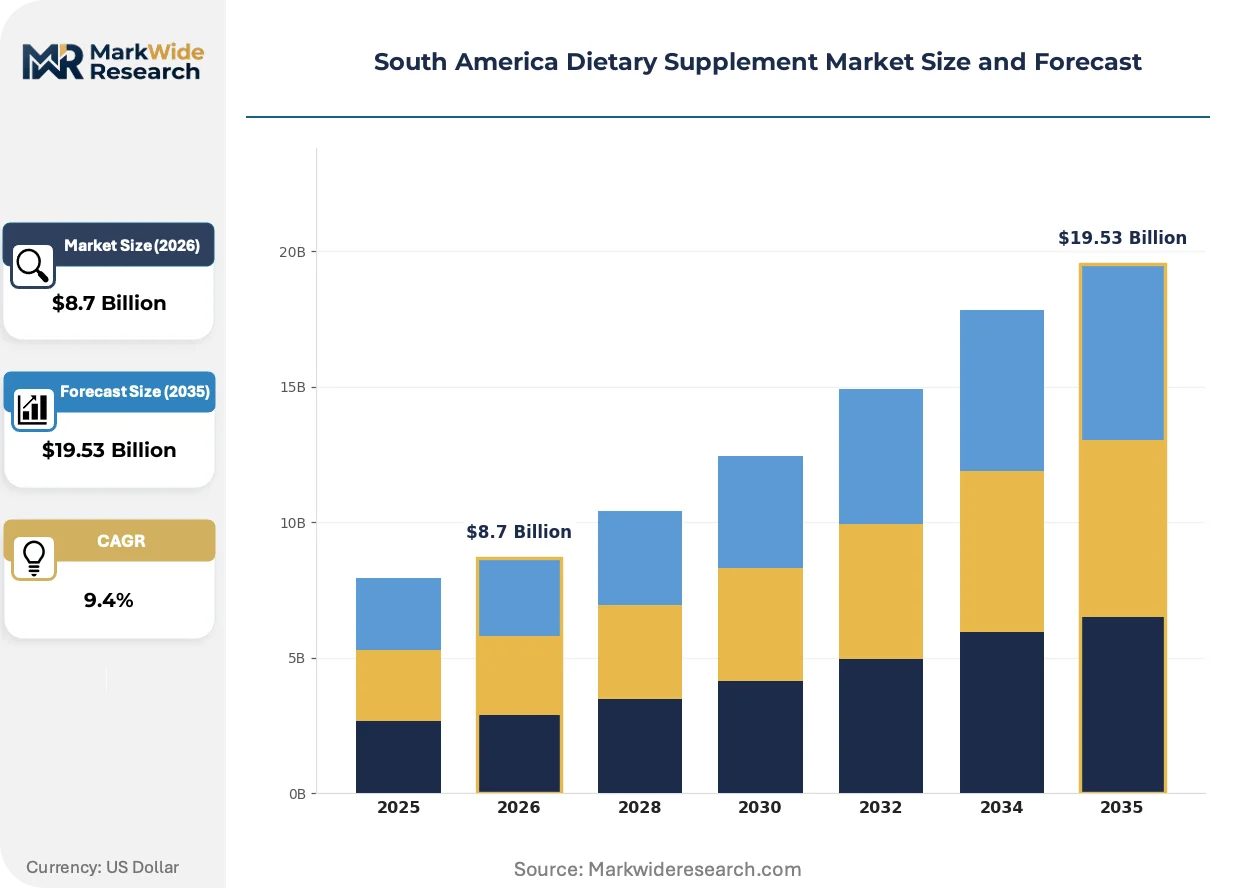
Market Dynamics
ANVISA's streamlined registration pathways are compressing product launch timelines, intensifying competitive pressure on incumbent brands while enabling agile entrants to capture shelf space in Brazil's pharmacy and supermarket channels.
Growth Catalysts
- ANVISA's updated supplement legislation:Reduced approval timelines accelerate market entry for both domestic and international brands, compressing the gap between formulation and commercialization.
- Sports nutrition adoption:Amateur and professional athletes across Brazil and Argentina are expanding consumption of protein isolates and amino acid formulations.
- Urban health corridors:São Paulo and Rio de Janeiro concentrate demand for premium vitamins and botanical extracts among affluent, health-conscious consumers.
Market Restraints
- Pea and rice protein input costs:Plant-based protein isolates harden cost structures as manufacturers shift from whey and casein toward alternative blends.
- Mercosur regulatory divergence:Harmonization failures force duplicative compliance investments across Brazil, Argentina, and Chile.
- Traditional pill format resistance:Children and seniors reject capsules and tablets, limiting addressable market for conventional delivery systems.
Strategic Opportunities
- Gummy format expansion:Palatability improvements open pediatric and geriatric segments previously closed to supplement adoption.
- Direct-to-consumer channels:Person-to-person distribution models in Colombia and Peru bypass traditional retail margin structures.
- Hospital and pharmacy anchoring:Clinical nutrition heritage positions specialized brands to capture institutional procurement contracts.
Industry Challenges
- Good manufacturing practice certification timelines:ANVISA and Chile's Ministry of Health enforce distinct stability testing standards that delay batch releases.
- Supply chain reconfiguration:Shifting from dairy-derived to plant-based inputs requires new supplier qualification and quality control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Dietary Supplement Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Amino Acids End User: Adults, Athletes, Seniors, Children Form: Pills, Powders, Liquids, Gummies Distribution Channel: Online Retail, Supermarkets, Pharmacies, Direct Sales |
| Companies Covered | Abbott Laboratories, Bayer AG, Herbalife Nutrition Ltd., Amway Corp., Glanbia PLC, Integralmedica, Pátria Suplementos, Medcell, Sanofi, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Dietary Supplement Market Evolving Landscape
Formulation science and delivery mechanism innovation are reshaping competitive positioning in South American dietary supplements, with three distinct vectors altering how products reach consumers and how manufacturers capture value.
Microencapsulation technology is integrating lipid-based shell systems around sensitive actives like omega-3 fatty acids and fat-soluble vitamins. Regional contract manufacturers in Brazil and Argentina are adopting these systems to extend shelf life in tropical storage conditions. This capability is integrating previously unstable botanical extracts into mainstream retail portfolios.
ANVISA's implementation of simplified notification pathways for low-risk supplements is compressing registration timelines from 24 months to under 90 days for qualifying formulations. The industrial consequence is a surge of new SKUs entering pharmacy channels, forcing incumbent brands to accelerate reformulation cycles. Sports nutrition and herbal extract categories are responding most aggressively, with brands launching seasonal variants to exploit faster approvals.
Subscription-based replenishment models are displacing traditional pharmacy repurchase patterns among urban professionals in São Paulo and Bogotá. Direct-to-consumer platforms are capturing recurring revenue streams that supermarkets and drugstores previously dominated. This shift is most visible in the premium vitamin segment, where auto-ship programs now account for a growing share of volume.
South America Dietary Supplement Market Segmentation
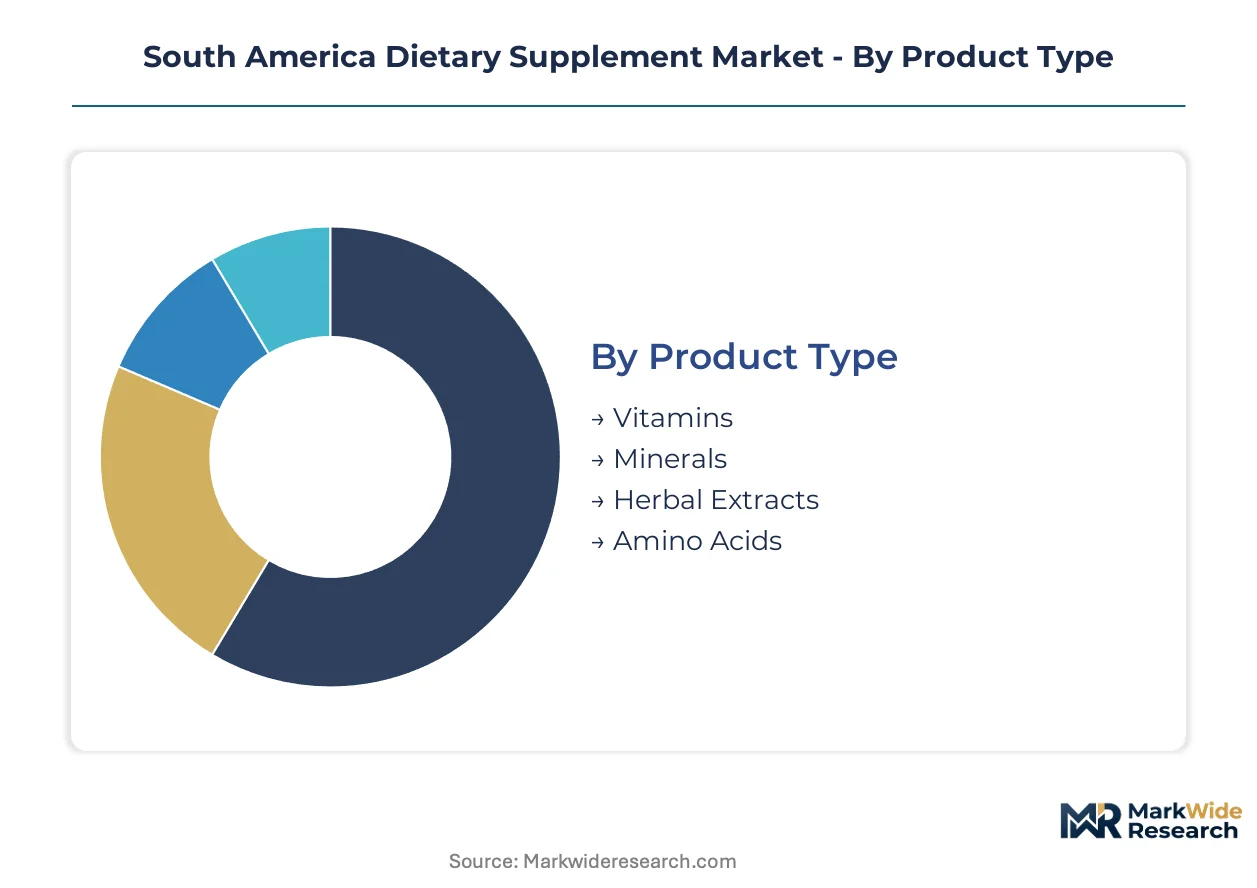
Segmentation in South American dietary supplements determines regulatory pathways, margin structures, and channel access. ANVISA and national regulators apply distinct registration burdens across product categories, while consumer demographics and delivery formats dictate pricing power and distribution economics.
Product Type:
Certification intensity varies sharply across product categories, with botanical extracts facing the most stringent stability documentation requirements under ANVISA's updated framework while vitamins navigate simplified notification pathways.
- Vitamins:Standardized compounds including fat-soluble and water-soluble variants formulated in precise IU concentrations. Demand concentrates in São Paulo's urban health corridors where affluent consumers purchase premium multivitamin complexes through pharmacy channels, though price sensitivity limits penetration in secondary Brazilian cities.
- Herbal Extracts:Botanical actives standardized to marker compound percentages, requiring extensive shelf-life validation under tropical storage conditions. Adoption accelerates among Argentine consumers seeking alternatives to synthetic actives, with yerba mate and açaí derivatives commanding regional formulation preferences.
- Minerals:Chelated and inorganic salt forms targeting deficiency correction in specific demographics.
- Amino Acids:Branched-chain and essential formulations supporting muscle protein synthesis.
Leading the category by volume: Vitamins. Growing fastest: Herbal Extracts.
End User:
Customer lifecycle positioning determines formulation complexity and channel strategy, with pediatric and geriatric segments requiring palatability engineering that adult formulations rarely demand.
- Adults:General wellness formulations spanning preventive and condition-specific applications. Brazil's southeastern corridor drives premium vitamin demand among health-conscious professionals, while mass-market penetration concentrates in pharmacy chains with private-label expansion.
- Athletes:Performance-oriented protein isolates and recovery formulations with documented bioavailability. Argentina's amateur sports culture and Brazil's professional athletic infrastructure sustain specialized nutrition demand, though input cost volatility in plant-based proteins compresses margin predictability.
- Seniors:Targeted formulations addressing absorption decline and medication interactions.
- Children:Palatability-optimized delivery systems overcoming traditional pill resistance.
Adults dominate absolute consumption. Athletes exhibit the steepest expansion trajectory.
Form:
Manufacturing capital requirements and stability testing protocols diverge substantially across delivery mechanisms, with liquid formulations demanding the most stringent ANVISA documentation.
- Gummies:Gelatin and pectin-based matrices masking active ingredient bitterness through flavor engineering. Pediatric and geriatric adoption in Colombia and Peru surges as direct-sales networks overcome pharmacy distribution limitations, though tropical humidity challenges shelf-life validation.
- Pills:Compressed tablets and two-piece capsules representing the established manufacturing base. Brazil's contract manufacturing infrastructure maintains substantial tableting capacity, with immediate-release and enteric-coated variants serving distinct absorption requirements.
- Powders:Bulk actives requiring consumer preparation and dosing precision.
- Liquids:Ready-to-consume formulations with homogenization and preservative challenges.
Pills retain manufacturing dominance. Gummies gain share fastest through demographic expansion.
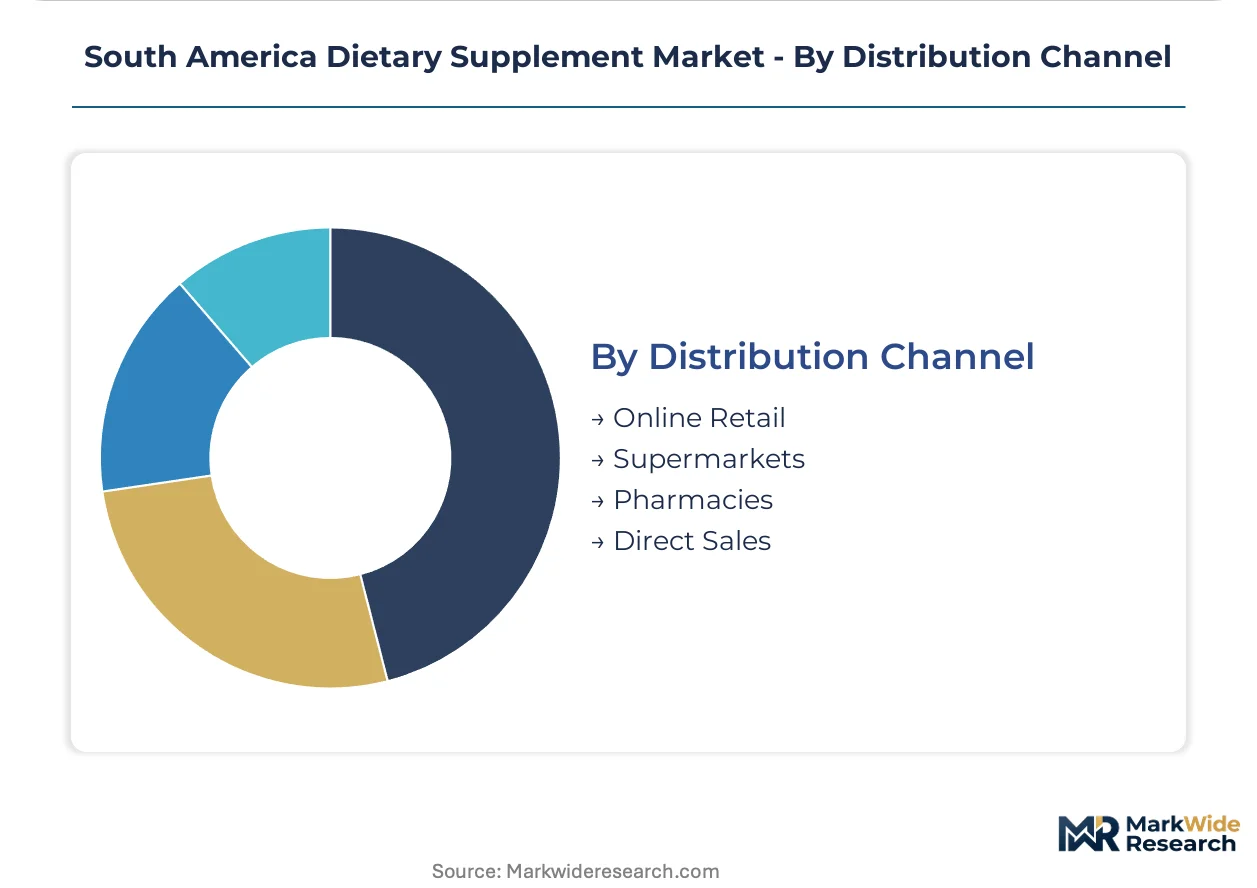
Distribution Channel:
Channel selection determines margin capture and regulatory exposure, with direct sales bypassing retail markup structures while pharmacy channels anchor clinical credibility.
- Pharmacies:Professional recommendation-driven purchases with ANVISA registration prerequisites. Brazil's pharmacy chains leverage clinical nutrition heritage to anchor institutional procurement, though supermarket private-label expansion intensifies price competition in standard vitamin categories.
- Direct Sales:Person-to-person distribution models dominating Colombia and Peru through established network structures. Herbalife's regional footprint demonstrates the model's viability for premium positioning, though regulatory scrutiny of income claims creates compliance overhead.
- Online Retail:Subscription-based replenishment capturing recurring revenue from urban professionals.
- Supermarkets:Mass-market accessibility with limited professional guidance and compressed margins.
Pharmacies lead channel volume. Direct sales expand most quickly in Andean markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for dietary supplements concentrates in Brazil's southeastern corridor, where São Paulo and Rio de Janeiro generate the majority of regional revenue. Argentina and Colombia follow as secondary markets with distinct channel preferences. Chile and Peru represent emerging frontiers with regulatory environments favoring faster product registration.
Brazil
São Paulo's urban health-conscious professionals drive premium vitamin and botanical extract consumption through pharmacy chains. ANVISA's streamlined notification pathways compress registration timelines from 24 months to under 90 days for qualifying formulations. Rio de Janeiro anchors sports nutrition demand as amateur and professional athletes expand protein isolate adoption.
Argentina
Amateur sports culture sustains specialized amino acid and recovery formulation demand among fitness enthusiasts. The national food and drug regulator enforces distinct stability documentation requirements that delay batch releases for herbal extracts. Buenos Aires concentrates mass-market vitamin penetration through supermarket private-label expansion.
Colombia
Direct-to-consumer platforms capture recurring revenue from Bogotá's urban professionals through subscription-based replenishment models. The country's health ministry maintains registration standards that favor established international brands with existing Mercosur documentation. Medellín and Cali emerging as secondary demand nodes for gummy-format pediatric supplements.
Chile
Santiago's affluent consumers exhibit accelerating interest in natural alternatives to synthetic actives, particularly yerba mate derivatives. The Ministry of Health enforces good manufacturing practice standards that determine pharmacy shelf access. Northern mining regions generate occupational health-driven demand for mineral deficiency correction products.
Peru
Person-to-person distribution networks dominate supplement access outside Lima's formal retail infrastructure. The national health authority applies simplified registration for low-risk vitamin formulations, enabling faster market entry. Andean highland cities show emerging demand for altitude-adapted nutritional support products.
South America Dietary Supplement Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical heritage companies anchoring institutional channels and direct-sales networks capturing person-to-person volume. Market structure tilts toward consolidation in pharmacy-driven Brazil while Andean markets sustain fragmented, network-based competition. Three archetypes dominate: clinical nutrition specialists leveraging hospital relationships, direct-sales operators bypassing retail margins, and regional contract manufacturers supplying private-label programs. Competitive moves center on format innovation—particularly gummy and powder delivery systems—and geographic expansion into secondary cities.
Among multinational pharmaceutical and nutrition groups, Abbott Laboratories and Bayer AG occupy positions reflecting clinical credibility and mass-market reach. Herbalife Nutrition Ltd. exemplifies the direct-sales archetype that dominates Colombian and Peruvian distribution. Brazil's Integralmedica and Pátria Suplementos represent regional specialists with localized formulation and regulatory expertise. Glanbia PLC anchors the ingredient supply tier, providing protein inputs to regional contract manufacturers.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Bayer AG |
| Herbalife Nutrition Ltd. |
| Amway Corp. |
| Glanbia PLC |
| Integralmedica |
| Pátria Suplementos |
| Medcell |
| Sanofi |
| Others |
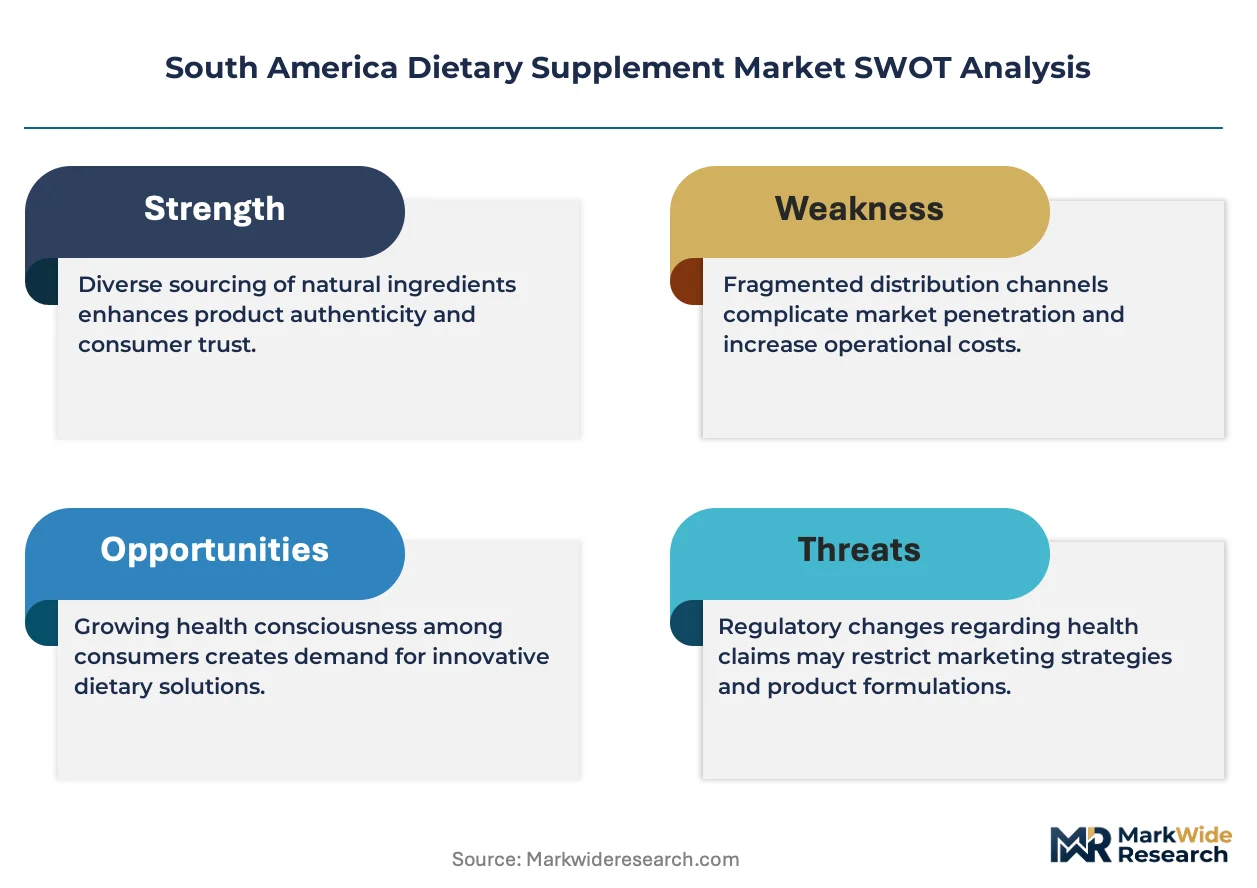
Value Network & Pricing Analysis
Pea protein isolate spot prices in Brazil's commodity exchanges cascade through formulation costs into three-tier pricing structures across premium, standard, and economy levels, with plant-based input volatility compressing margins at the mid-tier while ANVISA's streamlined registration enables premium brands to capture value through faster SKU rotation.
Pricing Analysis
Volume concentrates in pharmacy chains' private-label multivitamins where price differentiation rests on certification tier and brand heritage, while margins accrue to gummy-format specialists serving pediatric and geriatric segments. Pricing pressure stems from whey-to-plant protein transition costs that squeeze contract manufacturers. Mass-market supermarket buyers exhibit highest price sensitivity; institutional hospital procurement shows lowest.
Supply Chain Analysis
Dual-sourcing mandates from Brazil's leading pharmacy chains force contract manufacturers to qualify both Argentine and domestic peptide suppliers, extending qualification timelines. Raw material dependencies center on Chinese vitamin premixes, Indian botanical extracts, and domestic whey isolates. Single-source vulnerability concentrates in tropical-stability microencapsulation inputs. Distribution runs through São Paulo-based logistics hubs serving southeastern pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pea and rice protein concentrate availability constraints prop pricing premiums, creating a supply-constrained market structure where capacity-locked incumbents extract value from formulation agility.
For Market Incumbents: Extend gummy-format production capacity in Colombia and Peru to capture direct-sales channel growth before regulatory scrutiny tightens. Anchor hospital pharmacy contracts through clinical nutrition heritage to defend against supermarket private-label expansion. Accelerate ANVISA notification pathway expertise to compress competitor launch windows.
For New Entrants and Emerging Players: Launch via subscription-based replenishment platforms targeting Bogotá and São Paulo urban professionals with premium vitamin auto-ship programs. Exploit Peru's simplified low-risk vitamin registration to establish Andean footholds before Mercosur harmonization raises barriers. Prioritize palatability-engineered pediatric gummies in Medellín and Cali.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional contract manufacturers with ANVISA-certified tropical stability testing capabilities in Brazil's southeastern corridor. Long-term viability hinges on backward integration into plant protein processing. Monitor ANVISA registration backlog duration as inflection indicator for competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Gummy Format Capacity Expansion | Captures pediatric and geriatric demand in Colombia's direct-sales networks. |
| Backward Integration into Plant Protein Processing | Reduces exposure to pea isolate price volatility from Brazilian commodity markets. |
| ANVISA Notification Pathway Investment | Compresses launch timelines from 24 months to under 90 days for qualifying formulations. |
| Subscription Platform Development | Displaces pharmacy repurchase patterns among São Paulo urban professionals. |
| Hospital Pharmacy Contract Anchoring | Leverages clinical nutrition heritage to secure institutional procurement in Brazil. |
Research Methodology
Multi-period observation of ANVISA registration timelines, protein input cost indices, and pharmacy chain SKU velocity anchored the trend analysis, supplemented by interviews with Brazilian formulation scientists, Argentine regulatory affairs consultants, Colombian direct-sales network operators, and Peruvian health ministry officials. Secondary validation drew from ANVISA notification databases, Mercosur trade flow records, and pharmacy retail audit data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Input-output matrices mapped product type, end-user demographic, delivery form, and distribution channel dimensions across the analysis window, with value projections derived from pricing tier trajectories and volume assumptions. CAGRs were computed from segment-level growth rates weighted by base-year revenue shares. Forecast inputs incorporated ANVISA regulatory efficiency indices and plant protein substitution elasticities.
Regulatory reversal in Brazil, prolonged Mercosur harmonization failure, and tropical stability testing capacity bottlenecks are the dominant revision risks to the outlook. Deviation in ANVISA's notification processing speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
Mexico Collagen Peptides Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Canada Whey Protein Market
Nutritional Supplements
South America Nutricosmetics Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Coral Calcium Market
Nutritional Supplements
Microalgae DHA Market