
 Grass-Fed Collagen Market | 2026-2036
Grass-Fed Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Grass-Fed Collagen Market Analytics
Australia is fragmenting as new bovine hide processing capacity comes online to serve Asia-Pacific contract manufacturing. Vital Proteins LLC leverages its Amazon-native distribution to control premium shelf positioning in North American e-commerce. Gelita AG anchors European pharmaceutical-grade gelatin supply with backward integration into cattle byproduct streams. Rousselot Inc. competes through specialized enzymatic hydrolysis patents that yield lower-molecular-weight peptide fractions.
Grass-fed collagen denotes protein extracted from pasture-raised cattle and processed to preserve native amino acid ratios, particularly glycine, proline, and hydroxyproline, which support connective tissue synthesis in human nutrition. The material functions as a bioactive ingredient in functional foods, sports recovery formulations, and dermal health products where consumers prioritize provenance transparency. Hydrolyzed collagen dominates manufacturing throughput due to superior cold-water solubility, while collagen peptides command margin premiums in beauty and personal care applications where molecular weight specificity drives efficacy claims. Bovine sourcing sustains volume leadership across all channels, though poultry and marine alternatives carve niche positions in markets with religious dietary restrictions or pescatarian preferences.
The U.S. FDA oversees collagen as a food ingredient under GRAS determinations, while USDA organic certification governs pasture-raised claims that differentiate premium pricing tiers. Europe's EFSA evaluates health claim substantiation for collagen peptides marketed toward joint and skin benefits, creating compliance barriers for unsubstantiated marketing. Australia's Department of Agriculture enforces livestock traceability protocols that export-oriented processors must satisfy for market access. Stakeholders must monitor evolving clean-label enforcement intensity and decide whether to invest in third-party pasture-certification programs or absorb margin compression from commoditized uncertified supply.
Market Dynamics
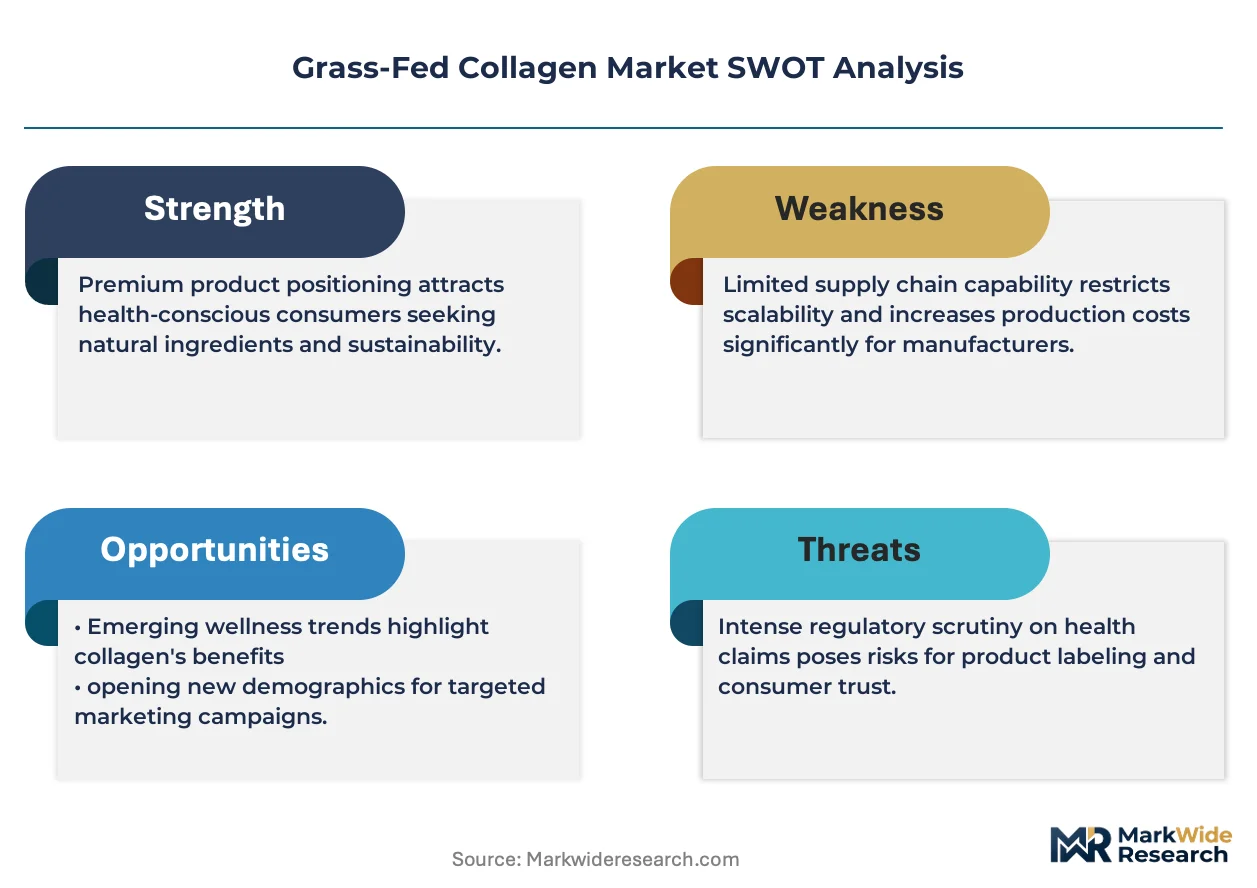
Clean-label enforcement intensity and pasture-certification program proliferation are compressing margins for uncertified suppliers while rewarding verified sourcing investments across bovine hide supply chains.
Growth Catalysts
- USDA Organic Certification:Pasture-raised verification commands shelf space premiums in North American direct-to-consumer channels where subscription velocity outperforms traditional retail.
- Sports Recovery Formulations:Clean-label protein demand from athletic nutrition brands drives hydrolyzed collagen throughput for cold-water solubility advantages.
- Enzymatic Hydrolysis Patents:Specialized processing yields lower-molecular-weight peptide fractions that unlock margin premiums in beauty and personal care efficacy claims.
Market Restraints
- Bovine Hide Input Volatility:Cattle byproduct stream availability fluctuates with beef processing cycles, squeezing gelatin supply predictability for European pharmaceutical-grade manufacturers.
- Australian Processing Fragmentation:New capacity coming online in Queensland and Victoria risks oversupply in Asia-Pacific contract manufacturing corridors.
- Marine Collagen Substitution:Pescatarian preferences and religious dietary restrictions displace bovine sourcing in Southeast Asian and Middle Eastern niche segments.
Strategic Opportunities
- Poultry Collagen White Space:Avian-sourced alternatives bypass pasture-certification complexity while capturing halal-certification-driven demand in Indonesia and Malaysia.
- Dermal Health E-Commerce:Molecular weight specificity claims enable direct-to-consumer peptide positioning outside pharmacy retail gatekeepers.
- EU Green Deal Alignment:Circular economy frameworks valorize cattle byproduct upcycling, creating regulatory tailwinds for backward-integrated processors.
Industry Challenges
- EFSA Health Claim Substantiation:Joint and skin benefit assertions require clinical dossiers that compress marketing timelines and raise compliance burn rates.
- Livestock Traceability Protocols:Australia's Department of Agriculture mandates export-oriented processors maintain chain-of-custody documentation that strains legacy ERP systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grass-Fed Collagen Market |
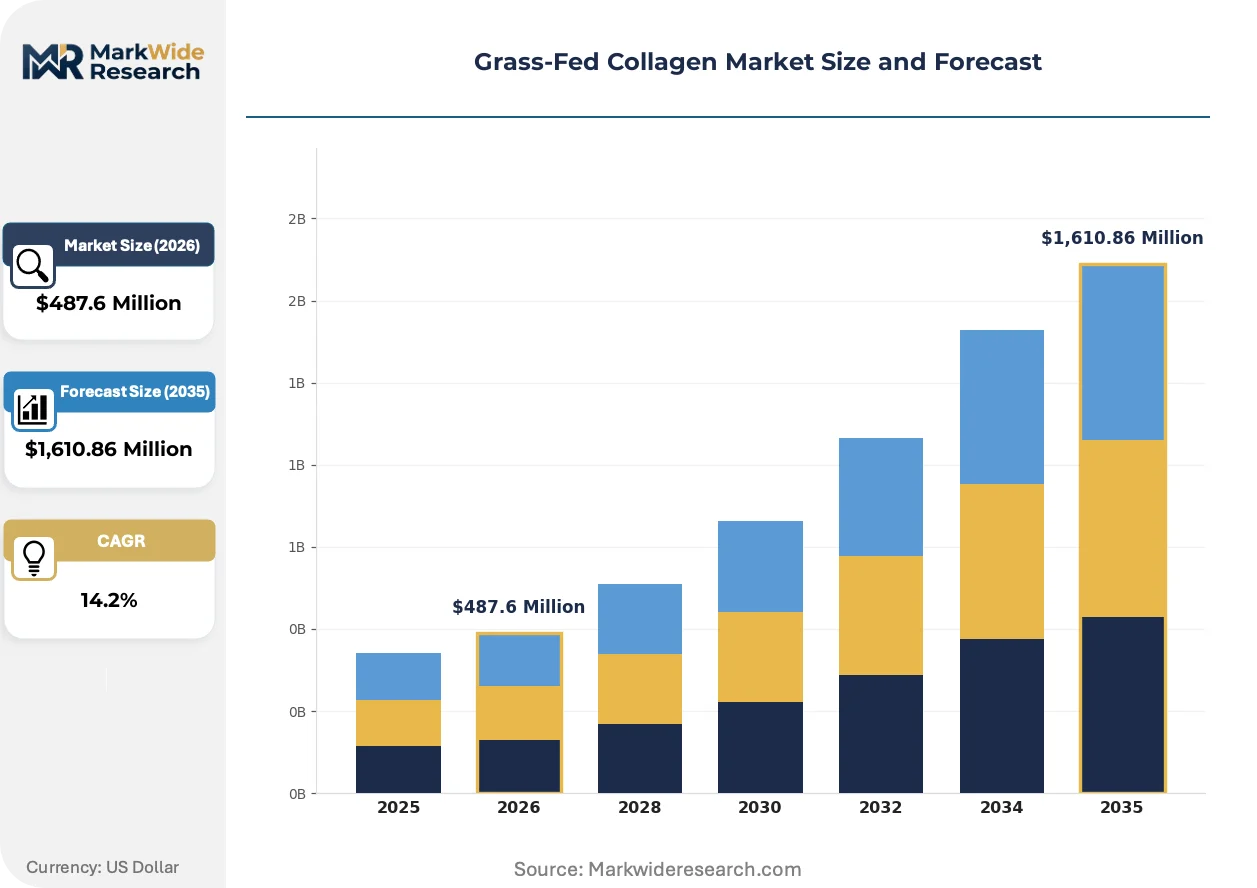
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Collagen Peptides, Gelatin, Collagen Powder End User: Sports Nutrition, Beauty And Personal Care, Functional Foods, Dietary Supplements Source: Bovine, Porcine, Poultry, Fish Distribution Channel: Online Stores, Supermarkets, Specialty Health Stores, Pharmacies |
| Companies Covered | Vital Proteins LLC, Gelita AG, Rousselot Inc., Nitta Gelatin NA Inc., Great Lakes Wellness, Ancient Nutrition, Codeage LLC, Hunter & Gather, Swisse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grass-Fed Collagen Market Evolving Landscape
Processing technology convergence and verification protocol digitization are reconfiguring competitive advantage from scale economics to provenance transparency and molecular precision.
Precision enzymatic hydrolysis is rendering obsolete conventional thermal processing for collagen peptide production. Beauty and personal care formulators now specify narrow molecular weight bands for dermal penetration claims, forcing ingredient suppliers to retool reactor configurations or surrender premium tier positioning.
EFSA's evolving health claim substantiation requirements compress marketing velocity for joint and skin benefit assertions. European nutraceutical brands must assemble clinical dossiers before commercial launch, diverting R&D budgets from formulation innovation toward regulatory defense and delaying geographic expansion timelines.
Subscription-based replenishment models displace pharmacy and mass retail distribution for routine collagen consumption. North American direct-to-consumer platforms capture higher lifetime value through automated reorder algorithms, while traditional retail velocity stagnates as buyers migrate to verified sourcing transparency available only through brand-controlled digital channels.
Grass-Fed Collagen Market Segmentation
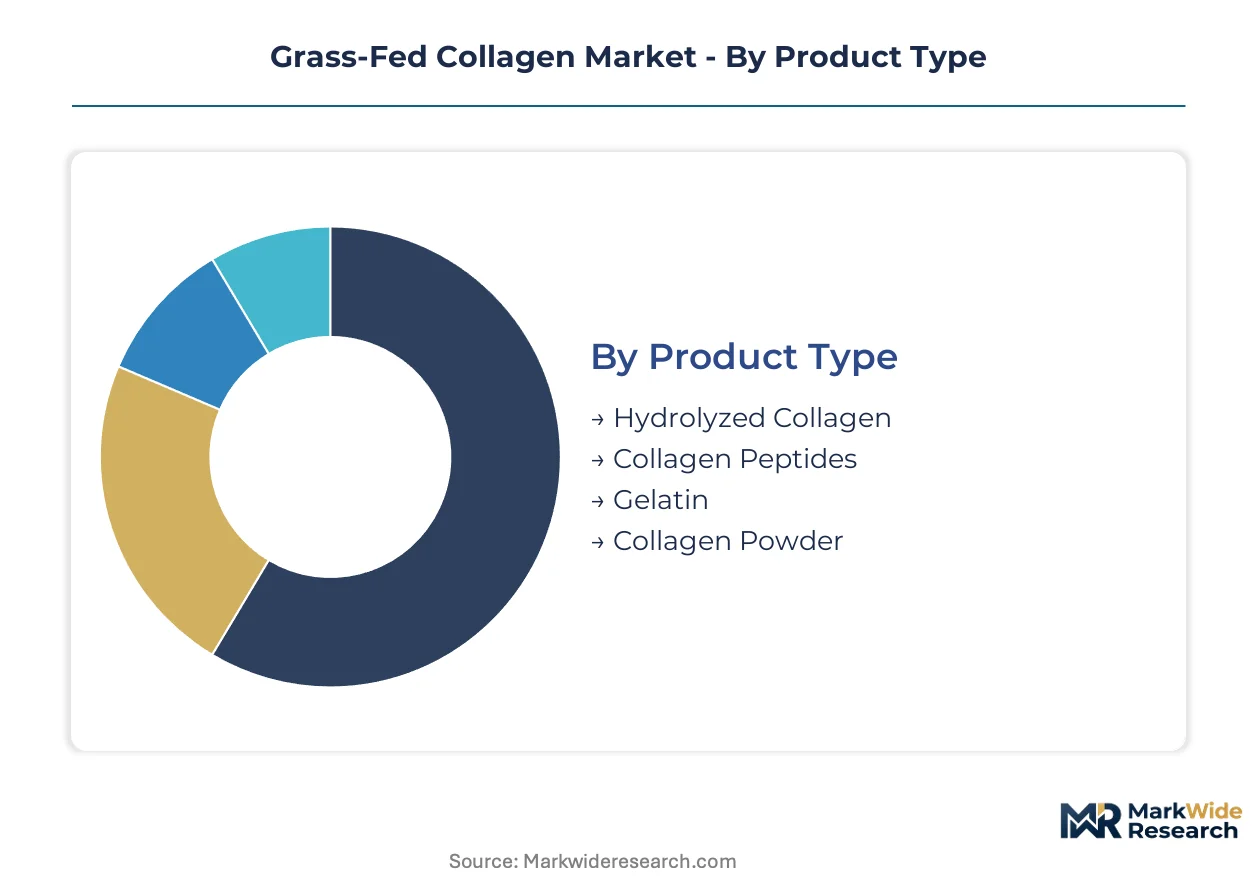
Grass-fed collagen markets fragment across processing intensity, sourcing provenance, and channel control. Each segmentation axis reveals distinct margin architectures and compliance burdens that reshape supplier positioning.
Product Type:
Mature thermal processing methods coexist with emerging enzymatic precision, creating tiered performance specifications across manufacturing outputs.
- Hydrolyzed Collagen:Partially broken protein chains achieve cold-water solubility through controlled thermal hydrolysis. Sports nutrition brands in the United States concentrate procurement here for ready-to-mix powder applications where dissolution speed determines formulation acceptance. USDA organic certification requirements add pasture-verification costs that uncertified suppliers cannot recover.
- Collagen Peptides:Enzymatic processing yields specific molecular weight fractions optimized for bioavailability claims. Beauty and personal care formulators specify narrow peptide bands for dermal penetration assertions, with EFSA health claim substantiation creating compliance barriers for unsubstantiated marketing in European markets.
- Gelatin:Higher-molecular-weight gelling agent serves pharmaceutical capsule and food texture applications.
- Collagen Powder:Unhydrolyzed native protein retains structural integrity for specialized research and industrial uses.
Hydrolyzed collagen retains volume leadership; collagen peptides hold the steepest expansion curve.
End User:
Application-driven demand splits between performance-obsessed athletic segments and appearance-focused wellness consumers with divergent purchasing rhythms.
- Sports Nutrition:Recovery-focused formulations leverage rapid amino acid absorption kinetics. North American direct-to-consumer subscription models capture repeat purchase velocity that traditional retail cannot match, with Amazon-native brands controlling premium digital shelf positioning through algorithmic replenishment.
- Beauty And Personal Care:Topical and ingestible dermal health products command molecular weight specificity premiums. EFSA clinical dossier requirements compress European launch timelines while rewarding early regulatory investment with defended positioning.
- Functional Foods:Fortified beverages and snack applications require flavor-masked, heat-stable collagen inputs.
- Dietary Supplements:Capsule and tablet formats prioritize compressibility and flow characteristics in manufacturing.
Sports nutrition retains volume leadership; beauty and personal care holds the steepest expansion curve.
Source:
Religious dietary restrictions and pasture-certification complexity fragment sourcing strategies across regional preference clusters.
- Bovine:Pasture-raised cattle hides dominate global throughput with established hide-processing infrastructure. Australia's Department of Agriculture livestock traceability protocols constrain export-oriented processors while creating verified supply premiums for compliant suppliers serving Asian contract manufacturing.
- Poultry:Avian-sourced alternatives bypass bovine pasture-certification complexity entirely. Halal-certification-driven demand in Indonesia and Malaysia accelerates capacity investment as religious dietary compliance becomes non-negotiable for market access.
- Porcine:Cost-competitive mammalian source excluded from halal and kosher markets.
- Fish:Marine collagen serves pescatarian preferences and Southeast Asian markets with established fishery byproduct streams.
Bovine retains volume leadership; poultry holds the steepest expansion curve.
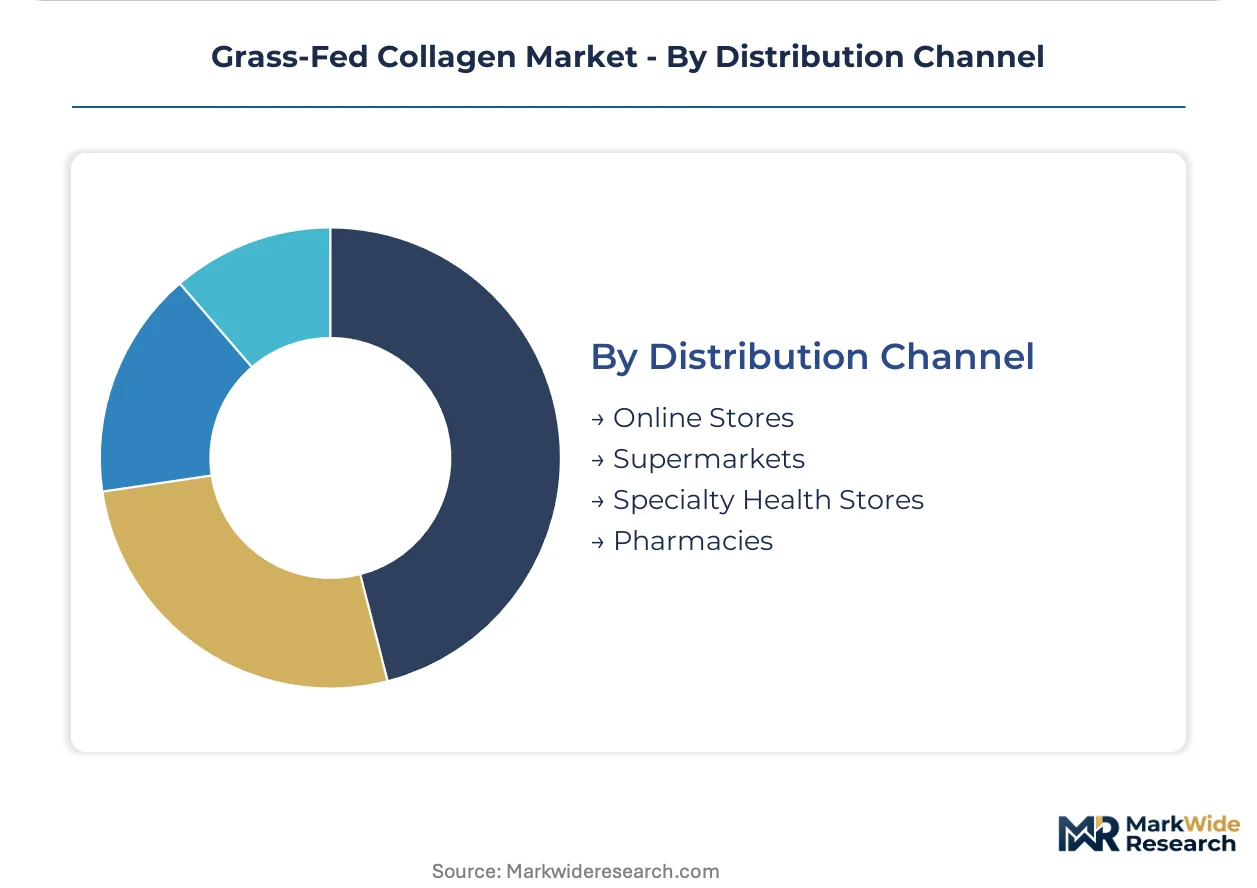
Distribution Channel:
Channel control determines margin capture, with digital-native platforms extracting lifetime value through data-driven replenishment mechanics.
- Online Stores:Brand-controlled e-commerce enables verified sourcing transparency and subscription automation. North American direct-to-consumer velocity outperforms traditional retail as buyers migrate to pasture-certification detail available only through proprietary digital channels.
- Supermarkets:Mass retail placement requires slotting fee absorption and price compression to hit mainstream price points.
- Specialty Health Stores:Curated assortment rewards third-party certification display with educated consumer self-selection.
- Pharmacies:Healthcare professional endorsement channels carry inventory carrying cost burdens and margin-sharing with retail gatekeepers.
Online stores retain volume leadership; specialty health stores hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA organic certification requirements anchor North American demand, while EFSA health claim substantiation governs European commercialization timelines. Australian livestock traceability protocols constrain Asia-Pacific supply chains. Brazil and Indonesia emerge as alternative sourcing corridors.
United States
Sports nutrition brands drive hydrolyzed collagen procurement through Amazon-native distribution platforms. The FDA oversees GRAS determinations for food ingredient applications. Subscription-based direct-to-consumer models in California and Texas capture repeat purchase velocity that traditional retail cannot match.
Germany
Pharmaceutical-grade gelatin demand concentrates in Baden-Württemberg processing clusters. The EU Green Deal valorizes cattle byproduct upcycling through circular economy frameworks. Gelita AG anchors European supply with backward integration into regional cattle byproduct streams.
Australia
Export-oriented processors in Queensland and Victoria expand bovine hide processing capacity to serve Asian contract manufacturing. The Department of Agriculture enforces livestock traceability protocols that strain legacy ERP systems. New capacity coming online risks oversupply in regional corridors.
Brazil
Halal-certification-driven demand accelerates poultry collagen capacity investment in São Paulo industrial zones. ANVISA governs ingredient safety assessments for functional food applications. São Paulo-based processors capture Indonesian and Malaysian market access through religious dietary compliance.
Indonesia
Religious dietary restrictions displace bovine sourcing in Southeast Asian niche segments. The national food and drug regulator enforces halal certification requirements for import market access. Jakarta and Surabaya processing hubs specialize in avian-sourced alternatives that bypass pasture-certification complexity.
Grass-Fed Collagen Market Competitive Landscape
Specialized enzymatic processors and scale-driven gelatin manufacturers split the market between premium peptide fractions and commodity hydrolyzed outputs. Consolidation concentrates around three strategic archetypes: Amazon-native direct-to-consumer brands, backward-integrated European pharmaceutical suppliers, and enzymatic patent holders. Dominant competitive moves include geographic expansion into Asia-Pacific contract manufacturing corridors and portfolio diversification into poultry-sourced alternatives.
Among North American direct-to-consumer specialists, Vital Proteins LLC and Ancient Nutrition exemplify subscription-model velocity capture. Gelita AG and Rousselot Inc. occupy positions within the European pharmaceutical-grade tier, representing contrasting approaches to molecular weight specificity and regional regulatory navigation.
| Leading Market Players |
|---|
| Vital Proteins LLC |
| Gelita AG |
| Rousselot Inc. |
| Nitta Gelatin NA Inc. |
| Great Lakes Wellness |
| Ancient Nutrition |
| Codeage LLC |
| Hunter & Gather |
| Swisse |
| Others |
Value Network & Pricing Analysis
Australian bovine hide processing concentration in Queensland and Victoria funnels margin capture toward enzymatic hydrolysis patent holders and Amazon-native direct-to-consumer brands, leaving commodity hydrolyzed suppliers exposed to pasture-certification cost absorption.
Pricing Analysis
North American e-commerce premiums diverge sharply from Asia-Pacific contract manufacturing rates. Subscription-based direct-to-consumer models stratify across USDA organic certified, third-party verified, and uncertified tiers. Cost compression in commodity hydrolyzed collagen intensifies as Australian capacity expansion floods regional corridors. Mass retail buyers exhibit highest price sensitivity; beauty formulators purchasing molecular-weight-specific peptides show lowest elasticity.
Supply Chain Analysis
Asia-Pacific contract manufacturers in Australia, Indonesia, and Malaysia hold expanding bovine and avian processing capacity. Raw material streams draw from cattle byproduct availability, poultry slaughterhouse output, and fishery waste recovery. Single-source vulnerability concentrates around Queensland hide processors serving export-oriented gelatin demand. Distribution runs through brand-controlled e-commerce platforms, pharmacy retail gatekeepers, and specialty health store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward Amazon-native subscription platforms and halal-certification-driven Southeast Asian procurement, fragmenting traditional pharmaceutical-grade offtake concentration.
For Market Incumbents: Pre-empt poultry collagen substitution threats by securing halal-certified avian processing capacity in São Paulo or Jakarta corridors. Anchor backward integration into cattle byproduct streams to defend margin position against enzymatic patent holders capturing peptide premiums. Prioritize USDA organic certification maintenance as uncertified suppliers face shelf-space exclusion. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's halal-certified poultry collagen white space where religious dietary compliance creates non-negotiable market access barriers for bovine incumbents. Target molecular weight specificity gaps in European beauty and personal care formulator procurement. Deploy direct-to-consumer subscription mechanics with automated replenishment algorithms to bypass pharmacy retail gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic hydrolysis equipment as precision reactor configurations commoditize. Long-term viability favors backward-integrated processors with captive cattle byproduct supply and verified pasture-certification programs. Monitor EFSA health claim substantiation approval velocity as inflection indicator for European peptide premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cattle Byproduct Streams | Gelita AG anchors European pharmaceutical-grade supply through captive hide processing in Baden-Württemberg clusters. |
| Halal Certification Program Expansion | Brazilian processors capture Indonesian and Malaysian market access through ANVISA-governed avian collagen safety assessments. |
| Direct-to-Consumer Platform Launch | Vital Proteins LLC extracts lifetime value through Amazon-native algorithmic replenishment mechanics. |
| Enzymatic Hydrolysis Patent Licensing | Rousselot Inc. defends premium positioning through lower-molecular-weight peptide fraction exclusivity. |
| USDA Organic Certification Investment | Subscription velocity in California and Texas channels rewards pasture-verification transparency with repeat purchase capture. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA GRAS determinations, USDA organic certification databases, EFSA health claim registers, and Australian Department of Agriculture livestock traceability protocols. Input sources span collagen procurement directors at sports nutrition brands, regulatory affairs leads at enzymatic processors, Amazon-native brand managers, and pharmaceutical gelatin buyers. Bottom-up demand modeling triangulates against top-down supply capacity assessments across Queensland, Victoria, São Paulo, and Jakarta processing hubs.
Forecast inputs incorporate processing technology diffusion rates, pasture-certification program proliferation trajectories, and halal certification regulatory enforcement intensity across the projection horizon. Segmentation dimensions span hydrolyzed collagen versus peptide molecular weight bands, bovine versus poultry versus marine sourcing, and direct-to-consumer subscription versus pharmacy retail channel control. CAGR derivation rests on subscription velocity capture rates and enzymatic hydrolysis capacity expansion timelines.
Sensitivities concentrate around Australian livestock traceability protocol enforcement intensity, EFSA health claim substantiation approval delays, and marine collagen substitution acceleration in Southeast Asian markets. Quarterly review of enzymatic patent expiration calendars, halal certification issuance rates, and Amazon subscription churn metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Vitamins Gummies Market
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
Asia-Pacific Nutraceutical Excipients Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Garcinia Cambogia Extract Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Europe Beta-Glucan Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Sea Moss Supplements Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Folate Market