
 Tongkat Ali Market | 2026-2036
Tongkat Ali Market Size, Share, and Industry Trends Forecast 2026-2036
Tongkat Ali Market Insights
Malaysian smallholder cooperatives is rebalancing raw root supply toward certified organic channels after years of wild-harvest depletion. Naturalin Bio Resources Co. Ltd. leverages backward integration into plantation operations across Hunan province. Changsha Herbway Biotech anchors its position through proprietary ethanol extraction protocols. AKARALI differentiates via Malaysian Medicines Advertisement Board-compliant labeling for testosterone-support positioning.
Tongkat Ali denotes Eurycoma longifolia, a Southeast Asian flowering tree whose roots yield quassinoid compounds including eurycomanone typically standardized at one to three percent in commercial extracts; manufacturers deploy spray-drying or vacuum concentration to preserve bioactive integrity for nutraceutical and traditional medicine applications. Powder formats dominate bulk ingredient trade due to lower processing overhead and extended shelf stability. Liquid extracts capture premium positioning within performance enhancement segments where rapid absorption claims support higher unit economics. Capsule formulations sustain volume growth through pharmacy and health store channels requiring dose-standardized presentation.
Malaysia's National Pharmaceutical Regulatory Agency and the U.S. FDA jointly shape export viability through Good Manufacturing Practice audits and New Dietary Ingredient notification requirements. BIS in India enforces heavy metal and microbial limits on imported botanicals entering Ayurvedic manufacturing streams. Stakeholders must monitor evolving adaptogen classification debates in European markets where EFSA novel food determinations could redirect commercialization pathways.
Market Dynamics
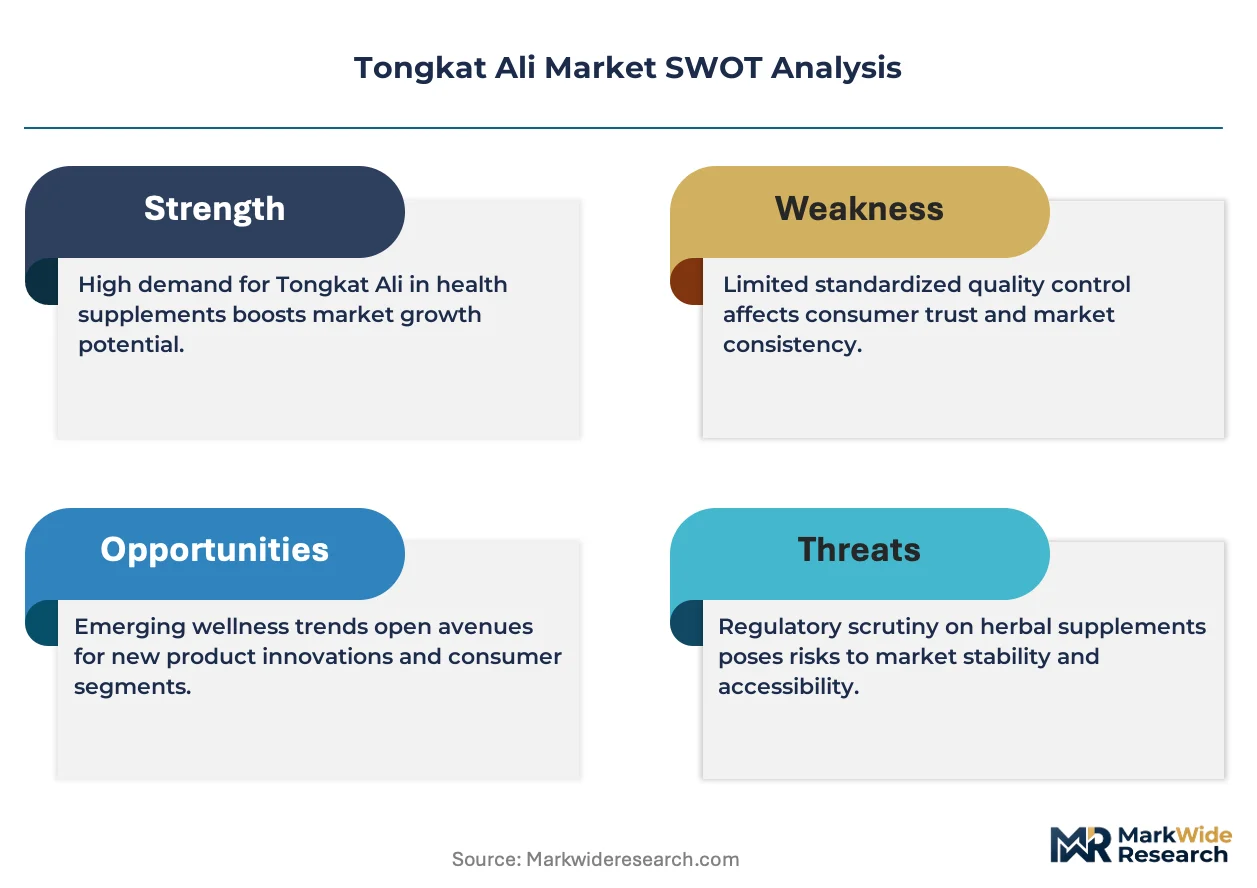
Standardized extract procurement is concentrating buyer power among nutraceutical formulators while Malaysian smallholder cooperatives pivot toward certified organic cultivation to escape wild-harvest depletion.
Growth Catalysts
- Malaysia's NPRA export certification:Mandatory quality protocols for herbal shipments unlock pharmacy and health store channels in destination markets, raising barrier entry for uncertified competitors.
- Direct-to-consumer channel expansion:North American e-commerce platforms bypass traditional distributor markups, capturing margin compression benefits for vertically integrated suppliers with compliant labeling.
- Ethanol extraction protocol refinement:Vacuum concentration and spray-drying advances preserve eurycomanone integrity at 1-3% standardization, enabling shelf-stable powder formats for bulk ingredient trade.
Market Restraints
- Wild root stock depletion:Decades of unregulated harvesting across Peninsular Malaysia has collapsed accessible mature Eurycoma longifolia populations, forcing three-to-five-year plantation maturation cycles.
- Heavy metal contamination risk:BIS microbial and heavy metal limits on imported botanicals entering Ayurvedic manufacturing streams in India reject non-compliant shipments at port.
- Synthetic testosterone substitute availability:Pharmaceutical-grade hormone replacement therapy delivers faster physiological response than botanical adaptogens, capturing performance-seeking consumers.
Strategic Opportunities
- EFSA novel food pathway:European adaptogen classification debates create first-mover advantage for extractors submitting dossiers ahead of formal determinations, preempting competitor entry.
- Liquid extract premium positioning:Rapid absorption claims in performance enhancement segments support higher unit economics than powder formats, targeting gym and athletic subcultures.
- Capsule pharmacy channel penetration:Dose-standardized presentation meets pharmacy procurement requirements in South Korea and Japan where MFDS and PMDA registration elevates professional credibility.
Industry Challenges
- Quassinoid analytical capability scarcity:HPLC standardization for eurycomanone quantification requires specialized phytochemistry expertise concentrated in contract laboratories with six-month backlog queues.
- Dual jurisdiction compliance complexity:Simultaneous NPRA GMP audits and FDA New Dietary Ingredient notifications demand parallel documentation streams, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tongkat Ali Market |
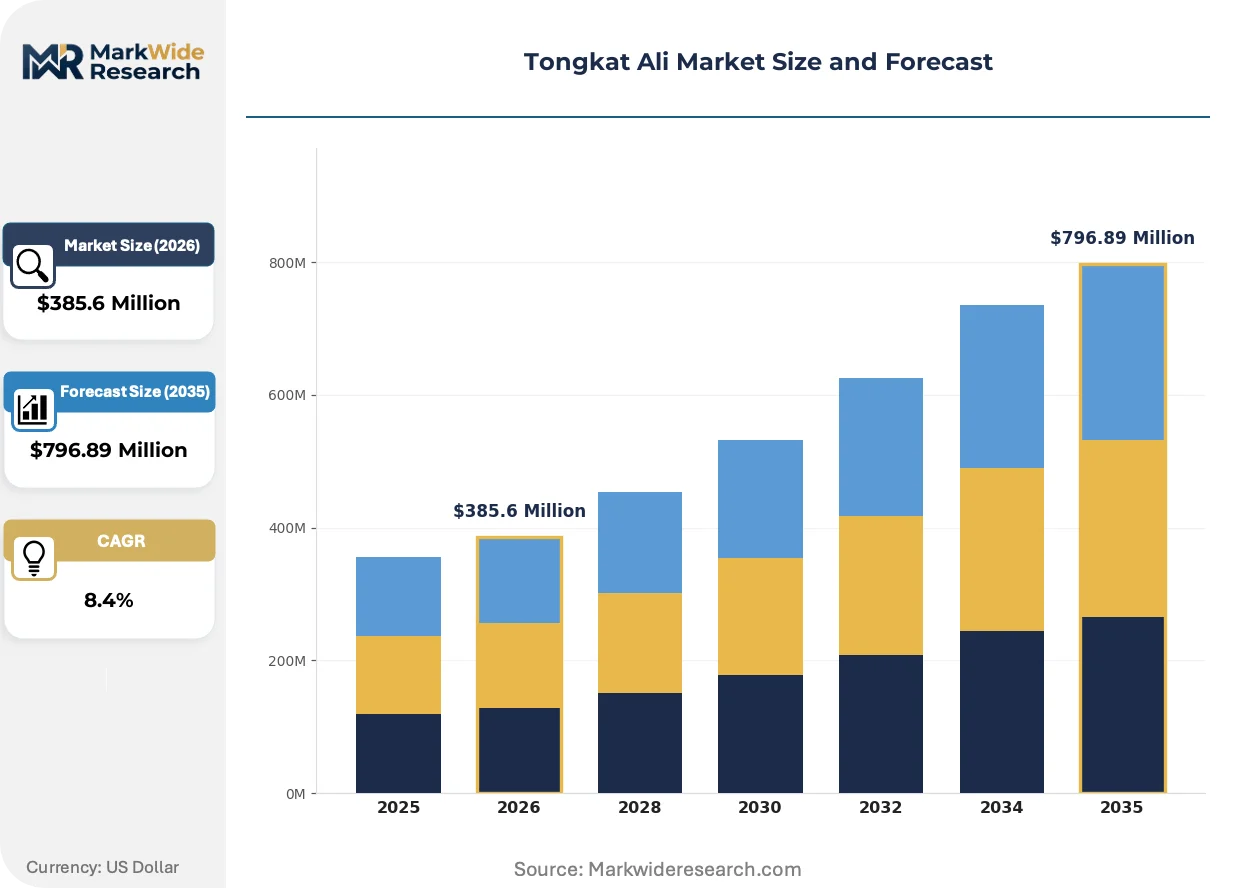
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid Extract, Tea End User: Fitness Enthusiasts, Nutraceutical Companies, Pharmacies, Health Stores Distribution Channel: Online Retail, Offline Stores, Direct Sales, Wholesale Application: Supplementation, Traditional Medicine, Performance Enhancement, Hair Care |
| Companies Covered | Naturalin Bio Resources Co. Ltd., Changsha Herbway Biotech, AKARALI, Rainforest Herbs, Masmani Sdn Bhd, Asia Botanicals Sdn. Bhd, Solaray Inc., Bixa Botanical, Hunan Huacheng Biotech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tongkat Ali Market Trends and Innovations
Extraction technology maturation and regulatory harmonization pressures are compressing the supplier base while reshaping how bioactive integrity is verified and communicated to end buyers.
Supercritical CO2 extraction equipment is consolidating mid-tier processors who previously relied on conventional solvent methods. Large nutraceutical contract manufacturers in the United States are retrofitting facilities to capture full-spectrum quassinoid profiles. This capital intensity is squeezing regional toll processors in Indonesia and Vietnam who lack depreciation capacity for stainless steel pressure vessel systems.
REACH-aligned contaminant screening is consolidating European import protocols for botanical adaptogens. EFSA guidance on novel food status is forcing extractors to compile toxicological dossiers before customs release. German and Dutch distributors are now requiring batch-level heavy metal certificates from Malaysian suppliers, shifting compliance burden upstream.
Subscription direct-to-consumer models are consolidating repeat purchase behavior away from pharmacy impulse buying. Athletic and wellness segments in Australia and Canada are locking into 90-day auto-ship programs with TGA and Health Canada-registered products. This channel shift rewards extractors with captive Malaysian plantation supply and in-house encapsulation capability.
Tongkat Ali Market Segmentation
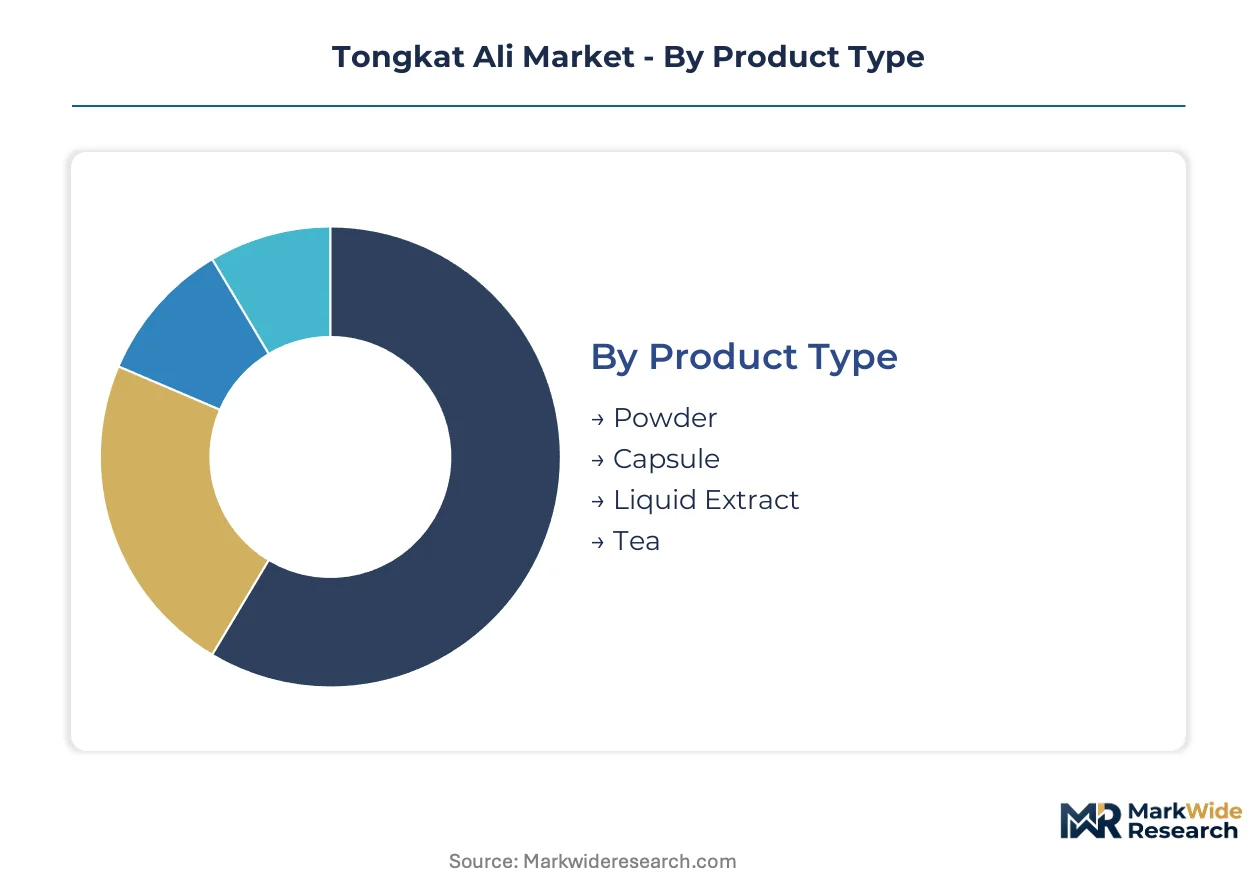
Segmentation in the Tongkat Ali market reflects divergent buyer priorities across bioactive potency requirements, regulatory compliance thresholds, and channel access economics. Formulators, retailers, and end consumers each impose distinct specification demands that reshape supplier positioning.
Product Type:
Buyers in this category differentiate primarily by processing overhead tolerance versus absorption speed requirements.
- Powder:Spray-dried or vacuum-concentrated formats with 1-3% eurycomanone standardization dominate bulk ingredient procurement due to extended shelf stability and lower unit processing costs. Demand concentrates among nutraceutical companies in the United States seeking cost-efficient encapsulation inputs, though HPLC verification queues create procurement bottlenecks.
- Liquid Extract:Ethanol-based tinctures and glycerites command premium positioning through rapid absorption claims targeting athletic subcultures. North American direct-to-consumer channels capture margin compression benefits for suppliers with Malaysian NPRA-certified captive plantation supply and in-house bottling capability.
- Capsule:Dose-standardized gelatin or vegetable cellulose shells meet pharmacy procurement requirements in Japan and South Korea where PMDA and MFDS registration elevates professional credibility above loose powder alternatives.
- Tea:Whole root or cut-and-sifted formats serve traditional medicine practitioners in Southeast Asian domestic markets with lower bioactive extraction efficiency but cultural authenticity positioning.
Powder leads volumes today; liquid extract is gaining share fastest.
End User:
Specification stringency escalates from consumer self-directed use through institutional pharmaceutical procurement.
- Nutraceutical Companies:Volume buyers requiring batch-level heavy metal certificates and quassinoid standardization documentation for FDA New Dietary Ingredient notifications. Malaysian suppliers with backward integration into certified organic plantations capture preferred vendor status.
- Pharmacies:South Korean and Japanese retail chains demand MFDS and PMDA-registered products with dose-standardized presentation, rejecting loose powder in favor of blister-packed capsules with tamper-evident sealing.
- Fitness Enthusiasts:Athletic subcultures in Australia and Canada subscribe to 90-day auto-ship programs with TGA and Health Canada-registered liquid extracts, locking in repeat purchase behavior away from impulse buying.
- Health Stores:Independent retailers in Germany and the Netherlands now require REACH-aligned contaminant screening and EFSA novel food dossier documentation before customs release, shifting compliance burden upstream to Malaysian extractors.
Nutraceutical companies anchor procurement volumes; pharmacy channel requirements are climbing the fastest.
Distribution Channel:
Margin retention and compliance documentation intensity separate channel strategies.
- Online Retail:Subscription direct-to-consumer models consolidate repeat purchase behavior through vertically integrated suppliers with compliant labeling. Athletic and wellness segments lock into auto-ship programs, bypassing traditional distributor markups.
- Wholesale:Bulk powder transactions serving contract manufacturers concentrate in Southeast Asian supply clusters with BIS-compliant heavy metal documentation for Indian Ayurvedic manufacturing streams.
- Offline Stores:Pharmacy and health store channels in Japan and South Korea require dose-standardized presentation with professional registration credentials.
- Direct Sales:Network marketing organizations target fitness enthusiasts with rapid absorption claims, though dual jurisdiction compliance complexity extends product launch timelines.
Wholesale handles the largest raw volumes; online retail is expanding most quickly.
Application:
Regulatory classification and clinical evidence thresholds determine market access pathways.
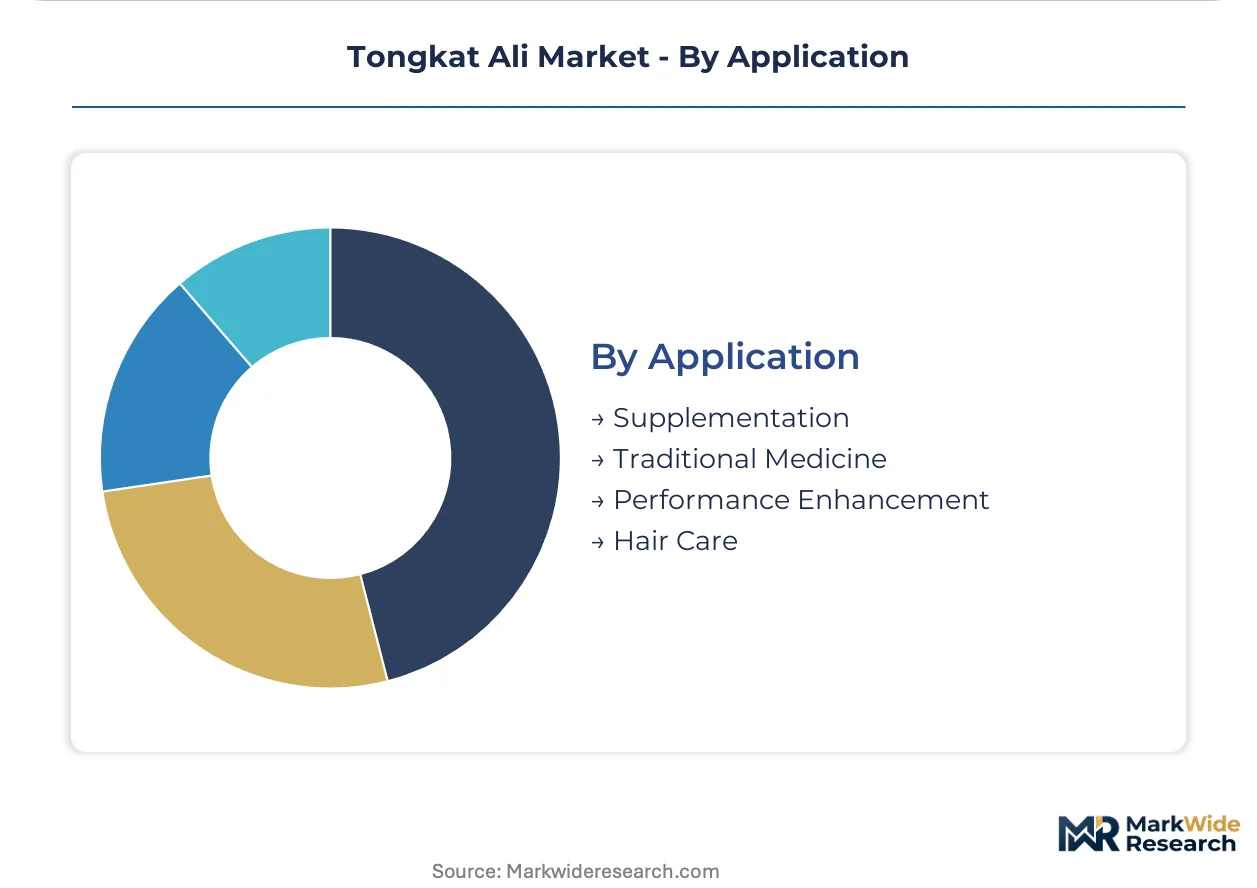
- Supplementation:General wellness positioning with testosterone-support claims requires Malaysian Medicines Advertisement Board-compliant labeling. NPRA export certification unlocks pharmacy and health store channels, raising barrier entry for uncertified competitors.
- Performance Enhancement:Athletic subculture targeting demands rapid absorption formats with higher unit economics. Liquid extracts capture premium positioning where synthetic testosterone substitute availability creates competitive pressure.
- Traditional Medicine:Whole root and tea formats serve Ayurvedic and traditional Chinese medicine practitioners with lower processing overhead but heavy metal contamination risk under BIS microbial limits.
- Hair Care:Emerging topical applications in Southeast Asian cosmetic manufacturing streams leverage quassinoid anti-inflammatory properties with less stringent bioactive standardization requirements.
Supplementation dominates current volumes; performance enhancement shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian plantation networks supply certified root stock to North American subscription channels while Chinese processors dominate solvent extraction capacity for bulk powder trade.
Malaysia
Smallholder cooperatives in Perak and Pahang states are converting wild-harvest operations to certified organic plantations. NPRA export certification mandates heavy metal and microbial testing for all herbal shipments, locking out uncertified competitors from pharmacy channels. Klang Valley processing clusters concentrate spray-drying and vacuum concentration equipment serving nutraceutical formulators in Australia and Canada.
United States
Direct-to-consumer brands capture margin compression benefits through vertically integrated supply relationships with Malaysian certified plantations. FDA New Dietary Ingredient notification requirements for testosterone-support positioning extend product launch timelines to 75 days. Utah and Colorado contract manufacturing hubs retrofit facilities for full-spectrum quassinoid extraction.
China
Hunan province plantation operators leverage backward integration into captive root supply for ethanol extraction protocol refinement. NMPA oversight of traditional medicine manufacturing streams enforces Good Manufacturing Practice audits on exported botanicals. Changsha processing clusters specialize in 1-3% eurycomanone standardization for North American bulk ingredient procurement.
South Korea
Pharmacy retail chains in Seoul and Busan demand MFDS-registered capsule formats with dose-standardized presentation and tamper-evident sealing. Fitness enthusiasts subscribe to 90-day auto-ship programs for liquid extracts with rapid absorption claims. Incheon import hubs enforce batch-level heavy metal documentation from Malaysian suppliers.
Germany
Health store retailers in Hamburg and Munich require REACH-aligned contaminant screening and EFSA novel food dossier documentation before customs release. ECHA guidance on botanical adaptogen classification forces extractors to compile toxicological data preemptively. Distributors are consolidating procurement toward Malaysian suppliers with NPRA dual certification.
Tongkat Ali Market Competitive Landscape
Malaysian plantation-integrated producers anchor one tier; Chinese solvent extraction specialists hold scale advantages in bulk powder supply. The supplier base compresses toward entities with captive cultivation assets and in-house analytical laboratories. Three archetypes dominate: vertically integrated plantation operators, toll processors with supercritical CO2 equipment, and direct-to-consumer brands with subscription logistics. Competitive moves concentrate on backward integration into certified organic cultivation and strategic partnerships with contract laboratories to clear HPLC verification backlogs.
Within the plantation-integrated tier, Naturalin Bio Resources Co. Ltd. and Changsha Herbway Biotech exemplify geographic specialization across Malaysian raw material access and Chinese processing scale respectively. AKARALI occupies a position representing regulatory-compliant positioning for testosterone-support claims through Malaysian Medicines Advertisement Board-aligned labeling. These three entities illustrate how competitive positioning separates those with upstream control over certified root supply from processors dependent on spot market procurement.
| Leading Market Players |
|---|
| Naturalin Bio Resources Co. Ltd. |
| Changsha Herbway Biotech |
| AKARALI |
| Rainforest Herbs |
| Masmani Sdn Bhd |
| Asia Botanicals Sdn. Bhd |
| Solaray Inc. |
| Bixa Botanical |
| Hunan Huacheng Biotech Inc. |
| Others |
Pricing and Supply Chain Analysis
Supercritical CO2 extraction equipment deployment is compressing processing economics while simultaneously consolidating supply toward capitalized operators with stainless steel pressure vessel depreciation capacity. Malaysian plantation operators with backward integration into certified organic cultivation capture margin expansion as toll processors in Indonesia and Vietnam face equipment obsolescence pressure.
Pricing Analysis
Capacity additions in Malaysia's Perak and Pahang plantation zones are reshaping price floors for certified organic root stock as three-to-five-year maturation cycles constrain near-term supply elasticity. Three-tier pricing structure across premium liquid extracts, standard powder formats, and economy tea-grade whole root reflects eurycomanone standardization levels and NPRA certification status. Cost compression in standard powder tiers is intensifying because Chinese processors in Hunan province leverage ethanol extraction scale advantages. Fitness enthusiasts subscribing to 90-day auto-ship programs show least price sensitivity; Ayurvedic manufacturers in India face tightest procurement budgets under BIS heavy metal compliance costs.
Supply Chain Analysis
Rejected shipments from non-compliant Malaysian suppliers feed reverse-logistics flows back through Klang Valley processing clusters for re-testing and re-export documentation. Primary supply draws from Malaysia, China, and Indonesia, with Malaysian certified plantations anchoring premium-tier procurement. Root stock extraction, quassinoid standardization testing, and encapsulation equipment form critical input dependencies. Single-source vulnerability concentrates in HPLC analytical capability with six-month backlog queues at contract laboratories. Distribution runs through vertically integrated direct-to-consumer brands bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through captive plantation supply consolidation as certified organic cultivation premiums widen over wild-harvest alternatives. Eurycomanone standardization capabilities and NPRA dual certification unlock pricing power in pharmacy channels.
For Market Incumbents: Cement backward integration into Malaysian certified organic plantations to lock root stock supply before maturation cycle constraints tighten. Fortify HPLC analytical partnerships to clear verification backlogs that stall customer shipments. Synthetic testosterone substitutes and supercritical CO2-equipped Chinese processors represent converging margin threats. NPRA export certification investment separates defendable premium positioning from commodity powder competition. For New Entrants and Emerging Players: Capture white-space in European health store channels before EFSA novel food determinations formalize and raise entry barriers. Target German and Dutch distributors requiring REACH-aligned contaminant screening where incumbent Malaysian suppliers lack documentation readiness. Liquid extract subscription models for Australian and Canadian fitness enthusiasts offer fastest penetration vector with TGA and Health Canada registration as qualifying threshold. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Malaysian plantation operators lacking in-house extraction equipment but holding NPRA-certified root stock inventory. Five-to-ten-year viability hinges on adaptogen classification clarity in European markets and sustained North American direct-to-consumer channel growth. Acquisition targets should show captive cultivation assets plus pending MFDS or PMDA registration for Japanese and South Korean pharmacy access. Monitor EFSA novel food dossier submission volumes as early signal of competitive positioning intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Plantation Acquisition | Locks certified organic root supply under NPRA protocols, eliminating spot market price volatility exposure. |
| Supercritical CO2 Equipment Deployment | Enables full-spectrum quassinoid profiles that command premium positioning against solvent-based competitors. |
| EFSA Novel Food Dossier Submission | Preempts European health store channel entry before regulatory determinations redirect commercialization pathways. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale distributor markups while capturing 90-day auto-ship loyalty in athletic segments. |
| MFDS/PMDA Registration Investment | Unlocks Japanese and South Korean pharmacy procurement requiring dose-standardized capsule presentation. |
Research Methodology
Coverage spans Malaysia, the United States, China, South Korea, and Germany, with primary inputs from each market cluster. The analysis combines structured interviews with plantation cooperative managers, nutraceutical procurement leads at contract manufacturers, regulatory affairs specialists at NPRA and FDA, and pharmacy category buyers in Seoul and Tokyo. Secondary validation draws from NPRA export certification databases, FDA New Dietary Ingredient notification filings, EFSA novel food status registers, and BIS botanical import inspection records. Bottom-up plantation yield modeling and top-down channel revenue estimates undergo triangulation against trade flow data.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. The analytical framework models product type segmentation across powder, liquid extract, capsule, and tea formats; end user segmentation across nutraceutical companies, pharmacies, fitness enthusiasts, and health stores; and application segmentation across supplementation, performance enhancement, traditional medicine, and hair care. CAGRs derive from regression against plantation maturation cycle timelines, channel shift velocity in subscription commerce, and regulatory approval queue lengths. Eurycomanone standardization adoption curves and certified organic cultivation conversion rates provide industry-specific forecast inputs.
Underlying measurement precision varies by segment; direct-to-consumer subscription channels carry tighter precision than traditional wholesale transactions due to disclosed auto-ship metrics. Forecasts reflect assumptions about NPRA certification enforcement continuity, EFSA novel food determination timing, and sustained testosterone-support positioning permissibility under FDA enforcement discretion. Practitioners should monitor EFSA dossier submission volumes, BIS rejection rate trends at Indian ports, and supercritical CO2 equipment installation announcements for early signals of competitive structure shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Brazil Whey Protein Market
Nutritional Supplements
Bee Pollen Supplements Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
Royal Jelly Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
Vitamin D Supplements Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Inositol Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
Nutritional Yeast Market