
 Low-Carb Fat Loss Market | 2026-2036
Low-Carb Fat Loss Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Carb Fat Loss Market Analytics
Millennial and Gen-Z fitness enthusiasts is rotating demand away from legacy weight watchers toward digitally native, performance-oriented consumers. Atkins Nutritionals leverages its established ketogenic brand equity to anchor shelf presence in North American specialty retailers. Nestlé S.A. competes through R&D intensity in protein-isolate formulations, while Perfect Keto differentiates via direct-to-consumer channel control and subscription-based replenishment models.
Low-carb fat loss encompasses food and beverage products engineered to contain fewer than twenty net carbohydrates per serving, typically substituting refined grains and sugars with protein isolates, fiber matrices, and alternative sweeteners to induce ketosis or caloric deficit. These formulations serve commercial purposes spanning weight management protocols, athletic body-composition programs, and convenience-driven meal replacement. Protein bars command the largest revenue pool among product types due to portability and satiety positioning, though meal replacements represent the fastest-growing segment as busy professionals replace traditional breakfast and lunch occasions. Online retail channels capture disproportionate margin expansion compared to supermarkets, where slotting fees compress profitability for emerging brands.
FDA oversees nutrition-fact-panel accuracy and health-claim substantiation for low-carb products sold in the United States, while EFSA evaluates permitted health claims under EU regulation, creating divergent compliance burdens for multinational portfolios. The FSSAI in India and China's SAMR are developing parallel frameworks for functional-food categorization that will shape market-access timelines for Western exporters. Stakeholders must monitor evolving glycemic-index labeling requirements and sugar-substitute safety reviews to anticipate reformulation mandates before they disrupt existing supply chains.
Market Dynamics
FDA nutrition-labeling reforms and EFSA health-claim frameworks are compressing formulation flexibility while simultaneously elevating compliance costs for multinational portfolios. These regulatory pressures are forcing rapid supply-chain recalibration across protein-isolate sourcing and alternative-sweetener validation protocols.
Growth Catalysts
- Ketogenic diet mainstreaming:Fitness enthusiasts in the United States and Germany are displacing conventional snacks with protein bars and meal replacements, creating pull-through demand for sub-20g net carbohydrate formulations.
- EFSA health-claim frameworks:Permitted glycemic-index and satiety claims under EU regulation are enabling premium positioning for fiber-matrix products in German and Dutch retail channels.
- Digital native replenishment models:Subscription-based direct-to-consumer platforms are capturing recurring revenue streams from millennial and Gen-Z consumers seeking convenience-driven breakfast and lunch replacements.
Market Restraints
- Protein-isolate input volatility:Whey and pea protein concentrate prices fluctuate with dairy and agricultural commodity cycles, compressing margin stability for mid-tier manufacturers.
- Alternative-sweetener safety reviews:EFSA and FDA parallel assessments of erythritol and allulose metabolic profiles are creating formulation uncertainty and inventory risk.
- Slotting fee concentration:North American supermarket chains extract disproportionate shelf-access payments that disadvantage emerging brands against established ketogenic portfolio holders.
Strategic Opportunities
- China functional-food categorization:SAMR's developing framework for low-carb product classification offers first-mover access for Western exporters meeting dual-carbon-aligned production standards.
- India FSSAI parallel frameworks:Emerging glycemic-index labeling requirements create white space for fiber-matrix meal replacements targeting urban professional cohorts in Mumbai and Bangalore.
- Precision fermentation convergence:Integration of microbial protein production with existing isolate infrastructure enables novel texture profiles and clean-label positioning in premium tiers.
Industry Challenges
- Cross-regulatory compliance talent scarcity:Formulation scientists capable of navigating simultaneous FDA, EFSA, and SAMR submission pathways command premium compensation and extended recruitment timelines.
- Supply chain reconfiguration friction:Transitioning from refined-grain to fiber-matrix and protein-isolate ingredient bases requires retooling at contract manufacturing facilities with limited capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Carb Fat Loss Market |
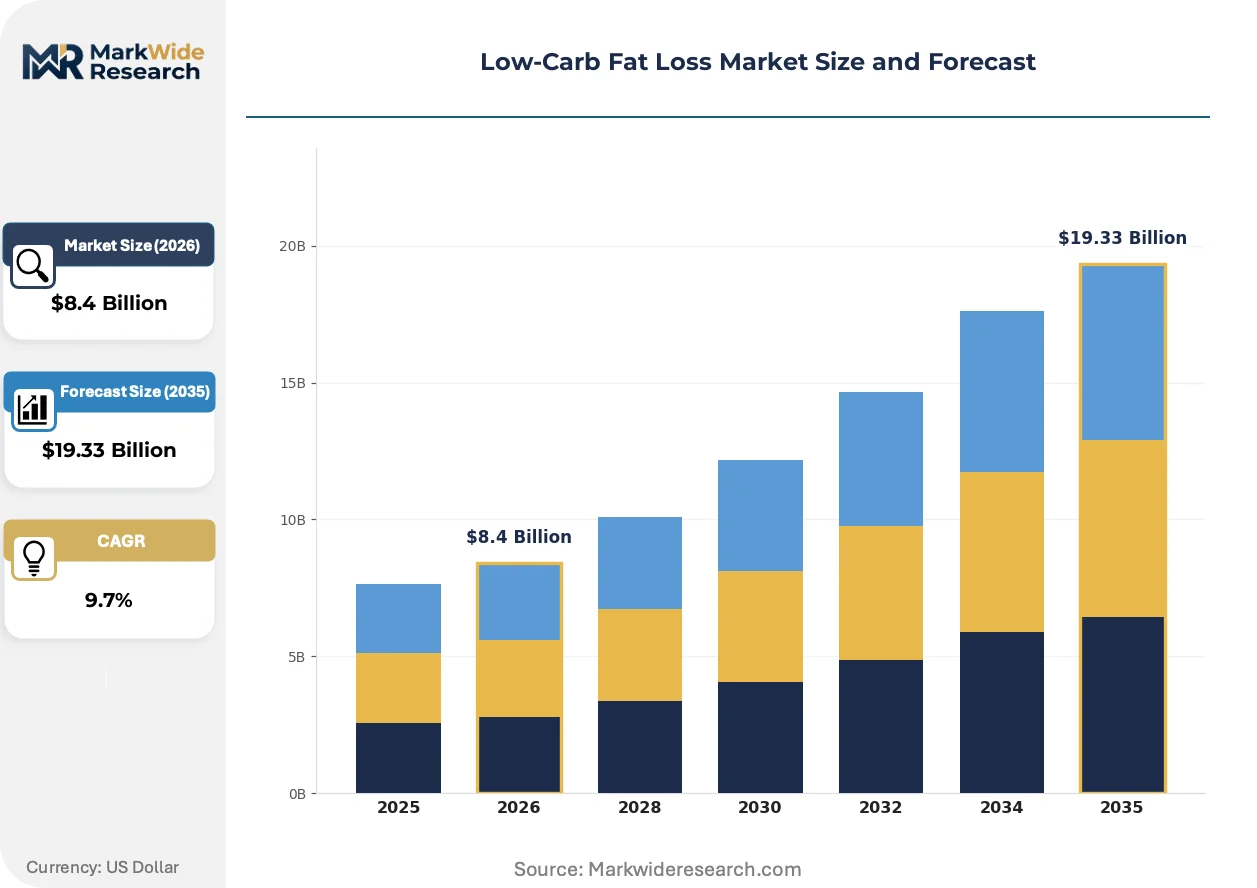
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Meal Replacements, Supplements, Snacks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores Customer Type: Fitness Enthusiasts, Weight Watchers, Athletes, General Consumers Application: Weight Management, Muscle Building, Energy Boosting, Meal Prep |
| Companies Covered | Nestlé S.A., Unilever Plc, General Mills Inc., The Kraft Heinz Company, Danone S.A., Atkins Nutritionals Inc., PepsiCo Inc., Conagra, Perfect Keto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Carb Fat Loss Market Evolving Landscape
Reformulation science and distribution architecture are undergoing simultaneous transformation as digital-native consumer acquisition models collide with tightening regulatory substantiation requirements. These intersecting pressures are compressing product development cycles while expanding the technical bar for market entry.
Precision fermentation-derived protein isolates are bifurcating the ingredient supply base between legacy agricultural extraction and biomanufactured alternatives. Early-stage adopters in athletic nutrition and clinical weight management are integrating these inputs at pilot scale. This technology is bifurcating R&D budgets toward novel texture engineering while compressing reliance on traditional dairy and legume supply chains.
EFSA's evolving substantiation requirements for glycemic-index and satiety claims are elevating clinical trial investment thresholds for European market access. Manufacturers must now commission human intervention studies to support front-of-pack positioning. Meal replacement powders and ready-to-drink formats face the steepest compliance burden as these categories carry the highest health-claim density.
Subscription-based replenishment is displacing impulse-purchase occasions in the United States and Germany as consumers automate routine nutrition decisions. Direct-to-consumer platforms capture customer-level data that enables predictive flavor and format development. This behavioral shift concentrates most visibly among millennial professionals in urban corridors seeking time-compressed meal solutions.
Low-Carb Fat Loss Market Segmentation
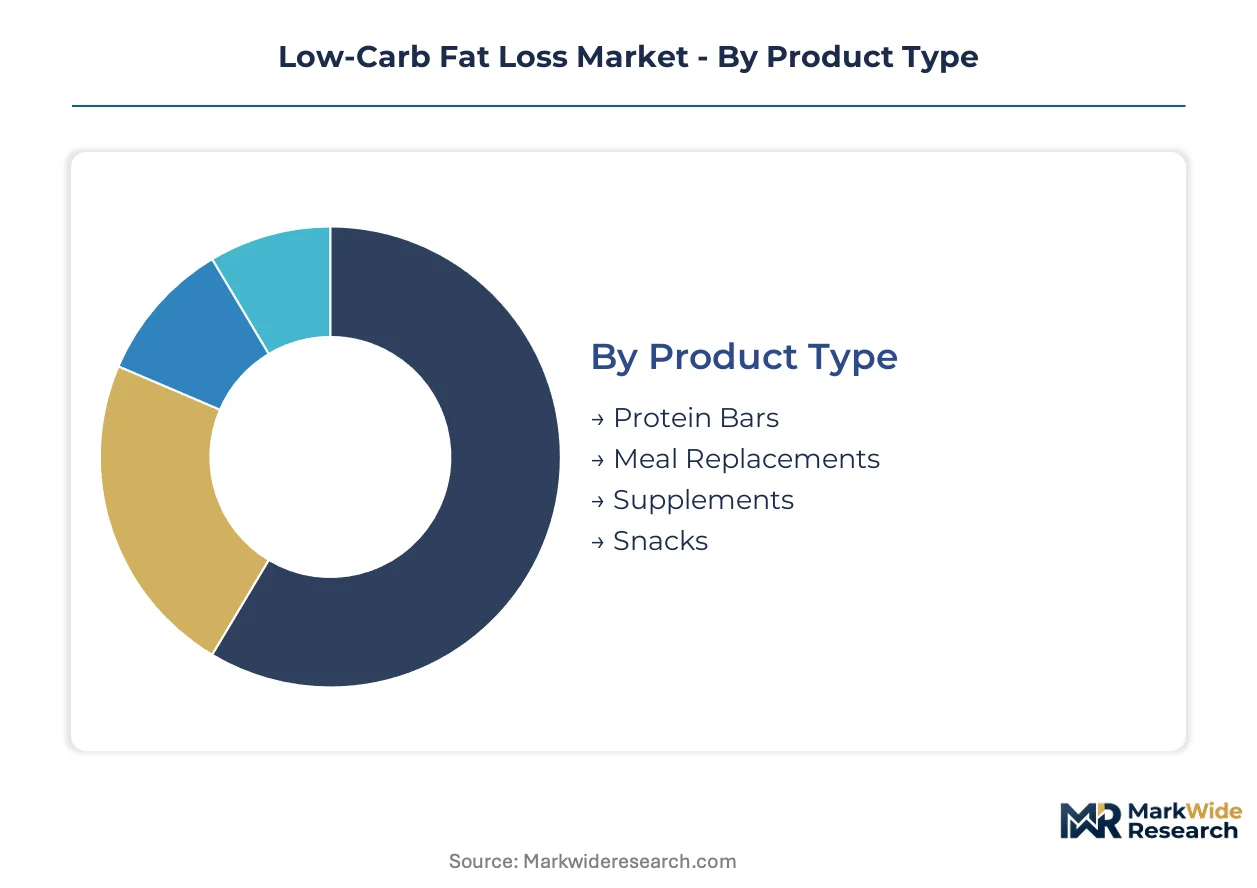
Segmentation in low-carb fat loss reveals how formulation specifications and channel economics create distinct competitive arenas. Protein-isolate concentration thresholds and net-carbohydrate ceilings determine which customer cohorts each product format can serve.
Product Type:
Channel-mix patterns show protein bars and meal replacements flowing disproportionately through online retail and specialty stores, while supplements and snacks distribute more evenly across supermarkets and health food channels.
- Protein Bars:Formulations combine whey or pea protein isolates with soluble fiber matrices and alternative sweeteners to achieve sub-20g net carbohydrate targets. Demand concentrates among fitness enthusiasts in the United States and Germany who prioritize portability and satiety between training sessions. FDA nutrition-labeling reforms are compressing formulation flexibility for front-of-pack protein claims.
- Meal Replacements:Powder and ready-to-drink formats deliver complete macronutrient profiles with controlled glycemic loads, typically 15-25g protein per serving with added micronutrient fortification. Urban professionals in China and the United States are displacing traditional breakfast and lunch occasions with these products. EFSA health-claim substantiation requirements are elevating clinical trial investment thresholds for European market access.
- Supplements:Exogenous ketones, MCT oils, and electrolyte formulations support ketosis maintenance and metabolic adaptation protocols.
- Snacks:Cheese crisps, pork rinds, and seed-based clusters serve impulse-purchase occasions with minimal carbohydrate content.
Protein bars dominate installed base. Meal replacements is where expansion concentrates.
Distribution Channel:
Margin structures diverge sharply between direct-to-consumer platforms and brick-and-mortar retail, with slotting fees in supermarkets compressing profitability for emerging brands while online channels capture disproportionate margin expansion.
- Online Retail:Subscription-based replenishment models capture recurring revenue streams and customer-level data for predictive product development. Fitness enthusiasts and millennial professionals in the United States and Germany automate routine nutrition decisions through these platforms. Digital-native brands leverage this channel to bypass slotting fee barriers.
- Supermarkets:Mass-market access requires substantial shelf-access payments that disadvantage emerging entrants against established ketogenic portfolio holders. General consumers and weight watchers in the United States drive volume through this channel. FDA nutrition-fact-panel compliance costs add friction for multinational portfolios.
- Specialty Stores:Curated assortments targeting ketogenic and paleo diet adherents with premium positioning and educated staff support.
- Health Food Stores:Independent retailers emphasize clean-label credentials and regional supplier relationships over national brand recognition.
Online retail commands the steepest margin expansion. Supermarkets retain the largest volume throughput.
Customer Type:
Application intensity varies across cohorts, with athletes and fitness enthusiasts demanding performance-verified formulations while general consumers prioritize taste and convenience over clinical substantiation.
- Fitness Enthusiasts:This cohort rotates demand away from legacy weight watchers toward digitally native, performance-oriented consumption patterns. Protein bars and meal replacements displace conventional snacks in the United States and Germany. Subscription replenishment models capture their routine-driven purchasing behavior.
- Weight Watchers:Traditional calorie-conscious consumers seeking portion-controlled solutions with established brand trust.
- Athletes:Body-composition-focused users require precise macronutrient timing and third-party certification for banned-substance testing.
- General Consumers:Convenience-driven buyers entering low-carb categories through mainstream retail exposure and influencer recommendations.
Fitness enthusiasts is gaining share fastest. Weight watchers retains the largest historical installed base.
Application:
End-use specifications determine formulation architecture, with weight management protocols requiring caloric deficit engineering and muscle building demanding complete amino acid profiles.
- Weight Management:Caloric deficit protocols leverage protein-induced thermogenesis and fiber-matrix satiety signaling to reduce ad libitum intake. Demand concentrates among urban professionals in China and India seeking convenient meal solutions. FSSAI emerging glycemic-index labeling requirements create compliance preparation windows.
- Muscle Building:Leucine-threshold protein dosing and peri-workout carbohydrate timing support hypertrophy goals with minimal fat accumulation. Athletes in Germany and the United States drive premium-tier demand. EFSA permitted health claims enable front-of-pack positioning for recovery-focused formulations.
- Energy Boosting:MCT and exogenous ketone formulations target cognitive performance and sustained fuel availability.
- Meal Prep:Batch-cooking convenience drives powder format adoption for planned nutrition scheduling.
Weight management dominates current application share. Muscle building is where premium pricing concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles and Long Beach complex anchors trans-Pacific distribution for protein-isolate imports serving West Coast formulation facilities. Germany's Rhine-Alpine corridor rail freight network enables just-in-time ingredient delivery to Dutch and Swiss contract manufacturers. China's Ningbo-Zhoushan port cluster handles bulk alternative-sweetener shipments for Yangtze River Delta processing plants.
United States
Fitness enthusiasts in California and Texas displace conventional snacks with protein bars and meal replacements, driving sub-20g net carbohydrate formulation demand. FDA nutrition-labeling reforms compress front-of-pack claim flexibility while elevating compliance costs for multinational portfolios. The Chicago metropolitan area concentrates contract manufacturing capacity for powder and ready-to-drink formats serving national distribution.
Germany
EFSA-permitted glycemic-index claims enable premium positioning for fiber-matrix products in Frankfurt and Munich retail channels. REACH-aligned ingredient validation protocols create compliance preparation windows for alternative-sweetener suppliers. The Cologne-Düsseldorf corridor hosts specialized logistics infrastructure for temperature-controlled protein-isolate storage and distribution.
China
Urban professionals in Shanghai and Beijing automate breakfast and lunch occasions through subscription-based meal replacement platforms. SAMR's developing functional-food categorization framework shapes market-access timelines for Western exporters meeting dual-carbon-aligned production standards. The Shenzhen manufacturing cluster supplies packaging materials and contract filling capacity for domestic and export-bound brands.
India
FSSAI emerging glycemic-index labeling requirements create white space for fiber-matrix meal replacements targeting Mumbai and Bangalore urban professional cohorts. The country's national food regulator develops parallel frameworks for functional-food classification that will shape import protocols. Hyderabad's pharmaceutical-grade manufacturing base offers contract production capabilities for clinical-nutrition-tier formulations.
United Kingdom
Digital-native replenishment models capture recurring revenue from London-based millennial professionals seeking time-compressed nutrition solutions. MHRA-aligned border inspection protocols for novel food ingredients create inventory planning complexity for continental suppliers. The Midlands distribution hub concentrates cold-chain logistics capacity for perishable low-carb ready-meal formats.
Low-Carb Fat Loss Market Competitive Landscape
Concentration sits with diversified multinational conglomerates possessing established ketogenic portfolio equity and shelf-access relationships. Tiered competitive structure separates legacy packaged-food conglomerates from digitally native direct-to-consumer specialists and clinical-nutrition-grade formulators. Strategic moves center on protein-isolate sourcing partnerships and precision fermentation technology licensing to secure next-generation ingredient supply.
Within the legacy conglomerate tier, Nestlé S.A. and Unilever Plc occupy positions defined by R&D intensity and global distribution infrastructure. Atkins Nutritionals Inc. exemplifies established ketogenic brand equity leveraged for North American specialty retail presence. Among direct-to-consumer specialists, Perfect Keto represents subscription-based replenishment models capturing recurring revenue from fitness-oriented cohorts. PepsiCo Inc. and General Mills Inc. anchor mass-market penetration strategies through supermarket channel dominance and impulse-purchase format development.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Unilever Plc |
| General Mills Inc. |
| The Kraft Heinz Company |
| Danone S.A. |
| Atkins Nutritionals Inc. |
| PepsiCo Inc. |
| Conagra |
| Perfect Keto |
| Others |
Value Network & Pricing Analysis
FDA nutrition-labeling reforms gate both supplier qualification and price differentiation simultaneously, compressing formulation flexibility for emerging brands while elevating compliance costs that tier manufacturers by certification tier. This regulatory architecture concentrates pricing power with established ketogenic portfolio holders who absorb front-of-pack claim validation expenses.
Pricing Analysis
Volume-discount tiering structures separate subscription-based direct-to-consumer replenishment from mass-market supermarket transactions, with digital-native brands capturing recurring revenue premiums. Three-tier pricing structure across premium, standard, and economy levels reflects protein-isolate concentration thresholds and glycemic-index certification status. Cost compression in mid-tier formulations is intensifying because whey and pea protein concentrate prices fluctuate with agricultural commodity cycles. Fitness enthusiasts demonstrate lowest price sensitivity due to performance-verified formulation demands, while general consumers entering through mainstream retail exhibit highest elasticity.
Supply Chain Analysis
The United States and Germany anchor protein-isolate extraction and formulation capacity, while China dominates alternative-sweetener production and packaging material supply. Whey protein concentrates, pea protein isolates, and erythritol draw from dairy cooperatives, legume processors, and fermentation facilities respectively. Single-source vulnerability concentrates in precision fermentation-derived protein inputs where commercial-scale capacity remains limited. Distribution runs through direct-to-consumer platforms for premium tiers and supermarket wholesale networks for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-carb fat loss market is entering a cyclical recovery phase as protein-isolate input costs stabilize following agricultural commodity volatility. Fitness enthusiast demand rotation toward performance-oriented formulations provides the cyclical driver justifying repositioning.
For Market Incumbents: Secure precision fermentation technology licensing agreements to de-risk protein-isolate supply concentration, while expanding contract manufacturing capacity in the Chicago metropolitan area to capture meal replacement powder demand growth. Nestlé S.A. and Atkins Nutritionals must defend against digitally native subscription competitors by tightening direct-to-consumer channel control. For New Entrants and Emerging Players: Subscription-based replenishment service gaps in India and China offer white-space entry where FSSAI and SAMR frameworks remain under development. Target urban professional cohorts in Mumbai and Bangalore with fiber-matrix meal replacements positioned for emerging glycemic-index labeling requirements. Go-to-market leverage rests on bypassing supermarket slotting fees through digital-native acquisition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer specialists possessing established subscription infrastructure but limited formulation R&D depth. Long-term viability across the projection horizon favors targets with dual FDA-EFSA submission capabilities and precision fermentation pilot partnerships. Monitor EFSA alternative-sweetener safety review outcomes as inflection indicator for inventory risk exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Microbial protein production integration enables novel texture profiles and clean-label positioning in premium tiers. |
| Direct-to-Consumer Channel Expansion | Subscription-based replenishment captures recurring revenue from millennial professionals automating routine nutrition decisions. |
| Dual-Jurisdiction Regulatory Submission | Simultaneous FDA and EFSA compliance pathways accelerate market access across North American and European retail channels. |
| Alternative-Sweetener Inventory Hedging | Parallel erythritol and allulose sourcing mitigates formulation uncertainty from ongoing metabolic safety reviews. |
| Urban Professional Cohort Targeting | Time-compressed meal solutions in Shanghai and Beijing displace traditional breakfast and lunch occasions. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain participant interviews anchors the qualitative findings. Primary fieldwork engaged formulation scientists at contract manufacturing facilities, procurement leads at protein-isolate suppliers, category buyers at specialty retailers, and regulatory affairs directors navigating FDA and EFSA submission pathways. Secondary sources encompassed FDA nutrition-labeling guidance documents, EFSA health-claim substantiation databases, customs records for protein-isolate trade flows, and SEC 10-K disclosures from diversified food conglomerates. Bottom-up product-format sizing and top-down macroeconomic anchoring provided triangulation checks.
Sensitivity analysis tested projection robustness across alternative protein-isolate price scenarios and regulatory timeline assumptions. Segmentation modeling spanned product type, distribution channel, customer archetype, and application intensity across the analysis window. CAGR derivation incorporated historical volume trajectories, cohort-specific adoption curves, and channel-mix evolution. Industry-specific inputs included precision fermentation capacity buildout schedules and FSSAI framework development milestones.
Underlying assumptions cover protein-isolate supply stabilization and EFSA glycemic-index claim substantiation pathways, with deviation risk concentrated in alternative-sweetener safety review outcomes and SAMR functional-food classification timing. Forecasts reflect these documented conditions with acknowledged sensitivity to agricultural commodity cycles and cross-regulatory compliance talent scarcity. Recalibration cycles align with material shifts in FDA labeling enforcement intensity and precision fermentation commercial-scale deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Europe Nutrition and Supplements Market
Nutritional Supplements
Canada Whey Protein Market
Nutritional Supplements
Fish Collagen Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Omega-3 Products Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Whey Protein Market
Nutritional Supplements
Green Food Supplements Market
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
Mineral Supplements Market