
 North America Wheat Protein Ingredients Market | 2026-2036
North America Wheat Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wheat Protein Ingredients Market Analytics
A capital-intensity divergence between integrated millers and specialty ingredient developers is redrawing competitive boundaries in the North America Wheat Protein Ingredients Market. Archer Daniels Midland Company leverages its grain origination network and captive processing assets across the U.S. Plains to secure cost-advantaged wheat gluten supply. Cargill Incorporated sustains downstream formulation partnerships with bakery and meat-alternative manufacturers that lock in multi-year offtake commitments. MGP Ingredients Inc. specializes in high-purity wheat protein isolates for beverage and dairy-alternative applications, occupying a narrower but defensible niche.
Wheat protein ingredients comprise functional protein fractions extracted from wheat flour through wet-processing or dry-milling separation, with gluten fractions typically exceeding 75% protein content on a dry basis and exhibiting viscoelastic properties critical to dough structure and meat-analog texture. Wheat gluten dominates volume flows into commercial bakery operations, where its film-forming and gas-retention capabilities remain irreplaceable at industrial scale. Textured wheat protein registers the fastest application expansion as meat-alternative brands reformulate for cleaner-label positioning, while hydrolyzed wheat protein concentrates command premium positioning in beverage fortification despite smaller absolute volumes.
FDA food allergen labeling mandates and USDA organic certification standards constrain formulation flexibility and elevate compliance costs for cross-contaminated production lines. Health Canada and CFIA parallel requirements for protein content claims and novel food notifications add friction to product introductions targeting the Canadian market. Stakeholders must monitor evolving plant-protein tariff classifications and biotech wheat regulatory thresholds that could abruptly alter raw material access economics.
Market Dynamics
Plant-based meat reformulation is compressing ingredient specification windows across North American wheat protein supply chains, forcing simultaneous upgrades in protein purity, flavor neutrality, and functional consistency.
Growth Catalysts
- FDA Food Allergen Labeling and Consumer Protection Act:Mandatory wheat allergen declarations have standardized disclosure protocols, reducing liability friction for bakery and meat-alternative manufacturers expanding product lines.
- Midwest milling infrastructure concentration:Kansas and Nebraska processing clusters provide captive wheat supply access that lowers logistics costs for gluten extraction operations serving industrial bakeries.
- Textured protein extrusion technology:Twin-screw extrusion advances enable meat-analog producers to achieve fibrous textures without soy, redirecting formulation budgets toward wheat-derived alternatives.
Market Restraints
- Hard red winter wheat price volatility:Drought cycles across the U.S. Southern Plains create input cost instability that compresses margin predictability for specialty ingredient processors.
- Supply concentration in U.S. Plains:Over-reliance on Kansas, Oklahoma, and Texas origination points creates geographic vulnerability to localized weather events and transportation bottlenecks.
- Gluten-free substitution momentum:Almond, pea, and rice protein isolates capture clean-label positioning in premium bakery segments, constraining wheat protein penetration in high-margin niches.
Strategic Opportunities
- Canadian Prairie expansion:Saskatchewan and Manitoba wheat production growth offers underutilized processing capacity for isolate production targeting Health Canada novel food notification pathways.
- Beverage fortification applications:Hydrolyzed wheat protein concentrates achieve solubility thresholds that unlock sports nutrition and ready-to-drink dairy alternative formulations.
- USDA BioPreferred program:Federal procurement preferences for biobased ingredients create dedicated offtake channels for wheat protein in industrial adhesives and biodegradable packaging films.
Industry Challenges
- Protein functionality certification timelines:CFIA novel food assessments for modified wheat proteins extend product launch cycles by months, delaying revenue recognition for Canadian market entries.
- Cross-contamination control capex:Dedicated allergen-free production lines require seven-figure capital commitments that strain mid-scale processors competing against integrated millers.
- Extrusion operator skill scarcity:Specialized knowledge in screw configuration and thermal profile optimization for textured protein production commands premium wages that inflate manufacturing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wheat Protein Ingredients Market |
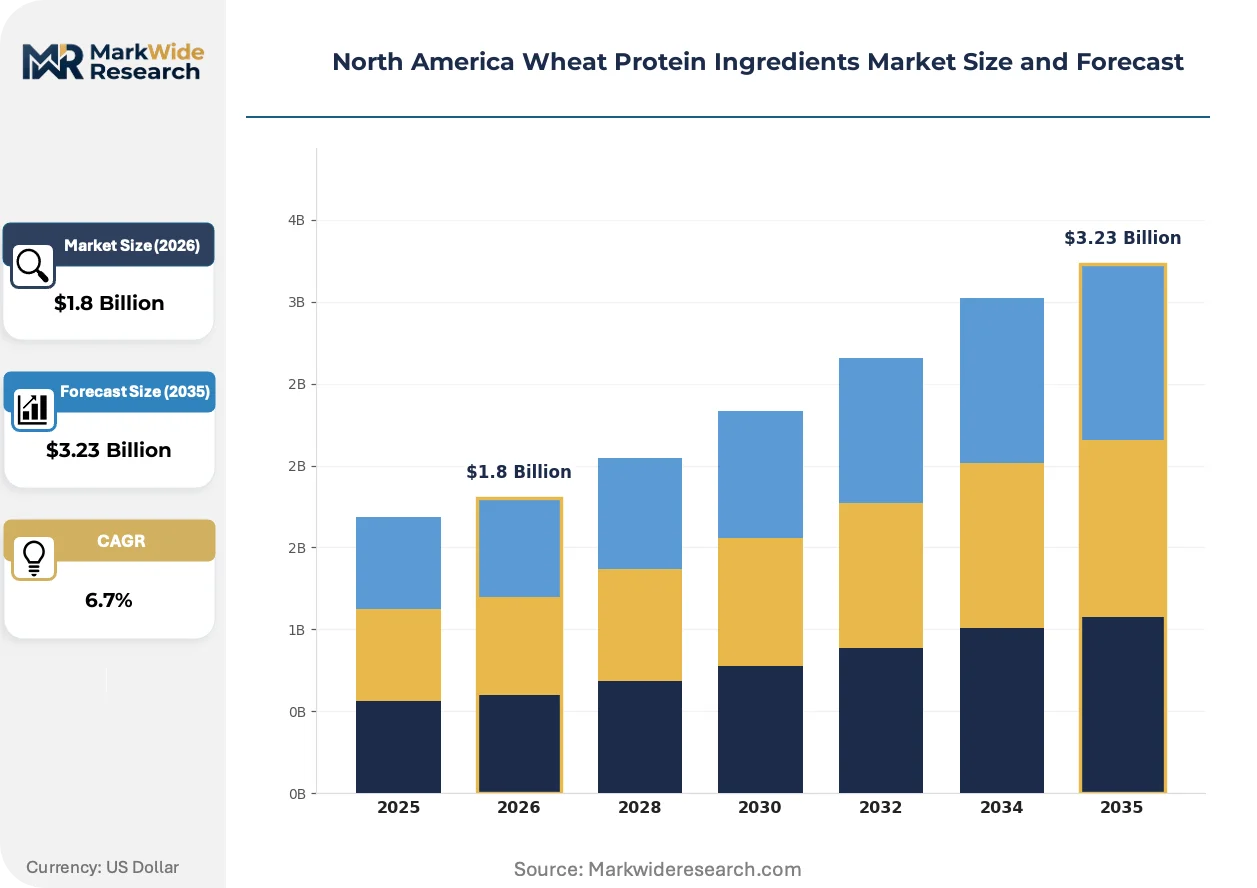
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Wheat Protein, Wheat Gluten, Textured Wheat Protein, Native Wheat Protein Application: Bakery, Meat Alternatives, Dairy Alternatives, Snacks End User: Food Manufacturers, Beverage Producers, Health Food Brands, Retail Form: Powder, Granules, Liquid, Concentrate |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Kerry Group PLC, MGP Ingredients Inc., Roquette Frères, Tereos, The Scoular Company, Manildra Group, Crespel & Deiters, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wheat Protein Ingredients Market Evolving Landscape
Clean-label imperatives are compressing ingredient lists while elevating protein functionality requirements, creating technical tension between simplicity and performance that suppliers must resolve through process innovation rather than additive solutions.
Membrane filtration technology for wheat protein isolate recovery is miniaturizing. Food-grade ceramic and polymeric membranes now achieve 90%+ protein separation efficiency at pilot scale, enabling regional processors to deploy modular units without centralized capital commitments. Mid-scale bakery ingredient suppliers in Minnesota and Iowa are adopting these systems to bypass tolling arrangements with integrated millers, compressing supply chain tiers from three to two.
Health Canada updated its Guidance on Novel Food Information Requirements for Plant-Based Proteins in late 2023, mandating expanded digestibility and allergenicity data for wheat protein ingredients entering the Canadian market. This regulatory tightening extends pre-market notification timelines and elevates analytical testing costs for U.S. exporters. Smaller specialty processors are responding by partnering with Canadian contract research organizations to establish domestic safety dossiers rather than relying on U.S. equivalency arguments.
Direct procurement relationships between meat-alternative brands and wheat protein processors are displacing traditional ingredient distributor intermediaries. Impossible Foods and Beyond Meat have established captive supply agreements with MGP Ingredients and ADM that bypass regional foodservice distributors, compressing margin pools and forcing distributor consolidation. This channel shift is most visible in California and Illinois, where alternative protein R&D clusters concentrate purchasing power among a handful of large formulation buyers.
North America Wheat Protein Ingredients Market Segmentation
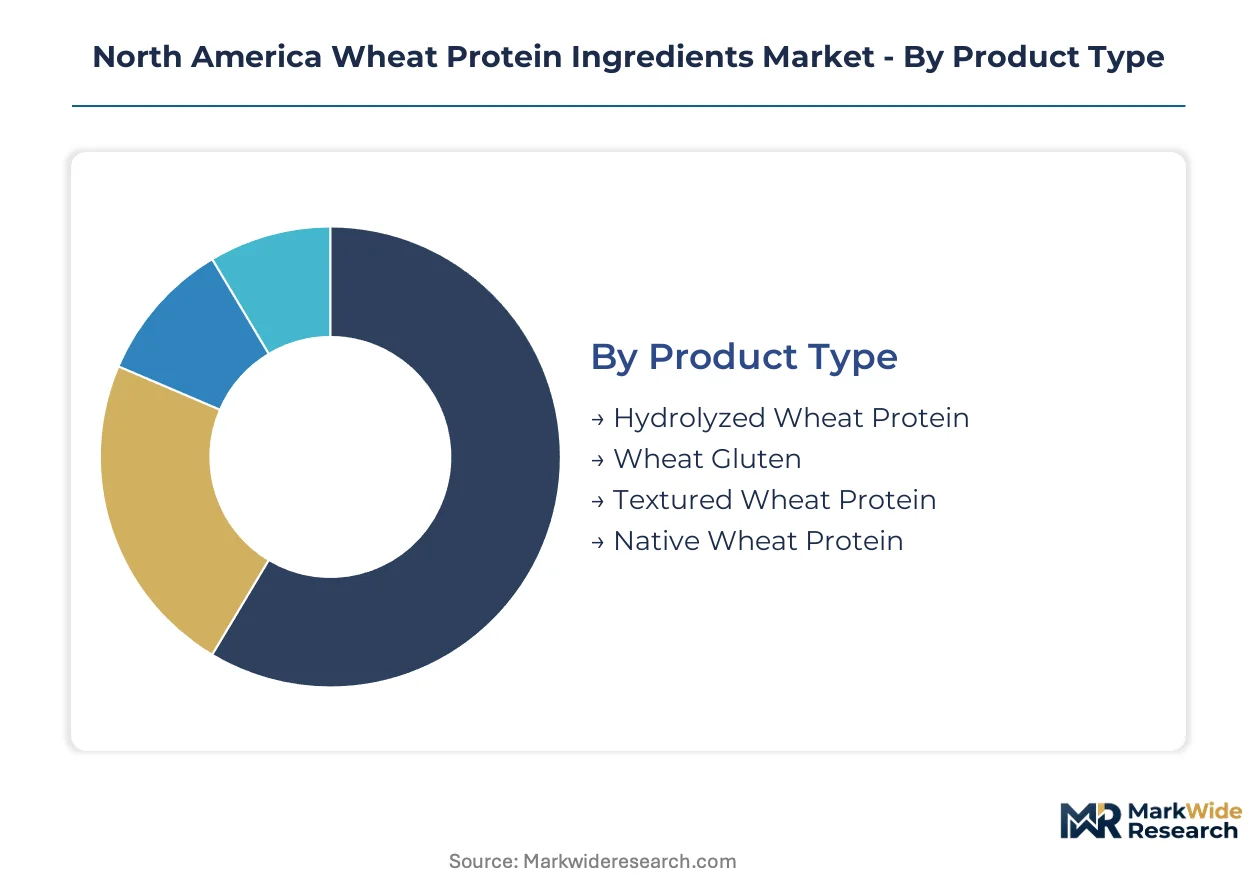
Wheat protein ingredients flow through distinct channel configurations depending on product form and end-use specifications. Segmentation reveals where formulation complexity, regulatory thresholds, and procurement scale reshape supplier-customer relationships across North American supply chains.
Product Type:
Channel mix varies sharply by protein fraction: wheat gluten moves predominantly through industrial bakery distributors, while textured and hydrolyzed variants increasingly ship direct to meat-alternative and beverage manufacturers.
- Wheat Gluten:Viscoelastic protein fractions exceeding 75% protein content on a dry basis, extracted through wet-processing of hard red winter wheat flour. Demand concentrates in U.S. Midwest industrial bakeries where gas-retention and film-forming properties remain irreplaceable for high-volume bread production. Kansas and Nebraska milling clusters provide captive supply access that compresses logistics costs for gluten extraction operations.
- Textured Wheat Protein:Extruded protein structures achieving fibrous textures through twin-screw thermal processing, enabling meat-analog applications without soy dependency. Expansion concentrates in California and Illinois alternative protein R&D clusters where Impossible Foods and Beyond Meat have established direct procurement relationships bypassing traditional distributors.
- Hydrolyzed Wheat Protein:Enzymatically cleaved peptide fractions with enhanced solubility for beverage fortification applications.
- Native Wheat Protein:Unmodified protein fractions retaining natural functional properties for clean-label bakery formulations.
Wheat gluten dominates installed base. Textured wheat protein is where expansion concentrates.
Application:
Cost tier stratification separates commodity bakery volumes from premium meat-alternative and dairy-alternative positioning, with margin capture varying threefold across application segments.
- Bakery:Established absorption of wheat gluten for dough conditioning, crumb structure, and shelf-life extension in commercial bread, pastry, and pizza operations. Demand localizes around U.S. Plains milling infrastructure where ADM and Cargill integrated networks supply industrial bakeries at scale.
- Meat Alternatives:Fastest-climbing application as extrusion technology enables fibrous texture replication without soy, with formulation budgets redirecting toward wheat-derived alternatives for cleaner-label positioning.
- Dairy Alternatives:Hydrolyzed wheat protein concentrates achieving solubility thresholds for ready-to-drink and sports nutrition beverages.
- Snacks:Textured protein inclusions for protein-fortified chips, crackers, and nutrition bars.
Bakery commands volume leadership. Meat alternatives represent the steepest expansion trajectory.
End User:
Customer type determines contract structure: food manufacturers lock in multi-year offtake agreements, while health food brands and retail channels purchase spot or quarterly.
- Food Manufacturers:Industrial-scale bakery and meat-alternative producers with formulation R&D capabilities and dedicated procurement teams. Concentrated purchasing power in California, Illinois, and Midwest processing corridors enables direct supplier relationships that displace distributor intermediaries.
- Beverage Producers:Sports nutrition and ready-to-drink dairy-alternative brands requiring hydrolyzed wheat protein isolates with solubility and flavor neutrality specifications.
- Health Food Brands:Premium-positioned clean-label formulators with smaller batch requirements and higher specification tolerance.
- Retail:Private-label and branded ingredient suppliers serving consumer packaged goods channels.
Food manufacturers anchor procurement volume. Beverage producers are gaining share fastest.
Form:
Supply concentration in powder processing creates tiered availability: powder and granules achieve scale economies, while liquid and concentrate forms require specialized handling infrastructure that limits supplier participation.
- Powder:Standardized dry form for bakery and textured protein applications, with Midwest tolling and in-house processing capacity concentrated among integrated millers.
- Granules:Intermediate particle size for controlled hydration in meat-analog extrusion operations.
- Liquid:Pre-hydrated suspensions for beverage fortification requiring solubility without additional processing steps.
- Concentrate:High-potency protein fractions for premium formulation applications with stringent purity requirements.
Powder dominates installed base. Concentrate is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest U.S. processors command pricing leverage over Canadian Prairie suppliers due to captive milling infrastructure and denser bakery manufacturing clusters. Kansas and Nebraska extraction operations source wheat within 150-mile radii, compressing logistics costs that Alberta and Saskatchewan processors cannot match without rail arbitrage.
United States
Industrial bakery demand absorbs two-thirds of regional wheat gluten volumes, with ADM and Cargill integrated networks supplying high-speed bread operations across the Midwest and Southeast. FDA Food Allergen Labeling mandates standardize disclosure protocols but extend compliance timelines for reformulated products. Kansas milling corridors anchor gluten extraction capacity adjacent to hard red winter wheat production belts.
Canada
Saskatchewan and Manitoba hard red spring wheat production expands isolate-grade protein supply for beverage and dairy-alternative formulators. Health Canada novel food notification requirements for modified wheat proteins extend pre-market assessment timelines, elevating analytical testing costs for U.S. exporters. Toronto-area contract research organizations absorb expanded safety dossier preparation as smaller processors establish domestic equivalency pathways.
Mexico
Bakery manufacturing growth in Querétaro and Guanajuato generates import demand for U.S.-origin wheat gluten, though tariff exposure on plant-protein classifications creates procurement uncertainty. COFEPRIS allergen labeling standards align with FDA frameworks but introduce Spanish-language documentation requirements that complicate cross-border supplier relationships. Baja California tortilla and snack processors represent emerging volume pockets for textured protein applications.
North America Wheat Protein Ingredients Market Competitive Landscape
Concentration sits with integrated grain processors that combine origination networks with captive extraction assets. Three structural tiers define competitive positioning: multinational agribusiness conglomerates with full supply chain control, mid-scale specialty ingredient developers focused on isolate purity tiers, and regional toll processors serving bakery distributors. Dominant competitive moves include backward integration into wheat origination and direct procurement relationships that displace distributor intermediaries in meat-alternative channels.
Within the integrated processor tier, Archer Daniels Midland Company and Cargill Incorporated represent capital-intensive archetypes that leverage Plains-based grain networks. MGP Ingredients Inc. occupies a narrower position among specialty isolate developers, with its Kansas operations exemplifying the mid-scale model of regional processing clusters serving beverage and dairy-alternative formulators. These three entities anchor the competitive spectrum from commodity gluten supply to premium protein fractionation.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Kerry Group PLC |
| MGP Ingredients Inc. |
| Roquette Frères |
| Tereos |
| The Scoular Company |
| Manildra Group |
| Crespel & Deiters |
| Others |
Value Network & Pricing Analysis
FDA Food Allergen Labeling and Consumer Protection Act compliance gates both supplier qualification and price differentiation simultaneously, with certification investment separating premium-positioned isolate developers from commodity gluten tollers while procurement scale determines contract leverage.
Pricing Analysis
Configured-to-order pricing for high-purity wheat protein isolates commands substantial premiums over standard gluten fractions, with protein content thresholds and Health Canada novel food notification status driving differentiation. Contract-based long-term offtake agreements dominate meat-alternative channel procurement, while spot purchasing persists in bakery distributor tiers. Cost compression in standard gluten runs through Midwest milling overcapacity and logistics efficiency gaps. Industrial bakeries exhibit highest price sensitivity due to formulation volume scale, whereas beverage producers accepting premium positioning for solubility-certified isolates show lowest.
Supply Chain Analysis
Just-in-time inventory strategies dominate industrial bakery procurement through Midwest distributor networks, while meat-alternative manufacturers maintain strategic stockpiles of textured protein to hedge extrusion operator scarcity. Geographic supply concentrates in the United States, Canada, and limited Mexican import flows. Hard red winter wheat, enzymatic processing inputs, and ceramic membrane filtration equipment constitute critical dependencies. Single-source vulnerability sits with Kansas and Nebraska extraction clusters exposed to Southern Plains drought cycles. Distribution runs through integrated miller direct relationships displacing traditional foodservice intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based meat reformulation represents an early-cycle expansion story, with textured wheat protein penetration in alternative protein applications still below saturation thresholds despite accelerating formulation budgets.
For Market Incumbents: Secure captive wheat origination through backward integration into Plains-based grain networks to defend margin position against drought-driven input volatility. Lock multi-year offtake agreements with California and Illinois meat-alternative R&D clusters before specialty isolate developers capture formulation partnerships. Channel control through direct procurement relationships remains the critical lever against distributor consolidation pressure.
For New Entrants and Emerging Players: Lead with Saskatchewan and Manitoba isolate production targeting Health Canada novel food notification pathways, where underutilized Prairie processing capacity meets expanding beverage fortification demand. Canadian Prairie expansion offers the most penetrable geography given regulatory friction burdening U.S. exporters. Position through Canadian contract research organization partnerships establishing domestic safety dossiers rather than equivalency arguments.
For Investors and Strategic Acquirers: Health Canada's updated Guidance on Novel Food Information Requirements for Plant-Based Proteins reshapes the acquisition landscape, elevating analytical testing capabilities to strategic assets. Mid-scale specialty processors with established Canadian regulatory dossiers present viable 5-10 year positioning plays. Watch CFIA assessment timeline extensions as the signal indicating regulatory barrier height and domestic capability premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Origination | Captive Plains supply secures cost-advantaged gluten extraction against drought-driven input volatility. |
| Health Canada Novel Food Dossier Investment | Domestic safety data establishment accelerates Canadian market entry timelines for isolate developers. |
| Direct Procurement Relationship Formation | Bypassing distributor intermediaries captures margin pools in California and Illinois alternative protein clusters. |
| Membrane Filtration Technology Deployment | Modular ceramic and polymeric systems enable regional processors to compress supply chain tiers. |
| Cross-Contamination Control Line Investment | Dedicated allergen-free production infrastructure qualifies suppliers for premium clean-label positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA enforcement actions, USDA organic certification databases, and SEC filings from integrated grain processors, combining interviews with wheat protein extraction plant managers, bakery procurement leads, meat-alternative formulation scientists, and Health Canada regulatory affairs specialists. Bottom-up volume triangulation from application-specific consumption rates converges with top-down value estimation from producer revenue disclosures and trade flow analysis.
Segmentation dimensions modeled span product type, application, end user, and form across the projection horizon, with protein purity tiers and regulatory certification status constituting additional industry-specific stratification. CAGRs derive from regression analysis against historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporate hard red winter wheat price cycle patterns and extrusion technology adoption curves in alternative protein manufacturing.
The analysis sits within stated boundaries; outcomes outside sustained plant-based meat reformulation momentum or stable FDA allergen labeling enforcement would require recalibration. Forecasts reflect assumptions regarding Midwest milling infrastructure continuity and Canadian regulatory pathway stability. Revision becomes warranted when wheat protein tariff classifications or biotech wheat regulatory thresholds cross material uncertainty thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Italy Soy Protein Market
Ingredients
North America Corn Starch Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Europe Corn Glucose Market
Ingredients
North America Collagen Ingredients Market
Ingredients
North America Potato Protein Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
Native Whey Protein Ingredients Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
Resistant Starch Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Green Gram Powder Market
Ingredients
Food Ingredients Market
Ingredients
Bouillon Market
Ingredients
South Africa Sodium Reduction Ingredients Market