
 North America Water Detection Sensors Market | 2026-2036
North America Water Detection Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Water Detection Sensors Market Analytics
The shift from outsourced maintenance contracts toward in-house sensor networks is hardening across North American water utilities. Honeywell International Inc. leverages its building automation heritage to bundle detection hardware with control platforms. Emerson Electric Co. sustains instrumentation credibility through its Rosemount analytical portfolio. Badger Meter, Inc. anchors municipal relationships with endpoint-to-cloud architectures that span leak detection and consumption metering.
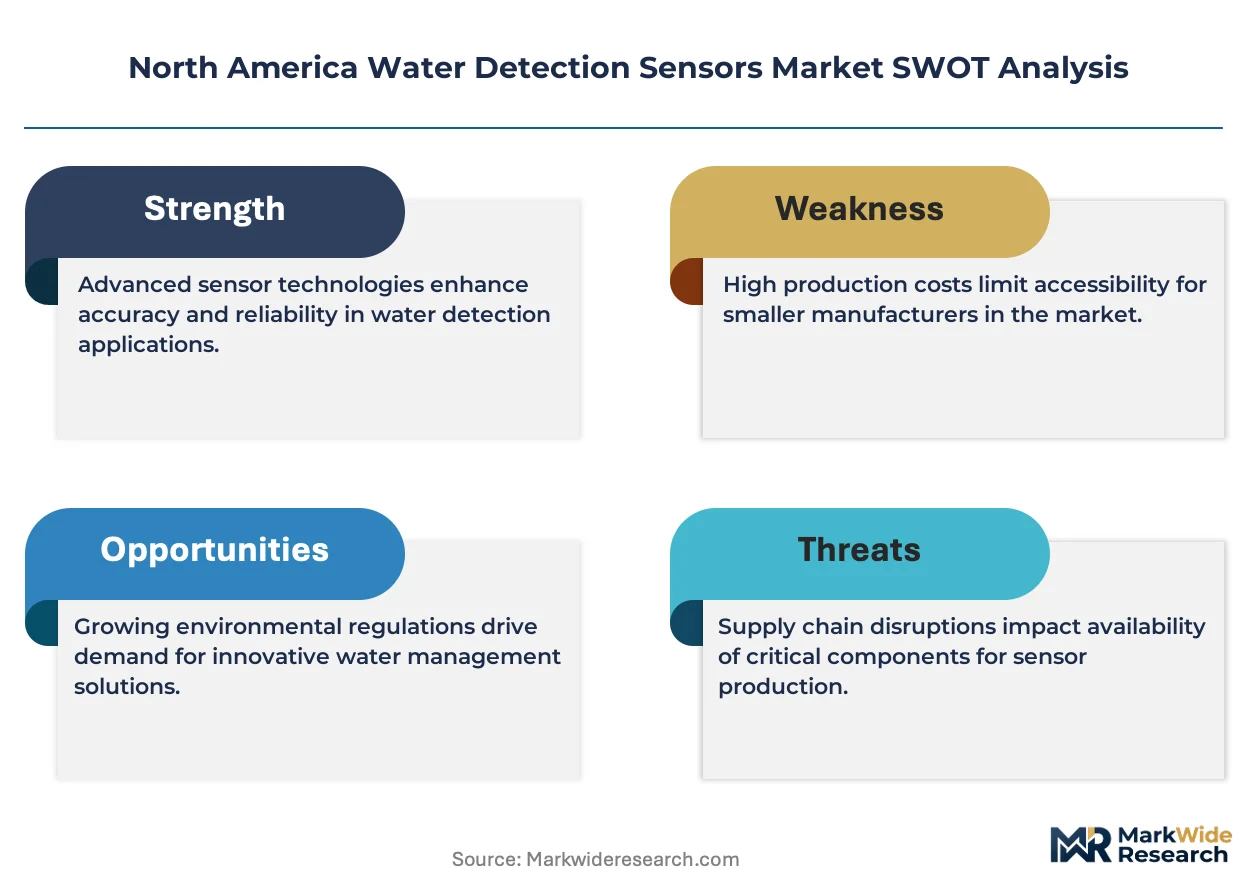
Water detection sensors are electromechanical or solid-state devices engineered to identify moisture presence, liquid level, or flow anomalies through capacitive, resistive, or ultrasonic principles, typically operating at detection thresholds between 0.1 and 5 millimeters for surface applications and pressure ratings up to 300 PSI for submerged industrial deployments. Their primary purpose is preventing catastrophic water damage, optimizing distribution efficiency, and ensuring regulatory compliance across built environments and process industries. Capacitive and ultrasonic sensor types command the technology mix where non-contact measurement and chemical compatibility determine specification wins. Wireless connectivity segments are capturing disproportionate growth as utilities depreciate copper wiring and adopt LoRaWAN and cellular backhaul for remote lift stations and transmission mains.
EPA enforcement of the Lead and Copper Rule Improvements and state-level mandates from California's Water Board and Texas Commission on Environmental Quality are mandating continuous monitoring at treatment plant effluent points and distribution system entry. NIST traceability requirements and AWWA standards for pressure and flow instrumentation further constrain supplier qualification, favoring manufacturers with certified calibration laboratories and documented quality systems. Stakeholders must weigh sensor refresh cycles against emerging digital twin integrations that promise predictive rather than reactive leak response.
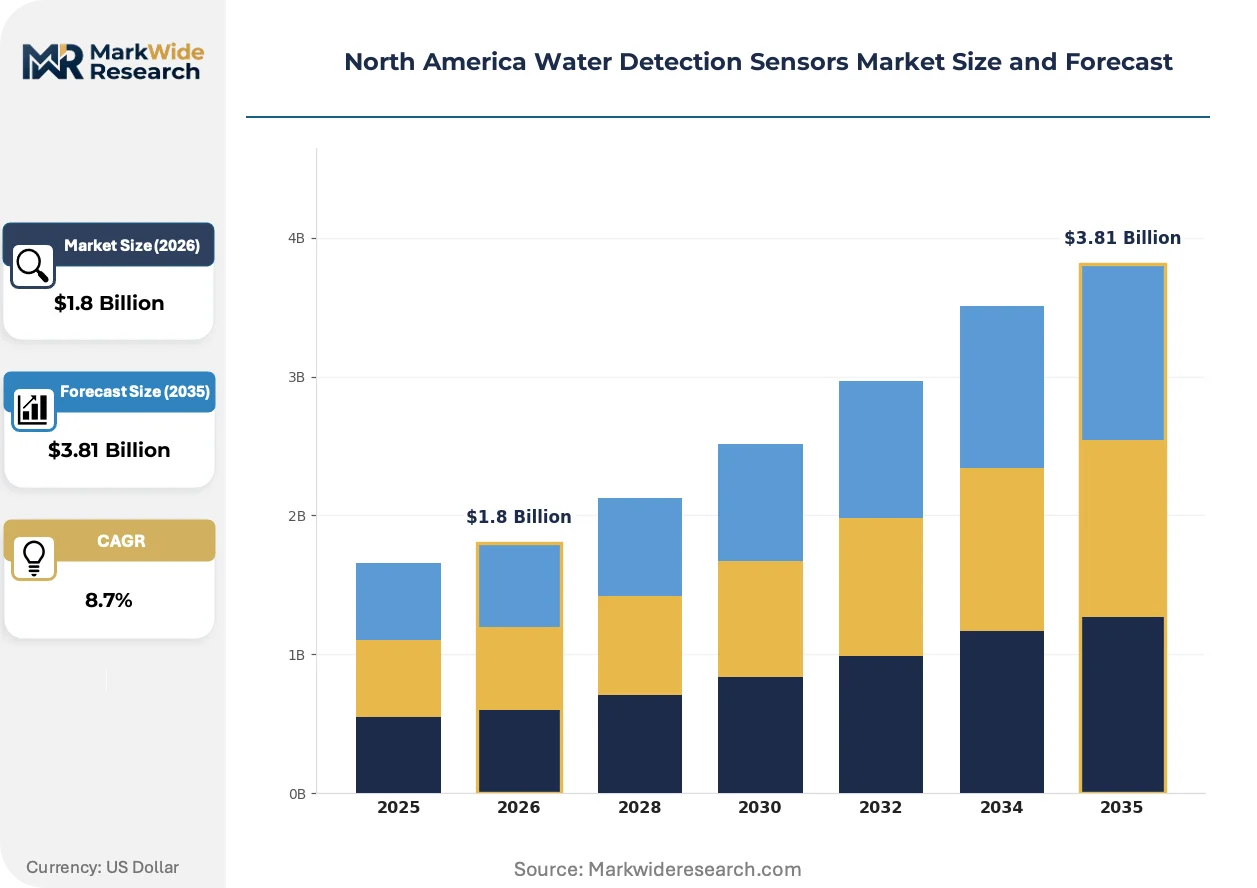
Market Dynamics
EPA Lead and Copper Rule Improvements are compressing sensor refresh cycles across municipal utilities, forcing capital allocation toward continuous monitoring architectures and away from periodic manual sampling regimes.
Growth Catalysts
- EPA Lead and Copper Rule Improvements:Federal mandates require real-time corrosion monitoring at distribution system entry points, compelling utilities to deploy electrochemical sensors with data logging capabilities.
- LoRaWAN backhaul adoption:Cellular and low-power wide-area networks are displacing copper wiring for remote lift station monitoring, cutting installation costs for transmission main leak detection.
- Southwestern drought persistence:Water loss detection carries premium urgency in Arizona, California, and Texas where non-revenue water reduction targets exceed national averages.
Market Restraints
- Semiconductor supply concentration:Sensor microcontroller and analog front-end component sourcing remains concentrated in East Asian foundries, exposing lead time volatility.
- NIST traceability compliance costs:Calibration laboratory certification and documented quality systems impose fixed cost barriers for smaller instrumentation suppliers.
- Capacitive sensor drift limitations:Electrochemical interference in high-mineral water matrices degrades measurement stability, requiring more frequent recalibration than ultrasonic alternatives.
Strategic Opportunities
- Digital twin integration:Predictive leak response algorithms are converging with hydraulic modeling platforms, creating subscription revenue streams beyond hardware sales.
- Texas Commission on Environmental Quality mandates:State-level continuous monitoring requirements for effluent points are accelerating sensor deployment timelines beyond federal minimums.
- Smart building retrofits:Commercial real estate operators in California are specifying wireless moisture detection for insurance premium reduction and property damage mitigation.
Industry Challenges
- SCADA integration complexity:Legacy municipal control systems require protocol translation gateways to ingest modern sensor data streams, extending deployment timelines.
- AWWA certification timelines:Pressure and flow instrumentation standards demand extended validation periods that delay product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Water Detection Sensors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Capacitive, Resistive, Optical, Ultrasonic Installation Type: Fixed, Portable, Integrated, Modular End User: Residential, Commercial, Industrial, Agricultural Connectivity: Wired, Wireless, Bluetooth, Zigbee |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., Badger Meter, Inc., Xylem Inc., Siemens AG, Endress+Hauser AG, Hach Company, Mueller Water Products, Inc., Pentair plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Water Detection Sensors Market Evolving Landscape
Sensor architectures are pivoting from reactive alarm triggers toward predictive analytics platforms, with connectivity modules and edge computing capabilities becoming standard specifications rather than premium options.
Ultrasonic time-of-flight sensors are electrifying non-contact liquid level measurement in chemical storage and wastewater applications. Municipal utilities in drought-stressed regions are specifying these units for corrosive environments where electrochemical degradation threatens maintenance budgets. The technology is compressing total cost-of-ownership calculations against traditional float switches and pressure transducers.
California's Water Board has enacted continuous monitoring mandates for treatment plant effluent that exceed federal baseline requirements. Industrial facilities discharging to municipal systems must now install certified sensors with automated reporting interfaces. The regulation is forcing instrumentation suppliers to pre-integrate data validation algorithms that flag anomalous readings before regulatory submission.
Buying committees at mid-sized utilities are consolidating vendor relationships around endpoint-to-cloud platform providers rather than sourcing discrete sensors through distribution channels. Specification authority is shifting from maintenance departments to IT and data analytics teams with cybersecurity screening requirements. This pattern is most pronounced in Texas and Arizona where capital improvement bonds fund comprehensive smart water deployments.
North America Water Detection Sensors Market Segmentation
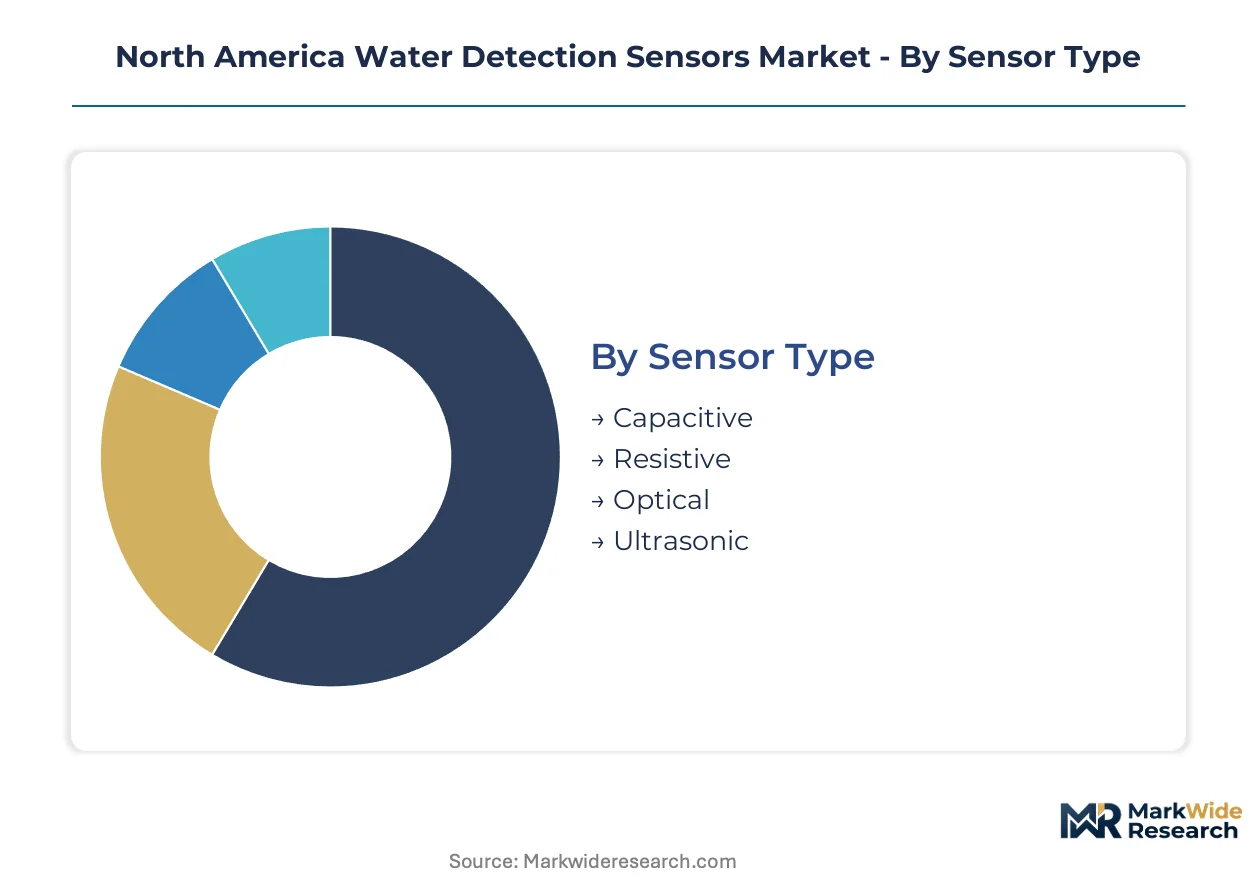
Water detection sensors fragment across four distinct specification axes that determine procurement patterns. Municipal utilities prioritize corrosion resistance and telemetry integration, while commercial real estate operators emphasize wireless retrofit compatibility and insurance compliance documentation.
Sensor Type:
Capacitive and ultrasonic variants dominate specification sheets where non-contact measurement and chemical compatibility determine competitive wins.
- Capacitive:Electromechanical devices detect moisture through dielectric constant shifts, achieving sub-millimeter precision in surface applications. Municipal utilities in Arizona and California specify these for distribution system entry points where EPA Lead and Copper Rule compliance demands continuous corrosion monitoring. Electrochemical interference in high-mineral matrices degrades measurement stability, forcing more frequent recalibration cycles than ultrasonic alternatives.
- Ultrasonic:Time-of-flight sensors measure liquid levels without media contact, eliminating electrochemical degradation risks in corrosive wastewater environments. Texas utilities deploying these at remote lift stations report compressed total cost-of-ownership against traditional float switches. The technology electrifies specification wins where maintenance access is limited and chemical compatibility is paramount.
- Resistive:Simple conductive probes with exposed electrodes offer lowest unit cost for residential basement and appliance leak detection applications.
- Optical:Infrared refractometry sensors serve specialized industrial process control where fluid transparency variations indicate contamination events.
Capacitive leads on scale; ultrasonic leads on momentum.
Installation Type:
Deployment architecture determines capital expenditure profiles and operational flexibility across utility and commercial portfolios.
- Fixed:Permanent-mount sensors anchor municipal infrastructure monitoring networks with hardwired power and telemetry integration. Southwestern utilities in drought-stressed regions specify these for transmission main leak detection where non-revenue water reduction targets exceed national benchmarks. Installation requires trenching and conduit runs that extend deployment timelines but deliver decades of operational service.
- Modular:Hot-swappable sensor nodes enable rapid field replacement without system shutdown, reducing maintenance truck rolls for remote lift station networks. California Water Board continuous monitoring mandates accelerate adoption of modular architectures that minimize compliance downtime during sensor refresh cycles. The approach commands premium pricing against fixed alternatives but compresses lifecycle labor costs.
- Portable:Battery-powered handheld units support spot-check verification and emergency response deployment without infrastructure investment.
- Integrated:Factory-sealed sensor-telemetry combinations streamline procurement for mid-sized utilities consolidating vendor relationships.
Fixed installations dominate capital budgets; modular architectures gain share fastest in compliance-driven replacement cycles.
End User:
Demand concentration varies sharply across customer types with divergent specification authority and procurement processes.
- Industrial:Process manufacturers deploy pressure-rated sensors up to 300 PSI for submerged chemical storage and effluent monitoring. Facilities discharging to municipal systems in California must install certified sensors with automated reporting interfaces per Water Board mandates. Data validation algorithms that flag anomalous readings before regulatory submission now determine supplier qualification.
- Commercial:Real estate operators in California specify wireless moisture detection for insurance premium reduction and property damage mitigation. Smart building retrofits concentrate specification authority with IT and data analytics teams rather than traditional maintenance departments. Cybersecurity screening requirements now gate vendor selection alongside functional performance.
- Residential:Homeowners and property managers deploy low-cost point sensors for basement flood prevention and appliance leak alerts.
- Agricultural:Irrigation system integrators specify soil moisture and flow anomaly detection for water use efficiency compliance in water-stressed growing regions.
Industrial segments command highest unit values; commercial retrofits expand most quickly behind insurance mandate tailwinds.
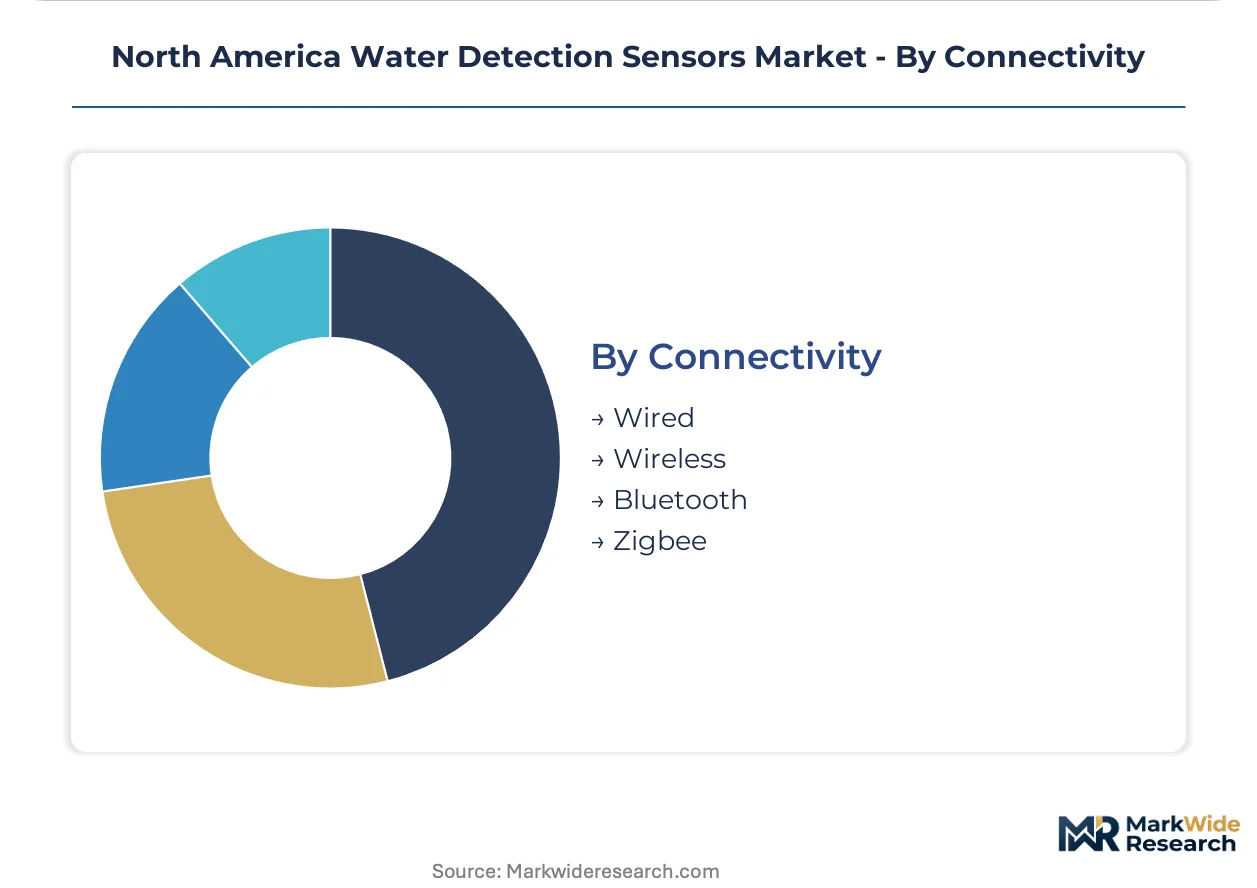
Connectivity:
Backhaul technology selection determines installation economics and data latency for distributed monitoring networks.
- Wireless:LoRaWAN and cellular backhaul displace copper wiring for remote lift station and transmission main monitoring. Texas and Arizona utilities depreciate legacy copper infrastructure while deploying low-power wide-area networks that cut trenching costs. The segment captures disproportionate growth as capital improvement bonds fund comprehensive smart water deployments.
- Wired:Hardwired RS-485 and 4-20mA loops persist in treatment plant environments where electromagnetic interference and cybersecurity hardening outweigh installation cost considerations.
- Bluetooth:Short-range protocols serve portable diagnostic tools and residential smart home integrations with limited range requirements.
- Zigbee:Mesh networking specifications address building automation integrations where sensor density and battery longevity trade off against bandwidth needs.
Wired connectivity retains plant-floor dominance; wireless architectures climb the fastest behind municipal infrastructure modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southwestern municipal utilities anchor North American demand concentration for water detection sensors, with drought-stressed infrastructure driving specification intensity across Arizona, California, and Texas metros.
United States
Southwestern utilities in Arizona and California deploy capacitive sensors at distribution system entry points to meet EPA Lead and Copper Rule Improvements. The EPA mandates real-time corrosion monitoring that displaces periodic manual sampling. Phoenix and Los Angeles water departments concentrate procurement authority with IT teams demanding LoRaWAN telemetry integration.
Canada
Provincial utilities in Ontario and British Columbia prioritize modular sensor architectures for freeze-thaw resilience in transmission networks. Health Canada guidelines for drinking water quality inform specification standards that exceed baseline federal requirements. Toronto and Vancouver municipal water authorities consolidate vendor relationships around endpoint-to-cloud platform providers.
Mexico
Water loss reduction programs in Mexico City and Monterrey drive demand for ultrasonic leak detection on aging distribution mains. The National Water Commission (CONAGUA) mandates continuous monitoring at treatment plant effluent points for facilities discharging to municipal systems. Industrial clusters in Nuevo León specify pressure-rated sensors for chemical storage applications.
North America Water Detection Sensors Market Competitive Landscape
Global majors compete with regional champions across telemetry integration and municipal relationship depth, creating a tiered structure where scale-driven conglomerates face specialized instrumentation houses. The vendor base organizes around three archetypes: building automation conglomerates bundling detection hardware with control platforms, analytical instrumentation specialists sustaining credibility through certified calibration laboratories, and endpoint-to-cloud platform providers consolidating specification authority with IT buying committees. Dominant competitive moves include backward integration into sensor microcontroller sourcing and strategic partnerships with hydraulic modeling software vendors for digital twin integration.
Within the building automation tier, Honeywell International Inc. and Siemens AG occupy positions that leverage heritage control platforms for bundled municipal offerings. Emerson Electric Co. and Endress+Hauser AG exemplify the analytical instrumentation archetype with documented quality systems and NIST-traceable calibration capabilities. Badger Meter, Inc. anchors the endpoint-to-cloud specialization, representing vendor consolidation trends among mid-sized utilities in Texas and Arizona capital improvement programs.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| Badger Meter, Inc. |
| Xylem Inc. |
| Siemens AG |
| Endress+Hauser AG |
| Hach Company |
| Mueller Water Products, Inc. |
| Pentair plc |
| Others |
Value Network & Pricing Analysis
EPA Lead and Copper Rule Improvements gate both qualified supply and premium-tier pricing access, forcing utilities to source only from vendors with NIST-traceable calibration laboratories while compressing procurement timelines for certified instrumentation. Municipal buyers in Arizona and California now face bifurcated markets where EPA-compliant sensors command substantial premiums over uncertified alternatives, with specification authority shifting toward IT teams that bundle cybersecurity screening into total cost evaluations.
Pricing Analysis
Input-cost pass-through from semiconductor microcontroller and analog front-end components runs through sensor pricing tiers, with East Asian foundry concentration exposing buyers to lead time volatility that suppliers partially absorb through contract buffers. Three-tier pricing structure across premium, standard, and economy levels separates NIST-certified municipal instrumentation from commercial retrofit units and residential point sensors. Cost compression in the economy tier is intensifying because of commodity resistive probe imports, while industrial buyers show lowest price sensitivity due to regulatory non-compliance penalties. Price differentiation centers on calibration certification grade and telemetry integration depth rather than raw sensor precision.
Supply Chain Analysis
AWWA certification and NIST-traceable laboratory accreditation gate supplier qualification, creating fixed-cost barriers that favor conglomerates with documented quality systems over smaller instrumentation houses. Microcontroller and analog front-end sourcing draws from Taiwan, South Korea, and China, while sensor packaging and final calibration concentrate in the United States and Germany. Single-source vulnerability in advanced node semiconductor fabrication threatens delivery timelines for electrochemical sensor variants. Distribution runs through municipal procurement departments consolidating vendor relationships around endpoint-to-cloud platform providers rather than discrete sensor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America water detection sensors market represents a late-cycle quality story as municipal utilities shift procurement authority toward IT teams demanding integrated telemetry and cybersecurity hardening that only premium-tier vendors can deliver.
For Market Incumbents: To counter semiconductor supply concentration and emerging platform-native competitors, incumbents should execute backward integration into sensor microcontroller sourcing through strategic foundry partnerships, while accelerating digital twin integration with hydraulic modeling vendors to capture subscription revenue beyond hardware sales. For New Entrants and Emerging Players: The price-point gap between NIST-certified premium tiers and uncertified economy alternatives creates entry space for mid-market challengers offering modular architectures with rapid field replacement capabilities. New entrants should target Texas and Arizona mid-sized utilities consolidating vendor relationships through capital improvement bonds, with a go-to-market angle emphasizing compressed deployment timelines against legacy SCADA integration complexity. For Investors and Strategic Acquirers: Roll-up economics work for endpoint-to-cloud platform specialists because municipal procurement consolidation favors comprehensive vendors over discrete sensor suppliers. The long-term viability window favors acquisition targets with certified calibration laboratories and documented AWWA quality systems. Investors should monitor EPA enforcement intensity around Lead and Copper Rule Improvements as the inflection signal for accelerated sensor refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Predictive leak response algorithms bundled with hydraulic modeling platforms create recurring revenue streams beyond hardware. |
| LoRaWAN Telemetry Partnership | Cellular and low-power wide-area network alliances cut installation costs for remote lift station monitoring in Texas and Arizona. |
| Calibration Laboratory Certification | NIST-traceable capabilities gate municipal procurement qualification and sustain pricing power against uncertified competitors. |
| SCADA Protocol Gateway Development | Legacy system translation tools compress deployment timelines for mid-sized utilities with aging control infrastructure. |
| Endpoint-to-Cloud Platform Consolidation | Comprehensive vendor relationships displace discrete sensor sourcing as IT buying committees assume specification authority. |
Research Methodology
Direct dialogue with municipal water utility procurement directors, IT infrastructure leads, instrumentation engineers at treatment plants, and regulatory compliance officers grounded the qualitative foundation. Secondary validation drew from EPA enforcement databases, AWWA technical standards, state water board mandate filings, and municipal capital improvement bond disclosures. Bottom-up and top-down triangulation cross-checked sensor deployment estimates against utility budget allocations and vendor shipment patterns.
Bottom-up modeling aggregated individual utility procurement plans across Arizona, California, and Texas drought-stressed regions, while top-down analysis calibrated against total addressable infrastructure spend. Segmentation dimensions included sensor type, installation architecture, connectivity protocol, and end-user category across industrial, commercial, and municipal verticals. CAGRs were derived from utility depreciation schedules for copper wiring and projected LoRaWAN adoption curves. Forecast inputs incorporated EPA compliance timeline assumptions and semiconductor foundry capacity expansion announcements.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic time-of-flight sensors displacing capacitive variants in corrosive environments would alter the outlook. Forecasts reflect assumptions around EPA enforcement consistency, semiconductor supply normalization, and municipal bond market access. A model refresh is warranted upon material change in Lead and Copper Rule implementation timelines or state-level mandate acceleration beyond federal baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
Temperature Transmitter Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market