
 Fork Sensor Market | 2026-2036
Fork Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Fork Sensor Market Analysis
German sensor production capacity is decoupling from generic photoelectric supply chains as specialized fork sensor fabrication scales up in Baden-Württemberg and Bavaria. SICK AG leverages vertical integration into custom ASIC design for its laser fork sensor lines. Pepperl+Fuchs sustains R&D intensity across ultrasonic fork variants for harsh-environment deployment. OMRON Corporation anchors its competitive position through dominance in compact photodiode fork sensors for Asian electronics manufacturing.
A fork sensor is a through-beam photoelectric device housed in a U-shaped mechanical frame, with emitter and receiver aligned at a fixed gap typically ranging from 2 mm to 220 mm, designed to detect object presence, position, or edge alignment without reflective surface dependency. Its primary industrial purpose is high-speed, repeatable detection in constrained spaces where diffuse or retroreflective sensors would fail due to material opacity or positioning tolerance. Laser fork sensors command premium positioning in pharmaceutical packaging lines where beam diameter below 0.5 mm enables tablet-count verification. Inductive fork sensors are displacing mechanical limit switches in automotive weld cells where magnetic immunity proves critical. RFID technology integration represents the fastest-growing technology segment as traceability mandates expand across European logistics hubs.
German manufacturers navigate CE marking requirements under the EU Machinery Directive alongside ISO 13849-1 safety integrity classifications for control system integration. The US OSHA machine guarding standards and FDA 21 CFR Part 11 electronic record provisions shape sensor selection in North American pharmaceutical and food packaging environments. Stakeholders must monitor how EU AI Act risk classifications begin intersecting with smart sensor data processing architectures in automated inspection systems.
Market Dynamics
Laser fork sensors are compressing detection tolerances in pharmaceutical packaging lines, forcing incumbent photoelectric suppliers to reengineer optical subsystems or cede high-margin precision applications to specialized fork sensor fabricators.
Growth Catalysts
- ISO 13849-1 functional safety classifications:European machinery OEMs must integrate SIL-rated sensors into safety circuits, mandating fork sensor replacement of mechanical switches in automated gates and conveyors.
- Tablet-count verification in pharmaceutical packaging:Beam diameters below 0.5 mm enable laser fork sensors to detect individual pills at blister-line speeds where diffuse sensors fail.
- China's eastern manufacturing corridor:Automotive OEMs in Jiangsu and Zhejiang provinces are retrofitting weld stations with inductive fork sensors for magnetic immunity in high-current environments.
Market Restraints
- ASIC foundry concentration in Taiwan:Custom photodiode arrays for laser fork sensors depend on a narrow supplier base, exposing lead time volatility.
- Indium phosphide wafer costs:Near-infrared emitter substrates face price pressure from competing demand in telecommunications fiber optics.
- Mechanical limit switch persistence:Low-complexity position detection in cost-sensitive machinery retains installed-base inertia against photoelectric conversion.
Strategic Opportunities
- RFID-integrated fork sensors:European logistics hubs under CSRD traceability mandates create white space for combined presence-detection and item-identification units.
- Ultrasonic fork variants for food processing:IP69K-rated housings with chemical-resistant faces address washdown requirements in dairy and meat packaging lines.
- India's PLI scheme for electronics manufacturing:Smartphone assembly expansion in Noida and Sri City generates demand for compact photodiode fork sensors in component placement verification.
Industry Challenges
- Optomechanical alignment tolerances:Sub-millimeter emitter-receiver coaxiality demands specialized assembly technicians scarce in contract manufacturing regions.
- FDA 21 CFR Part 11 validation timelines:Pharmaceutical sensor deployments require extended IQ/OQ/PQ documentation cycles that compress deployment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fork Sensor Market |
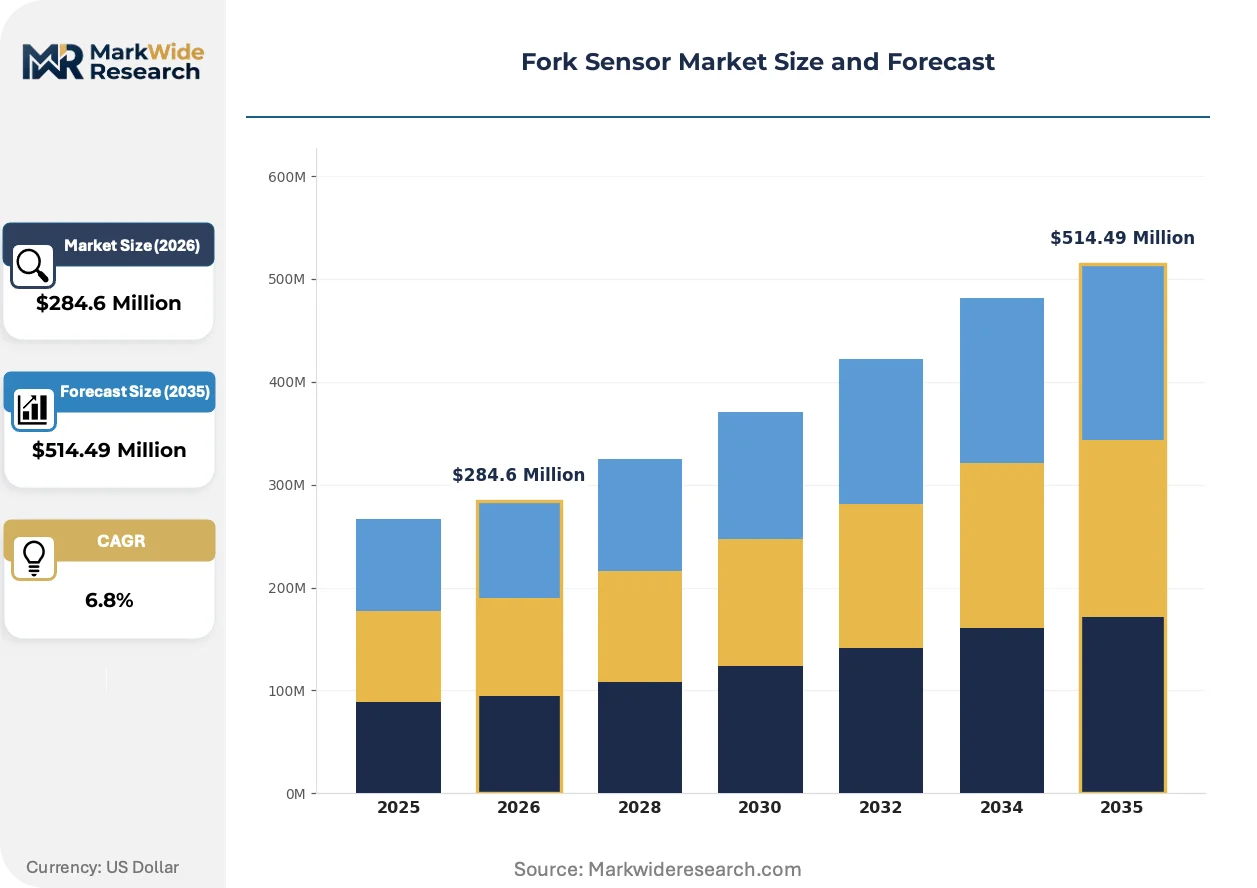
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $514.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Fork Sensors, Photodiode Fork Sensors, Inductive Fork Sensors, Capacitive Fork Sensors Technology: Optical Technology, Ultrasonic Technology, RFID Technology, Magnetic Technology Application: Material Handling, Packaging, Position Detection, Level Measurement End User: Manufacturing, Logistics, Automotive, Electronics |
| Companies Covered | SICK AG, Pepperl+Fuchs, OMRON Corporation, Baumer, Leuze Electronic, Datalogic S.p.A., SensoPart Industriesensorik GmbH, Balluff GmbH, Banner Engineering Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fork Sensor Market Emerging Trajectories
Three intersecting developments are restructuring competitive advantage in fork sensor supply: optical precision escalation, safety-system integration mandates, and procurement model compression favoring sensor-integrator partnerships over component distribution.
Laser diode emitters with sub-0.5 mm beam waist are absorbing the tablet-detection and micro-component verification applications previously served by vision systems. Pharmaceutical packagers in Germany and Switzerland are specifying these units for count-verification stations where mechanical throughput exceeds 600 units per minute. The technology is absorbing margin from machine vision suppliers by delivering comparable precision at one-third the integration complexity.
The EU AI Act risk classifications are beginning to intersect with smart sensor architectures in automated inspection systems. Sensor manufacturers must now document decision-path transparency for edge-processing units that perform local classification, not mere presence detection. Fork sensor lines with onboard FPGA processing face re-certification scope expansion in European packaging machinery.
Consolidated procurement through system integrators is displacing traditional component distribution in high-volume electronics manufacturing. Contract manufacturers in Vietnam and Mexico now specify fork sensors through SMT placement equipment vendors rather than direct sensor procurement. This channel compression favors suppliers with embedded software stacks and line-integration engineering support.
Fork Sensor Market Segmentation
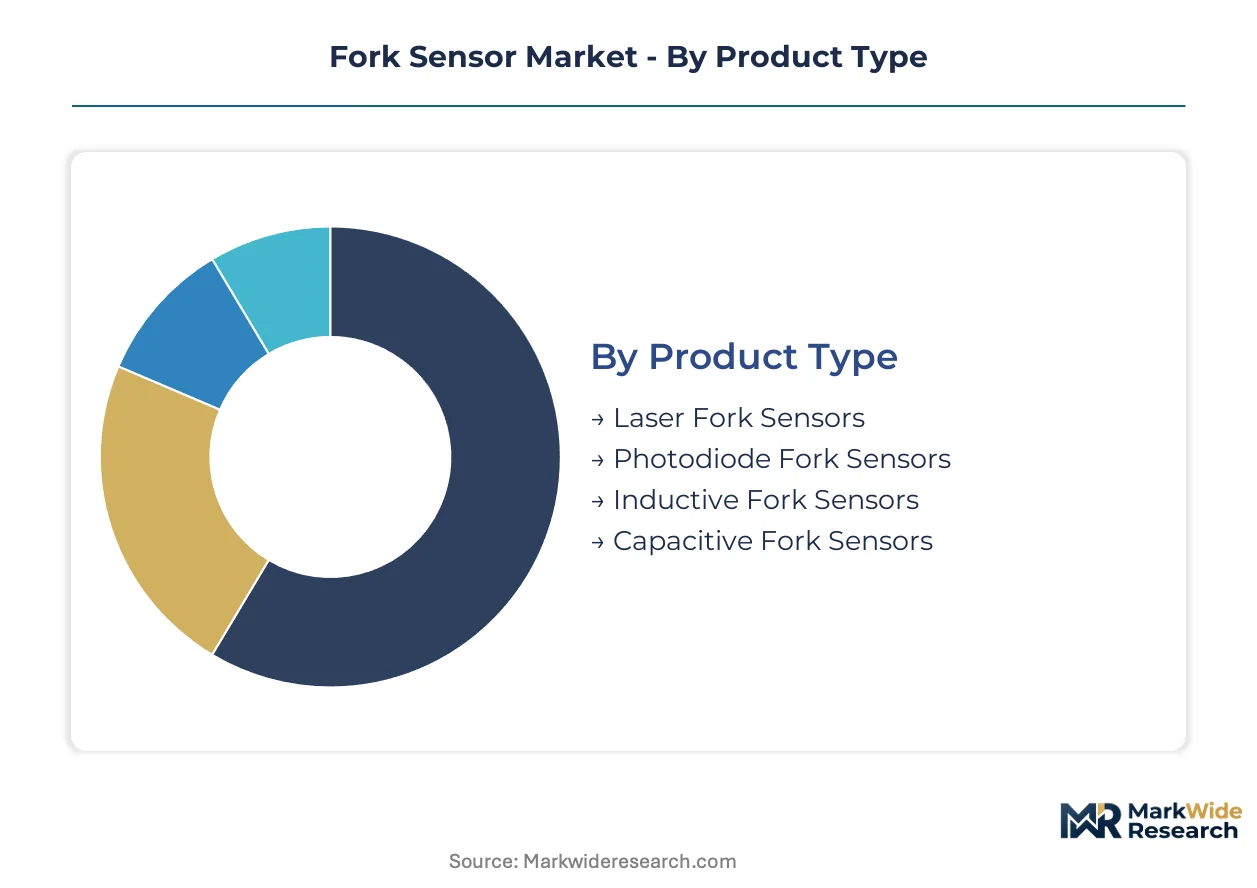
Fork sensor procurement patterns diverge sharply across industrial contexts. Buyers prioritize beam precision in pharmaceutical packaging, magnetic immunity in automotive weld cells, and washdown durability in food processing. Each segment category reflects distinct technical trade-offs between detection accuracy, environmental tolerance, and integration complexity.
Product Type:
Cost tier separates buyers seeking premium precision from those optimizing for magnetic immunity or capacitive versatility.
- Laser Fork Sensors:Sub-0.5 mm beam waist enables tablet-count verification at blister-line speeds exceeding 600 units per minute. Pharmaceutical packagers in Germany and Switzerland specify these units where diffuse sensors fail on material opacity. CE marking under the EU Machinery Directive and FDA 21 CFR Part 11 validation requirements compress deployment timelines for safety-critical installations.
- Inductive Fork Sensors:Magnetic field immunity suits high-current automotive weld cells where photoelectric units suffer interference. Automotive OEMs in Jiangsu and Zhejiang provinces retrofit assembly stations with these units for position verification in magnetic environments. China's GB standards for industrial automation equipment shape local procurement specifications.
- Photodiode Fork Sensors:Compact form factors dominate Asian electronics manufacturing for component placement verification. OMRON Corporation anchors supply through dominance in compact photodiode architectures for smartphone assembly lines.
- Capacitive Fork Sensors:Non-metallic detection capability addresses level measurement in bulk material handling where optical beam interruption proves unreliable.
Laser fork sensors lead volumes today; inductive variants are gaining share fastest in automotive retrofit programs.
Technology:
Application environment dictates technology selection — optical precision for packaging, ultrasonic resilience for washdown, RFID for traceability mandates.
- Optical Technology:Through-beam photoelectric architectures with fixed emitter-receiver alignment deliver repeatable detection without reflective surface dependency. SICK AG leverages in-house ASIC design for custom photodiode arrays serving high-speed label detection.
- RFID Technology:Combined presence-detection and item-identification units address CSRD traceability mandates expanding across European logistics hubs. This segment climbs the fastest as consolidated procurement through system integrators favors multi-function sensor platforms.
- Ultrasonic Technology:IP69K-rated housings with chemical-resistant faces serve dairy and meat packaging washdown requirements. Pepperl+Fuchs sustains R&D intensity across harsh-environment ultrasonic variants.
- Magnetic Technology:Reed switch and Hall-effect alternatives persist in cost-sensitive machinery where photoelectric conversion faces installed-base inertia.
Optical technology maintains volume leadership; RFID-integrated units show steepest expansion trajectory under European sustainability reporting requirements.
Application:
Throughput requirements and positioning tolerance define buyer priorities across material handling, packaging, and detection tasks.
- Packaging:Laser fork sensors compress detection tolerances in pharmaceutical and food packaging lines where beam diameter below 0.5 mm enables count verification. German packaging machinery OEMs specify these units under ISO 13849-1 functional safety classifications for safety circuit integration.
- Position Detection:Inductive and photodiode variants displace mechanical limit switches in automated gates and conveyors requiring SIL-rated sensor integration. Automotive assembly stations in China's eastern manufacturing corridor drive retrofit demand.
- Material Handling:Standard photoelectric fork sensors with 2 mm to 220 mm gap ranges serve conveyor presence detection in logistics hubs. CSRD traceability mandates in Europe accelerate RFID-integrated unit adoption.
- Level Measurement:Capacitive and ultrasonic technologies address bulk solids and liquid detection where optical beam interruption is impractical.
Packaging applications dominate current volumes; position detection is expanding most quickly under machinery safety standard upgrades.
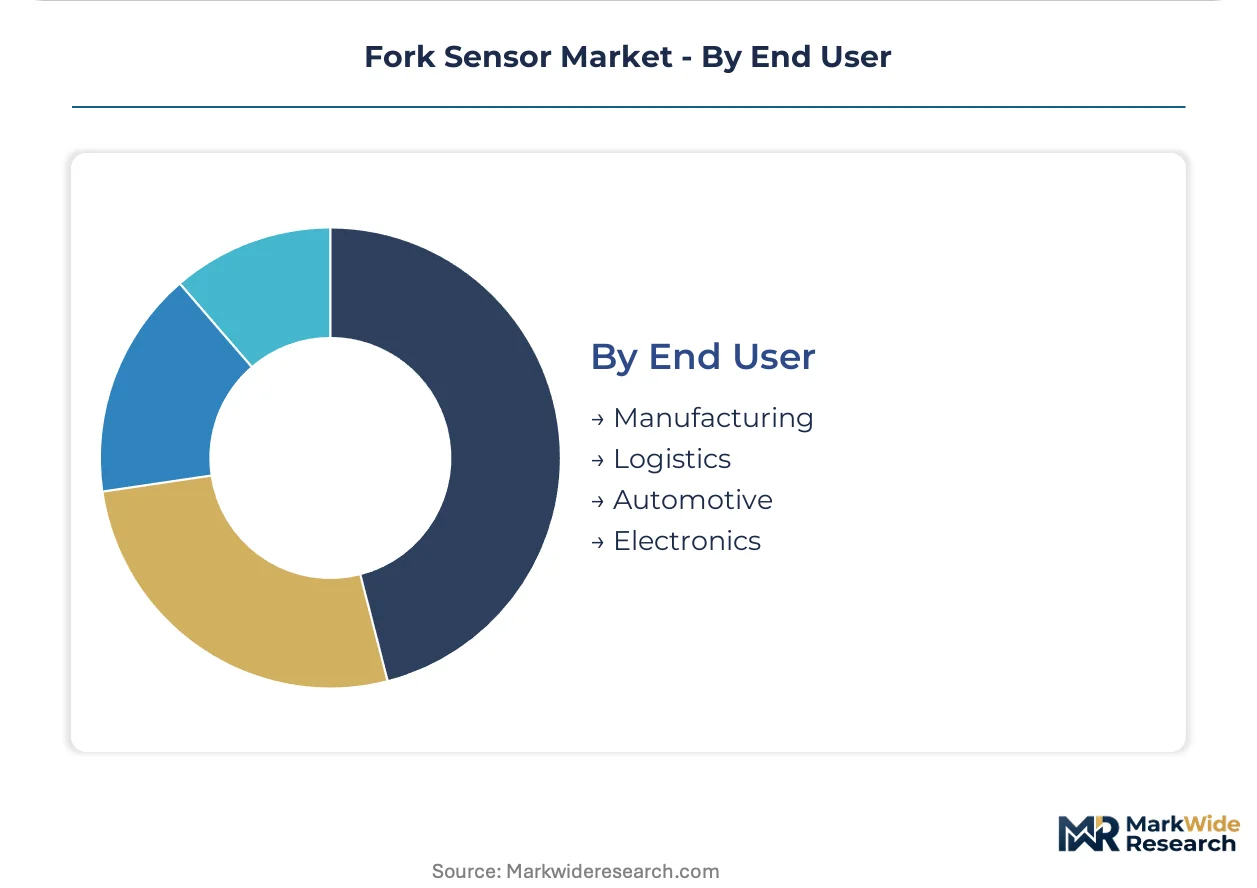
End User:
Customer type determines specification intensity — automotive and electronics buyers demand precision certification; logistics prioritizes traceability integration.
- Automotive:Magnetic immunity requirements in weld cells drive inductive fork sensor specification. OEMs in Germany's Baden-Württemberg and Bavaria clusters source from vertically integrated regional fabricators.
- Electronics:Compact photodiode fork sensors serve component placement verification in smartphone assembly expansion under India's PLI scheme. Noida and Sri City manufacturing corridors generate concentrated demand.
- Manufacturing:General industrial automation spans multiple sensor technologies with ISO 13849-1 compliance increasingly mandatory for European machinery exports.
- Logistics:European hub operators under CSRD mandates specify RFID-integrated units for combined detection and traceability.
Manufacturing end users lead absolute volumes; electronics sector demand is gaining share fastest through Asia-Pacific assembly expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting fork sensor procurement toward jurisdictions with streamlined machinery safety certification pathways. German fabricators exploit CE marking reciprocity agreements while Asian contract manufacturers absorb volume through consolidated system-integrator channels.
Germany
ISO 13849-1 functional safety mandates drive SIL-rated sensor integration into automated gates and conveyors. The EU Machinery Directive tightens alignment requirements for safety circuit components. Baden-Württemberg and Bavaria host specialized fabrication clusters where laser fork sensor production scales vertically into custom ASIC design.
China
Automotive OEMs in Jiangsu and Zhejiang provinces retrofit weld stations with inductive variants for magnetic immunity in high-current environments. GB standards for industrial automation equipment shape local procurement specifications. The eastern manufacturing corridor concentrates demand for position verification sensors in assembly line retrofits.
United States
FDA 21 CFR Part 11 electronic record provisions govern sensor selection in pharmaceutical packaging environments. OSHA machine guarding standards shape safety circuit architecture in food processing lines. Midwest automotive hubs and Southeast electronics corridors drive specification intensity for traceability-integrated units.
India
The PLI scheme for electronics manufacturing accelerates smartphone assembly expansion in Noida and Sri City. Compact photodiode fork sensors serve component placement verification in high-volume production lines. BIS certification requirements for industrial automation equipment filter supplier eligibility in government-linked procurement.
Switzerland
Pharmaceutical packagers specify laser fork sensors with sub-0.5 mm beam waist for tablet-count verification at blister-line speeds exceeding 600 units per minute. Swissmedic device regulations intersect with machinery safety standards in packaging line validation. Basel and Zurich pharmaceutical clusters demand precision detection without vision system integration complexity.
Fork Sensor Market Vendor Landscape
German producers anchor one tier; Japanese and Chinese specialists hold differentiated positions in compact photoelectric and cost-optimized segments. The vendor base stratifies across three tiers: vertically integrated precision fabricators, mid-scale technology licensors, and regional contract manufacturers. Strategic archetypes include safety-system integrators, harsh-environment specialists, and volume electronics suppliers. Capacity expansion in Baden-Württemberg and strategic partnerships with SMT equipment vendors dominate competitive moves.
Among Germany-based fabricators, SICK AG and Pepperl+Fuchs exemplify the vertically integrated tier, while OMRON Corporation represents the Asia-Pacific electronics manufacturing anchor. SICK AG occupies a position defined by in-house ASIC design capabilities. Pepperl+Fuchs exemplifies the harsh-environment specialization archetype. OMRON Corporation anchors the compact photodiode segment for high-volume component verification applications.
| Leading Market Players |
|---|
| SICK AG |
| Pepperl+Fuchs |
| OMRON Corporation |
| Baumer |
| Leuze Electronic |
| Datalogic S.p.A. |
| SensoPart Industriesensorik GmbH |
| Balluff GmbH |
| Banner Engineering Corp. |
| Others |
Supply Flow & Price Mechanics
Indium phosphide wafer spot prices cascade through laser fork sensor production into three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical OEMs in Germany absorb premium tier costs for sub-0.5 mm beam precision, while Asian electronics contract manufacturers negotiate volume discounts on photodiode variants.
Pricing Analysis
Distributor markups of 15-25% separate direct-to-OEM pricing from component resale channels. Price differentiation hinges on ISO 13849-1 SIL certification tier and after-sales calibration service bundling. Cost compression in standard photoelectric tiers is intensifying because of consolidated procurement through SMT equipment vendors. Electronics assembly buyers in Vietnam and Mexico exhibit highest price sensitivity; pharmaceutical packagers in Switzerland demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs mandate qualified suppliers in both Baden-Württemberg and Taiwan for photodiode arrays. Production draws from Germany, China, and Japan for finished sensors, with indium phosphide wafers and custom ASICs as critical inputs. Single-source vulnerability concentrates in Taiwan foundries serving laser emitter substrates. Distribution runs through system integrators and direct OEM contracts rather than traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with the EU AI Act risk classification mandate for edge-processing sensors driving replacement cycles in European packaging machinery.
For Market Incumbents: Deploy ASIC design captivity as the priority lever. SICK AG and Pepperl+Fuchs should deepen in-house production of custom photodiode arrays to defend against Taiwanese foundry volatility. Certification investment in FDA 21 CFR Part 11 validation documentation compresses deployment windows for pharmaceutical entrants.
For New Entrants and Emerging Players: The 40-60% price-point gap between laser fork sensors and standard photoelectric variants opens mid-tier positioning for inductive fork specialists. India's PLI scheme electronics corridors in Noida and Sri City present the most penetrable geography. Partner with SMT placement equipment vendors for channel access rather than building direct sales.
For Investors and Strategic Acquirers: Asymmetric upside sits with harsh-environment ultrasonic specialists serving IP69K washdown requirements. Five-to-ten year viability favors suppliers with dual competence in optical precision and RFID integration. Watch CSRD traceability mandate expansion across European logistics hubs as the demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Design Captivity | In-house photodiode array production insulates SICK AG from Taiwan foundry lead time volatility. |
| RFID Integration Development | Combined presence-detection and item-identification units address CSRD mandates in European logistics hubs. |
| IP69K Housing Certification | Ultrasonic variants with washdown ratings capture dairy and meat packaging line retrofits. |
| India PLI Corridor Entry | Compact photodiode sensors for Noida and Sri City smartphone assembly verification. |
| ISO 13849-1 SIL Certification | Safety-rated sensor qualification opens automated gate and conveyor replacement demand in Germany. |
Methodological Framework
Bottom-up electronics manufacturing modeling reconciled against top-down sensor fabrication tracking forms the analytical core. Primary interviews with packaging machinery OEMs, automotive weld cell engineers, pharmaceutical validation specialists, and system integrator procurement heads combined with secondary validation from EU Machinery Directive implementation reports, FDA 21 CFR Part 11 guidance documents, and CSRD traceability compliance databases. Triangulation against customs data for indium phosphide wafer imports and ASIC foundry capacity disclosures ensures supply-side calibration.
Input-output matrices map laser diode emitter costs, SIL certification compliance overhead, and channel margin structures across product tiers. Segmentation dimensions include sensor technology type, application environment, end-user industry vertical, and regional regulatory cluster. CAGRs derive from installed base replacement velocity under machinery safety standard upgrades and pharmaceutical traceability mandate expansion. Industry-specific forecast inputs incorporate automotive weld cell retrofit programs and India's PLI scheme electronics assembly capacity buildout.
Caveats apply where Taiwan foundry concentration or EU AI Act re-certification scope expansion could materially shift the outlook. Forecasts reflect assumptions about ISO 13849-1 adoption timelines and CSRD mandate enforcement intensity. Deviation in indium phosphide wafer pricing or ASIC lead time volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Digital Flow Meter Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
Distributed Temperature Sensing Market
Sensors and Controls
Middle East and Africa Pressure Sensors Market
Sensors and Controls
Quantum Dot Sensor Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Ambient Light Sensor Market
Sensors and Controls
Middle-East and Africa Nanosensors Market
Sensors and Controls
Subcool Metering Device Market