
 Digital Barometer Market | 2026-2036
Digital Barometer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Barometer Market Analysis
Project finance for sensor manufacturing infrastructure is narrowing the competitive field to firms with balance-sheet depth. WIKA Alexander Wiegand SE & Co. KG leverages its captive pressure-sensor foundry to control component costs across digital product lines. Honeywell sustains aviation certification pipelines that lock in multi-year OEM contracts. Shenzhen Handsome Technology competes on volume economics for wireless barometer modules sold into marine and HVAC channels.
A digital barometer measures atmospheric pressure using solid-state pressure transducers, typically MEMS-based silicon piezoresistive elements or capacitive ceramic sensors rated for accuracy within ±0.1 hectopascal, converting analog pressure differentials into digital outputs for altitude computation and weather prediction. Digital barometers with Bluetooth connectivity dominate consumer and light-industrial deployments where smartphone integration replaces dedicated display hardware, while capacitive sensors anchor high-precision meteorological installations where drift stability over decades matters more than unit cost. MEMS technology segments fastest in aviation altimetry as FAA and EASA mandate redundant digital pressure sensing for next-generation flight decks.
FAA airworthiness directives and EASA CS-25 certification standards govern pressure-instrument accuracy for commercial aviation, forcing manufacturers to maintain traceable calibration chains back to national metrology institutes. EPA and OSHA industrial monitoring rules extend demand for ruggedized digital barometers in chemical processing and offshore platforms where explosive atmospheres require intrinsically safe pressure instrumentation. Stakeholders must weigh whether to deepen sensor-fabrication capabilities or source MEMS dies from specialized foundries as supply-chain concentration for pressure-sensor wafers tightens procurement risk.
Market Dynamics
Aviation regulatory mandates for redundant digital pressure sensing are forcing hardware refresh cycles across commercial fleets, while MEMS foundry consolidation concentrates component supply among a handful of wafer fabricators.
Growth Catalysts
- FAA and EASA airworthiness directives:Mandates for redundant digital altimetry in next-generation flight decks compel airlines to replace aging mechanical instruments with solid-state pressure transducers.
- EU Green Deal calibration standards:Atmospheric monitoring networks across Central Europe require upgraded instrumentation with traceable metrology chains, tightening replacement cycles for weather stations.
- MEMS piezoresistive miniaturization:Silicon wafer-scale manufacturing drives unit economics for wireless barometer modules, expanding deployment in marine electronics and building automation.
Market Restraints
- MEMS wafer supply concentration:Pressure-sensor die fabrication clusters in Taiwan and South Korea expose procurement pipelines to geopolitical disruption and capacity allocation priority shifts.
- Extended certification timelines:EASA CS-25 and FAA TSO-C88 validation processes for aviation-grade barometers stretch 18-36 months, freezing design iterations and delaying revenue recognition.
- Capacitive ceramic sensor cost floors:High-purity alumina substrates and noble-metal electrode materials resist scale economies, pricing precision meteorological installations above budget-constrained municipal weather services.
Strategic Opportunities
- India Smart Cities Mission:Urban air quality monitoring networks in Delhi, Mumbai, and Bangalore seek cost-optimized digital pressure sensors for dense sensor-grid deployment.
- Bluetooth Low Energy convergence:Integration with smartphone ecosystems and IoT gateways opens consumer hiking and marine channels previously served by dedicated display hardware.
- OSHA Process Safety Management expansion:Chemical processing facilities face upgraded pressure instrumentation mandates for explosive atmosphere zones, creating demand for intrinsically safe digital barometers.
Industry Challenges
- Metrology talent scarcity:Calibration engineers with national standards traceability expertise are concentrated at PTB in Germany and NIST in the US, creating recruitment bottlenecks for manufacturer quality departments.
- Legacy system integration friction:Analog-to-digital signal conversion for existing weather station networks requires custom protocol adapters, extending deployment timelines and inflating project engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Barometer Market |
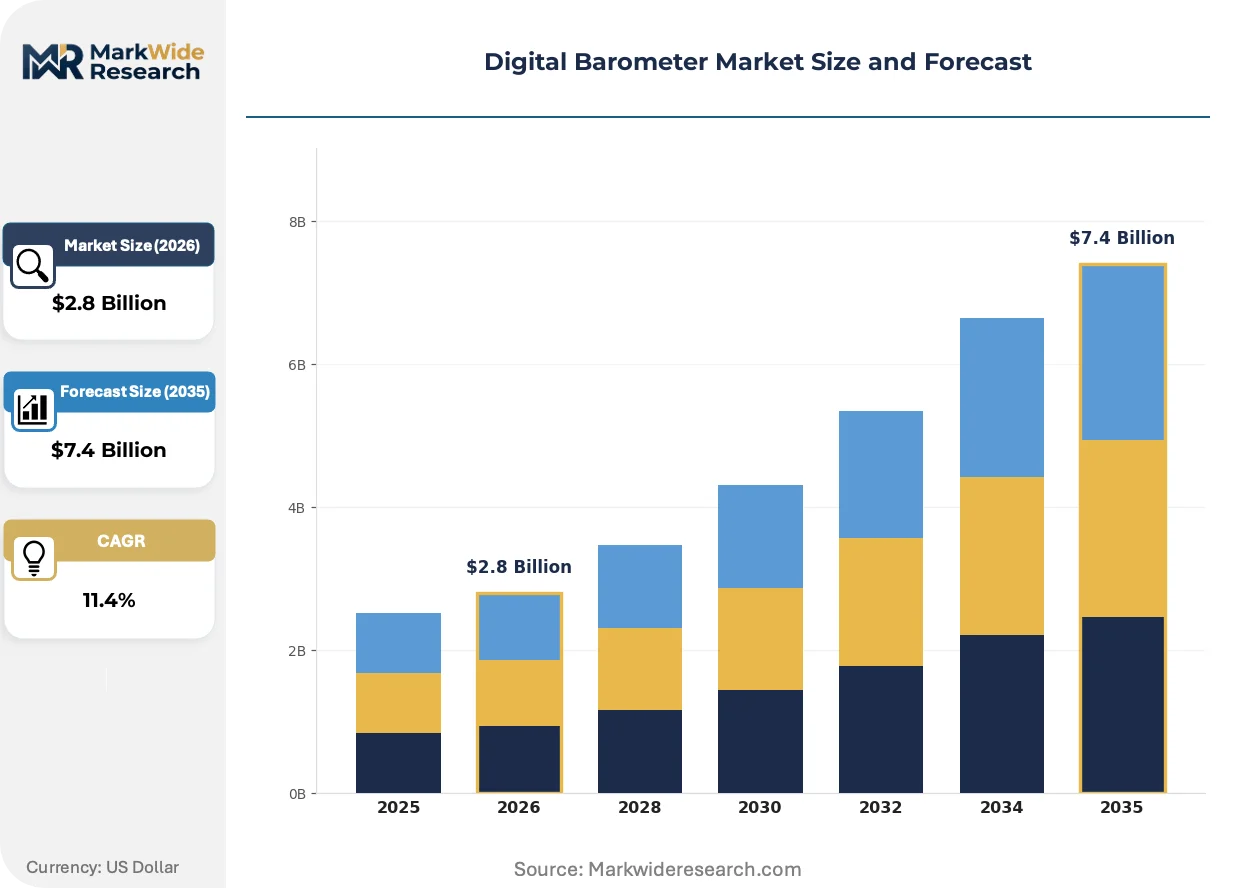
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Barometers, Digital Barometers, Wireless Barometers, Smart Barometers Technology: Capacitive Sensors, Pressure Sensors, MEMS Technology, Bluetooth Connectivity End User: Aviation, Meteorology, Marine, HVAC Application: Weather Forecasting, Altitude Measurement, Industrial Monitoring, Environmental Research |
| Companies Covered | Thermo Fisher Scientific, Traceable Products, WIKA Alexander Wiegand SE & Co. KG, NovaLynx Corporation, Shenzhen Handsome Technology, Ahlborn Mess- und Regelungstechnik, Aquatech Scientific Instruments, Omegadyne, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Barometer Market Emerging Trajectories
Silicon photonics packaging techniques and solid-state sensor fusion are compressing form factors while regulatory pressure on calibration traceability is tightening performance verification protocols across installation types.
Wafer-level vacuum encapsulation of MEMS resonant pressure sensors is rendering obsolete traditional oil-filled stainless steel diaphragm assemblies in aviation altimetry. Airlines retrofitting narrow-body fleets for next-generation flight management systems specify these solid-state packages for their shock resistance and elimination of fluid leakage failure modes. The shift collapses maintenance intervals from 2,000 flight hours to condition-based monitoring.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon-based calibration reference standards is forcing metrology laboratories to adopt nitrogen-filled piston gauges and laser interferometry for pressure traceability. National institutes in Germany, France, and the Netherlands are re-certifying transfer standards ahead of the 2030 ban timeline. High-precision meteorological sensor manufacturers must revalidate entire product lines against the new primary standards.
Marine electronics distributors are unbundling after-sales calibration service contracts from hardware procurement, shifting risk to third-party metrology service providers in Rotterdam, Hamburg, and Singapore. Charter fleet operators now source digital barometers through e-commerce platforms and contract local calibration laboratories for annual recertification. The disintermediation compresses hardware margins while expanding recurring service revenue pools for certified laboratories.
Digital Barometer Market Segmentation
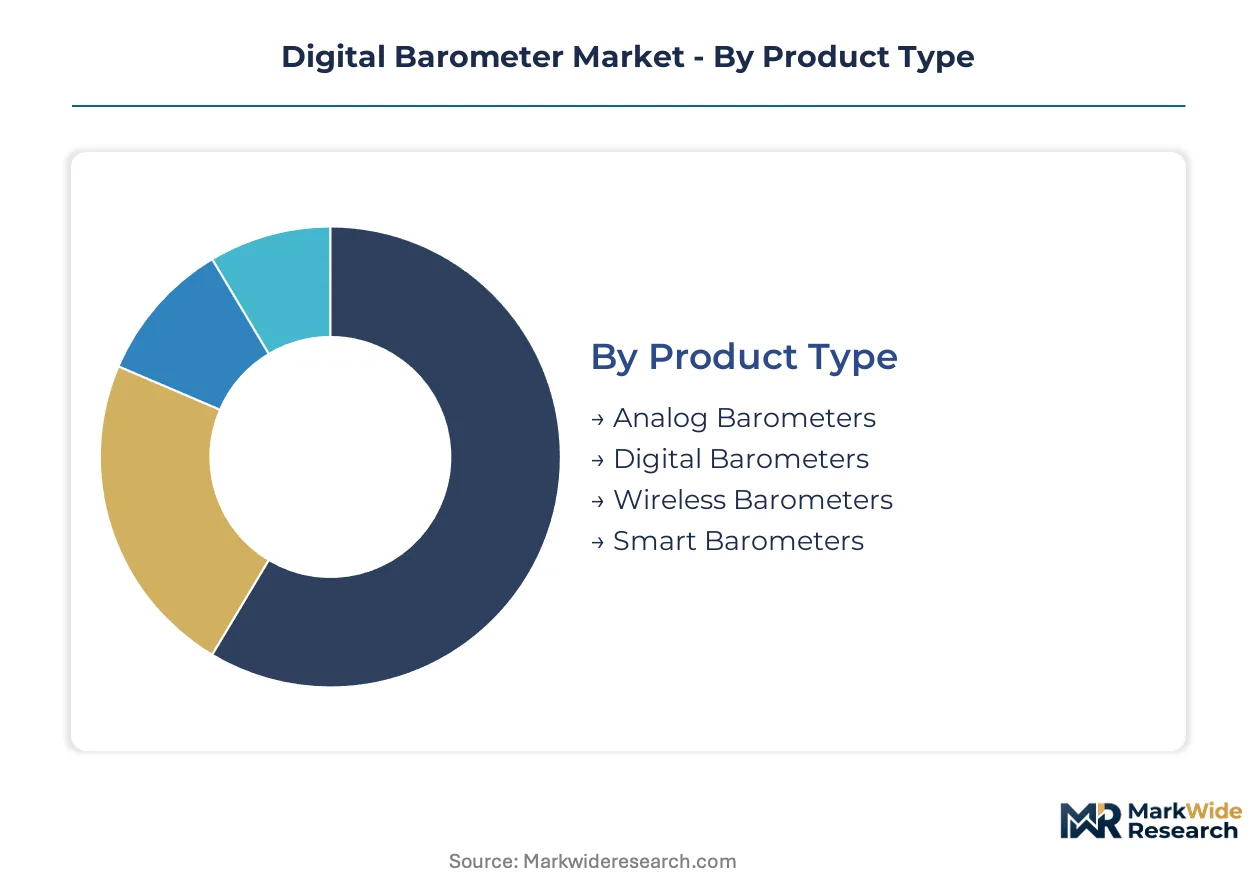
Digital barometer procurement splits sharply between capital-intensive aviation systems demanding decades-long calibration chains and disposable consumer modules where unit cost dominates replacement cycles. Understanding these fault lines reveals where margin pools concentrate and which technical specifications lock in multi-year supplier relationships.
Product Type:
After-sales calibration intensity varies dramatically across product architectures, with aviation-grade instruments requiring annual metrology recertification while consumer wireless units operate maintenance-free until battery depletion.
- Digital Barometers:Solid-state pressure transducers with MEMS piezoresistive elements deliver ±0.1 hectopascal accuracy for flight deck altimetry and meteorological networks. Airlines in Germany and France mandate these for redundant altitude sensing under EASA CS-25 directives, locking in 18-36 month certification pipelines.
- Wireless Barometers:Bluetooth Low Energy modules eliminate dedicated display hardware, integrating with smartphone ecosystems for marine and hiking applications. Shenzhen manufacturing clusters supply these at volume economics for recreational boating channels where annual hardware refresh outpaces calibration investment.
- Smart Barometers:Sensor-fusion packages combining pressure, temperature, and humidity transducers with edge computing for predictive maintenance in building automation.
- Analog Barometers:Mechanical diaphragm instruments with liquid-filled displays retain niche demand from maritime traditionalists and museum-grade weather station restorations.
By volume, Wireless Barometers leads. By growth pace, Smart Barometers is ahead.
Technology:
Component sourcing strategies diverge between captive MEMS foundry operations and merchant wafer procurement, reshaping cost structures and supply security profiles.
- MEMS Technology:Silicon wafer-scale manufacturing enables shock-resistant vacuum-encapsulated resonant pressure sensors. FAA airworthiness directives for next-generation flight decks are displacing oil-filled diaphragm assemblies across narrow-body retrofit programs.
- Bluetooth Connectivity:Radio modules integrated with pressure transducers collapse bill-of-materials costs for consumer marine electronics. Rotterdam and Hamburg distributors now unbundle hardware from calibration contracts, shifting revenue to third-party metrology laboratories.
- Capacitive Sensors:High-purity alumina substrates with noble-metal electrodes achieve drift stability across decades for national meteorological agencies.
- Pressure Sensors:General-purpose piezoresistive elements serving industrial automation and process control applications.
MEMS Technology commands the largest revenue share. Bluetooth Connectivity is expanding most quickly into new application channels.
End User:
Regulatory compliance burdens concentrate in aviation and meteorology, while marine and HVAC segments prioritize procurement flexibility and installation simplicity.
- Aviation:Commercial fleets face mandatory hardware refresh cycles under FAA and EASA redundant sensing mandates. Traceable calibration chains back to PTB Germany or NIST USA lock in supplier relationships for multi-year OEM contracts.
- Meteorology:EU Green Deal atmospheric monitoring standards require upgraded instrumentation with nitrogen-filled piston gauge traceability. Central European agencies in Germany, France, and the Netherlands are re-certifying transfer standards ahead of F-Gas Regulation phase-downs.
- Marine:Charter fleet operators source through e-commerce platforms with local calibration contracting, compressing hardware margins.
- HVAC:Building automation systems specify wireless pressure sensors for zone-level climate control with minimal maintenance overhead.
Aviation generates the highest per-unit revenue. Marine is gaining share fastest through volume channel expansion.
Application:
Performance verification protocols tighten with measurement consequence, separating precision altimetry from environmental sensing where drift tolerance relaxes.
- Altitude Measurement:Flight-critical pressure sensing demands shock-resistant solid-state packages with condition-based monitoring replacing fixed maintenance intervals. Airlines specify these for next-generation flight management system retrofits.
- Weather Forecasting:Dense sensor-grid deployments for urban air quality monitoring in India Smart Cities Mission seek cost-optimized digital pressure sensors. Municipal networks in Delhi and Mumbai prioritize unit economics over decades-long stability.
- Industrial Monitoring:OSHA Process Safety Management mandates drive intrinsically safe instrumentation for chemical processing explosive atmosphere zones.
- Environmental Research:Academic and governmental climate monitoring programs requiring long-term data continuity with minimal sensor drift.
Altitude Measurement anchors premium pricing tiers. Weather Forecasting shows the steepest expansion trajectory through municipal infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and F-Gas Regulation are accelerating hardware refresh cycles across national meteorological networks, while aviation regulatory mandates in North America and Asia-Pacific drive fleet-wide instrument upgrades.
Germany
Precision manufacturing clusters around PTB Braunschweig supply calibration-traceable sensors to Central European weather agencies. The F-Gas Regulation's 2030 phase-down forces metrology laboratories to adopt nitrogen-filled piston gauges. Bavarian sensor fabricators dominate high-precision atmospheric instrumentation for EASA-compliant aviation systems.
United States
FAA airworthiness directives mandate redundant digital altimetry across commercial narrow-body retrofits. NIST maintains primary pressure standards that anchor traceable calibration chains for domestic sensor manufacturers. Aerospace clusters in Greater Seattle and Wichita integrate solid-state pressure transducers into next-generation flight management systems.
China
MEMS foundry capacity in the Yangtze River Delta and Pearl River Delta supplies pressure-sensor dies for wireless barometer modules. The country's dual carbon goals drive urban air quality monitoring grid expansion in Beijing-Tianjin-Hebei. Shenzhen manufacturing clusters dominate volume production of Bluetooth-enabled marine electronics.
India
The Smart Cities Mission funds dense sensor-grid deployment for air quality monitoring in Delhi, Mumbai, and Bangalore. BIS standards for atmospheric instrumentation tighten procurement specifications for municipal weather services. Tamil Nadu and Karnataka electronics corridors assemble cost-optimized digital pressure sensors for government infrastructure contracts.
Netherlands
Rotterdam and Amsterdam port authorities specify marine-grade barometers for charter fleet instrumentation. The country's national metrology institute supports re-certification of transfer standards ahead of EU F-Gas prohibitions. Randstad distribution hubs unbundle hardware procurement from third-party calibration service contracts.
Digital Barometer Market Vendor Landscape
On the supply side, the industry is bifurcating between capital-intensive aviation specialists with captive calibration infrastructure and volume-oriented wireless module assemblers sourcing merchant MEMS dies. German precision manufacturers and Chinese electronics fabricators occupy opposing ends of this spectrum. Strategic archetypes include integrated sensor-foundry operators, certification-anchored aviation suppliers, and scale-driven consumer electronics assemblers. Dominant competitive moves encompass backward integration into MEMS wafer fabrication and geographic expansion into Indian municipal infrastructure channels.
Among German-based precision instrumentation specialists, WIKA Alexander Wiegand SE & Co. KG exemplifies the captive-foundry archetype with in-house pressure-sensor production. Honeywell occupies a position as a certification-anchored aviation supplier with long-standing FAA and EASA approval pipelines. Shenzhen Handsome Technology represents the scale-driven module assembler archetype, leveraging Pearl River Delta manufacturing density for wireless barometer volume production.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Traceable Products |
| WIKA Alexander Wiegand SE & Co. KG |
| NovaLynx Corporation |
| Shenzhen Handsome Technology |
| Ahlborn Mess- und Regelungstechnik |
| Aquatech Scientific Instruments |
| Omegadyne |
| Honeywell |
| Others |
Supply Flow & Price Mechanics
MEMS wafer supply concentration in Taiwan and South Korea exposes procurement pipelines to geopolitical disruption and capacity allocation priority shifts, compressing margins in wireless barometer tiers while amplifying pricing power for aviation-grade instruments with captive foundry operations. This single-source dependency forces tier spreads that separate traceable calibration-anchored systems from disposable consumer modules.
Pricing Analysis
Certification level creates the primary spread across the Digital Barometer Market, with EASA CS-25 and FAA TSO-C88 validation tiers commanding premium positioning against uncertified consumer variants. Three-tier pricing structure separates aviation OEM contracts with multi-year calibration obligations from marine electronics sourced through e-commerce platforms and municipal weather station procurements driven by unit economics. Pricing pressure stems from Shenzhen manufacturing clusters flooding recreational boating channels with Bluetooth-enabled modules. Municipal weather services in India exhibit highest price sensitivity, while commercial aviation fleets prioritize traceability over unit cost.
Supply Chain Analysis
TSMC and GlobalFoundries hold dominant MEMS foundry capacity for pressure-sensor die fabrication, with Yangtze River Delta packaging houses completing wireless module assembly. Taiwan, South Korea, and China anchor geographic supply concentration for silicon wafers and ceramic substrates. High-purity alumina and noble-metal electrodes for capacitive sensors draw from limited specialty chemical suppliers. Single-source vulnerability concentrates in Taiwan Strait logistics corridors. Distribution runs through Rotterdam and Hamburg marine electronics distributors, with unbundled calibration contracts shifting downstream to third-party metrology laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
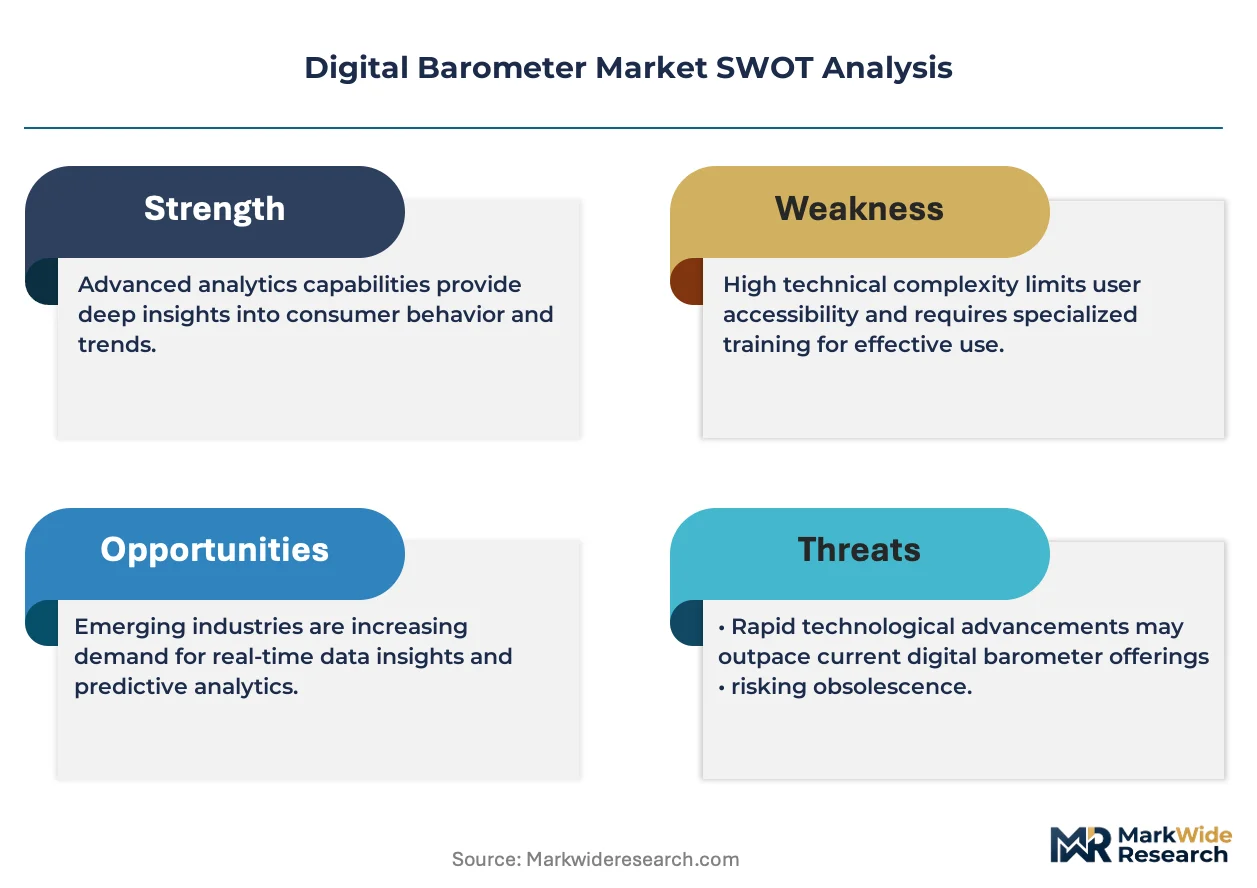
The Digital Barometer Market enters a cyclical recovery phase driven by FAA and EASA mandatory fleet retrofit programs for redundant digital altimetry. Airlines accelerating narrow-body upgrades create sustained demand visibility for certification-anchored suppliers.
For Market Incumbents: Harden supply security through backward integration into MEMS wafer fabrication or long-term foundry capacity reservations, as Taiwan concentration threatens component allocation priority shifts. Deepen calibration infrastructure lock-in with PTB Germany and NIST USA traceability chains to defend against emerging sensor-fusion competitors. Aviation certification pipelines remain the priority defensive lever against volume-oriented module assemblers. For New Entrants and Emerging Players: Pursue white-space opportunities in India Smart Cities Mission municipal contracts, where BIS-standard atmospheric instrumentation procurement lacks established supplier relationships. Target marine charter fleet channels through e-commerce platform integration with local calibration laboratory partnerships. Bluetooth Low Energy convergence with smartphone ecosystems offers the most penetrable go-to-market angle against dedicated display hardware incumbents. For Investors and Strategic Acquirers: The EU F-Gas Regulation 2030 phase-down reshapes the acquisition landscape toward metrology laboratories with nitrogen-filled piston gauge capabilities and sensor manufacturers with revalidated product lines. Long-term viability centers on calibration-traceable revenue streams with recurring service components rather than transactional hardware margins. Watch for EASA accelerated certification timeline reforms as the critical inflection signal for aviation supplier valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Investment | TSMC capacity allocation priority shifts threaten merchant die procurement for aviation-grade sensor manufacturers. |
| Calibration Infrastructure Expansion | PTB Germany traceability chains lock in multi-year OEM contracts with EASA-compliant airlines. |
| Bluetooth Module Volume Scale-Up | Shenzhen manufacturing clusters exploit Pearl River Delta electronics density for marine electronics channels. |
| Smart City Sensor Grid Partnerships | Delhi and Mumbai municipal procurement under India Smart Cities Mission creates dense deployment opportunities. |
| F-Gas Regulation Compliance Repositioning | Nitrogen-filled piston gauge adoption ahead of 2030 ban timeline differentiates metrology service providers. |
Methodological Framework
The analysis maps MEMS piezoresistive, capacitive ceramic, and Bluetooth-connected wireless barometer sub-sectors, each validated through calibration engineers, aviation procurement officers, marine electronics distributors, and municipal weather station operators. Primary interviews with PTB Germany metrologists and FAA certification specialists combined with secondary validation from EASA CS-25 directives, EU F-Gas Regulation filings, and India Smart Cities Mission procurement databases. SEC 10-K filings from listed sensor manufacturers, customs trade data for pressure-sensor wafer flows, and NIST calibration standard publications anchored bottom-up and top-down triangulation.
Assumptions held fixed include EASA and FAA regulatory mandate timelines, EU F-Gas prohibition schedules, and MEMS foundry capacity allocation priorities, while aviation fleet refresh rates and India municipal infrastructure deployment pacing varied across scenarios. Segmentation dimensions modeled encompass product architecture, sensing technology, end-user regulatory burden, and application measurement consequence. CAGRs derived from installed base replacement cycles and new sensor-grid deployment trajectories. Forecast inputs incorporated airline narrow-body retrofit program announcements and China dual carbon goals urban air quality monitoring expansion.
Sensitivities concentrate around Taiwan Strait logistics disruption, EASA certification timeline acceleration, and India BIS standard enforcement intensity. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and foundry capacity expansion. Quarterly review of aviation OEM contract awards, municipal weather station procurement tenders, and MEMS wafer spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
North America Water Detection Sensors Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Consumer Grade Electrochemical CO Sensor Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Europe Vibration Sensors Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
US Distributed Acoustic Sensing Market