

Piece-Level Inventory Tracking and Vision Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Piece-Level Inventory Tracking and Vision Systems Market Insights
Market Dynamics
Machine vision engineering talent scarcity is redrawing competitive boundaries in piece-level tracking, forcing vendors to build automated configuration tools that reduce deployment dependency on specialized integrators. Cognex Corporation leverages its deep learning software stack to sustain margin premiums in high-mix electronics inspection. KEYENCE CORPORATION anchors its position through direct sales engineers who control commissioning timelines for Japanese automotive suppliers. Zebra Technologies competes by extending its RFID hardware into cloud-managed edge deployments for third-party logistics operators.
Technology and Segment Structure
Piece-level inventory tracking and vision systems encompass sensor arrays, image processors, and identification tags that capture dimensional, positional, and serial data at the individual unit level, typically operating at throughputs exceeding sixty frames per second for conveyor-mounted inspection. Their primary purpose is eliminating manual counting errors and enabling reverse-logistics traceability across distributed supply networks. Computer vision applications in quality inspection occupy the highest margin pools due to defect-classification complexity, while RFID deployments in warehouse management represent the fastest-expanding segment as omnichannel fulfillment mandates real-time inventory accuracy. Edge computing deployment modes are gaining traction among food processing operators who must resolve contamination alerts without cloud latency.
Regulatory Environment and Outlook
The EU Falsified Medicines Directive and FDA Drug Supply Chain Security Act shape pharmaceutical adoption by mandating unit-level serialization, while OSHA machine guarding standards influence vision system enclosure designs for manufacturing lines. REACH compliance pressures are restricting certain RFID substrate chemistries, redirecting European demand toward ceramic and paper-based tag alternatives. Stakeholders must monitor evolving EU AI Act conformity requirements for autonomous inspection decisions, as these will determine which vision platforms qualify for regulated pharmaceutical and aerospace deployments without human-in-the-loop overrides.
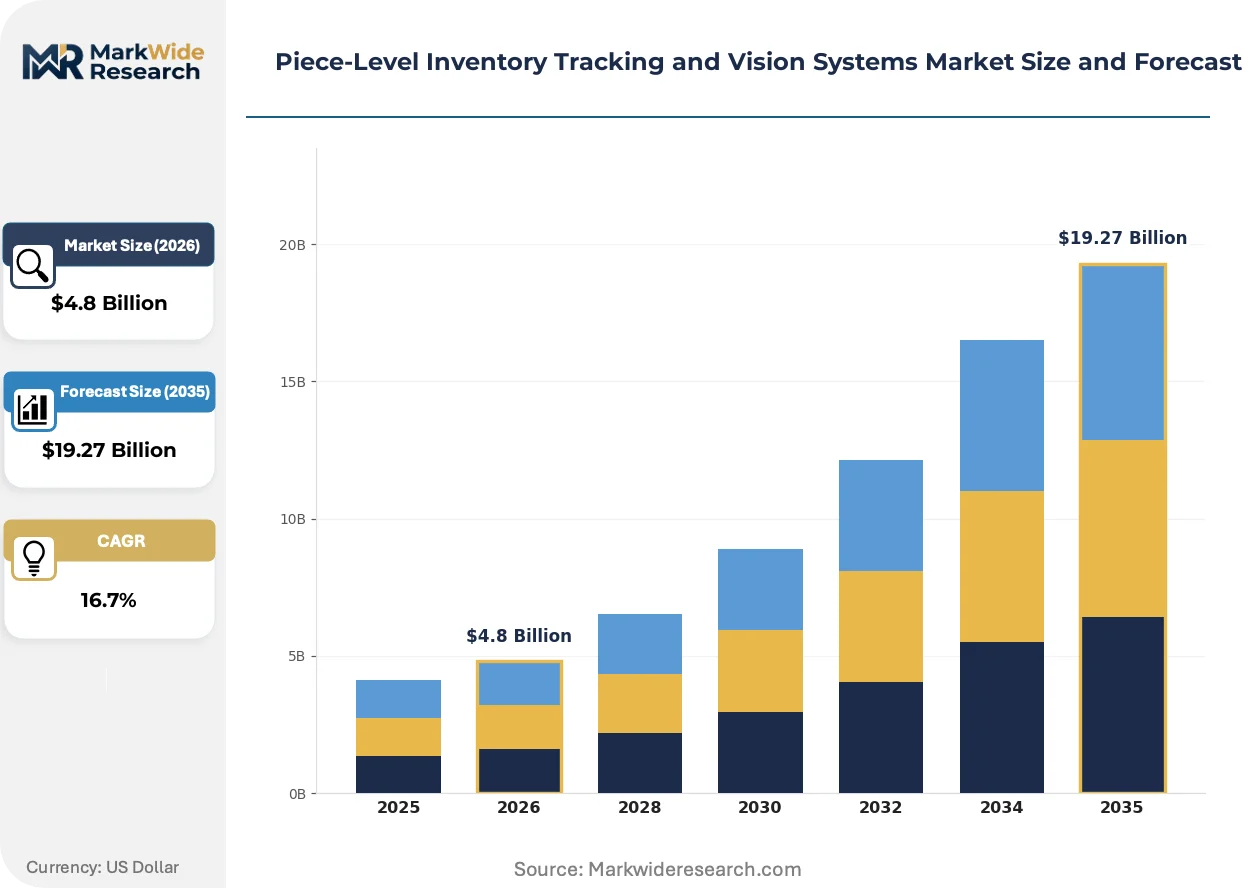
Market Dynamics
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive are compressing deployment timelines for vision systems across European contract manufacturing organizations, forcing vendors to pre-validate hardware configurations before site installation.
Growth Catalysts
- Warehouse robotics integration:E-commerce fulfillment centers in Germany are deploying piece-level RFID tracking to synchronize autonomous mobile robot fleets with real-time inventory positions.
- EU AI Act conformity pathways:Pharmaceutical manufacturers are accelerating procurement of vision platforms with documented algorithmic audit trails to preempt regulatory disqualification.
- Automotive OEM traceability mandates:Just-in-sequence assembly lines at German Tier-1 suppliers now require unit-level barcode verification at every material transfer point.
Market Restraints
- Silicon image sensor supply concentration:Japanese and South Korean foundries control wafer supply for high-speed CMOS sensors used in conveyor-mounted inspection arrays.
- REACH substrate restrictions:ECHA regulations on persistent organic pollutants are eliminating certain polymer RFID inlays from European pharmaceutical packaging lines.
- Deep learning compute costs:Edge GPU modules capable of real-time defect classification at 60+ frames per second carry unit economics that exclude mid-volume food processors.
Strategic Opportunities
- Indian pharmaceutical export corridors:CDSCO serialization requirements for active pharmaceutical ingredient shipments are creating first-mover advantage for vision system vendors with local service presence.
- Hyperspectral imaging convergence:Food safety operators are combining near-infrared spectroscopy with conventional machine vision to detect contamination without physical sampling.
- Cloud-managed edge deployments:Third-party logistics operators are adopting subscription-based vision-as-a-service models to convert capex into operational expenditure.
Industry Challenges
- Machine vision engineering scarcity:System integrators report 18-month lead times for commissioning complex multi-camera pharmaceutical inspection lines due to certified technician shortages.
- FDA validation documentation:Pharmaceutical manufacturers face 12-24 month qualification timelines for computer vision systems used in drug release decisions under 21 CFR Part 11.
- Legacy MES integration friction:Brownfield automotive plants require custom middleware to bridge 1990s-era manufacturing execution systems with modern OPC-UA vision data streams.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piece-Level Inventory Tracking and Vision Systems Market Trends and Innovations
Deep learning inference at the network edge is compressing defect response times from seconds to milliseconds, eliminating cloud dependency for contamination alerts in food processing environments.
Embedded 3D time-of-flight sensors are miniaturizing dimensional inspection capabilities previously requiring multi-camera stereo setups. Automotive seat suppliers in Stuttgart are adopting single-chip solutions for real-time foam density verification at 120 frames per second. This is miniaturizing hardware footprints on crowded assembly stations while collapsing calibration complexity for line engineers.
EMA serialization deadlines for the EU Falsified Medicines Directive are mandating aggregation of unit-level data across secondary and tertiary packaging hierarchies. Contract packagers in Ireland and the Netherlands are deploying vision-guided robotic handling systems to maintain throughput during manual line conversions. Pharmaceutical manufacturers with validated cold chain operations face the steepest compliance penalties for data integrity failures.
Subscription-based vision-as-a-service contracts are displacing perpetual license purchases among third-party logistics operators with variable throughput requirements. German automotive inbound logistics providers are piloting per-scan pricing models for RFID verification at cross-docking facilities. This procurement pattern shift is most visible in European contract manufacturing, where OEM traceability mandates create demand spikes that resist fixed infrastructure commitments.
Piece-Level Inventory Tracking and Vision Systems Market Segmentation
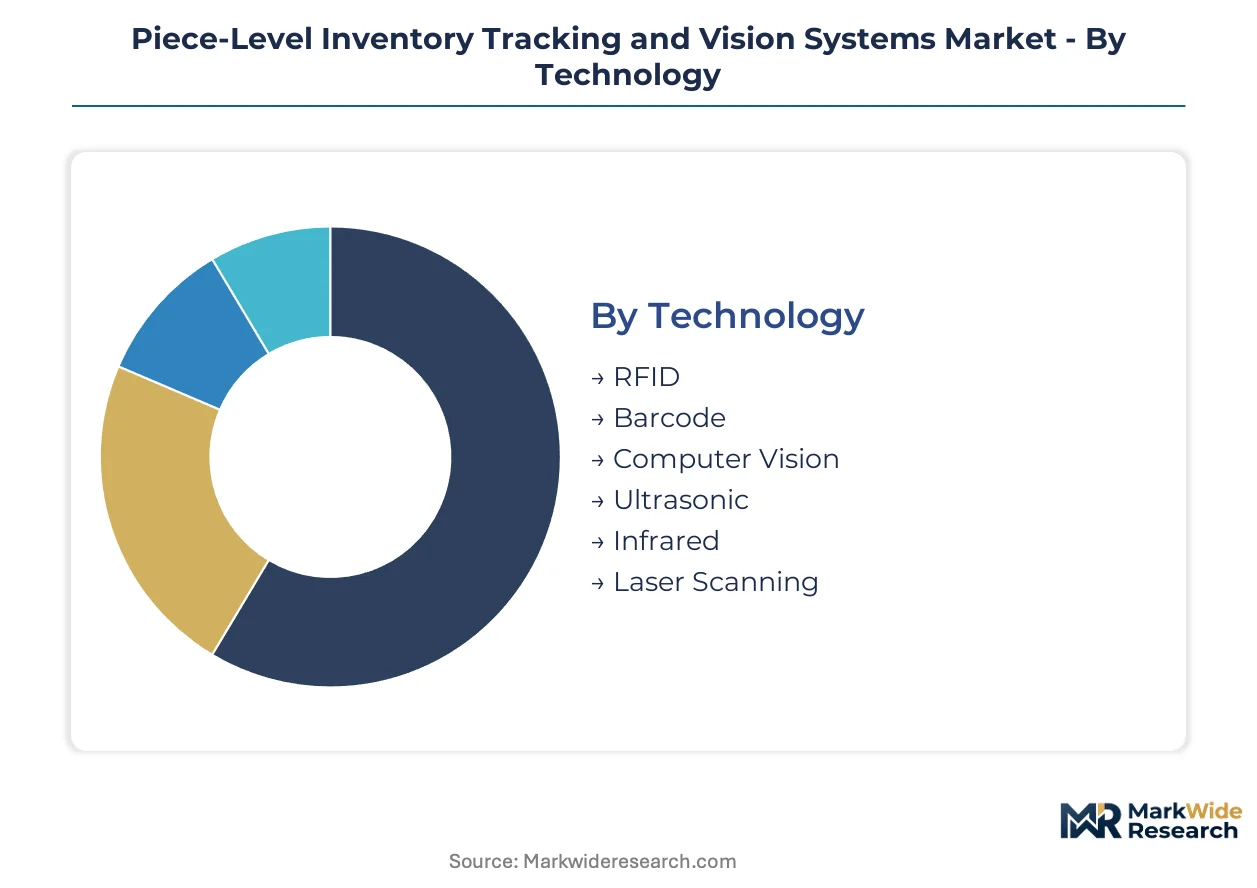
Piece-level tracking systems fragment across multiple technology and deployment dimensions, each carrying distinct margin profiles and integration complexity. Procurement decisions hinge on throughput requirements, regulatory validation burdens, and legacy infrastructure compatibility.
Technology:
Computer vision platforms face intensifying substitution pressure from emerging sensor fusion architectures that combine multiple identification modalities in single hardware units.
- Computer Vision:Deep learning-enabled camera arrays process dimensional and defect data at 60+ frames per second for conveyor-mounted inspection. Pharmaceutical manufacturers in Germany concentrate procurement on platforms with pre-validated algorithmic audit trails to satisfy EMA documentation requirements.
- RFID:Passive and active radio-frequency identification tags enable non-line-of-sight inventory tracking across distributed warehouse networks. E-commerce fulfillment operators in Germany deploy UHF RFID to synchronize autonomous mobile robot fleets with real-time stock positions.
- Barcode:Linear and 2D optical codes remain the lowest-cost unit identification method for high-volume consumer goods. German automotive Tier-1 suppliers mandate barcode verification at every material transfer point on just-in-sequence assembly lines.
- Laser Scanning:LiDAR-based dimensional measurement systems capture sub-millimeter tolerances for quality-critical aerospace components.
- Ultrasonic:Proximity and level sensing technologies penetrate opaque packaging for liquid and bulk material verification.
- Infrared:Thermal imaging arrays detect contamination and seal integrity failures in food processing environments.
Barcode anchors the volume base while computer vision gains share at the steepest rate.
Application:
Cost tier differentiation separates high-investment pharmaceutical validation environments from price-sensitive retail deployments.
- Quality Inspection:Multi-camera vision systems classify surface defects and dimensional deviations for release decisions. FDA 21 CFR Part 11 validation requirements extend pharmaceutical qualification timelines to 12-24 months, creating substantial switching costs.
- Warehouse Management:RFID and barcode infrastructure enables real-time inventory positioning for omnichannel fulfillment. German third-party logistics operators pilot subscription-based per-scan pricing models to convert fixed infrastructure into variable expenditure.
- Manufacturing Lines:Piece-level tracking synchronizes material flow with production schedules in automotive and electronics assembly.
- Logistics:Cross-docking and freight verification applications demand ruggedized hardware for variable environmental conditions.
- Asset Tracking:Returnable container and tooling location systems reduce capital tied up in circulating equipment pools.
- Retail Shelving:Shelf-mounted vision and RFID systems automate out-of-stock detection and planogram compliance monitoring.
Warehouse management commands the largest installed base while quality inspection delivers the highest margin realization.
End User Industry:
Customer type segmentation reveals divergent procurement authority structures between regulated pharmaceutical environments and cost-driven apparel operations.
- Pharmaceuticals:Serialization mandates under the EU Falsified Medicines Directive and FDA Drug Supply Chain Security Act mandate unit-level traceability from active ingredient through patient dispensing. Contract packagers in Ireland and the Netherlands deploy vision-guided robotics to maintain throughput during line conversions for aggregation requirements.
- Automotive Suppliers:OEM traceability mandates penetrate Tier-1 and Tier-2 supplier networks with escalating data granularity requirements. Stuttgart-based seat suppliers adopt embedded 3D time-of-flight sensors for real-time foam density verification at 120 frames per second.
- Consumer Electronics:High-mix assembly lines demand flexible vision configuration for rapid product changeovers.
- Food Processing:Contamination detection and allergen segregation protocols drive edge computing deployment to eliminate cloud latency for critical alerts.
- Aerospace:Part pedigree and counterfeit prevention requirements mandate serialized identification for flight-critical components.
- Apparel:Item-level RFID enables omnichannel inventory accuracy and return processing efficiency for fashion retailers.
Automotive suppliers generate the highest unit volume while pharmaceuticals exhibit the steepest technology upgrade trajectory.
Deployment Mode:
Supply concentration in edge GPU and specialized vision processors shapes procurement options for compute-intensive applications.
- Edge Computing:Local inference execution eliminates network dependency for sub-100-millisecond defect response. Food safety operators resolve contamination alerts without cloud round-trip latency.
- Cloud-Based:Centralized data aggregation and algorithm updates suit distributed retail and logistics networks with consistent connectivity.
- Hybrid:Tiered architectures process time-critical decisions locally while feeding aggregate analytics to cloud platforms.
- On-Premises:Air-gapped installations satisfy pharmaceutical and defense security requirements for isolated operational technology environments.
Edge computing captures the fastest expansion trajectory while on-premises retains dominance in regulated validation environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA serialization deadlines under the EU Falsified Medicines Directive are compressing procurement timelines across European contract manufacturers, while FDA mandates and CDSCO export requirements are simultaneously reshaping investment patterns in North America and India.
Germany
Automotive OEM traceability mandates penetrate Tier-1 supplier networks with escalating data granularity requirements. KBA enforcement of component pedigree documentation compels Stuttgart-based seat suppliers to deploy embedded 3D time-of-flight sensors for real-time foam density verification at 120 frames per second.
United States
FDA 21 CFR Part 11 validation requirements extend pharmaceutical vision system qualification timelines to 12-24 months, creating substantial switching costs for drug manufacturers. The FDA Drug Supply Chain Security Act mandates unit-level serialization from active ingredient through patient dispensing, driving Midwestern contract packagers toward pre-validated hardware configurations.
India
CDSCO serialization requirements for active pharmaceutical ingredient shipments are creating first-mover advantage for vision system vendors with local service presence. Maharashtra-based pharmaceutical exporters face tightening documentation standards for EU and US-bound shipments, accelerating adoption of aggregation-capable vision-guided robotic handling systems.
Japan
PMDA pharmaceutical manufacturing standards and METI industrial automation incentives converge to sustain demand for high-speed CMOS sensor arrays. Automotive suppliers in the Nagoya-Toyota industrial corridor deploy piece-level barcode verification at every material transfer point to satisfy domestic OEM traceability protocols.
China
NMPA medical device serialization requirements and SAMR product quality traceability mandates are expanding addressable market for unit-level identification systems. Yangtze River Delta electronics contract manufacturers integrate machine vision for high-mix assembly lines facing rapid product changeover pressures.
Piece-Level Inventory Tracking and Vision Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, producing a tiered structure where deep learning software stacks command margin premiums while hardware-centric vendors compete on deployment speed. The market fragments across three strategic archetypes: integrated automation conglomerates with captive vision divisions, pure-play machine vision specialists with proprietary algorithm stacks, and industrial identification hardware vendors extending into cloud-managed edge deployments. Dominant competitive moves include vertical integration into specialized image sensor supply and strategic partnerships with warehouse robotics OEMs to secure fleet synchronization contracts.
Within the pure-play specialist tier, Cognex Corporation and KEYENCE CORPORATION exemplify divergent go-to-market approaches, with the former anchoring high-mix electronics inspection through software-defined configuration tools and the latter controlling commissioning timelines through direct sales engineer deployment. Zebra Technologies occupies a position bridging industrial identification hardware and subscription-based edge management platforms for third-party logistics operators. These three companies represent the primary competitive anchors around which mid-cap specialists and regional system integrators orbit.
| Leading Market Players |
|---|
| Cognex Corporation |
| KEYENCE CORPORATION |
| Omron Corporation |
| Teledyne Technologies |
| Basler AG |
| Siemens |
| Zebra Technologies |
| Honeywell International |
| NVIDIA |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month commissioning lead times for complex multi-camera pharmaceutical inspection lines concentrate pricing power with certified system integrators who control deployment timelines. This supply bottleneck feeds into tiered pricing structures where validated configurations command substantial premiums over standard hardware.
Pricing Analysis
German automotive Tier-1 suppliers pay 15-25% premiums over Asian contract manufacturers for identical vision hardware due to embedded validation documentation and local commissioning support. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical platforms from logistics-grade RFID deployments. Cost compression in mid-volume food processing tiers is intensifying because edge GPU modules exclude smaller operators from real-time defect classification. Third-party logistics operators exhibit highest price sensitivity, accelerating adoption of subscription-based per-scan models that convert fixed infrastructure into variable expenditure.
Supply Chain Analysis
Sixty-day sensor inventory cycles at Japanese and South Korean foundries constrain wafer availability for high-speed CMOS arrays used in conveyor-mounted inspection. Production concentrates in Japan, South Korea, and Taiwan for silicon image sensors, while edge GPU modules draw from NVIDIA's supply network and specialized vision processor vendors. REACH substrate restrictions on polymer RFID inlays create regulatory risk for European pharmaceutical packaging lines. Distribution runs through direct sales engineer networks for complex pharmaceutical validations, contrasting with distributor channels for standard logistics hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where interoperability between vision systems and warehouse robotics fleets determines competitive survival. OPC-UA data standardization and cloud-managed edge architectures are reshaping procurement authority toward logistics operators seeking fleet synchronization.
For Market Incumbents: Consolidate algorithmic audit trail capabilities to preempt EU AI Act disqualification, and deepen captive supply of specialized image sensors to insulate margins from wafer allocation volatility. Deep learning software stacks face substitution pressure from sensor fusion architectures; backward integration into CMOS sensor supply secures throughput guarantees for pharmaceutical validation environments. For New Entrants and Emerging Players: Lead with subscription-based vision-as-a-service models targeting Indian pharmaceutical exporters facing CDSCO serialization deadlines, where local service presence creates first-mover advantage. Cloud-managed edge deployments for variable-throughput third-party logistics operators represent the most penetrable segment, with per-scan pricing models converting capex-resistant buyers into recurring revenue streams. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because pharmaceutical serialization mandates under EMA and FDA jurisdictions create durable switching costs and 12-24 month validation timelines that entrench incumbent positions. Acquisition targets should display pre-validated hardware configurations and established algorithmic audit trails. Watch EU AI Act conformity pathway announcements as the signal indicating which vision platforms qualify for autonomous inspection without human-in-the-loop overrides.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | OPC-UA standardization bridges legacy MES with modern vision data streams for brownfield automotive plants. |
| Strategic Partnership | Warehouse robotics OEM alliances secure fleet synchronization contracts in German e-commerce fulfillment centers. |
| Acquisition of Specialist Firm | Deep learning software stacks command margin premiums in high-mix electronics inspection environments. |
| Geographic Expansion | Local service presence in Maharashtra captures CDSCO-driven demand from pharmaceutical API exporters. |
| Product Launch | Embedded 3D time-of-flight sensors miniaturize dimensional inspection for crowded automotive assembly stations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and hyperscaler capex disclosures to establish baseline market sizing. Interviews with machine vision system integrators, pharmaceutical manufacturing engineers, automotive Tier-1 procurement leads, and third-party logistics operators provided deployment timeline and pricing validation. Secondary sources include EMA serialization guidance documents, FDA 21 CFR Part 11 validation protocols, and SEC filings from listed automation vendors. Bottom-up unit economics triangulate against top-down industry spend estimates.
Segmentation dimensions modeled encompass technology modality, application environment, end-user industry vertical, and deployment architecture across the analysis window. Pharmaceutical serialization mandate deadlines, automotive OEM traceability requirement escalations, and warehouse robotics fleet penetration curves inform demand-side projections. CAGRs derive from installed base growth rates, replacement cycle compression, and technology substitution elasticities observed in comparable automation markets.
Underlying assumptions cover sustained enforcement of EMA and FDA serialization deadlines, with deviation risk concentrated in silicon image sensor supply disruptions from foundry concentration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.