
 Laser Sensor Market | 2026-2036
Laser Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Sensor Market Intelligence
A widening capability gap between photonics-integrated specialists and component assemblers is reorganizing competitive tiers in the laser sensor industry. Keyence leverages in-house semiconductor foundry partnerships to sustain margin control across its triangulation sensor portfolio. SICK AG anchors its position through backward integration into custom ASIC design for industrial time-of-flight modules. Baumer competes by dominating niche applications in high-speed packaging inspection where response latency defines purchasing criteria.
Laser sensors are electro-optical devices that emit coherent light pulses or continuous wave signals to measure distance, displacement, velocity, or object presence with resolutions reaching sub-micron levels in triangulation configurations. These instruments convert optical return signals into electrical data for closed-loop control in automated manufacturing, autonomous mobility, and precision metrology systems. Solid-state laser sources now lead volume shipments due to reliability gains and elimination of mechanical scanning components, while photonic integrated circuit architectures represent the fastest-growing technology tier as silicon photonics foundries reduce packaging costs. Time-of-flight applications in robotics and security command the largest share of end-user revenue, though precision agriculture deployments are accelerating as variable-rate equipment spreads.
FDA laser product performance standards govern safety classifications for sensors deployed in medical and consumer proximity applications, while FCC emissions rules constrain radio-frequency interference from integrated data transmission modules. The EU Machinery Directive and CE marking requirements enforce functional safety validation for laser sensors operating alongside human workers in automated production cells. Stakeholders must monitor divergence between regional electromagnetic compatibility test protocols and emerging photonics-specific sustainability disclosure rules that could reshape supplier qualification timelines.
Market Dynamics
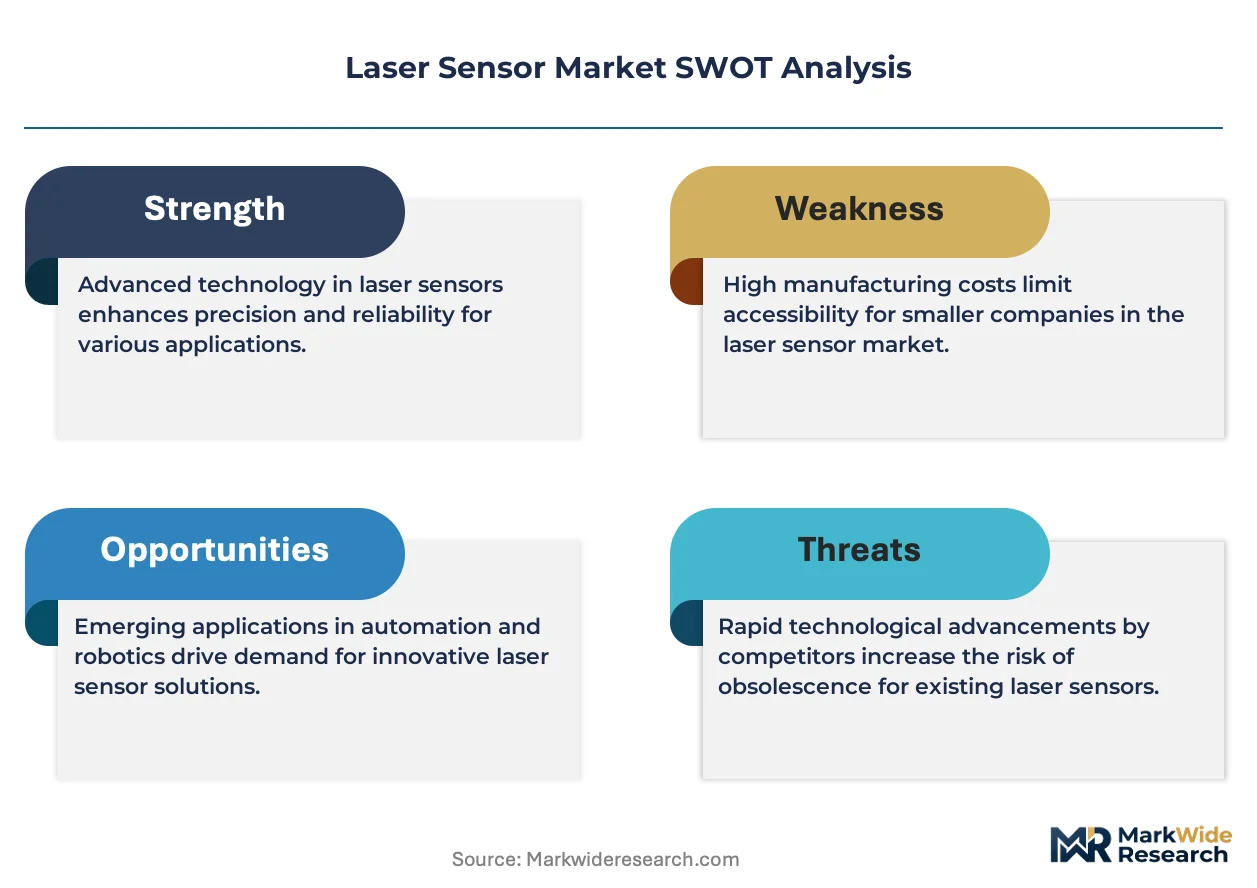
Photonic integrated circuit architectures are compressing component counts and packaging costs, forcing legacy module assemblers to either acquire silicon photonics capabilities or retreat to low-margin aftermarket service roles.
Growth Catalysts
- EU AI Act compliance mandates:Machinery safety directives now require performance verification for optical sensing equipment in collaborative robot environments, pulling demand for certified time-of-flight modules.
- Autonomous navigation procurement:Automotive OEMs are expanding specification-setting for LiDAR and distance measurement modules in production vehicle programs.
- Precision agriculture variable-rate equipment:Deployment of laser-guided spraying and planting systems is accelerating sensor volume in North American and European farming operations.
Market Restraints
- Indium phosphide substrate volatility:Supply concentration for III-V semiconductor materials creates input cost instability for solid-state laser source production.
- CE marking functional safety validation:The EU Machinery Directive imposes extended certification timelines that delay revenue recognition for collaborative robot sensor deployments.
- Camera-based stereo vision substitution:Machine learning-enhanced 2D imaging systems are capturing price-sensitive displacement measurement applications below 50-micron precision requirements.
Strategic Opportunities
- India precision manufacturing clusters:PLI scheme incentives for electronics manufacturing are attracting module assembly investment as domestic automotive and pharmaceutical automation expands.
- Silicon photonics-MEMS convergence:Foundry integration of optical phased arrays with micro-electromechanical steering is enabling chip-scale solid-state LiDAR without mechanical scanning components.
- Outcome-based sensor service contracts:Industrial end-users in Germany are unbundling hardware purchase from calibration and uptime guarantees, creating recurring revenue streams for integrated solution providers.
Industry Challenges
- Photonics-electronics packaging skill scarcity:Talent gaps in optical alignment and thermal management for multi-channel transceiver modules constrain production ramp rates.
- ISO/IEC 60825 laser safety certification complexity:Divergent regional interpretations of maximum permissible exposure testing extend product qualification cycles for medical and consumer proximity applications.
- Legacy PLC integration friction:Brownfield manufacturing facilities require protocol translation layers that degrade real-time response latency in closed-loop control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Sensor Market |
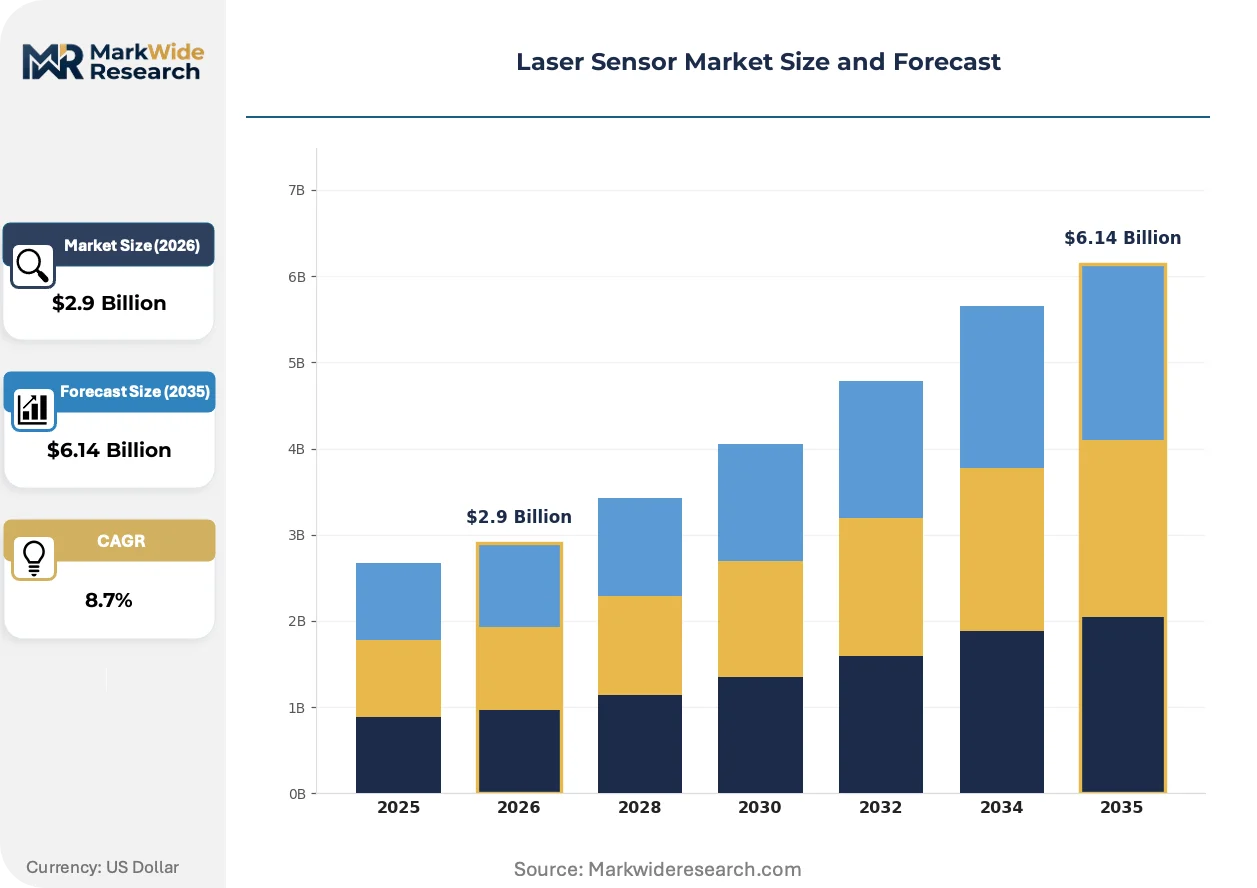
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time-of-Flight, Triangulation, Phase Shift, Time Correlated Single Photon Counting, Frequency Modulated Continuous Wave Technology: Solid State, MEMS, Fiber Optic, LIDAR, Photonic Integrated Circuit Application: Robotics, Security & Surveillance, Consumer Electronics, Environmental Monitoring, Precision Agriculture End User: OEMs, Tier-1 Suppliers, Research Institutes, Military & Defense, Construction Firms |
| Companies Covered | SICK AG, Banner Engineering, Keyence, IFM Electronic, Micro-Epsilon, Panasonic, OMRON, Baumer, Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Sensor Market Strategic Shifts & Innovations
Silicon photonics foundry economics are rewriting cost structures across distance measurement and spectral sensing applications, compressing the viable competitive set to players with captive wafer access or deep foundry partnerships.
Solid-state laser sources is miniaturizing through photonic integrated circuit architectures that replace discrete lens assemblies with on-chip waveguides and gratings. Automotive LiDAR developers are qualifying these devices for 2026-2027 production ramps. The technology is miniaturizing module footprints by 60-70% while eliminating mechanical scanning failure modes, enabling roofline-integrated sensor pods that preserve vehicle aerodynamics.
REACH substance restrictions on lead and cadmium in optical coatings are forcing reformulation of dielectric stacks used in high-power laser sensor front optics. Industrial time-of-flight module suppliers face supply chain requalification costs that favor larger players with in-house thin-film deposition capabilities. German precision manufacturing clusters are responding fastest due to existing environmental compliance infrastructure and customer specification pressure.
Specification-setting authority is migrating from distributor technical sales teams to end-user central engineering functions with direct foundry relationships. Automotive and aerospace OEMs in Japan and Germany are bypassing traditional sensor distributors to negotiate volume pricing and custom wavelength configurations directly with photonics foundries. This channel compression is most visible in time-of-flight applications above 100-meter range where performance differentiation justifies direct engagement.
Laser Sensor Market Segmentation
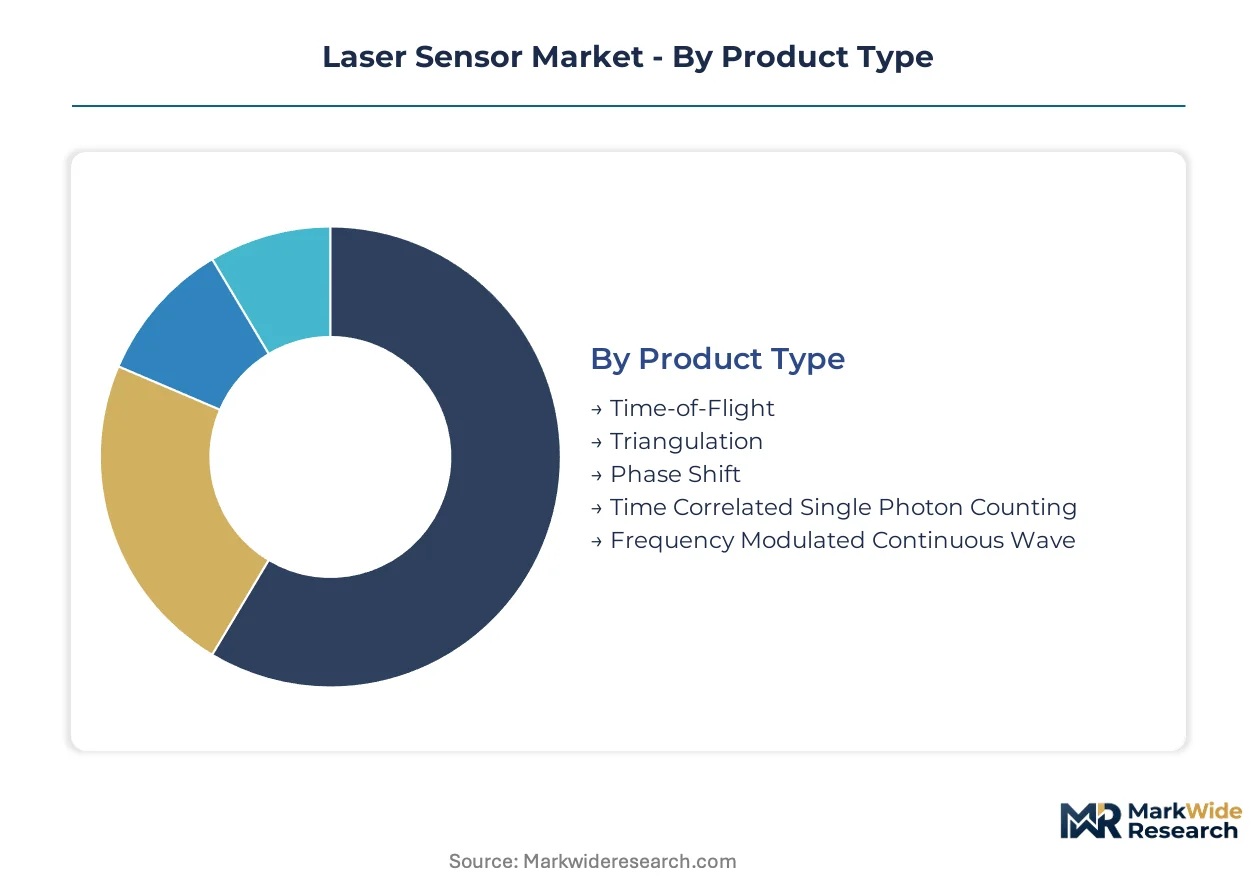
Laser sensor architectures vary dramatically in cost structure and performance envelope, creating distinct margin pools across measurement principles and integration technologies. Procurement patterns diverge sharply between automotive specification-setting and industrial aftermarket replacement cycles.
Product Type:
Margin concentration sits with long-range modules where optical precision commands premium pricing against camera-based alternatives.
- Time-of-Flight:Emits pulsed laser signals and measures return interval to calculate distance with centimeter precision across 100-meter ranges. Automotive OEMs in Germany and Japan are qualifying solid-state variants for autonomous navigation programs, pulling volume from mechanical scanning LiDAR. The dominant share belongs to Time-of-Flight, while Triangulation is closing the gap fastest.
- Triangulation:Projects angular displacement onto position-sensitive detectors to achieve sub-50-micron resolution at close range. High-speed packaging lines in pharmaceutical manufacturing clusters specify these for dimensional verification where response latency determines throughput.
- Phase Shift:Compares phase difference between emitted and reflected continuous-wave signals for medium-range industrial positioning.
- Time Correlated Single Photon Counting:Detects individual photon arrivals to enable extreme low-light ranging for scientific metrology.
- Frequency Modulated Continuous Wave:Sweeps optical frequency to encode distance in beat frequency, emerging in coherent LiDAR architectures.
Time-of-Flight captures the dominant revenue position, though Triangulation modules are expanding most quickly in precision manufacturing applications.
Technology:
Silicon photonics integration is redrawing competitive boundaries by collapsing packaging costs for multi-channel architectures.
- Solid State:Eliminates mechanical scanning through electronically steered optical phased arrays. Automotive qualification programs in Germany and Japan are driving 2026-2027 production ramps for roofline-integrated sensor pods.
- Photonic Integrated Circuit:Monolithically integrates lasers, modulators, and detectors on silicon substrates. Foundry economics at scale favor players with captive wafer access or deep foundry partnerships in Taiwan and the Netherlands.
- MEMS:Micro-electromechanical mirrors enable compact beam steering for mid-range industrial scanners.
- Fiber Optic:Delivers laser excitation to remote sensing heads for harsh-environment displacement measurement.
- LIDAR:Mechanical scanning systems retain installed base in mapping and defense applications.
Solid State technology leads volume shipments, with Photonic Integrated Circuit architectures gaining share fastest as silicon photonics foundries reduce unit costs.
Application:
Procurement concentration varies by specification authority, with automotive central engineering functions bypassing traditional distribution channels.
- Robotics:Collaborative robot deployments require ISO-compliant time-of-flight modules for human presence detection. EU AI Act compliance mandates are accelerating certified sensor procurement in German automotive manufacturing clusters.
- Security & Surveillance:Perimeter monitoring systems integrate long-range laser rangefinders with thermal imaging for threat classification at border installations.
- Consumer Electronics:Proximity sensing and facial recognition drive VCSEL-based short-range modules in smartphone and tablet devices.
- Environmental Monitoring:Differential absorption LiDAR tracks atmospheric particulate concentrations for regulatory compliance reporting.
- Precision Agriculture:Variable-rate spraying and planting equipment in North American farming operations specifies laser-guided boom control.
Robotics commands the largest end-use revenue, while Precision Agriculture is climbing the fastest as variable-rate equipment spreads beyond early-adopter regions.
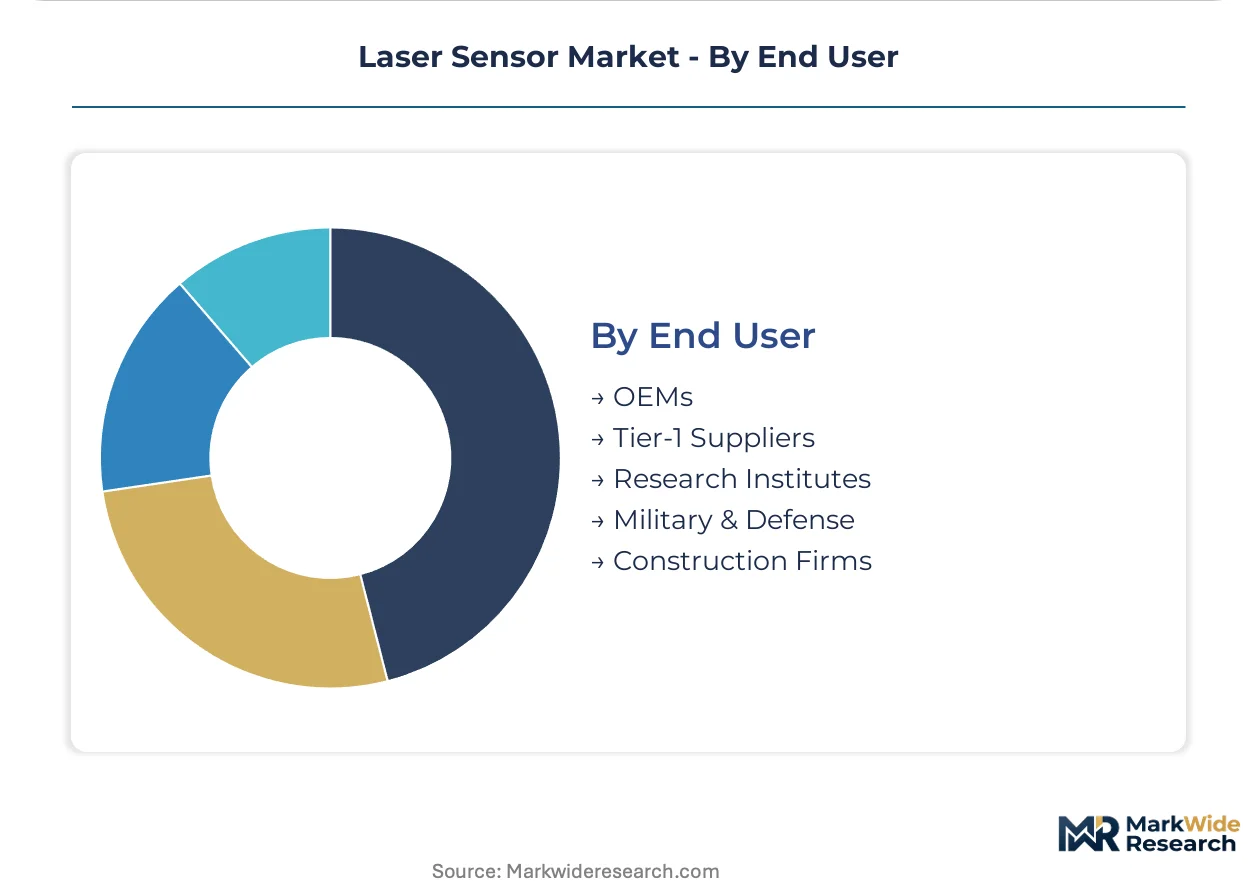
End User:
Channel compression is most visible where performance differentiation justifies direct foundry engagement over distributor technical sales.
- OEMs:Automotive and aerospace manufacturers negotiate custom wavelength configurations directly with photonics foundries. German and Japanese OEMs are establishing volume pricing frameworks for 2026-2027 production ramps.
- Tier-1 Suppliers:Module integrators face margin pressure from backward integration by OEMs and forward integration by component specialists.
- Research Institutes:National laboratories specify custom time-correlated single photon counting systems for quantum sensing development.
- Military & Defense:Secure ranging and target designation programs require ITAR-compliant supply chains with domestic packaging capabilities.
- Construction Firms:Surveying and machine control applications favor ruggedized phase-shift modules for earthmoving equipment.
OEMs hold the dominant procurement position, with Tier-1 Suppliers defending relevance through system integration and calibration service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs demonstrate the lowest price elasticity, absorbing premium solid-state LiDAR modules for autonomous programs, while Indian precision manufacturing clusters exhibit acute cost sensitivity that favors triangulation sensor imports over domestic photonics investment.
Germany
Automotive central engineering functions at BMW, Mercedes-Benz, and Volkswagen negotiate directly with silicon photonics foundries for 2026-2027 LiDAR production ramps. The EU AI Act and Machinery Directive enforce ISO-compliant time-of-flight certification for collaborative robot deployments. Stuttgart and Munich precision manufacturing clusters anchor specification-setting for industrial sensor standards across European Tier-1 supply chains.
United States
FDA laser product performance standards govern safety classifications for medical proximity sensors, while FCC emissions rules constrain integrated data transmission modules in security applications. FDA and FCC dual compliance extends qualification timelines for consumer electronics deployments. Detroit automotive engineering centers and Silicon Valley autonomous vehicle developers split procurement between mechanical scanning LiDAR and solid-state photonic integrated circuit architectures.
Japan
METI industrial policy supports domestic photonics foundry capacity for automotive LiDAR qualification programs at Toyota and Honda. JIS standards and METI guidance shape performance benchmarks for robotics integration. Nagoya and Osaka precision equipment clusters concentrate module assembly for export to Southeast Asian electronics manufacturing.
China
MIIT standards and GB certification requirements compress product development cycles for domestic LiDAR suppliers serving NIO, XPeng, and Li Auto. SAMR market regulation and dual carbon goals accelerate solid-state laser source adoption over mechanical scanning systems. Yangtze River Delta and Pearl River Delta manufacturing corridors concentrate photonic integrated circuit packaging investment.
India
PLI scheme incentives for electronics manufacturing attract module assembly investment as domestic automotive and pharmaceutical automation expands. BIS certification requirements and DGFT import duties on finished sensors create localization pressure. Gujarat and Maharashtra precision manufacturing clusters drive specification-setting for cost-optimized triangulation sensors in packaging inspection.
Laser Sensor Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the laser sensor industry. Keyence and SICK AG anchor the upper tier through captive semiconductor capabilities and custom ASIC design, while mid-scale specialists compete on niche application dominance. Three archetypes define competitive positioning: photonics-integrated foundry partners, backward-integrated industrial automation houses, and precision measurement specialists. Consolidation pressure favors M&A activity among module assemblers lacking silicon photonics access, while strategic partnerships between automotive OEMs and foundries accelerate channel compression.
Among Germany-based industrial sensor houses, SICK AG exemplifies the backward-integrated archetype through custom ASIC design for time-of-flight modules. Japanese precision automation conglomerates Keyence and OMRON occupy positions spanning photonics foundry partnerships and high-speed packaging inspection specialization. These three companies represent the competitive spectrum from captive semiconductor control to niche application dominance, with each archetype defending margin pools through distinct integration strategies.
| Leading Market Players |
|---|
| SICK AG |
| Banner Engineering |
| Keyence |
| IFM Electronic |
| Micro-Epsilon |
| Panasonic |
| OMRON |
| Baumer |
| Rockwell Automation |
| Others |
Cost & Logistics Intelligence
CE marking functional safety validation gates both supplier qualification timelines and price differentiation between certified and uncertified time-of-flight modules in European collaborative robot deployments. This dual gating mechanism compresses margins for assemblers lacking in-house compliance infrastructure while amplifying pricing power for photonics-integrated specialists with captive certification pathways.
Pricing Analysis
After-sales service contracts and calibration subscriptions now drive lifetime value capture for industrial laser sensor vendors. Pricing stratifies across premium, standard, and economy tiers based on ISO compliance grade and volume commitment scale. Cost compression in the economy tier intensifies as camera-based stereo vision substitutes capture displacement applications below 50-micron precision. Automotive OEMs in Germany demonstrate the lowest price sensitivity, absorbing premium solid-state LiDAR modules for autonomous navigation programs.
Supply Chain Analysis
Strategic stockpiling of indium phosphide substrates characterizes procurement behavior among solid-state laser source manufacturers facing III-V semiconductor supply concentration. Taiwan, the Netherlands, and Germany anchor photonic integrated circuit fabrication and custom ASIC design. Production draws from concentrated III-V epitaxy capacity for laser diodes, silicon wafers for photonic integration, and precision optical substrates for front-end optics. Single-source vulnerability in indium phosphide substrate supply creates input cost instability. Distribution runs through direct foundry relationships for automotive OEMs and technical distributor networks for industrial aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as specification-setting authority migrates from distributor technical sales to end-user central engineering functions, creating niche openings for specialized module providers with direct foundry access or unique calibration capabilities.
For Market Incumbents: Fortify margin position through backward integration into custom ASIC design and captive silicon photonics foundry partnerships. Defend against channel compression by automotive OEMs through bundling outcome-based uptime guarantees with hardware supply. Prioritize certification investment for EU AI Act compliance to maintain specification-setting authority in German precision manufacturing clusters.
For New Entrants and Emerging Players: Differentiate on response latency performance in high-speed packaging inspection where Baumer's niche dominance leaves white space for cost-optimized alternatives. Target India's PLI scheme-supported precision manufacturing clusters with localized triangulation sensor assembly. Pursue foundry partnership routes rather than capital-intensive captive wafer investment.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward certified module providers with established ISO compliance pathways. Long-term viability centers on photonics-electronics packaging capabilities and direct automotive OEM relationships. Monitor silicon photonics-MEMS convergence progress as inflection indicator for chip-scale solid-state LiDAR commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Secures wafer access for automotive LiDAR qualification programs at German and Japanese OEMs. |
| Custom ASIC Design Capability | Enables backward integration that defends margin pools in industrial time-of-flight modules. |
| EU AI Act Certification Investment | Opens specification-setting authority for collaborative robot sensor deployments in Stuttgart clusters. |
| Outcome-Based Service Contract Launch | Captures recurring revenue from German industrial end-users unbundling hardware from calibration. |
| India Module Assembly Localization | Exploits PLI scheme incentives for cost-optimized triangulation sensor production. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation across regulatory and trade databases. Conversations engaged photonics foundry engineering directors, automotive OEM sensor procurement leads, industrial automation plant engineers, and Tier-1 module integrator executives. Secondary sources encompassed FDA laser product performance standards filings, EU Machinery Directive guidance documents, SEC 10-K disclosures from listed automation conglomerates, and customs trade data for photonic integrated circuit imports. Bottom-up and top-down triangulation reconciled module shipment estimates with end-use equipment production volumes.
Across the projection horizon, the analytical framework modeled demand across product architecture, integration technology, application segment, and end-user procurement channel. CAGRs derived from segment-level volume trajectories weighted by average selling price evolution. Forecast inputs incorporated automotive LiDAR qualification timelines, REACH substance restriction compliance costs for optical coating reformulation, and PLI scheme incentive uptake rates in Indian precision manufacturing.
Decision-makers should treat outputs as directional under assumptions of stable III-V semiconductor substrate supply and sustained automotive OEM direct foundry engagement; material deviation would warrant model refresh. Revision becomes warranted when indium phosphide price volatility or regulatory divergence between EU and US laser safety standards crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Automotive Steering Sensors Market
Sensors and Controls
Global Temperature Sensors Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Latin America Lidar Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Temperature Controller Market