
 Peritoneal Cancer Treatment Market | 2026-2036
Peritoneal Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Peritoneal Cancer Treatment Market Analytics
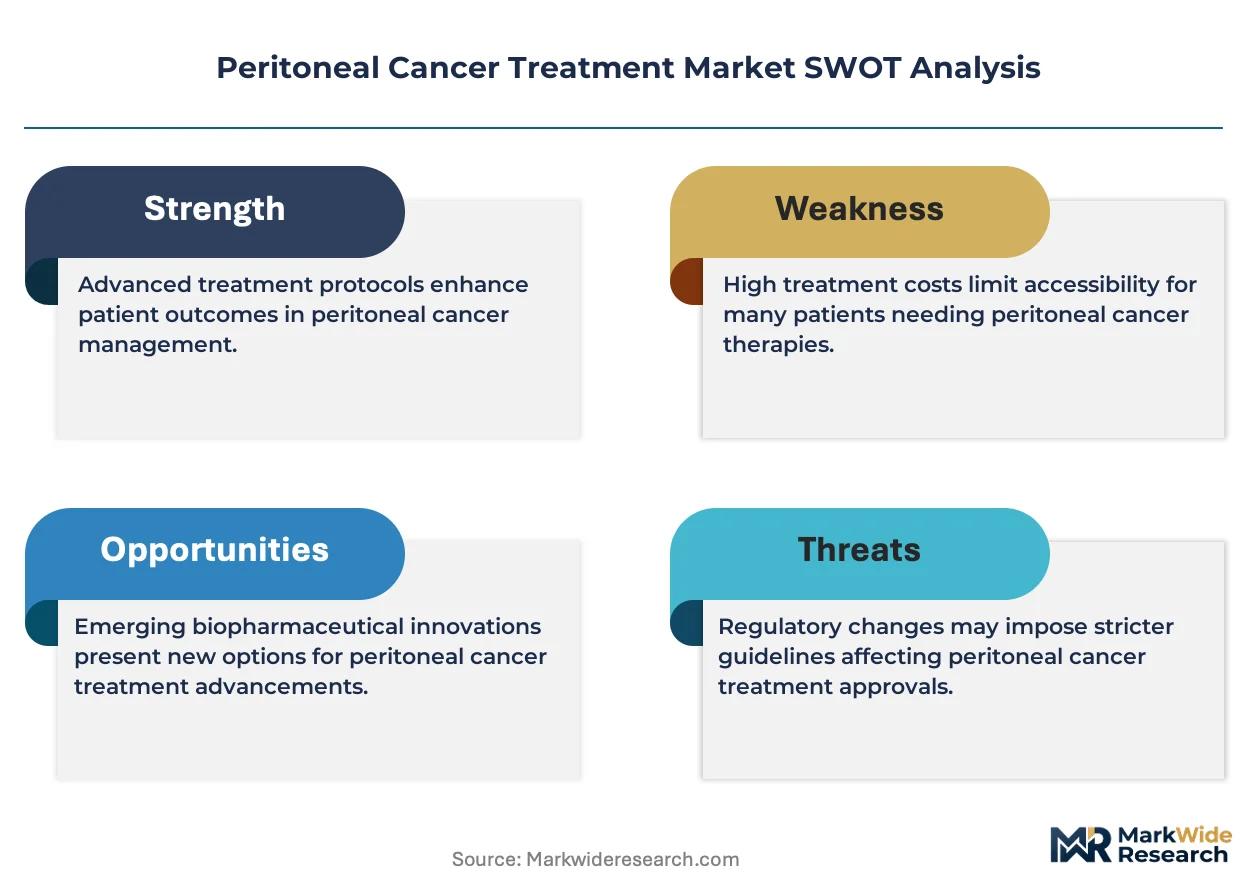
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for device-dependent modalities like HIPEC perfusion systems. AstraZeneca leverages its PARP inhibitor portfolio to sustain presence in ovarian peritoneal carcinomatosis. Roche Holding anchors European clinical development through its network of academic medical center partnerships. Merck & Co Inc competes on checkpoint inhibitor combinations for colorectal peritoneal metastases.
Peritoneal cancer treatment encompasses multimodal interventions targeting malignant dissemination across the peritoneal lining, combining surgical cytoreduction with locoregional chemotherapy delivery at temperatures of 41-43°C to enhance drug penetration and cytotoxicity. Intraperitoneal chemotherapy retains primacy in ovarian cancer protocols where margin pools concentrate, while hyperthermic intrraperitoneal chemotherapy represents the fastest-growing modality as specialized centers validate survival benefits in colorectal and gastric indications. Targeted therapy segments show maturation in HER2-directed approaches, with adjuvant delivery modes capturing expanding share as hospitals standardize perioperative protocols.
The FDA's Breakthrough Therapy designation and EMA's PRIME scheme together compress development timelines for peritoneal malignancy therapies, while the EU AI Act introduces compliance obligations for algorithmic diagnostic tools used in peritoneal disease staging. Japan's PMDA maintains distinct evidentiary requirements for HIPEC device approvals that fragment market access timelines across OECD markets. Stakeholders must monitor evolving reimbursement thresholds for complex cytoreductive procedures as health technology assessment bodies weigh cost-effectiveness against survival gains.
Market Dynamics
The FDA's Breakthrough Therapy designation compresses development timelines for peritoneal malignancy therapies, while tertiary hospitals consolidate cytoreductive surgery volumes into specialized centers that achieve procedural critical mass.
Growth Catalysts
- EMA PRIME Scheme:The European Medicines Agency's priority medicines framework accelerates regulatory assessment for orphan oncology indications, shortening time-to-market for novel intraperitoneal agents.
- HIPEC Protocol Standardization:Academic medical centers in Germany and Japan have published standardized perioperative chemotherapy regimens that reduce inter-facility outcome variance and build payer confidence.
- Ovarian Cancer Margin Pools:Concentrated disease presentation in the peritoneal cavity of advanced ovarian patients creates addressable patient cohorts for locoregional delivery systems.
Market Restraints
- Platinum-Based Drug Supply:Concentration of active pharmaceutical ingredient production for cisplatin and oxaliplatin in limited manufacturing geographies exposes treatment protocols to input volatility.
- HIPEC Device Certification Timelines:Japan's PMDA maintains distinct evidentiary requirements for hyperthermic perfusion systems that fragment market access timelines across OECD markets.
- Technical Limitation in Gastric Indications:Incomplete cytoreduction rates in diffuse-type gastric peritoneal carcinomatosis restrict addressable populations despite protocol advances in colorectal and ovarian settings.
Strategic Opportunities
- Underpenetrated United States Tertiary Centers:Community oncology programs in the US Southeast and Mountain West lack dedicated peritoneal surface malignancy units, representing expansion targets for established academic networks.
- EU AI Act Diagnostic Compliance:Algorithmic staging tools for peritoneal disease burden quantification face new conformity obligations that first-mover developers can leverage for competitive positioning.
- Checkpoint Inhibitor Convergence:Combination protocols merging hyperthermic intraperitoneal chemotherapy with PD-1/PD-L1 blockade are entering phase II evaluation for mismatch repair-deficient colorectal metastases.
Industry Challenges
- Surgical Oncologist Training Pipeline:Cytoreductive surgery with peritonectomy requires subspecialty fellowship programs that graduate fewer than fifty surgeons annually across the United States and Germany combined.
- CE Marking Transition Under MDR:Medical device regulation reclassification of HIPEC perfusion systems forces manufacturers through enhanced clinical evidence requirements that extend recertification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peritoneal Cancer Treatment Market |
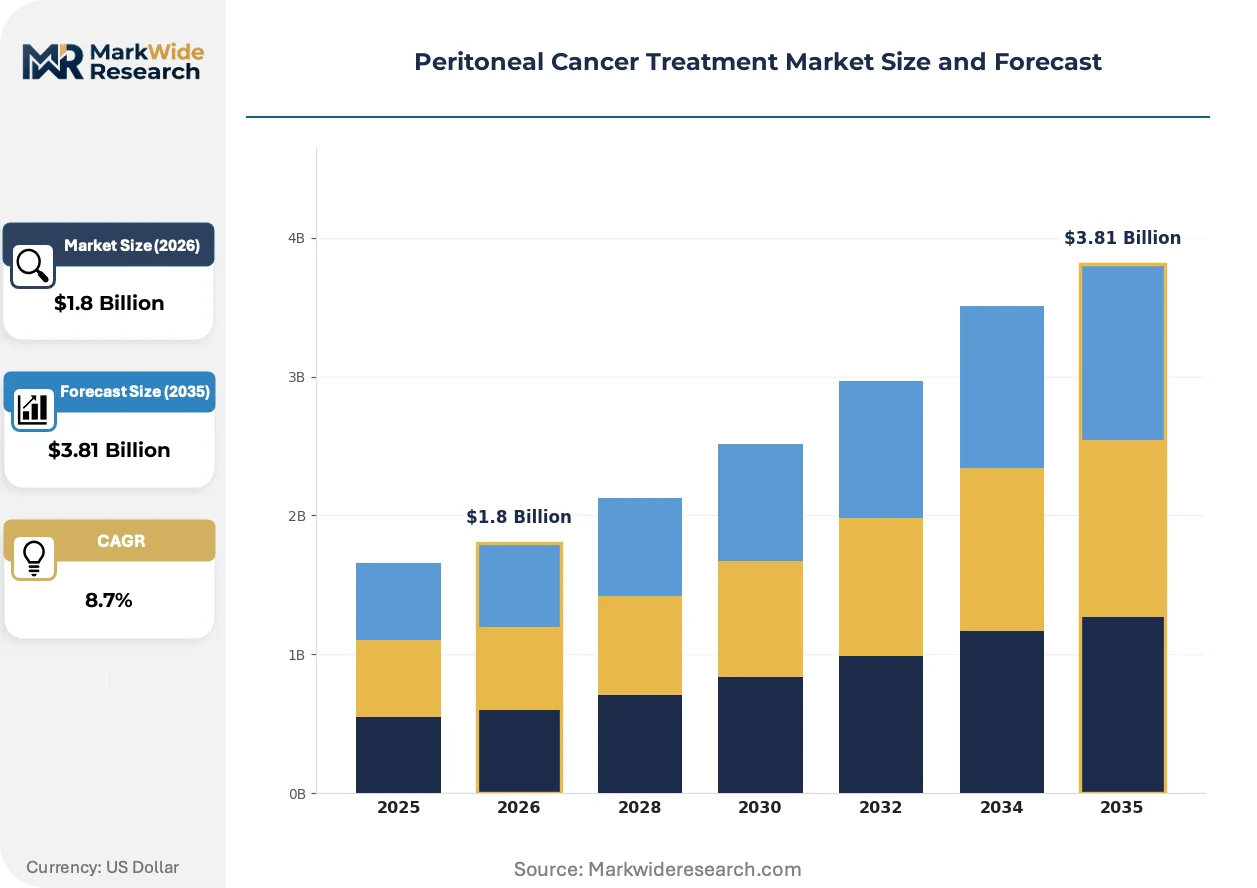
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraperitoneal Chemotherapy, Cytoreductive Surgery, Hyperthermic Intraperitoneal Chemotherapy, Targeted Therapy Delivery Mode: Intraperitoneal, Systemic, Neoadjuvant, Adjuvant End User: Hospitals, Cancer Treatment Centers, Outpatient Clinics, Research Institutions Therapy Area: Ovarian Cancer, Colorectal Cancer, Gastric Cancer, Mesothelioma |
| Companies Covered | AstraZeneca, GlaxoSmithKline, Merck & Co Inc, Novartis, Roche Holding, ImmunoGen, Zentalis Pharmaceuticals, Oncoinvent AS, Genelux Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peritoneal Cancer Treatment Market Evolving Landscape
Peritoneal cancer treatment is experiencing modality convergence as device engineering, pharmaceutical formulation, and surgical technique advance in parallel rather than sequentially.
Closed-circuit HIPEC perfusion systems are miniaturizing pump and heat exchanger assemblies to enable bedside installation in standard operating theaters rather than dedicated surgical suites. Community hospitals in the United States and Japan are piloting these compact units to extend cytoreductive surgery access beyond academic centers. Equipment footprint compression is lowering capital barriers and redistributing procedural volumes across hospital tiers.
The EU Medical Device Regulation's enhanced clinical evidence requirements for class III devices are forcing manufacturers to generate prospective registry data rather than rely on predicate equivalence. This regulatory friction disproportionately affects perfusion system suppliers with legacy CE marks grandfathered under prior directives. German notified bodies are processing submissions through extended review cycles that delay market re-entry.
Japanese tertiary centers are unbundling after-sales service contracts for HIPEC equipment, shifting from comprehensive maintenance agreements to per-procedure technical support fees. This procurement model change compresses vendor revenue recognition but aligns costs with actual utilization. The pattern is visible in Osaka and Tokyo academic hospitals where procedure volumes fluctuate seasonally.
Peritoneal Cancer Treatment Market Segmentation
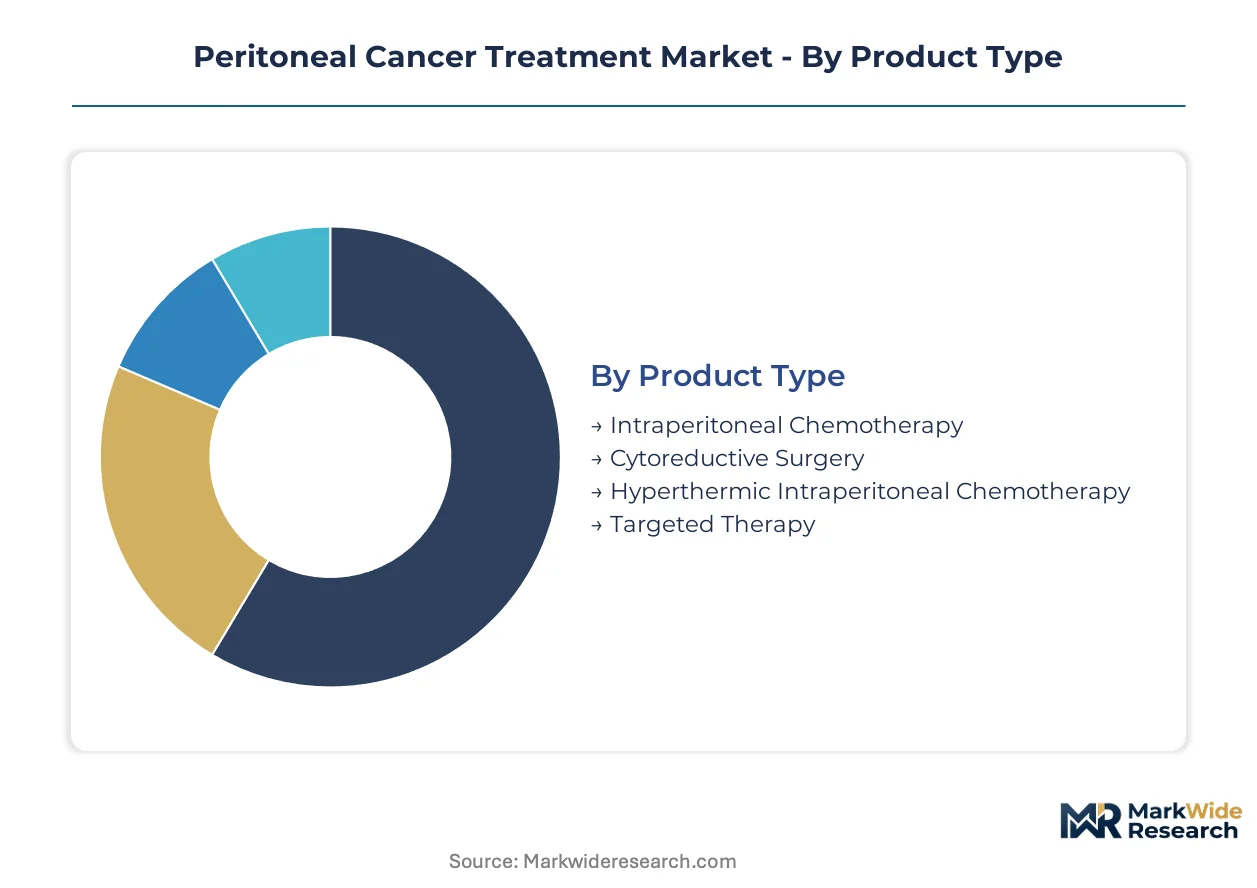
Peritoneal cancer treatment modalities fragment across intervention types, delivery timing, and care settings. Segmentation reveals where capital deployment concentrates and which patient cohorts drive protocol innovation.
Product Type:
Domestic procedural volumes in Germany and Japan anchor demand for device-intensive modalities, while export-oriented pharmaceutical supply chains sustain chemotherapy segments across OECD markets.
- Hyperthermic Intraperitoneal Chemotherapy:Closed-circuit perfusion systems heat chemotherapeutic agents to 41-43°C during cytoreductive surgery, enhancing cytotoxic penetration into peritoneal nodules. Tertiary centers in the United States and Germany achieve critical volume thresholds that validate survival outcomes and secure payer reimbursement.
- Targeted Therapy:HER2-directed agents and PARP inhibitors address molecular subtypes in ovarian peritoneal carcinomatosis. Academic medical centers in Japan and the United States concentrate clinical trial enrollment for biomarker-selected cohorts.
- Intraperitoneal Chemotherapy:Direct locoregional delivery of cisplatin or paclitaxel targets residual disease after surgical debulking in ovarian cancer protocols.
- Cytoreductive Surgery:Peritonectomy procedures require specialized surgical oncologists trained in visceral resection and peritoneal stripping techniques.
Cytoreductive surgery holds the largest share; momentum sits with hyperthermic intraperitoneal chemotherapy as center specialization accelerates.
Delivery Mode:
Cost tier differentiation separates capital-intensive intraoperative delivery from outpatient systemic administration, with neoadjuvant protocols commanding premium pricing for multidisciplinary coordination.
- Intraperitoneal:Direct catheter delivery into the peritoneal cavity achieves high locoregional drug concentrations with limited systemic exposure. Specialized centers in Germany standardize perioperative regimens that reduce inter-facility outcome variance.
- Adjuvant:Post-surgical intraperitoneal or systemic therapy targets microscopic residual disease following complete cytoreduction. Cancer treatment centers in Japan favor adjuvant HIPEC for gastric and colorectal indications where margin pools concentrate.
- Neoadjuvant:Preoperative systemic therapy reduces tumor burden to enable complete surgical resection in initially unresectable peritoneal carcinomatosis.
- Systemic:Intravenous chemotherapy remains standard for diffuse peritoneal disease unsuitable for locoregional approaches or as palliative management.
Intraperitoneal delivery holds the largest share; adjuvant timing is climbing the fastest as hospitals standardize perioperative protocols.
End User:
Customer type concentration in tertiary academic centers creates volume thresholds that community hospitals cannot replicate, fragmenting procedural access geographically.
- Hospitals:Tertiary academic medical centers anchor cytoreductive surgery volumes through dedicated peritoneal surface malignancy units. The United States and Germany host the highest concentration of specialized programs graduating fellowship-trained surgical oncologists.
- Cancer Treatment Centers:Dedicated oncology facilities integrate medical and surgical oncology for multimodal protocol delivery. Japanese cancer centers pilot compact HIPEC systems to extend procedural access beyond flagship academic hospitals.
- Outpatient Clinics:Community settings manage systemic chemotherapy and surveillance for stable peritoneal disease.
- Research Institutions:Academic centers conduct phase I/II trials for novel intraperitoneal agents and combination immunotherapy protocols.
Hospitals hold the largest share; cancer treatment centers are gaining share fastest through dedicated peritoneal malignancy program development.
Therapy Area:
Application maturity varies by indication, with ovarian cancer protocols most established and gastric peritoneal carcinomatosis facing technical limitations that restrict addressable populations.
- Ovarian Cancer:Peritoneal carcinomatosis represents the dominant disease presentation in advanced epithelial ovarian cancer. Intraperitoneal chemotherapy protocols developed at United States academic centers retain primacy where disease concentrates in the peritoneal cavity.
- Colorectal Cancer:Isolated peritoneal metastases in selected patients achieve survival equivalence with systemic therapy when complete cytoreduction combines with HIPEC. German surgical oncology networks publish standardized regimens that build payer confidence.
- Gastric Cancer:Diffuse-type peritoneal carcinomatosis exhibits incomplete cytoreduction rates that limit protocol adoption despite technical advances in other indications.
- Mesothelioma:Malignant peritoneal mesothelioma represents a rare indication where cytoreductive surgery with heated chemotherapy achieves durable survival in selected patients.
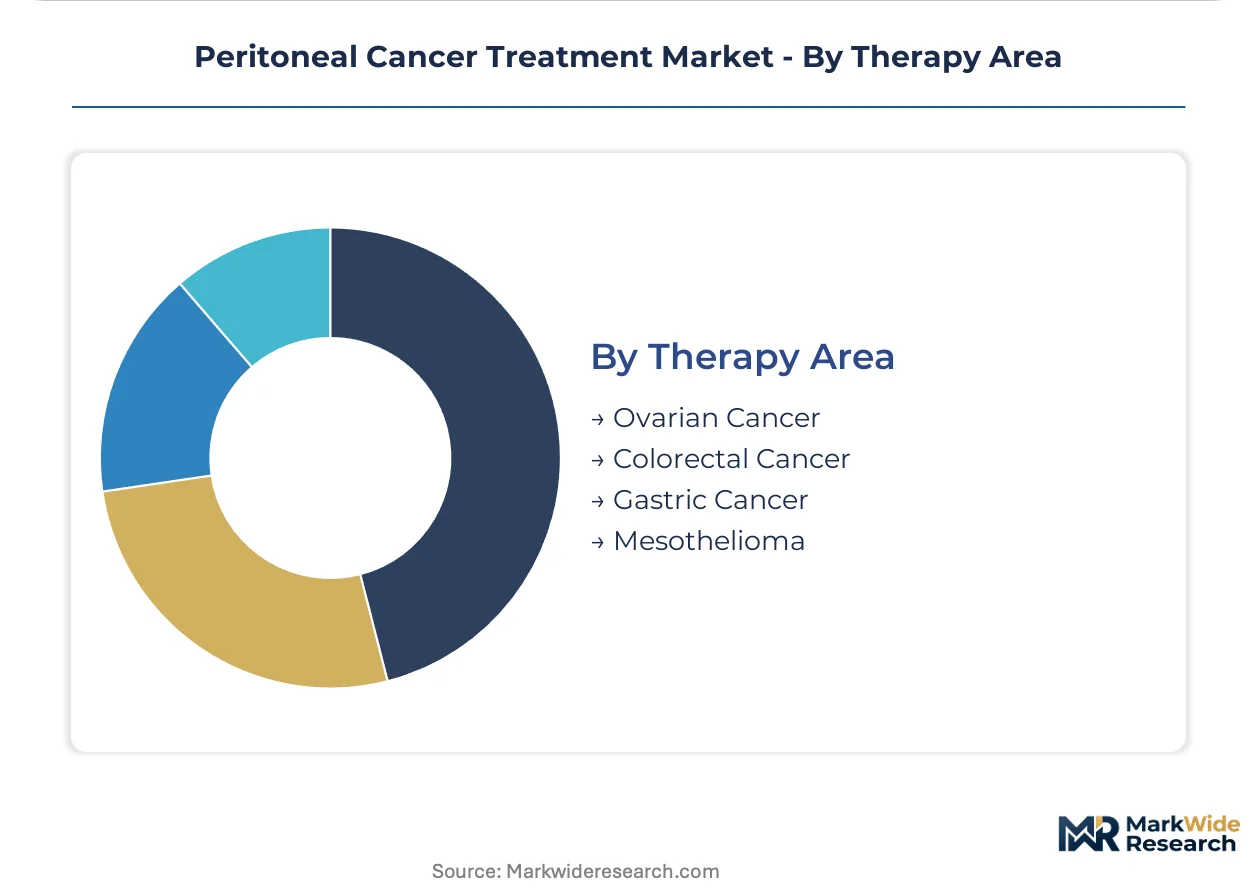
Ovarian cancer holds the largest share; colorectal cancer shows the steepest expansion trajectory as specialized centers validate survival benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Breakthrough Therapy designations and EMA PRIME scheme accelerations are concentrating clinical development in jurisdictions with expedited regulatory pathways. Specialized peritoneal surface malignancy centers in the United States, Germany, and Japan have achieved procedural volume thresholds that validate survival outcomes and secure reimbursement.
United States
Tertiary academic medical centers in Houston, New York, and Los Angeles anchor cytoreductive surgery volumes through dedicated peritoneal malignancy units. The FDA's accelerated approval pathways for orphan oncology indications compress development timelines for novel intraperitoneal agents. Community oncology programs in the Southeast and Mountain West lack dedicated peritoneal surface malignancy units, representing expansion targets for established academic networks.
Germany
Surgical oncology networks in Munich and Berlin publish standardized HIPEC perioperative regimens that reduce inter-facility outcome variance. EMA PRIME scheme prioritization accelerates regulatory assessment for orphan oncology indications entering European markets. Notified bodies under the EU Medical Device Regulation process HIPEC perfusion system submissions through extended review cycles that delay market re-entry.
Japan
Cancer centers in Osaka and Tokyo pilot compact HIPEC systems to extend procedural access beyond flagship academic hospitals. PMDA maintains distinct evidentiary requirements for hyperthermic perfusion systems that fragment market access timelines across OECD markets. After-sales service contracts for HIPEC equipment are unbundling toward per-procedure technical support fees that align costs with actual utilization.
United Kingdom
Academic medical center partnerships in London and Manchester concentrate clinical trial enrollment for biomarker-selected cohorts in ovarian peritoneal carcinomatosis. MHRA recognition of EMA centralized approvals streamlines market entry for novel intraperitoneal agents. Regional variation in NHS commissioning thresholds for complex cytoreductive procedures creates geographic access disparities.
Switzerland
Roche Holding anchors European clinical development through its network of academic medical center partnerships spanning Basel and Zurich. Swissmedic maintains alignment with EMA scientific opinions while preserving national flexibility for HIPEC device certification. Cantonal hospital systems concentrate cytoreductive surgery volumes in university-affiliated centers that achieve procedural critical mass.
Peritoneal Cancer Treatment Market Competitive Landscape
Listed leaders compete with private specialists across regulatory submission capacity and clinical trial infrastructure. The vendor base stratifies between multinational pharmaceutical conglomerates with PARP inhibitor and checkpoint inhibitor portfolios and emerging biotechs developing novel intraperitoneal delivery platforms. Three archetypes dominate: Big Pharma oncology divisions, mid-cap targeted therapy specialists, and device-dependent perfusion system manufacturers. Consolidation pressures favor M&A activity around clinical-stage intraperitoneal assets and strategic partnerships between pharmaceutical developers and academic medical centers.
Within the Big Pharma tier, AstraZeneca and Roche Holding represent established oncology incumbents with differentiated molecular targeting capabilities. Merck & Co Inc occupies a position in immuno-oncology combination protocols. Among emerging biotechs, ImmunoGen and Zentalis Pharmaceuticals exemplify the targeted therapy specialist archetype focused on novel mechanisms for peritoneal malignancies.
| Leading Market Players |
|---|
| AstraZeneca |
| GlaxoSmithKline |
| Merck & Co Inc |
| Novartis |
| Roche Holding |
| ImmunoGen |
| Zentalis Pharmaceuticals |
| Oncoinvent AS |
| Genelux Corporation |
| Others |
Value Network & Pricing Analysis
EU Medical Device Regulation recertification timelines for HIPEC perfusion systems simultaneously gate supply qualification and stratify price tiers, compressing margins for legacy manufacturers while rewarding first-movers with prospective registry data. Device-dependent modalities face dual pressure from extended notified body review cycles and divergent national evidentiary requirements that fragment pricing power across OECD markets.
Pricing Analysis
Certification level (CE-MDR Class III versus legacy CE marks) creates the primary spread between premium and standard tier HIPEC systems, with FDA 510(k) clearance commanding additional brand premium in United States academic centers. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales bundling intensity and geographic service coverage, though Japanese tertiary centers are unbundling maintenance contracts toward per-procedure fees that compress vendor revenue recognition. Cost compression in standard tier equipment is intensifying because compact bedside systems lower capital barriers for community hospital entry. Community oncology programs in the US Southeast exhibit highest price sensitivity, while German academic networks prioritize outcome-validated protocols over acquisition cost.
Supply Chain Analysis
Active pharmaceutical ingredient production for platinum-based agents concentrates in India and China, with limited secondary sourcing exposing cytoreductive surgery protocols to input volatility. German and Japanese device engineering for perfusion pump assemblies rests on specialized heat exchanger components and medical-grade silicone tubing that draw from concentrated polymer suppliers. Single-source vulnerability in cisplatin API manufacturing creates systemic risk for HIPEC protocol standardization across European centers. Distribution runs through hospital procurement consortia and GPO contracts in the United States, while German hospital systems favor direct manufacturer relationships with extended service level agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peritoneal cancer treatment market rewards organizations that control scarce surgical oncologist training pipelines and specialized center accreditation, with fewer than fifty fellowship-trained surgeons graduating annually across the United States and Germany combined.
For Market Incumbents: Consolidate procedural volume through academic medical center partnership networks that lock in referral patterns and secure payer reimbursement thresholds. Acquire clinical-stage intraperitoneal delivery platform developers to deepen therapeutic modality coverage before checkpoint inhibitor combination protocols mature. Backward integration into perfusion system manufacturing insulates against CE-MDR recertification delays that threaten device supply continuity. For New Entrants and Emerging Players: Lead with compact HIPEC system deployments targeting community oncology programs in the US Mountain West and Southeast where dedicated peritoneal surface malignancy units remain underdeveloped. Capture share through per-procedure technical support pricing that aligns with Japanese procurement model shifts and lowers customer capital commitment. Prioritize algorithmic staging tool development that satisfies EU AI Act diagnostic compliance obligations ahead of larger imaging incumbents. For Investors and Strategic Acquirers: FDA Breakthrough Therapy designation density reshapes the acquisition landscape toward clinical-stage assets with expedited regulatory pathways and biomarker-selected patient cohorts. Target developers with phase II intraperitoneal immunotherapy combinations and established academic center principal investigator relationships. Watch EMA PRIME scheme award velocity as the signal indicating which orphan oncology platforms will compress time-to-market and command premium valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Recertification Pathway | Prospective registry generation unlocks European market re-entry for legacy perfusion system manufacturers. |
| Academic Medical Center Partnership | Volume concentration in Houston and Munich validates survival outcomes and secures payer reimbursement. |
| Compact HIPEC System Launch | Bedside installation capability extends cytoreductive surgery access beyond dedicated surgical suites. |
| Checkpoint Inhibitor Combination Protocol | PD-1/PD-L1 blockade integration with HIPEC addresses mismatch repair-deficient colorectal metastases. |
| Surgical Oncologist Fellowship Expansion | Training pipeline growth alleviates procedural capacity constraints limiting addressable patient populations. |
Research Methodology
A spread of perspectives from surgical oncologists, hospital procurement managers, regulatory affairs leads at device manufacturers, and payer access specialists converged on the working assumptions underlying modality adoption trajectories. Primary interviews with clinicians at tertiary centers in the United States, Germany, and Japan combined with secondary validation against FDA 510(k) filings, EMA PRIME scheme designations, PMDA approval databases, and hospital procurement records. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimates across the analysis window.
Segmentation dimensions modeled include treatment modality, delivery timing, end-user facility type, and therapy area indication throughout the forecast period. CAGRs were derived from procedure volume growth at specialized centers, pharmaceutical pricing trajectories, and device replacement cycles. Forecast inputs incorporated HIPEC protocol standardization rates, surgical oncologist training pipeline output, and reimbursement threshold evolution at health technology assessment bodies.
The analysis sits within stated boundaries; outcomes outside sustained payer acceptance of complex cytoreductive procedures or uninterrupted platinum-based drug supply would require recalibration. Forecasts reflect assumptions regarding regulatory pathway continuity and center specialization economics. Practitioners should keep alternative scenarios live as EMA notified body processing capacity and API manufacturing geographic concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Vulvar Cancer Market
Oncology
Lung Cancer Treatment Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
America Cancer Immunotherapy Market
Oncology
Thymus Cancer Market
Oncology
Testicular Cancer Treatment Market
Oncology
Particle Therapy Systems Market
Oncology
Immuno-Oncology Clinical Trials Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
Gynecological Cancer Drugs Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Throat Cancer Market
Oncology
Paranasal Sinus Cancer Market
Oncology
North America Tumor Ablation Market
Oncology
Pancreatic Cancer Treatment Market