
 BCD Power IC Market | 2026-2036
BCD Power IC Market Size, Share, and Industry Trends Forecast 2026-2036
BCD Power IC Market Analysis
Automotive electrification is decoupling from traditional consumer electronics as the primary demand engine for BCD power ICs. Texas Instruments leverages its broad analog portfolio to anchor North American supply relationships with tier-one automotive OEMs. STMicroelectronics specializes in silicon-on-insulator BCD variants for high-voltage traction inverter applications. Infineon Technologies dominates European automotive qualification channels with its extended temperature-grade product families.
BCD power ICs integrate bipolar, CMOS, and DMOS structures on a single die to deliver efficient power management with mixed-signal processing capability, typically operating at voltage ranges from sub-5V to 700V depending on process node and isolation technology. Bipolar-CMOS technology leads in industrial motor drive applications where high-current handling meets precision analog control, while SOI variants capture the fastest growth in automotive gate drivers requiring galvanic isolation. Voltage regulators and power management components concentrate the deepest margin pools as system architects prioritize energy efficiency certification compliance over discrete driver cost minimization.
FDA medical device regulations and EU automotive functional safety standards under ISO 26262 constrain design cycles and qualification timelines for BCD power IC suppliers targeting life-critical and safety-critical applications. NHTSA vehicle electrification mandates and EPA industrial efficiency benchmarks directly shape power density and thermal performance specifications that define market access thresholds. Stakeholders must monitor how China's GB standards for new energy vehicles and dual carbon goals evolve local content requirements that could redirect supply chain configuration decisions.
Market Dynamics
Automotive electrification is compressing design cycles and forcing foundries to retool for high-voltage BCD processes that traditional consumer applications never required. Tier-one suppliers now demand ISO 26262 functional safety certification as a baseline qualification, not a premium tier.
Growth Catalysts
- EU Green Deal carbon neutrality mandates:Tightening automotive emissions standards in Europe are mandating higher semiconductor efficiency in EV powertrain systems, accelerating BCD power IC qualification timelines.
- China domestic fab capacity expansion:Localized 300mm BCD process lines in Shanghai and Hefei are reducing import dependency for integrated power management solutions serving new energy vehicle manufacturers.
- Silicon-on-insulator gate driver integration:SOI-based BCD variants now deliver galvanic isolation for 800V traction inverters, opening design wins previously captured by discrete optocoupler solutions.
Market Restraints
- 300mm silicon wafer input volatility:Foundry spot pricing for automotive-grade silicon substrates fluctuates with polysilicon purification capacity concentrated in Xinjiang and Inner Mongolia.
- Extreme ultraviolet lithography equipment concentration:ASML's monopoly on EUV scanners for advanced BCD nodes creates single-source dependency for sub-40nm power management die shrinks.
- ISO 26262 functional safety certification friction:The ASIL-D qualification process extends product development timelines by 18-24 months, freezing out mid-tier suppliers without captive automotive validation labs.
Strategic Opportunities
- India PLI scheme for semiconductor manufacturing:Production-linked incentives for domestic fab construction in Gujarat and Karnataka create greenfield entry points for BCD process licensing.
- GaN-SiC-BCD heterogeneous integration:Combining wide-bandgap power switches with intelligent BCD gate drivers on multichip modules enables next-generation onboard chargers.
- Direct OEM contracting bypassing tier-one distributors:BYD and NIO are building captive semiconductor procurement teams, creating channel disintermediation for qualified BCD suppliers.
Industry Challenges
- Mixed-signal analog design talent scarcity:The specialized skill set combining power device physics with precision CMOS analog is concentrated among engineers with 15+ years of BCD-specific experience.
- Legacy 12V automotive electrical architecture integration:New 48V mild-hybrid systems require BCD power ICs that bridge voltage domains without disrupting existing body electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BCD Power IC Market |
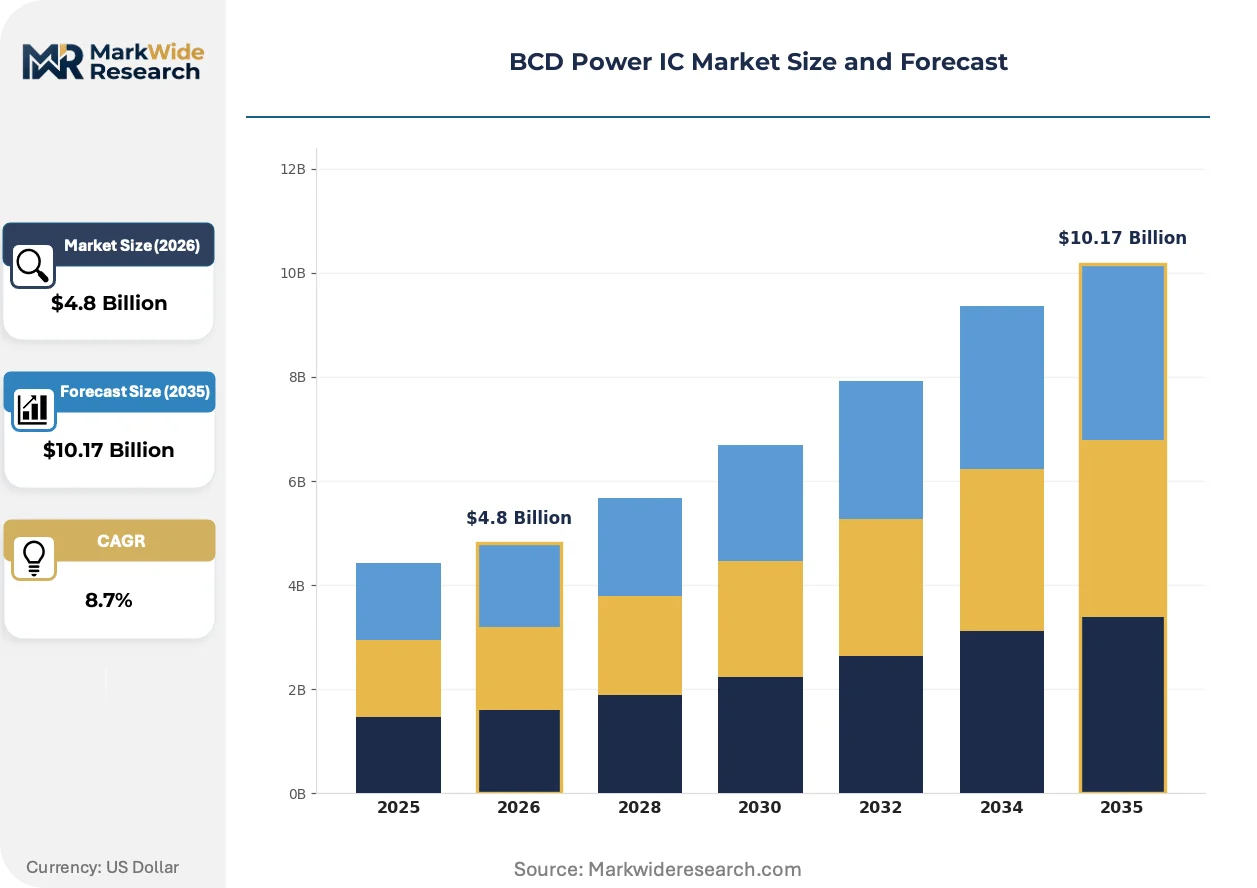
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bipolar-CMOS, CMOS, BiCMOS, SOI Component: Voltage Regulators, Power Management, Integrated Circuits, Drivers Application: Consumer Electronics, Automotive, Industrial Automation, Telecommunications End User: OEMs, Distributors, System Integrators, Aftermarket Providers |
| Companies Covered | NXP Semiconductors, Analog Devices, STMicroelectronics, Rohm Semiconductor, Renesas Electronics, Texas Instruments, ON Semiconductor (onsemi), MagnaChip Semiconductor, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BCD Power IC Market Emerging Trajectories
Process architecture convergence is collapsing the traditional separation between power management and signal conditioning functions. Foundries now compete on integrated isolation density rather than raw voltage tolerance.
Silicon-on-insulator BCD with deep trench isolation is rewriting competitive positioning in 800V EV platforms. European tier-one inverters from Bosch and Vitesco are adopting SOI gate drivers for traction modules. This technology is compressing the addressable market for discrete isolation components while expanding BCD content per vehicle.
The EU F-Gas Regulation phasing down fluorinated greenhouse gases is constraining thermal management refrigerant choices for power module cooling. Automotive thermal engineers must redesign cold plate architectures to accommodate lower-GWP alternatives. This regulatory pressure is accelerating demand for BCD-based temperature sensing and fan control ICs with higher precision.
Chinese EV OEMs are consolidating semiconductor procurement around vertically integrated power module suppliers. NIO, XPeng, and Li Auto now specify BCD gate drivers directly rather than delegating to tier-one inverter manufacturers. This buyer concentration is visible most acutely in Suzhou and Hefei, where local BCD foundries have established dedicated automotive program offices.
BCD Power IC Market Segmentation
BCD Power IC architectures fragment across four technical dimensions that determine procurement patterns and margin capture. Buyers prioritize voltage tolerance, isolation density, and qualification grade depending on end-use criticality and regulatory exposure.
Technology:
Process selection hinges on voltage domain requirements and galvanic isolation needs rather than cost optimization alone.
- SOI:Silicon-on-insulator variants embed deep trench isolation for 800V traction inverters, capturing design wins in European EV platforms where Bosch and Vitesco specify galvanic isolation. The EU Green Deal emissions mandates accelerate SOI qualification timelines for automotive gate drivers.
- Bipolar-CMOS:Dominates industrial motor drives where high-current handling meets precision analog control, with demand concentrating in German factory automation clusters. ISO 26262 functional safety certification requirements constrain mid-tier supplier entry.
- CMOS:Standard CMOS-BCD hybrids serve sub-40V consumer power management where die shrinks prioritize EUV lithography access.
- BiCMOS:Bipolar-CMOS-DMOS triple-well structures address mixed-signal precision in medical devices under FDA 510(k) pathways.
Volume sits with Bipolar-CMOS in industrial automation; growth tilts toward SOI in 800V automotive electrification.
Component:
Margin pools concentrate where system architects prioritize energy efficiency certification compliance over discrete component cost minimization.
- Voltage Regulators:Linear and switching regulators with integrated protection logic anchor power management subsystems in automotive body electronics. NHTSA electrification mandates drive precision requirements for 48V mild-hybrid voltage domain bridging.
- Power Management:Multi-rail PMICs with dynamic voltage scaling capture the steepest expansion trajectory in smartphone and notebook platforms where battery life certification shapes consumer purchasing.
- Integrated Circuits:Monolithic BCD die combining power stages with mixed-signal processing serve space-constrained wearable devices.
- Drivers:Gate driver ICs for MOSFET and IGBT switching populate motor control modules in Chinese EV manufacturing clusters around Hefei and Suzhou.
Revenue concentrates in Power Management across consumer platforms; qualification-grade Voltage Regulators expand fastest in automotive safety-critical systems.
Application:
End-use diversification is compressing as automotive electrification displaces consumer electronics as the primary demand engine.
- Automotive:Traction inverters, onboard chargers, and DC-DC converters in EV powertrains specify BCD gate drivers with ASIL-D functional safety grades. China's GB standards for new energy vehicles reshape local content requirements for integrated power management.
- Industrial Automation:Servo motor drives and programmable logic controllers in German and Japanese manufacturing bases demand extended temperature-grade BCD variants.
- Consumer Electronics:Smartphone PMICs and notebook power subsystems face margin pressure from commoditization in Asian contract manufacturing.
- Telecommunications:Base station power amplifiers and optical module drivers require RF-tolerant BCD processes with specialized substrate engineering.
Shipment volume remains with Consumer Electronics; value expansion concentrates in Automotive as 800V architectures proliferate.
End User:
Channel structure is fragmenting as Chinese EV OEMs build captive semiconductor procurement teams and bypass traditional tier-one distribution.
- OEMs:BYD, NIO, and XPeng now specify BCD gate drivers directly rather than delegating to inverter manufacturers, compressing distributor margins in Suzhou and Hefei procurement clusters.
- Distributors:Arrow and Avnet retain relevance in North American industrial automation where fragmented demand requires technical application support.
- System Integrators:Tier-one automotive suppliers like Bosch and Vitesco consolidate BCD sourcing for European EV platforms under EU Green Deal compliance timelines.
- Aftermarket Providers:Replacement power modules for legacy 12V automotive electrical architectures serve secondary markets with reduced qualification burdens.
Transaction volume flows through Distributors in industrial segments; direct OEM contracting gains share fastest in Chinese EV manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the majority of BCD Power IC output for EV manufacturing, while production capacity concentrates in East Asian foundry clusters and European IDM facilities. This geographic split creates supply chain tension as automotive OEMs demand localized sourcing.
China
Hefei and Suzhou host dedicated automotive program offices serving NIO, BYD, and XPeng with direct OEM contracting bypassing tier-one distributors. MIIT's GB standards for new energy vehicles mandate local content requirements that redirect supply chain configuration decisions. Shanghai and Hefei foundries operate localized 300mm BCD process lines reducing import dependency.
Germany
Bosch and Vitesco specify SOI-based gate drivers for 800V traction inverters under EU Green Deal carbon neutrality timelines. The KBA enforces automotive qualification standards that compress supplier entry windows. Bavarian and Baden-Württemberg industrial clusters anchor European demand for extended temperature-grade BCD variants in factory automation.
United States
NHTSA vehicle electrification mandates shape power density specifications for 48V mild-hybrid systems bridging legacy 12V architectures. EPA industrial efficiency benchmarks define market access thresholds for power management ICs. Texas and Arizona fabrication facilities supply North American tier-one automotive OEMs through technical application support networks.
Japan
METI policies coordinate domestic semiconductor manufacturing reinforcement targeting automotive and industrial automation segments. Tokyo and Osaka metropolitan areas concentrate precision analog design talent with 15+ years BCD-specific experience. Japanese factory automation bases demand bipolar-CMOS variants for servo motor drives.
South Korea
Seoul Capital Area system houses integrate BCD PMICs for smartphone and notebook platforms where battery life certification shapes consumer purchasing. MFDS medical device regulations constrain design cycles for suppliers targeting life-critical applications. Busan-Ulsan manufacturing corridors supply multichip modules combining wide-bandgap power switches with intelligent gate drivers.
BCD Power IC Market Vendor Landscape
Top-tier vendors anchor automotive qualification channels, while mid-tier specialists occupy industrial automation niches. The vendor base stratifies across three tiers: IDMs with captive fabrication, fabless designers licensing process technology, and foundry operators offering BCD as a specialty service. Two strategic archetypes dominate: silicon-on-insolation specialists capturing 800V EV design wins, and bipolar-CMOS incumbents defending industrial motor drive positions. Competitive moves concentrate on ASIL-D functional safety certification acquisition and 300mm capacity expansion in automotive-grade process nodes.
Among European IDMs, STMicroelectronics and Infineon Technologies exemplify the SOI-BCD archetype for high-voltage traction applications. Texas Instruments occupies a position representing North American analog portfolio breadth in tier-one automotive supply relationships. NXP Semiconductors anchors the mixed-signal precision tier serving medical device pathways under FDA 510(k) frameworks.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Analog Devices |
| STMicroelectronics |
| Rohm Semiconductor |
| Renesas Electronics |
| Texas Instruments |
| ON Semiconductor (onsemi) |
| MagnaChip Semiconductor |
| Infineon Technologies |
| Others |
Supply Flow & Price Mechanics
IDM consolidation through private-equity roll-ups in European automotive semiconductor supply chains is tightening wafer allocation discipline while compressing distributor margins in high-volume automotive programs. This ownership restructuring simultaneously concentrates supply-side bargaining power and enforces stricter price corridors across qualification-grade product tiers.
Pricing Analysis
Cost-down pressure on standard-grade Bipolar-CMOS variants accelerates because Chinese EV OEMs are consolidating procurement around vertically integrated power module suppliers. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade levels separates ASIL-D certified gate drivers from extended-temperature industrial variants and commoditized smartphone PMICs. Pricing pressure stems from foundry spot pricing volatility for automotive-grade silicon substrates concentrated in Xinjiang and Inner Mongolia. Consumer electronics buyers exhibit highest price sensitivity; automotive OEMs prioritize qualification reliability over unit cost minimization.
Supply Chain Analysis
Refurbishment flows for legacy 12V automotive power modules are creating secondary market channels that compete with new-production BCD die in aftermarket segments. Supply concentrates in Taiwan, South Korea, and Germany for advanced BCD process nodes, while China expands localized 300mm capacity in Shanghai and Hefei. Raw material dependencies include polysilicon purification capacity, EUV lithography equipment from ASML, and specialized SOI substrates. Single-source vulnerability around EUV scanner access creates qualification bottlenecks for sub-40nm power management shrinks. Distribution runs through Arrow and Avnet in North American industrial automation where technical application support retains value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as tier-one automotive suppliers and OEMs pursue in-house BCD design capability to secure supply continuity and capture gate driver specification control.
For Market Incumbents: Deploy ASIL-D certification acquisition as a defensive moat against fabless entrants lacking captive automotive validation labs. Expand 300mm automotive-grade capacity in Texas and Arizona to anchor North American tier-one relationships. Consolidate bipolar-CMOS industrial positions through backward integration into specialized substrate sourcing. The threat of Chinese foundry cost competition in standard-grade consumer PMICs demands margin defense through qualification-grade product mix shift. For New Entrants and Emerging Players: Capture white-space in India PLI scheme greenfield fab construction in Gujarat and Karnataka through BCD process licensing partnerships. Target automotive gate driver segments where ISO 26262 certification friction freezes out mid-tier competitors without 15+ year analog design talent benches. Penetrate through direct OEM contracting models bypassing tier-one distributor channels that dominate in Suzhou and Hefei procurement clusters. For Investors and Strategic Acquirers: Distressed-cycle entries favor SOI-BCD specialists with existing 800V automotive design wins in European EV platforms. Long-term viability over the next decade hinges on heterogeneous integration capability combining wide-bandgap power switches with intelligent gate drivers. Monitor ASML EUV equipment allocation announcements as inflection indicators for sub-40nm power management node access.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Functional Safety Certification | STMicroelectronics and Infineon Technologies leverage this to lock out mid-tier suppliers from 800V traction inverter design wins. |
| 300mm Automotive-Grade Capacity Expansion | Localized process lines in Shanghai and Hefei reduce Chinese EV OEM import dependency for integrated power management. |
| GaN-SiC-BCD Heterogeneous Integration | Multichip modules combining wide-bandgap switches with intelligent gate drivers enable next-generation onboard chargers. |
| Direct OEM Contracting Bypass | BYD and NIO procurement teams compress distributor margins while accelerating qualification timelines. |
| SOI Deep Trench Isolation Investment | Bosch and Vitesco specifications for galvanic isolation in European EV platforms rewrite competitive positioning. |
Methodological Framework
Independent corroboration across primary interviews with tier-one automotive procurement officers, foundry process engineers, and power module design leads, combined with secondary validation through SEC semiconductor filings, MIIT GB standard publications, and IHS Markit vehicle production databases, underwrites the qualitative findings. Bottom-up triangulation against top-down market sizing reconciles foundry capacity announcements with OEM bill-of-materials estimates. Primary fieldwork concentrated on Hefei, Suzhou, and Stuttgart automotive semiconductor clusters.
Comparable-period anchoring to historical BCD process node transitions and automotive electrification adoption curves shaped the projection horizon. The analytical framework segments by technology architecture, component type, application criticality, and end-user channel structure across the modeling period. CAGRs derive from wafer demand forecasts, content-per-vehicle trajectories in 48V and 800V architectures, and foundry utilization rates. Industry-specific inputs include EU Green Deal compliance timelines and China dual carbon policy implementation pace.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EUV equipment allocation constraints, polysilicon supply geopolitics, and ISO 26262 certification timeline extensions. Forecasts reflect documented assumptions around automotive electrification penetration and foundry capacity expansion schedules. Practitioners should monitor NHTSA vehicle electrification mandate revisions and MIIT GB standard updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Vehicle Inverter Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
Battery Balancer Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Europe Variable Frequency Drive Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
HVDC Converters Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
Solid State Transformer Market
Power Systems
Space DC-DC Converters Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Global Power Discrete and Modules Market