
 Electric Vehicle Inverter Market | 2026-2036
Electric Vehicle Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Inverter Market Insights
East Asian foundry capacity for silicon carbide substrates is hardening as the primary supply bottleneck for high-performance traction inverters. Robert Bosch GmbH leverages in-house wafer sourcing to secure wafer allocations ahead of merchant competitors. Mitsubishi Electric Corporation anchors its position through dedicated joint ventures with Japanese SiC crystal growers. Continental AG competes via vertical integration into power module packaging lines in Germany.
An electric vehicle inverter converts direct current from the battery pack into alternating current for the traction motor, operating at switching frequencies between 10 kHz and 20 kHz in silicon-based designs and up to 100 kHz in gallium nitride architectures. Its primary purpose is to modulate voltage and frequency to control motor torque and regenerative braking efficiency. Bidirectional inverter configurations now dominate design pipelines because vehicle-to-grid capability unlocks auxiliary revenue streams for fleet operators. Silicon carbide technology leads in premium passenger vehicle platforms where thermal efficiency and power density justify material cost premiums against conventional silicon insulated-gate bipolar transistor modules.
EPA tailpipe standards and the EU F-Gas Regulation shape inverter refrigerant integration requirements for thermal management systems, while China's GB standards mandate efficiency thresholds for domestically produced new energy vehicles. NHTSA safety protocols in the United States govern electromagnetic compatibility and fault isolation in high-voltage power electronics. Stakeholders must monitor SiC substrate yield improvements and foundry expansion timelines to calibrate procurement commitments against technology transition risks.
Market Dynamics
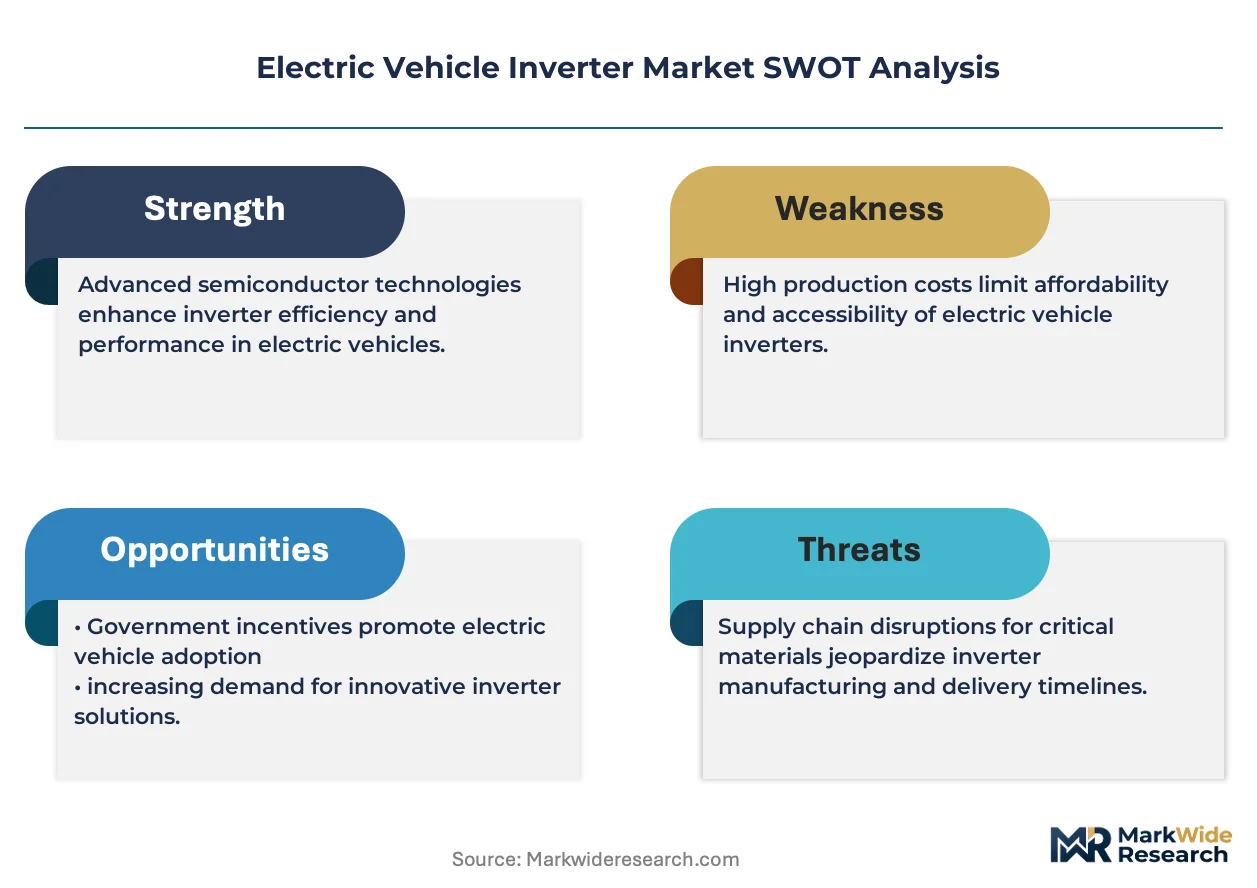
The transition from silicon IGBTs to silicon carbide MOSFETs is compressing inverter footprints while multiplying switching frequencies, forcing foundries to reallocate capital toward wide-bandgap substrate capacity before demand outstrips supply.
Growth Catalysts
- EPA tailpipe rules:United States passenger vehicle OEMs face tightening emissions thresholds that elevate SiC inverter efficiency from optional to mandatory for compliance.
- Onboard integration:Chinese new energy vehicle platforms are consolidating inverter, OBC, and DC-DC functions into single powertrain units to reduce mass and assembly steps.
- Vehicle-to-grid capability:Bidirectional power flow specifications unlock auxiliary revenue streams for fleet operators managing grid-stabilization contracts.
Market Restraints
- Substrate supply concentration:East Asian foundries control the bulk of 6-inch SiC wafer output, creating allocation bottlenecks for European and North American module assemblers.
- Material cost structure:SiC substrate prices remain elevated against silicon equivalents, compressing gross margins on economy-segment vehicle platforms where cost sensitivity dominates.
- Technical yield limitations:Defect densities in SiC crystal growth constrain usable die area, reducing effective wafer throughput below theoretical capacity.
Strategic Opportunities
- Commercial vehicle electrification:Heavy-duty truck and bus segments in India and Brazil present underpenetrated demand for high-current inverter architectures.
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating integration of inverter thermal management with low-GWP cooling systems.
- Gallium nitride convergence:GaN power devices are penetrating 400V architectures where SiC remains over-specified, opening mid-market tier differentiation.
Industry Challenges
- Power electronics talent scarcity:Shortages of engineers proficient in wide-bandgap device characterization and gate-drive design are extending development timelines.
- Functional safety certification:ISO 26262 ASIL-D compliance for traction inverters demands exhaustive fault-mode analysis, stretching validation cycles.
- Supply chain reconfiguration:Geopolitical trade measures are forcing module manufacturers to dual-source substrates across non-aligned jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Inverter Market |
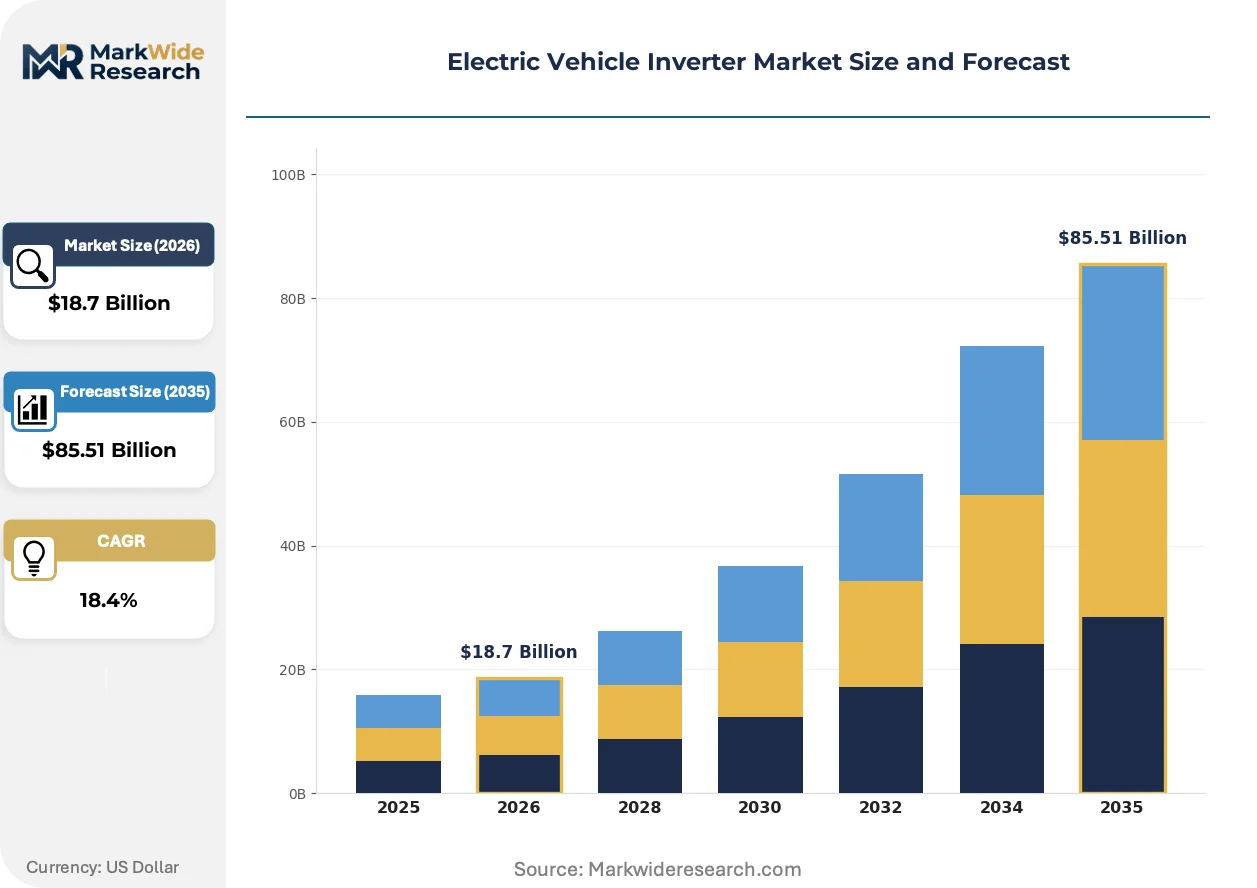
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bidirectional Inverter, Multi-Level Inverter, Modular Inverter, Matrix Inverter Technology: Silicon, SiC, GaN, Hybrid End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, E-Bikes Installation: Onboard, Offboard, Integrated, Standalone |
| Companies Covered | Continental AG, Robert Bosch GmbH, DENSO Corporation, Vitesco Technologies, Toyota Industries Corporation, Mitsubishi Electric Corporation, Hitachi Astemo Ltd, Valeo Group, BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Inverter Market Trends and Innovations
Power semiconductor packaging is evolving from discrete module assemblies toward integrated cooling and current-sensing subsystems, compressing development cycles while raising thermal management complexity.
Silicon carbide power modules are modularizing around standardized half-bridge footprints that accommodate multiple vehicle voltage classes without redesign. Tier 1 suppliers are adopting these platforms to amortize validation costs across OEM programs. The approach is compressing time-to-market for new vehicle launches while reducing unique part proliferation.
The EU F-Gas Regulation is mandating refrigerant transitions that force inverter thermal system redesigns to accommodate lower-GWP coolants with altered thermodynamic properties. Module manufacturers are responding with compatible cold-plate geometries and sealing materials. Premium passenger vehicle platforms are absorbing these changes first, with volume segments following as cost curves flatten.
Fleet procurement is consolidating inverter specifications around service-interval predictability and remanufacturing potential rather than upfront unit cost. Logistics operators are negotiating lifecycle cost frameworks that penalize premature failure. This shift is most visible in European and North American commercial vehicle segments where total cost of ownership dominates capital allocation decisions.
Electric Vehicle Inverter Market Segmentation
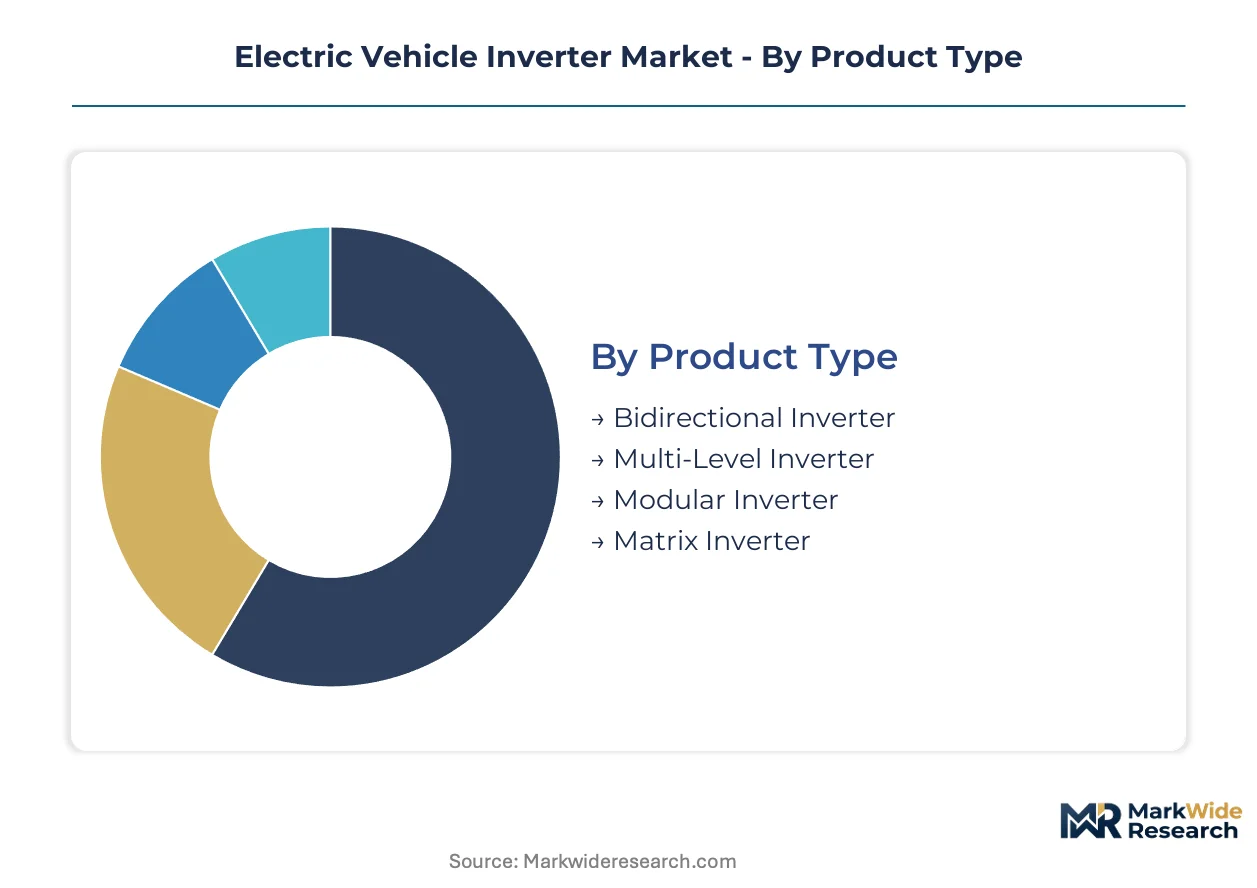
Segmentation in the electric vehicle inverter market reveals how procurement priorities diverge across voltage classes, thermal envelopes, and integration architectures. Understanding these fault lines enables suppliers to align wafer sourcing and packaging investments with the specific performance tiers where OEMs concentrate spending.
Product Type:
Upgrade cycles in traction inverter architectures are compressing as OEMs transition from discrete silicon IGBTs toward integrated wide-bandgap platforms, with replacement decisions increasingly tied to vehicle-to-grid compatibility requirements.
- Bidirectional Inverter:Enables power flow reversal between battery and grid, essential for vehicle-to-grid revenue models. Demand concentrates in European fleet procurement frameworks where grid-stabilization contracts incentivize bidirectional capability. Regulatory pressure from EU grid codes accelerates specification mandates.
- Multi-Level Inverter:Reduces switching losses through cascaded voltage levels, delivering superior waveform quality for high-torque motor control. Adoption clusters in premium Chinese passenger platforms where 800V architectures demand harmonic distortion minimization. BYD and NIO specifications favor this topology for flagship sedans.
- Modular Inverter:Scalable half-bridge arrays accommodate multiple vehicle classes without redesign. Tier 1 suppliers adopt standardized footprints to amortize validation costs.
- Matrix Inverter:Direct AC-to-AC conversion eliminates DC-link capacitors, reducing component count. Limited deployment in specialized commercial vehicle applications.
Volume placements concentrate in bidirectional configurations; the faster expansion belongs to multi-level architectures as 800V platforms proliferate.
Technology:
Cost tier stratification in power semiconductors determines which substrate materials penetrate which vehicle price bands, with thermal efficiency premiums dictating margin structures.
- Silicon:Mature insulated-gate bipolar transistor technology dominates economy vehicle platforms where cost sensitivity overrides efficiency gains. Production concentrates at Chinese foundries serving domestic OEMs under GB standard compliance thresholds.
- SiC:Silicon carbide MOSFETs enable switching frequencies above 50 kHz, shrinking magnetic component mass. Premium passenger OEMs in Germany and the United States specify SiC for EPA compliance and thermal envelope constraints.
- GaN:Gallium nitride devices penetrate 400V architectures where SiC remains over-specified, opening mid-market differentiation.
- Hybrid:Combines SiC and silicon devices to balance cost and performance in transition platforms.
Silicon retains the largest installed base; SiC claims the steepest expansion trajectory as foundry capacity scales.
End User:
Customer type fragmentation separates fleet procurement frameworks focused on total cost of ownership from consumer retail decisions driven by upfront vehicle pricing.
- Passenger Vehicles:OEM procurement emphasizes power density and NVH reduction for cabin comfort. Specifications diverge between mass-market Chinese platforms and premium European architectures.
- Commercial Vehicles:Heavy-duty electrification in India and Brazil generates demand for high-current inverter architectures capable of sustained peak loads. Fleet operators negotiate service-interval guarantees.
- Two-Wheelers:Cost-optimized silicon designs dominate Southeast Asian markets where price elasticity constrains semiconductor selection.
- E-Bikes:Low-voltage inverter integration with hub motors drives unit volumes in European urban mobility segments.
Passenger vehicles absorb the greatest absolute volume; commercial vehicle electrification offers the most rapid share gain potential.
Installation:
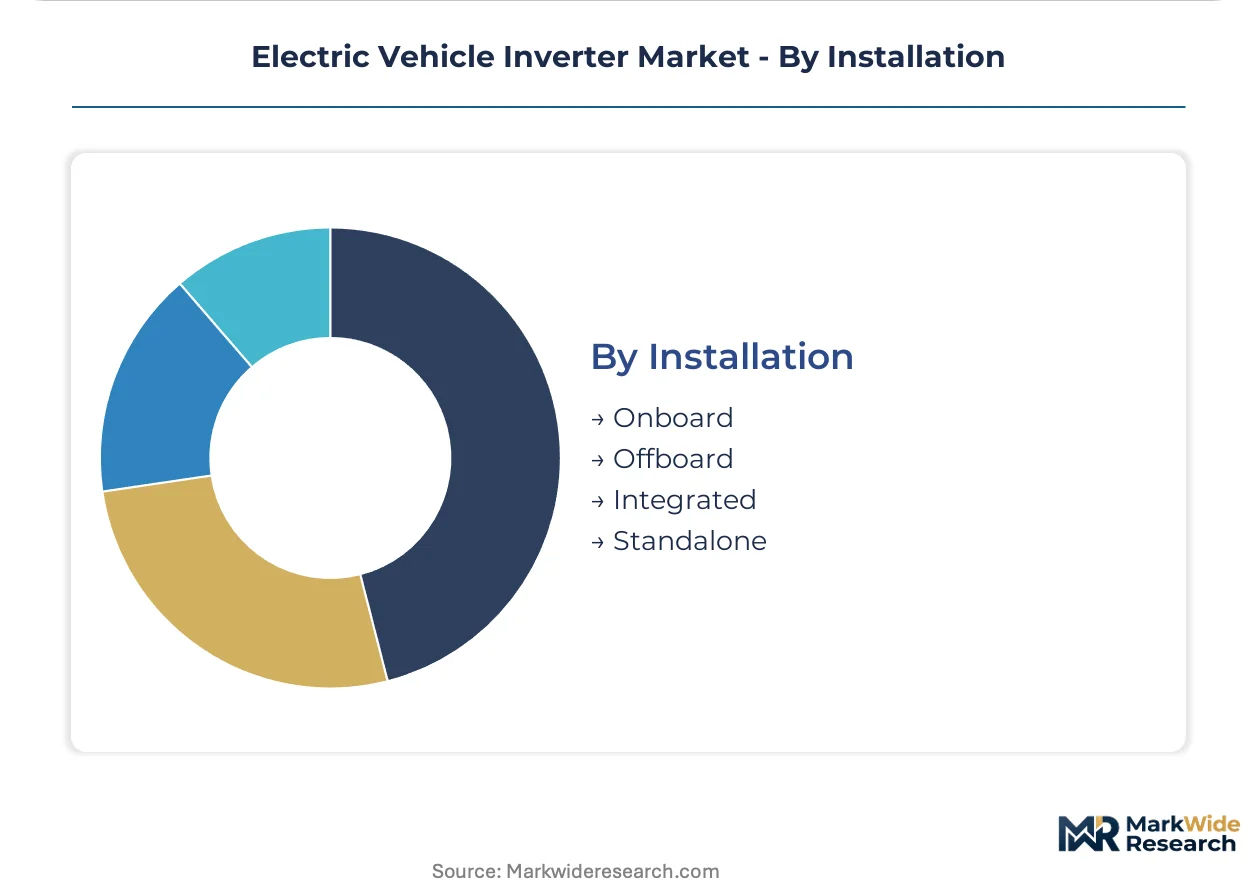
Supply concentration in onboard integration reflects Chinese manufacturing scale advantages for consolidated powertrain units.
- Onboard:Standard configuration for passenger vehicles, with inverter packaged adjacent to motor or integrated within axle assemblies. Chinese OEMs lead consolidation with inverter-OBC-DC-DC combinations.
- Offboard:Stationary charging infrastructure employs grid-tied inverters for DC fast-charging stations. Deployment tracks charging network buildouts.
- Integrated:Power electronics merged with transmission or motor housing reduces assembly steps and mass.
- Standalone:Discrete inverter enclosures persist in retrofit applications and specialized commercial configurations.
Integrated installations are climbing fastest as platform engineering prioritizes mass reduction; onboard units maintain volume dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon carbide substrate supply from East Asian foundries anchors geographic production patterns for high-performance traction inverters. Procurement networks concentrate where automotive OEMs and power semiconductor fabricators cluster near raw material processing and battery assembly ecosystems.
China
BYD and CATL supply chains drive volume demand for onboard integrated inverter units across domestic new energy vehicle platforms. GB standards mandate efficiency thresholds that accelerate SiC adoption in domestically produced passenger vehicles. Shenzhen and Shanghai anchor manufacturing clusters where inverter-OBC-DC-DC consolidation reduces assembly steps.
United States
EPA tailpipe rules tighten emissions thresholds for passenger vehicle OEMs, elevating SiC inverter procurement from optional to mandatory compliance infrastructure. NHTSA safety protocols govern electromagnetic compatibility in high-voltage power electronics validation. Michigan and California house engineering centers where Tier 1 suppliers calibrate thermal management systems for 800V architectures.
Germany
Premium passenger OEMs specify SiC traction inverters for thermal envelope constraints and power density requirements in luxury electric platforms. EU F-Gas Regulation mandates refrigerant transitions that force thermal system redesigns for lower-GWP coolants. Bavaria and Baden-Württemberg concentrate power module packaging lines where Continental AG operates captive production facilities.
Japan
Mitsubishi Electric Corporation anchors market position through dedicated joint ventures with domestic SiC crystal growers securing wafer allocations. METI industrial policy supports wide-bandgap semiconductor foundry expansion to reduce import dependency. Nagoya and Tokyo metropolitan areas host integrated motor-inverter development centers serving Toyota and Honda electrification programs.
South Korea
Hyundai Motor Group and Kia Corporation procurement frameworks prioritize bidirectional inverter capability for vehicle-to-grid revenue models in fleet segments. MFDS regulatory alignment with international electromagnetic compatibility standards streamlines export certification for module manufacturers. Gyeonggi Province clusters power electronics R&D facilities near battery cell production sites.
Electric Vehicle Inverter Market Competitive Landscape
Global majors compete with regional champions across substrate sourcing and module packaging capabilities. The vendor base stratifies into three tiers: integrated automotive Tier 1 suppliers with captive semiconductor capacity, specialized power electronics fabricators dependent on merchant wafer supply, and emerging Asian challengers leveraging domestic foundry relationships. Strategic archetypes include backward-integrated technology leaders, scale-focused module assemblers, and niche specialists in commercial vehicle high-current architectures. Competitive moves center on securing long-term SiC wafer offtake agreements and expanding power module packaging capacity in proximity to OEM assembly plants.
Among German-based diversified automotive suppliers, Continental AG and Robert Bosch GmbH occupy positions reflecting different integration strategies. Bosch leverages in-house wafer sourcing to secure allocations ahead of merchant competitors, while Continental competes via captive supply of power module packaging lines. Japanese industrial conglomerates Mitsubishi Electric Corporation and Hitachi Astemo Ltd exemplify the Asia-Pacific archetype of tight coordination between crystal growth partnerships and automotive OEM supply relationships. These three named entities represent distinct geographic and structural approaches to managing substrate bottlenecks.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| DENSO Corporation |
| Vitesco Technologies |
| Toyota Industries Corporation |
| Mitsubishi Electric Corporation |
| Hitachi Astemo Ltd |
| Valeo Group |
| BorgWarner Inc. |
| Others |
Pricing and Supply Chain Analysis
SiC substrate yield improvements simultaneously compress unit economics and concentrate supply power among East Asian foundries with proven crystal growth capabilities. EPA tailpipe rules and EU F-Gas mandates force OEMs to absorb material cost premiums while negotiating long-term offtake agreements that lock in allocation priority.
Pricing Analysis
Warranty and service bundling separates premium inverter suppliers from commodity assemblers, with fleet operators negotiating lifecycle cost frameworks that penalize premature failure. Three-tier pricing structure across premium, standard, and economy levels reflects SiC content, thermal management complexity, and ISO 26262 ASIL-D certification status. Cost compression in economy-tier silicon IGBT modules intensifies as Chinese foundries expand 6-inch wafer capacity. Fleet procurement exhibits lowest price sensitivity due to total cost of ownership frameworks, while two-wheeler OEMs in Southeast Asia remain most cost-constrained.
Supply Chain Analysis
Dual-sourcing mandates from European and North American OEMs force module manufacturers to qualify substrates across Japanese, South Korean, and domestic crystal growers simultaneously. Raw material dependencies center on high-purity silicon carbide powder, copper-clad ceramic substrates, and epoxy molding compounds. Single-source vulnerability concentrates in 6-inch SiC wafer supply where East Asian foundries control bulk output. Distribution runs through Tier 1 automotive suppliers with captive packaging lines positioned adjacent to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around substrate allocation security as SiC wafer bottlenecks force merchant-dependent assemblers toward acquisition or exit.
For Market Incumbents: Acquire captive SiC crystal growth capacity or secure exclusive joint venture offtake before foundry expansion saturates premium allocations. Defensive moves center on backward integration into wafer sourcing and expanding power module packaging footprint in proximity to German and US OEM engineering centers. GaN device substitution threatens SiC over-specification in 400V architectures. For New Entrants and Emerging Players: Fleet procurement channels offer the most penetrable entry vector given lifecycle cost frameworks that reward service-interval predictability over incumbent brand recognition. White-space targets include heavy-duty commercial vehicle electrification in India and Brazil, plus bidirectional inverter specifications for European grid-stabilization contracts. Go-to-market positioning should emphasize remanufacturing potential and remanufactured unit availability. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to automotive Tier 1 suppliers seeking SiC allocation security, with IPO viability tethered to demonstrated wafer sourcing independence. Long-term viability favors entities with proven crystal growth partnerships or captive substrate supply. Watch SiC substrate yield inflection at East Asian foundries as the signal for margin expansion versus compression across the value chain.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Wafer Supply Agreement | Locks allocation priority ahead of merchant competitors as EPA rules tighten. |
| Power Module Packaging Expansion | Positions captive capacity adjacent to BMW and Ford assembly ecosystems. |
| GaN Device Platform Development | Captures 400V architecture share where SiC remains economically over-specified. |
| Vehicle-to-Grid Certification Investment | Unlocks fleet procurement frameworks requiring bidirectional power flow compliance. |
| Commercial Vehicle Thermal System Redesign | Addresses EU F-Gas refrigerant mandates for heavy-duty electrification segments. |
Research Methodology
Document review covered SEC automotive supplier filings, EPA regulatory dockets, and SiC substrate trade data, complemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, and power semiconductor foundry operations managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, and customs records tracking wide-bandgap device imports. Bottom-up unit economics triangulated against top-down OEM procurement forecasts.
Historical capacity expansion patterns cross-referenced against panel input from crystal growth equipment vendors and substrate manufacturers. Segmentation modeling spanned vehicle class, propulsion voltage architecture, semiconductor technology tier, and regional production cluster. CAGRs derived from installed base replacement cycles and technology transition elasticity coefficients. Forecast inputs incorporated EPA compliance timeline acceleration and EU F-Gas refrigerant phase-down schedules.
Caveats apply where SiC substrate yield improvements, geopolitical trade measure escalation, or GaN device performance breakthroughs could materially shift the outlook. Deviation in East Asian foundry expansion timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Synchronous Condenser Market
Power Systems
Power Supply Isolation Equipment Market
Power Systems
US Variable Frequency Drive Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Global Power Discrete and Modules Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
Intelligent Power Module (IPM) Market
Power Systems
Pulse Generator Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Harmonic Generators Market
Power Systems
Telecom Battery Market
Power Systems
Battery Electronic Control Unit Market