
 APAC Variable Frequency Drives Market | 2026-2036
APAC Variable Frequency Drives Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Variable Frequency Drives Market Outlook
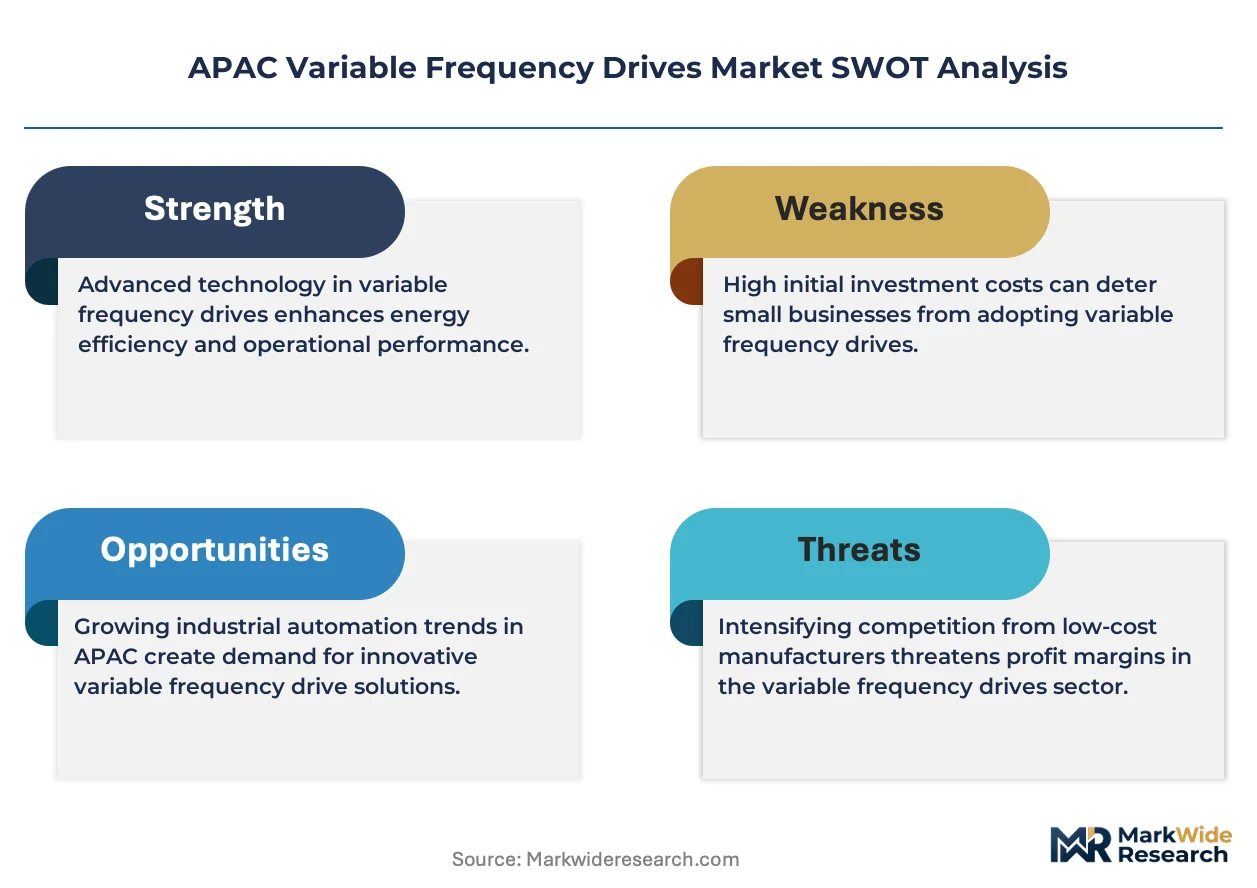
Chinese VFD manufacturing capacity is hardening around high-voltage and medium-voltage platforms for heavy industry. ABB Ltd. leverages its Shanghai and Beijing engineering centers to anchor regional service density for steel and cement clients. Siemens AG competes through localized production in Jiangsu, while Yaskawa Electric Corporation specializes in precision servo drive architectures for robotics and semiconductor fabrication tools.
A variable frequency drive modulates motor speed by varying input frequency and voltage, typically operating across 0.75 kW to multiple megawatt ranges with insulated-gate bipolar transistor switching topologies. AC Drives dominate installed base volumes across pumping and HVAC applications, though Servo Drives claim the densest margin pools in precision material handling and automated conveying lines where vector control algorithms enable sub-millisecond torque response.
China's MIIT enforces GB motor efficiency standards that effectively mandate VFD pairing for new installations above designated power thresholds, while India's BEE star-labeling program and Perform Achieve Trade scheme compress payback periods for industrial retrofit projects. Japan's METI directs technical assistance programs that diffuse advanced closed-loop control methods to ASEAN manufacturing clusters. Stakeholders must track how carbon border adjustment mechanisms in buyer countries redirect export-oriented factory investment toward premium efficiency tiers.
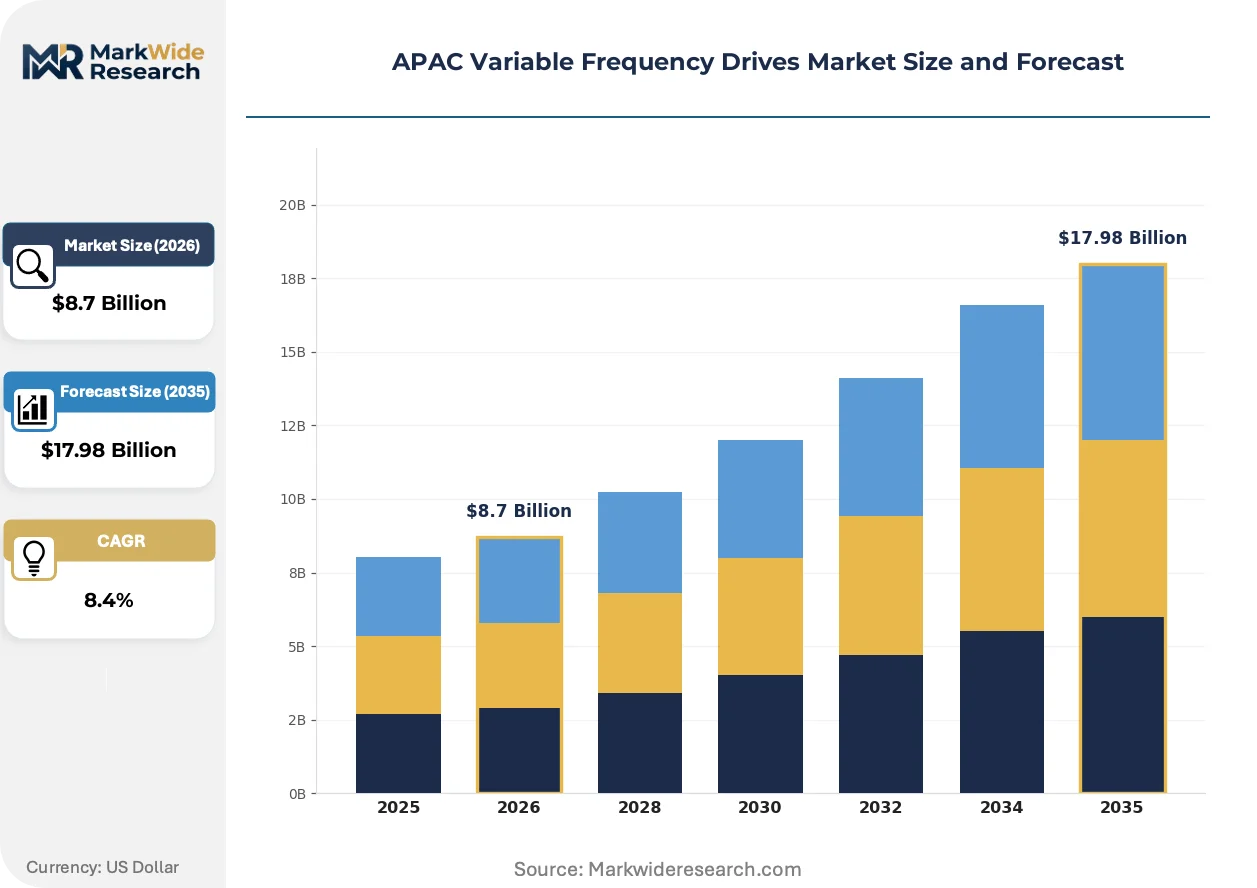
Market Dynamics
China's dual carbon goals and India's Bureau of Energy Efficiency mandates are compressing payback periods for industrial motor retrofits while reshaping procurement specifications across coastal manufacturing belts.
Growth Catalysts
- GB Motor Efficiency Standards:China's MIIT enforces mandatory VFD pairing for new installations above designated power thresholds, eliminating baseline motor-only deployments in heavy industry.
- Textile Cluster Electrification:Manufacturing facilities across Zhejiang and Guangdong provinces accelerate efficiency retrofits as industrial electricity tariffs climb and carbon disclosure rules tighten.
- IGBT Switching Topologies:Advances in insulated-gate bipolar transistor architectures enable higher voltage handling with reduced switching losses, expanding addressable applications in cement and steel.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings from Chinese export quotas inflate permanent magnet motor costs, compressing VFD system margins.
- Semiconductor Foundry Concentration:Power chip fabrication concentrates in Taiwan and South Korea, exposing supply continuity to geopolitical friction and capacity allocation priorities.
- Legacy DC Motor Installed Base:Extensive existing DC architectures in Indian textile mills and Japanese machine tool parks delay AC VFD conversion cycles despite efficiency advantages.
Strategic Opportunities
- Vietnamese Manufacturing Expansion:Export-oriented factory construction in Bac Ninh and Hai Phong industrial zones creates first-mover positioning for efficiency-integrated drive packages.
- Perform Achieve Trade Credits:India's PAT scheme monetizes energy savings into tradable instruments, financing retrofit investments for designated consumers in aluminum and pulp.
- Predictive Maintenance Convergence:Vibration sensing and edge analytics integration with drive controllers enables condition-based servicing contracts displacing fixed-interval maintenance.
Industry Challenges
- Field Commissioning Expertise Gap:Vector control parameter tuning for servo-grade torque response requires specialized technicians scarce outside Shanghai, Tokyo, and Bangalore technical centers.
- Dual Certification Timelines:Simultaneous BIS and GB mark approvals for pan-Asian product launches extend time-to-revenue by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Variable Frequency Drives Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drives, DC Drives, Servo Drives, Micro Drives End User: Water & Wastewater, Oil & Gas, Mining, Manufacturing Technology: Vector Control, Open Loop Control, Closed Loop Control, Pulse Width Modulation Application: Pumping, HVAC, Conveying, Material Handling |
| Companies Covered | ABB Ltd., Siemens AG, Schneider Electric SE, Mitsubishi Electric Corporation, Danfoss A/S, Fuji Electric Co., Ltd., Yaskawa Electric Corporation, Rockwell Automation, Inc., Toshiba Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Variable Frequency Drives Market Strategic Shifts
Silicon carbide power semiconductors and AI-enhanced control algorithms are compressing form factors while extending operational envelopes, forcing incumbents to recalibrate R&D roadmaps and manufacturing footprints.
Wide-bandgap silicon carbide MOSFETs replace traditional silicon IGBTs in medium-voltage platforms above 400 kW. Japanese automotive press shops and Korean battery gigafactories adopt these architectures for regeneration-heavy duty cycles. This transition is rewriting thermal management requirements and enabling liquid-cooled drive enclosures that halve cabinet volumes.
China's MIIT periodically tightens GB 18613 efficiency tiers, most recently elevating IE3 as the minimum acceptable level for motors above 0.75 kW. The regulation forces domestic manufacturers to bundle VFDs with premium efficiency motors rather than selling standalone units. Textile and chemical plants in Jiangsu and Shandong provinces now specify integrated motor-drive packages to preempt compliance verification costs.
Industrial buyers increasingly unbundle hardware procurement from commissioning and long-term service agreements. Japanese automotive tier suppliers and Singaporean water utilities now source drives through distributor channels while contracting directly with system integrators for installation and predictive maintenance. This channel fragmentation concentrates margin capture with technical specialists in Malaysia's Penang corridor and Thailand's Eastern Economic Corridor.
APAC Variable Frequency Drives Market Segmentation
VFD procurement specifications diverge sharply across installation contexts. Certification requirements from India's BIS and China's GB standards create compliance moats that reshape competitive positioning within each segment cluster.
Product Type:
Certification burdens concentrate heaviest on Servo and AC Drive platforms, where MIIT's GB 18613 efficiency tiers and BIS mark mandates impose dual-testing protocols that extend time-to-market by eight to fourteen months.
- AC Drives:Insulated-gate bipolar transistor switching architectures dominate installed base volumes across 0.75 kW to multiple megawatt ranges. Demand concentrates in China's coastal manufacturing belts, where textile and chemical plants face steep efficiency compliance deadlines from dual carbon goals.
- Servo Drives:Vector control algorithms enable sub-millisecond torque response for precision material handling applications. Japanese automotive tier suppliers and Korean battery gigafactories adopt these architectures for regeneration-heavy duty cycles, though permanent magnet motor costs fluctuate with Chinese rare earth export quotas.
- DC Drives:Legacy architectures persist in Indian textile mills and Japanese machine tool parks, delaying conversion cycles despite AC VFD efficiency advantages.
- Micro Drives:Compact units below 0.75 kW serve distributed pumping and small HVAC loads across Southeast Asian commercial buildings.
Leading the category by volume: AC Drives. Expanding most quickly: Servo Drives.
End User:
Cost tier stratification separates premium efficiency-integrated packages for carbon-intensive sectors from standard configurations serving price-sensitive municipal utilities.
- Manufacturing:Textile clusters across Zhejiang and Guangdong provinces accelerate motor efficiency retrofits as industrial electricity tariffs climb. China's MIIT enforces mandatory VFD pairing for new installations above designated power thresholds.
- Water & Wastewater:Municipal pumping stations across Singapore and Thailand's Eastern Economic Corridor specify integrated motor-drive packages to preempt compliance verification costs.
- Oil & Gas:Upstream and midstream facilities in Australia's offshore basins and India's western coast deploy medium-voltage platforms for compression and pumping duty.
- Mining:Australian iron ore operations and Indonesian nickel processing plants demand ruggedized enclosures for dust-heavy environments with continuous duty cycles.
Highest margin capture: Manufacturing. Steepest retrofit urgency: Water & Wastewater.
Technology:
Application complexity determines control architecture selection, with precision positioning tasks demanding closed-loop feedback while bulk material movement tolerates simpler open-loop configurations.
- Vector Control:Sensorless and flux-vector methods enable precise speed-torque decoupling for crane and hoist applications across Korean shipyards and Chinese port facilities.
- Closed Loop Control:Encoder feedback architectures serve semiconductor fabrication tools and robotics cells in Japan's precision manufacturing clusters.
- Pulse Width Modulation:Carrier frequency optimization reduces motor heating in long-cable installations common to Australian mining conveyors.
- Open Loop Control:Volts-per-hertz schemes satisfy cost-constrained fans and pumps in Indian commercial HVAC retrofits.
Widest deployment: Vector Control. Densest margin pool: Closed Loop Control.
Application:
Geographic concentration of end-use demand reshapes regional service density requirements, with coastal manufacturing belts and desert mining corridors imposing divergent thermal and environmental specifications.
- Pumping:Water distribution networks and process industries account for substantial installed base volume across India's Bureau of Energy Efficiency mandate zones.
- HVAC:Commercial building codes in Singapore and Australia's NCC specification tiers drive premium efficiency tier adoption for chiller and air handling units.
- Conveying:Bulk material transport systems in Indonesian coal terminals and Australian iron ore export facilities demand regenerative braking capabilities.
- Material Handling:Automated storage and retrieval systems in Vietnam's Bac Ninh industrial zones specify servo-grade precision for high-bay warehouse operations.
Largest addressable base: Pumping. Fastest specification upgrading: Material Handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing capacity in China's Inner Mongolia and Jiangxi provinces anchors regional VFD supply chains, with downstream drive assembly clustering along coastal manufacturing belts where electrification mandates bite hardest.
China
Steel and cement producers in Hebei and Shandong provinces face accelerating MIIT enforcement of GB motor efficiency standards that mandate VFD pairing above 0.75 kW. The Yangtze River Delta textile corridor consumes premium servo-drive packages as Zhejiang plants retrofit for carbon disclosure compliance.
India
Aluminum smelters and pulp mills designated under the PAT scheme monetize energy savings into tradable certificates that finance VFD retrofits. Bureau of Energy Efficiency star-labeling compresses payback periods across Maharashtra and Gujarat industrial zones where electricity tariffs climb fastest.
Japan
Automotive press shops and semiconductor fabrication tools in the Chubu region drive demand for silicon carbide-based medium-voltage architectures. METI technical assistance programs diffuse closed-loop control methods to ASEAN manufacturing clusters through Nagoya-based engineering centers.
South Korea
Battery gigafactories in the Seoul Capital Area adopt regeneration-heavy drive systems for electrode coating lines. Korean power semiconductor foundries in Suwon and Pyeongtaek supply IGBT modules that reduce switching losses in heavy industrial duty cycles.
Vietnam
Export-oriented electronics assembly in Bac Ninh and Hai Phong industrial zones creates first-mover demand for integrated motor-drive packages. Foreign-owned factories specify efficiency-integrated systems to preempt carbon border adjustment exposure in EU and US buyer markets.
APAC Variable Frequency Drives Market Competitive Environment
Global majors compete with regional champions across service density and certification speed, producing a tiered structure where European and Japanese conglomerates anchor premium segments while Chinese specialists capture volume in standard AC drive categories. Three archetypes dominate: integrated automation conglomerates with captive semiconductor supply, precision motion specialists focused on servo architectures, and cost-optimized domestic manufacturers serving retrofit markets. Competitive intensity manifests through localized production investments and strategic partnerships with system integrators rather than direct price confrontation.
Among Switzerland-based and Germany-based automation conglomerates, ABB Ltd. and Siemens AG exemplify the integrated archetype with engineering center density across Shanghai and Jiangsu province. Yaskawa Electric Corporation, a Japanese precision motion specialist, occupies a position in the servo-drive tier where vector control algorithms command premium positioning. These three anchors illustrate how geographic origin and corporate structure map to competitive specialization without overlapping segment territory.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Danfoss A/S |
| Fuji Electric Co., Ltd. |
| Yaskawa Electric Corporation |
| Rockwell Automation, Inc. |
| Toshiba Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive semiconductor fabrication in Taiwan and South Korea anchors pricing power for insulated-gate bipolar transistor modules, while Chinese rare earth processing concentration in Inner Mongolia and Jiangxi provinces dictates permanent magnet motor cost trajectories across the APAC Variable Frequency Drives Market. This upstream integration pattern separates premium servo-drive suppliers from standard AC drive assemblers competing on procurement efficiency.
Pricing Analysis
Warranty and commissioning service bundling separates premium-tier suppliers from hardware-only vendors across the APAC Variable Frequency Drives Market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation between GB-marked and BIS-approved systems versus unlabeled alternatives. Pricing pressure stems from rare earth magnet volatility inflating permanent magnet motor costs, compressing system margins. Municipal utilities and Indian commercial HVAC retrofits exhibit highest price sensitivity, while Japanese automotive tier suppliers prioritize torque response precision over unit economics.
Supply Chain Analysis
Freight cost escalation from Taiwanese semiconductor foundries to Chinese coastal assembly plants is reshaping regional inventory positioning across the APAC Variable Frequency Drives Market. Power chip fabrication concentrates in Taiwan and South Korea, while rare earth processing and magnet production centers on China's Jiangxi and Inner Mongolia provinces. Single-source vulnerability in IGBT module supply exposes continuity risks from geopolitical friction. Distribution runs through authorized distributor networks in Malaysia's Penang corridor and Thailand's Eastern Economic Corridor, with system integrators capturing commissioning and predictive maintenance revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC Variable Frequency Drives Market is consolidating around integrated motor-drive packages as China's MIIT tightens GB 18613 efficiency tiers, eliminating standalone motor vendors unable to bundle control electronics.
For Market Incumbents: Acquire field commissioning expertise in Vietnamese and Indonesian industrial corridors before technical talent scarcity hardens. Backward integration into silicon carbide power semiconductor sourcing reduces exposure to Taiwanese foundry allocation priorities. Capture aftermarket service contracts through vibration sensing and edge analytics integration, displacing fixed-interval maintenance revenue pools. For New Entrants and Emerging Players: System integrators in Vietnam's Bac Ninh and Hai Phong zones represent the most penetrable channel partner type for first-mover positioning. Target export-oriented electronics assembly facilities seeking efficiency-integrated packages to preempt carbon border adjustment exposure. White-space exists in predictive maintenance convergence for Indonesian nickel processing and Australian iron ore conveying applications. Lead with commissioning capability rather than hardware cost to differentiate from established distributors. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated automation conglomerates seeking regional service density. The five-to-ten year viability window favors targets with captive GB and BIS certification capabilities and established system integrator relationships. Acquisition target archetype: mid-cap specialists with vertical control over servo-grade vector control tuning expertise. Watch for carbon border adjustment mechanism expansion in EU and US buyer markets as the inflection signal redirecting factory investment toward premium efficiency tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Sourcing | Reduces switching losses in medium-voltage platforms above 400 kW for Korean battery gigafactories. |
| GB-BIS Dual Certification Investment | Compresses time-to-revenue for pan-Asian product launches in textile and chemical verticals. |
| Predictive Maintenance Platform Development | Enables condition-based servicing contracts displacing fixed-interval maintenance in Australian mining. |
| Vietnamese Manufacturing Footprint Expansion | Captures first-mover demand from export-oriented electronics assembly in Bac Ninh industrial zones. |
| Servo-Grade Commissioning Capability Buildout | Addresses field expertise scarcity outside Shanghai, Tokyo, and Bangalore technical centers. |
Study Parameters
Trade databases, MIIT regulatory filings, and BEE star-labeling program documentation formed the secondary backbone for this analysis. Primary interviews with plant engineers at Chinese textile and chemical facilities, procurement leads at Japanese automotive tier suppliers, aftermarket service heads at regional distributors, and technical R&D directors at power semiconductor foundries validated demand assumptions. Bottom-up and top-down triangulation reconciled installation volumes with efficiency mandate compliance timelines.
Bottom-up modeling of segment-level demand across product type, end user, technology, and application dimensions anchored the forecast framework. Top-down validation against industrial electricity tariff trajectories and carbon disclosure rule adoption patterns ensured consistency. CAGRs were derived from payback period compression under China's dual carbon goals and India's PAT scheme across the projection horizon. Forecast inputs incorporated IGBT switching topology adoption curves and silicon carbide MOSFET penetration in regeneration-heavy duty cycles.
Caveats apply where semiconductor foundry capacity allocation priorities or rare earth export quota adjustments could materially shift the outlook. Forecasts reflect assumptions regarding MIIT enforcement consistency and BEE mandate expansion that industry stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Traction Inverter Market
Power Systems
Global Gan Power Device Market
Power Systems
Telecom Battery Market
Power Systems
Transformer Tap Changers and Voltage Control Relay Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Generator Circuit Breaker Market
Power Systems
Charge Controller System Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
Global Next Generation Power Semiconductors Market
Power Systems
North America Micro Inverter Market
Power Systems
Power Inverter Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
North America Electric Vehicle Power Inverter Market