
 Medical Waste Management System Market | 2026-2036
Medical Waste Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Waste Management System Market Foresight
Small clinic outsourcing is collapsing into consolidated hospital system contracts as procurement centralizes. Stericycle anchors North American biohazard logistics through its national pickup infrastructure. Veolia dominates European thermal treatment capacity with dedicated medical waste incinerators. Clean Harbors competes in industrial-scale chemical disposal for pharmaceutical manufacturing byproducts.
A medical waste management system encompasses containers, autoclaves, shredders, and compactors paired with incineration, chemical, microwave, or plasma treatment technologies to neutralize infectious, pathological, and pharmaceutical residues. Autoclave-based systems process saturated steam at 121°C for 30–60 minutes to achieve sterility assurance levels required for landfill diversion. Incineration leads technology deployment due to regulatory familiarity, though plasma technology captures margin pools where mercury and dioxin restrictions tighten. Collection and transportation services generate recurring revenue stickiness that disposal and recycling segments struggle to match.
The US EPA Resource Conservation and Recovery Act, OSHA Bloodborne Pathogens Standard, and EU Waste Framework Directive shape generator liability chains and treatment facility permitting timelines. Germany's KBA-aligned federal waste ordinances and France's ANSM hospital hygiene circulars enforce traceability from point-of-generation to final destruction. Stakeholders must monitor emerging state-level pharmaceutical take-back mandates and EU MDR packaging waste extensions that could redefine generator responsibility boundaries.
Market Dynamics
Hospital procurement centralization is compressing vendor relationships into multi-year integrated service contracts, eliminating standalone equipment sales and forcing treatment providers to absorb capital risk for on-site autoclave and microwave systems.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:US outpatient surgical centers face mandatory exposure control plans that drive outsourcing to certified haulers with documented chain-of-custody protocols.
- Pharmaceutical manufacturing expansion:Biologics production in Singapore and Switzerland generates cytotoxic waste streams requiring specialized chemical inactivation infrastructure.
- EU Waste Framework Directive traceability mandates:Generator liability extension to final destruction point compels clinics in France and Germany to contract with permitted treatment networks rather than self-manage.
Market Restraints
- Energy cost volatility:Thermal treatment facilities in Germany and Poland face margin compression from natural gas price swings that autoclave and microwave operators avoid.
- Incinerator permitting timelines:US state environmental agencies require 18–36 months for new medical waste combustion permits, freezing capacity expansion in high-demand corridors.
- Mercury recovery limitations:Dental amalgam separator waste lacks economical secondary processing routes, forcing generators to stockpile or pay premium hazardous disposal rates.
Strategic Opportunities
- India's CDSCO pharmaceutical manufacturing clusters:Export-oriented API producers near Hyderabad and Ahmedabad require WHO-compliant waste treatment partnerships to maintain GMP certification.
- On-site microwave-sterilization convergence:Integration with hospital building management systems enables real-time fill-level monitoring and predictive collection dispatch.
- US state pharmaceutical take-back mandates:Extended producer responsibility laws in California and Washington create reverse-logistics revenue streams for controlled substance destruction.
Industry Challenges
- Autoclave operator certification gaps:Biomedical equipment technicians with steam sterilizer validation expertise command premium wages that strain mid-sized service providers.
- Legacy incinerator retrofit complexity:Existing facilities face multi-million dollar upgrades to meet tightened EU Industrial Emissions Directive dioxin limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Waste Management System Market |
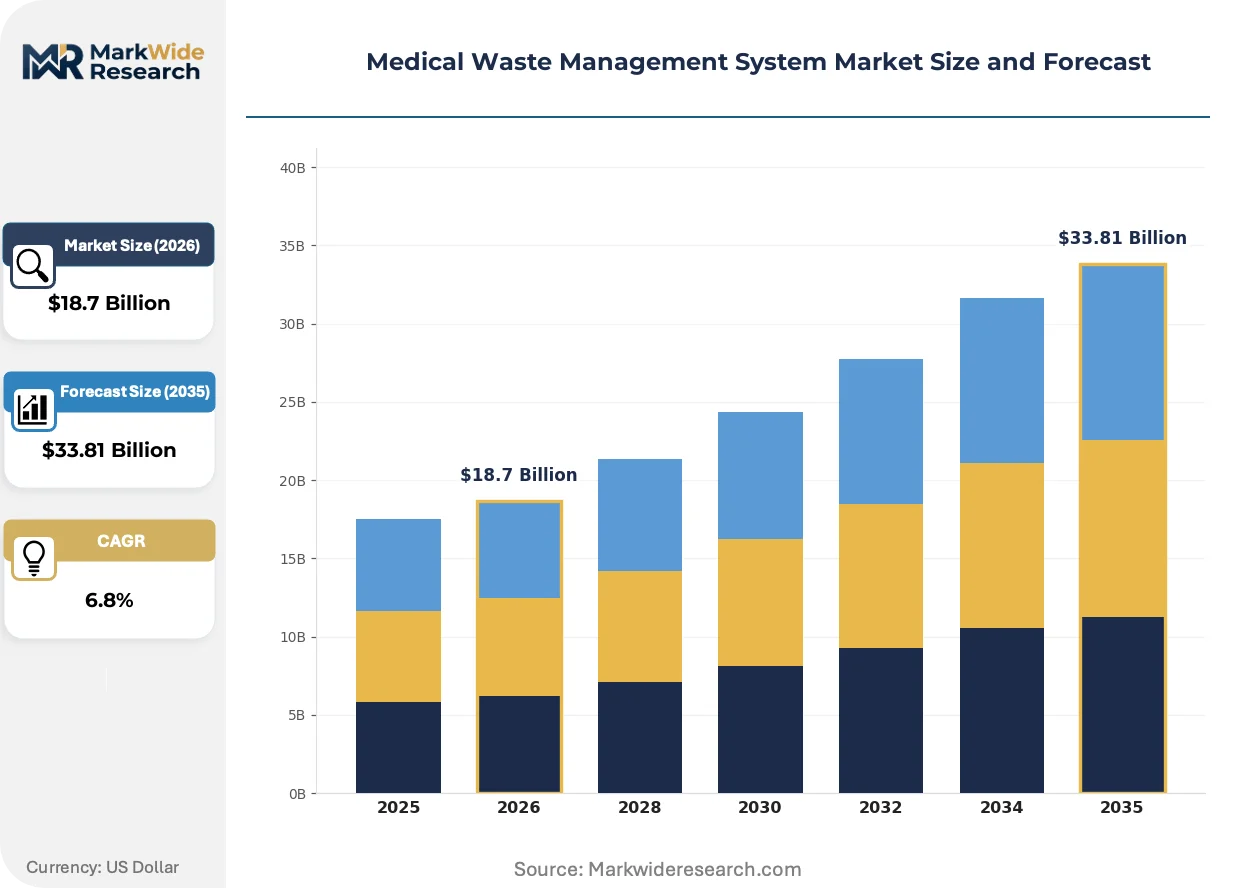
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Autoclaves, Shredders, Compactors Technology: Incineration, Chemical Treatment, Microwave Treatment, Plasma Technology End User: Hospitals, Clinics, Laboratories, Long-term Care Facilities Service Type: Collection, Transportation, Disposal, Recycling |
| Companies Covered | Stericycle, Clean Harbors, Veolia, Republic Services, Waste Management, REMONDIS SE & Co. KG, Suez, Sharps Compliance, Daniels Sharpsmart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Waste Management System Market Shifts & Advancements
Plasma arc gasification is advancing from pilot demonstrations to commercial deployment, offering mercury and dioxin destruction capabilities that thermal oxidation cannot match. Treatment technology selection now hinges on local air quality restrictions rather than capital cost alone.
Microwave-based sterilization systems operating at 2450 MHz are displacing conventional autoclaves in US outpatient surgery chains seeking faster cycle times and lower water consumption. Sutter Health and Kaiser Permanente pilot programs demonstrate 40% throughput gains for pathological waste streams. The technology is compressing equipment replacement cycles from ten years to five as efficiency benchmarks tighten.
France's ANSM hospital hygiene circulars now mandate electronic waste tracking from generation through final destruction, effective January 2024. This obligation forces treatment providers to deploy RFID-tagged containers and cloud-based manifest systems. Small French clinics lacking IT infrastructure are consolidating contracts with national logistics operators capable of compliance data management.
Buying committees at US health systems now bundle waste services with linen, environmental services, and food contracts under single-source GPO arrangements. Premier and Vizient negotiate multi-hospital system agreements that displace regional haulers. This concentration is most visible in Texas and Florida where HCA and Tenet facilities dominate metropolitan service territories.
Medical Waste Management System Market Segmentation
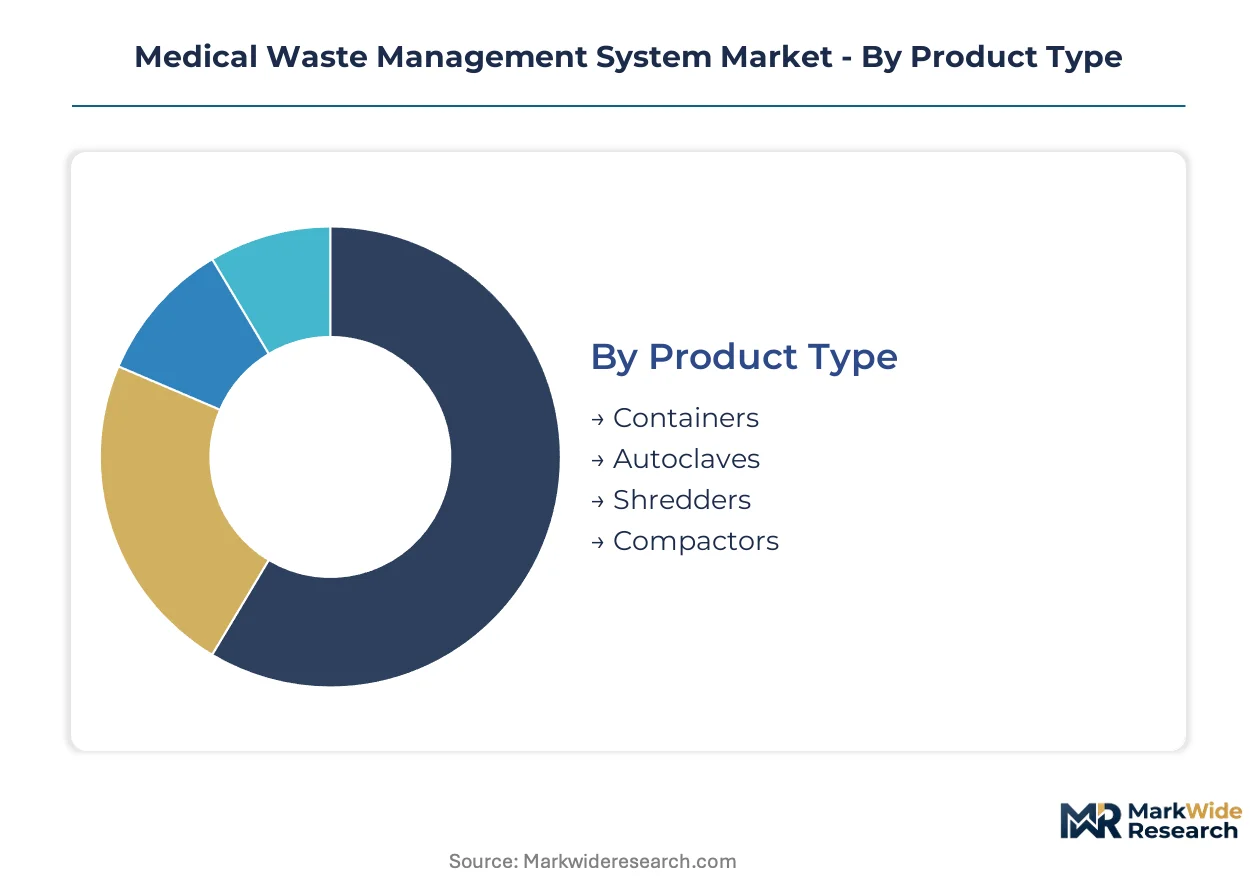
Medical waste management procurement divides sharply between capital equipment buyers and service contract holders. Regulatory complexity varies dramatically across these boundaries, with technology selection often predetermined by local air quality standards and liability frameworks.
Product Type:
OSHA container standards and EU MDR traceability mandates create divergent specification requirements across jurisdictions.
- Containers:Leak-resistant, puncture-proof vessels with color-coded lids for sharps, biohazard, and pharmaceutical streams. Demand concentrates in US outpatient surgery chains where OSHA Bloodborne Pathogens Standard enforcement drives replacement cycles; RFID-tagged variants gain traction in France under ANSM electronic tracking mandates.
- Autoclaves:Pressure vessels delivering saturated steam at 121°C for 30–60 minutes to achieve sterility assurance levels. German hospital procurement centralization favors integrated autoclave-logistics bundles from REMONDIS and Veolia; energy efficiency benchmarks compress equipment replacement from ten years to five.
- Shredders:Mechanical size-reduction units for pathological waste preprocessing. US veterinary clinics and small laboratories deploy compact countertop models.
- Compactors:Volume-reduction equipment for general medical waste streams. Long-term care facilities in Texas and Florida favor these for landfill cost containment.
Autoclaves handle the majority of throughput; containers are expanding most quickly on share.
Technology:
Capital intensity and permitting timelines separate incineration operators from alternative technology adopters.
- Incineration:Thermal oxidation at 800–1200°C destroying infectious, pathological, and pharmaceutical residues through complete combustion. Poland and Germany host dense networks of permitted facilities; natural gas price volatility compresses margins in these markets.
- Chemical Treatment:Oxidizing agents or pH neutralization for liquid infectious waste and cytotoxic pharmaceutical byproducts. Singapore biologics manufacturers require specialized chemical inactivation infrastructure for WHO GMP compliance.
- Microwave Treatment:2450 MHz radiation sterilization with faster cycle times and lower water consumption than autoclaving. Sutter Health and Kaiser Permanente pilot programs demonstrate 40% throughput gains for US outpatient surgery chains.
- Plasma Technology:Arc gasification at 3000–7000°C achieving mercury and dioxin destruction impossible through thermal oxidation. Commercial deployment advances where EU Industrial Emissions Directive limits tighten.
Incineration dominates installed base; plasma technology climbs the fastest on regulatory-driven replacement.
End User:
Generator scale determines whether facilities self-manage treatment or outsource to permitted haulers.
- Hospitals:Large acute-care facilities generating 10–15% of total medical waste volume. US health system procurement centralization through Premier and Vizient GPOs bundles waste services with linen and environmental contracts.
- Clinics:Outpatient and ambulatory surgical centers facing mandatory exposure control plans under OSHA Bloodborne Pathogens Standard. Smaller French clinics lacking IT infrastructure consolidate contracts with national logistics operators for ANSM compliance.
- Laboratories:Diagnostic and research facilities producing chemical and biological waste streams. Pharmaceutical testing labs in Switzerland and Singapore generate specialized cytotoxic residues.
- Long-term Care Facilities:Nursing homes and assisted living centers with lower infectious waste ratios but steady pharmaceutical discard volumes. California and Washington extended producer responsibility laws create reverse-logistics requirements for controlled substance destruction.
Hospitals anchor revenue concentration; clinics are gaining share fastest on outsourcing conversion.
Service Type:
Recurring revenue stickiness varies dramatically across the value chain, with collection and transportation outperforming disposal margins.
- Collection:Scheduled or on-demand pickup of containerized waste from point of generation. Stericycle's national US infrastructure leverages density for route optimization.
- Transportation:DOT-regulated hauling with documented chain-of-custody protocols. EU Waste Framework Directive traceability mandates extend generator liability through final destruction.
- Disposal:Terminal treatment through permitted incineration, autoclaving, or alternative technologies. Veolia's dedicated medical waste incinerators in Germany command premium pricing for mercury and dioxin compliance.
- Recycling:Recovery of plastics, metals, and pharmaceutical packaging materials. Clean Harbors competes in industrial-scale chemical disposal for manufacturing byproducts.
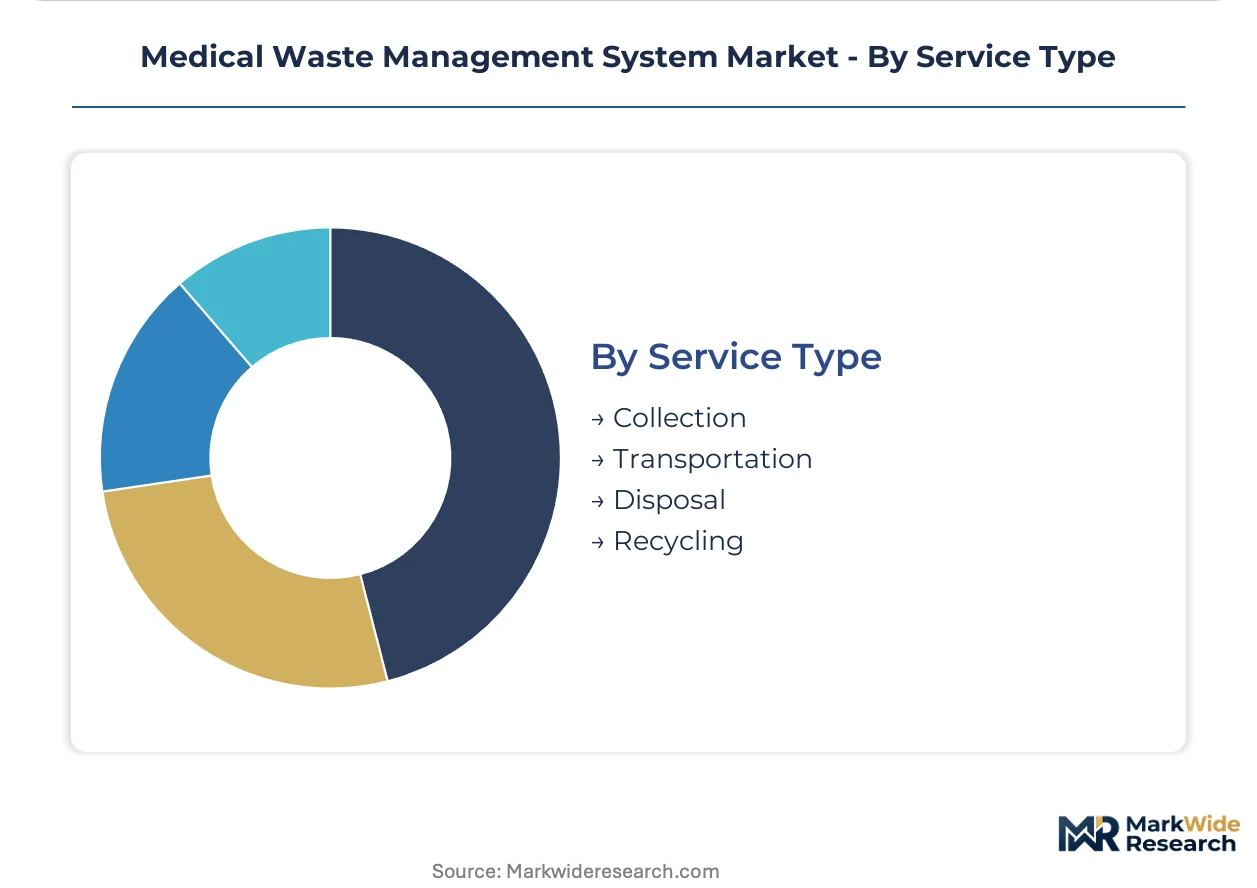
Collection and transportation lock in recurring revenue; recycling captures the steepest expansion trajectory on sustainability pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports integrated autoclave-logistics bundles to neighboring EU member states facing tightened traceability mandates. France and Poland absorb cross-border treatment capacity as generator liability chains extend.
United States
Hospital procurement centralization through Premier and Vizient GPOs compresses vendor relationships into multi-year bundled contracts. OSHA Bloodborne Pathogens Standard enforcement drives outpatient surgical center outsourcing to certified haulers. Texas and Florida metropolitan corridors concentrate HCA and Tenet facility demand.
Germany
KBA-aligned federal waste ordinances enforce traceability from point-of-generation to final destruction. REMONDIS and Veolia operate dense thermal treatment networks with dedicated medical waste incinerators. Natural gas price volatility compresses margins for combustion operators in the industrial Rhineland.
France
ANSM hospital hygiene circulars mandate electronic waste tracking effective January 2024. Small clinics lacking IT infrastructure consolidate contracts with national logistics operators for compliance data management. Île-de-France acute-care facilities anchor RFID-tagged container deployment.
Singapore
Biologics manufacturing expansion generates cytotoxic waste streams requiring specialized chemical inactivation infrastructure. WHO GMP certification requirements pressure API producers to contract permitted treatment partnerships. Pharmaceutical clusters near Tuas Biomedical Park drive demand for industrial-scale disposal.
India
CDSCO pharmaceutical manufacturing clusters near Hyderabad and Ahmedabad require WHO-compliant waste treatment for export certification. Biomedical Waste Management Rules enforcement tightens generator accountability across Maharashtra and Gujarat. API producers face GMP audit pressure to upgrade on-site sterilization capacity.
Medical Waste Management System Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory compliance dimensions. The vendor base stratifies between integrated service platforms and equipment fabricators. Three archetypes dominate: national logistics operators with dense pickup infrastructure, regional thermal treatment specialists with permitted incineration assets, and technology licensors selling autoclave and microwave systems. Competitive moves concentrate on multi-year contract consolidation and on-site equipment placement absorbing generator capital risk.
Within the integrated logistics tier, Stericycle and Clean Harbors exemplify North American archetypes with national route density. Veolia occupies a position representing European thermal treatment concentration with dedicated medical waste incinerator networks. REMONDIS SE & Co. KG anchors German-speaking market bundling of collection-to-disposal services under KBA-aligned federal compliance frameworks.
| Leading Market Players |
|---|
| Stericycle |
| Clean Harbors |
| Veolia |
| Republic Services |
| Waste Management |
| REMONDIS SE & Co. KG |
| Suez |
| Sharps Compliance |
| Daniels Sharpsmart |
| Others |
Supply & Pricing Matrix
Incinerator capacity utilization above 85% in Germany's industrial Rhineland anchors pricing power for thermal treatment operators, while autoclave and microwave system providers compete on equipment financing terms to capture hospital procurement centralization. Scale economies at Veolia's dedicated medical waste incinerators compress per-tonne processing costs, forcing mid-sized competitors to absorb generator capital risk through on-site equipment placement or exit high-fixed-cost markets entirely.
Pricing Analysis
Conventional autoclave sterilization commands standard-tier contract rates, while plasma arc gasification systems capture premium pricing for mercury and dioxin destruction where EU Industrial Emissions Directive limits tighten. Three-tier pricing structure across premium, standard, and economy levels separates plasma technology deployments from microwave-autoclave hybrids and basic steam sterilization. Cost compression in thermal treatment is intensifying because natural gas price volatility erodes incinerator margins in Poland and Germany. Small outpatient surgical centers exhibit highest price sensitivity, negotiating per-pickup rates against bundled GPO contracts, while biologics manufacturers in Singapore accept premium chemical inactivation pricing to maintain WHO GMP certification.
Supply Chain Analysis
Container shipping congestion on Asia-Europe trade lanes elevates inbound logistics costs for stainless steel pressure vessels and RFID-tagged waste containers sourced from Chinese fabricators. Manufacturing concentration for autoclave pressure vessels rests on Germany, Italy, and South Korea, while specialized plasma arc electrodes draw from Japanese and US suppliers. Single-source vulnerability for 2450 MHz magnetron components in microwave sterilization systems threatens equipment delivery timelines. Distribution runs through national logistics operators with DOT-permitted hauling fleets, consolidating collection density before handoff to permitted treatment facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified biomedical equipment technicians capable of steam sterilizer validation and EPA compliance documentation represent the critical skill gap constraining mid-sized service provider expansion. Incumbents and entrants alike compete for this scarce capability base as hospital procurement centralization accelerates.
For Market Incumbents: Shield route density advantages in Texas and Florida metropolitan corridors by absorbing capital risk for on-site microwave system placement at HCA and Tenet facilities, denying regional haulers volume footholds. Lock in multi-year GPO contracts with Premier and Vizient before plasma technology costs decline sufficiently to disrupt standard-tier pricing. Prioritize backward integration into RFID-tagged container manufacturing to capture ANSM electronic tracking mandate value pools in France.
For New Entrants and Emerging Players: Lead with specialized chemical inactivation partnerships targeting CDSCO-registered API producers near Hyderabad and Ahmedabad, where WHO GMP audit pressure outstrips local treatment capacity. Capture small French clinic consolidation demand by bundling cloud-based manifest systems with collection logistics, addressing IT infrastructure gaps that block ANSM compliance. Position on microwave-autoclave hybrid systems for US outpatient surgery chains seeking faster throughput without plasma capital intensity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among national logistics operators with dense pickup infrastructure and documented chain-of-custody protocols, generating sticky multi-year contracts that equipment fabricators cannot replicate. Long-term viability favors platforms integrating collection, transportation, and permitted disposal under single liability chains. Monitor state-level pharmaceutical take-back mandate expansion as the inflection signal for reverse-logistics revenue pool emergence.
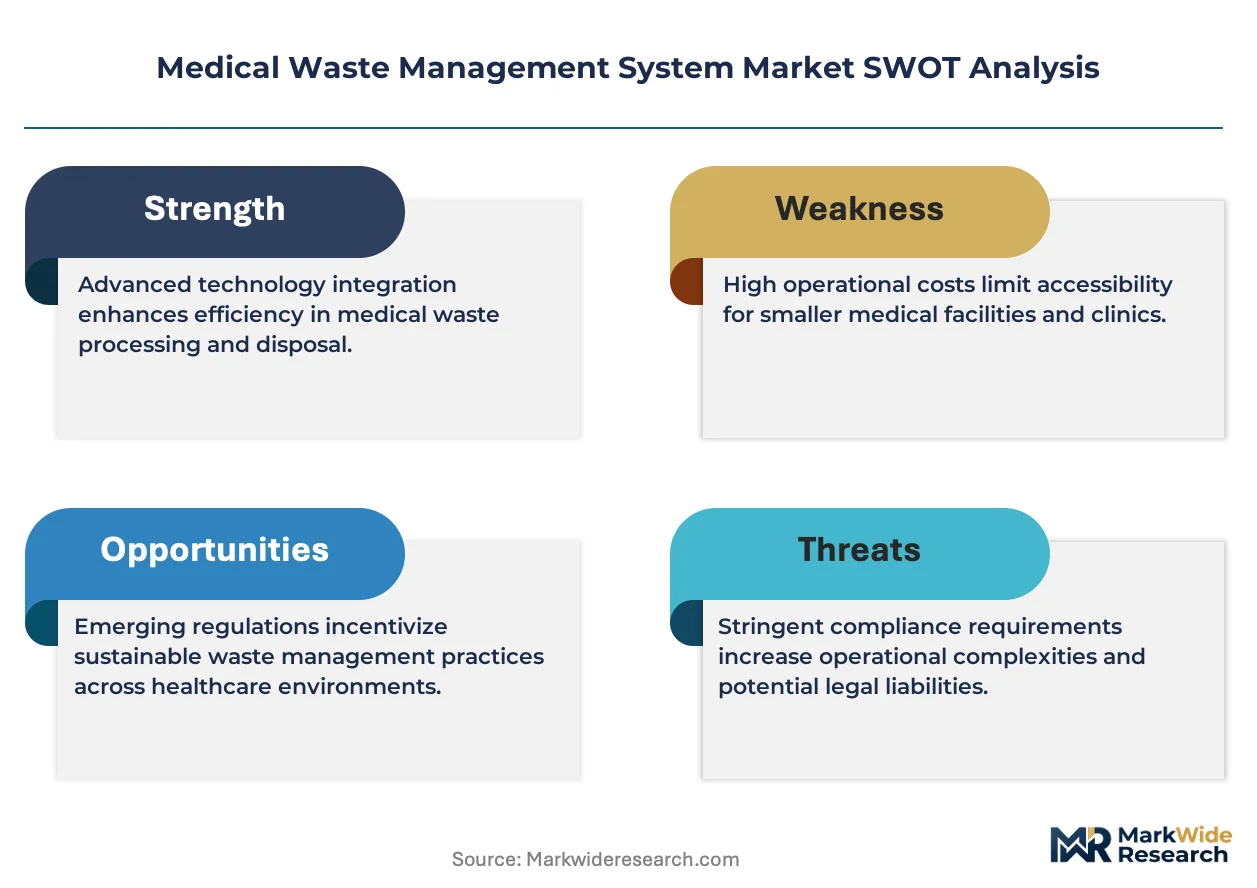
| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Equipment Placement | Absorbs generator capital risk while locking in exclusive collection contracts under OSHA compliance frameworks. |
| RFID-Tagged Container Deployment | Captures ANSM electronic tracking mandate value pools across French acute-care and clinic consolidation. |
| Plasma Technology Commercialization | Commands premium pricing where EU Industrial Emissions Directive dioxin limits tighten beyond thermal oxidation capability. |
| Reverse-Logistics Infrastructure Buildout | Positions for California and Washington extended producer responsibility laws creating controlled substance destruction revenue. |
| Chemical Inactivation Partnership | Secures WHO GMP-compliant treatment capacity for Singapore biologics manufacturers facing cytotoxic waste stream growth. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical equipment technicians, GPO contracts specialists, and EPA compliance officers; and secondary validation against OSHA enforcement databases, EU Waste Framework Directive implementation reports, FDA 510(k) sterilization equipment filings, and hospital capital expenditure disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers produced volume and value estimates.
Across the projection horizon, the analytical framework modeled demand by product type, treatment technology, generator scale, and service tier, with regional regulatory cluster overlays for US, Germany, France, and Singapore. CAGRs derived from equipment replacement cycle compression, outsourcing conversion rates, and permitted capacity expansion timelines. Forecast inputs incorporated natural gas price volatility scenarios for thermal treatment margins and microwave sterilization throughput benchmarks from Sutter Health and Kaiser Permanente pilot programs.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement intensity, EU traceability mandate adherence, or hospital procurement centralization trajectories would require recalibration. Forecasts reflect assumptions regarding permitting timeline stability, energy cost normalization, and technician certification pipeline expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Vacuum Waste Systems Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
PET Recycling Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
Europe Plastic Waste Management Market