
 Global Waste Disposal Equipment Market | 2026-2036
Global Waste Disposal Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waste Disposal Equipment Market Foresight
The waste disposal equipment sector is pivoting between premium automated sorting lines and commodity compaction fleets as capital budgets fragment across mature and emerging economies. Wastequip leverages its North American manufacturing scale to dominate the standard container and compactor segment. TOMRA Systems ASA sustains technology leadership through sensor-based optical sorting platforms that command pricing premiums. Steinert GmbH specializes in magnetic and induction sorting systems for complex metal recovery streams.
Waste disposal equipment encompasses machinery engineered to reduce volume, separate materials, or neutralize waste streams through mechanical force, thermal oxidation, or biological decomposition, typically operating at throughput rates from one to over fifty tons per hour depending on application scale. The primary industrial purpose centers on enabling regulatory-compliant material diversion while minimizing landfill dependency and operational labor intensity. Shredders and compactors anchor the product mix in mature markets where replacement cycles and rental fleet turnover generate steady revenue. Thermal incineration systems capture margin concentration in biomedical and hazardous waste applications where emission compliance thresholds are most stringent. Mechanical sorting technology leads volume deployment, though optical and AI-augmented separation modules represent the fastest-expanding capability layer as contamination standards tighten.
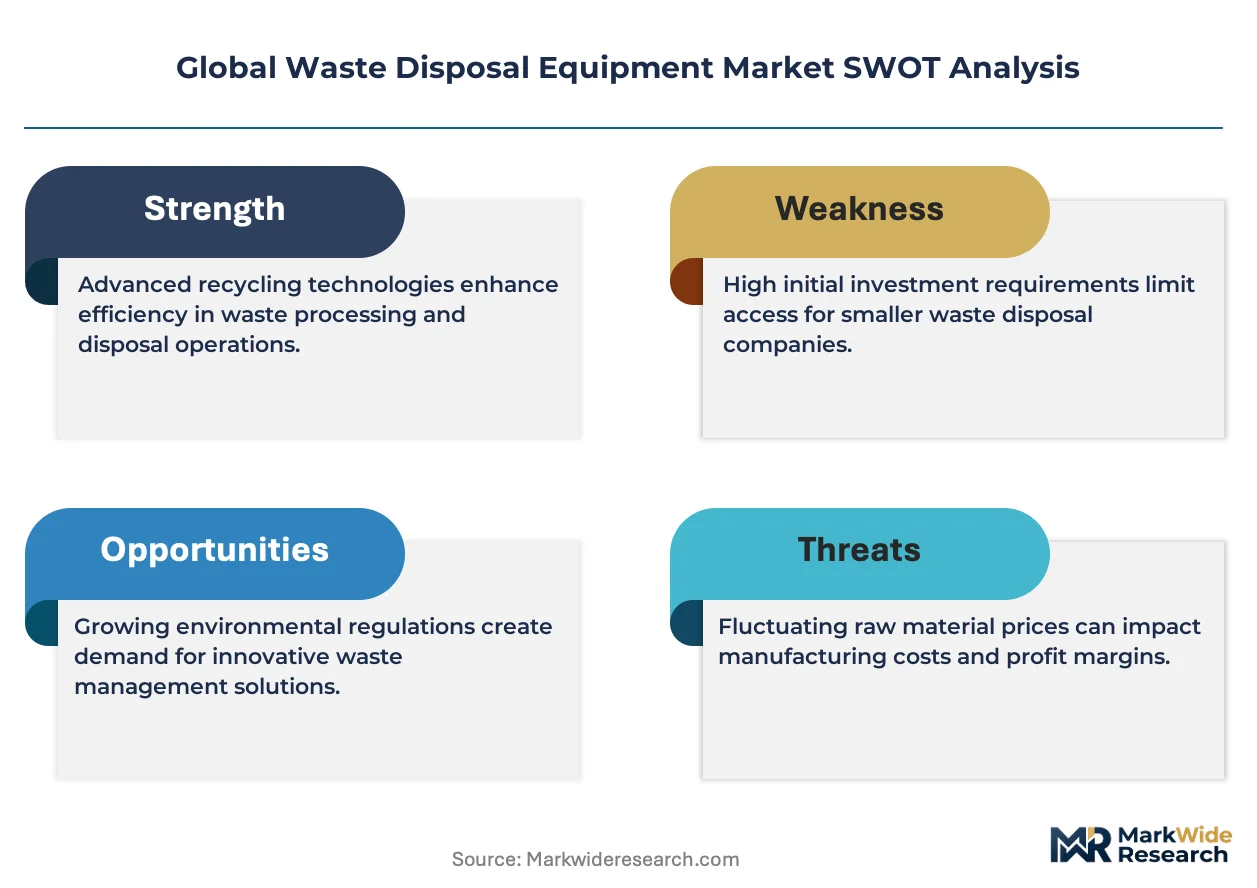
The EPA enforces landfill diversion targets and emission limits that directly shape equipment specification requirements across US municipal procurement. EMA and REACH frameworks in Europe mandate material traceability and hazardous substance controls that elevate capital costs for thermal and biological processing units. China's MEE administers dual carbon compliance timelines that accelerate retirement of uncontrolled incineration assets. Stakeholders must monitor regulatory divergence between carbon-accounting jurisdictions to anticipate which equipment configurations will retain resale value and financing eligibility.
Market Dynamics
The waste disposal equipment sector is bifurcating between high-throughput automated sorting infrastructure demanded by EU landfill diversion mandates and cost-optimized compaction fleets serving emerging municipal budgets, with capital allocation decisions increasingly tied to carbon-accounting eligibility rather than pure throughput economics.
Growth Catalysts
- EU Green Deal landfill diversion targets:Germany and France are accelerating procurement of optical sorting lines to meet 2035 zero-landfill commitments, forcing incumbent fleet replacements.
- China's dual carbon compliance timelines:MEE enforcement is retiring uncontrolled incineration assets in Guangdong and Jiangsu provinces, opening demand for emission-compliant thermal systems.
- Biomedical waste stream expansion:Post-pandemic healthcare infrastructure buildouts in Brazil and India are driving hazardous-capable shredder and autoclave deployments.
Market Restraints
- Steel and rare-earth magnet cost volatility:Magnetic separator manufacturers face margin compression from neodymium price swings and European energy-intensive steel supply constraints.
- Optical sensor supply concentration:Near-infrared and X-ray detector modules concentrate among Japanese and German component suppliers, creating procurement bottlenecks for sorting system integrators.
- REACH substance restriction compliance:ECHA restrictions on flame retardants and heavy metals in electrical components extend certification timelines for thermal processing equipment by 8-14 months.
Strategic Opportunities
- India's Smart Cities Mission waste infrastructure:Municipal corporations in Maharashtra and Tamil Nadu are tendering integrated material recovery facilities with 15-20 year O&M contracts.
- AI-augmented contamination detection:Machine vision training on heterogeneous waste streams is converging with robotic pick-and-place systems to enable single-stream MRF retrofits.
- Japan's carbon-neutral port initiatives:METI funding for maritime waste-to-energy clusters is creating demand for high-capacity shredders and RDF preparation lines in coastal industrial zones.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of sensor-based sorting systems requires cross-trained personnel in pneumatics, machine vision, and PLC diagnostics that vocational pipelines have not scaled to match deployment rates.
- Legacy analog compactor fleet integration:Telematics retrofitting of rental container fleets with weight sensors and route-optimization hardware faces interoperability gaps with 1990s-era hydraulic control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waste Disposal Equipment Market |
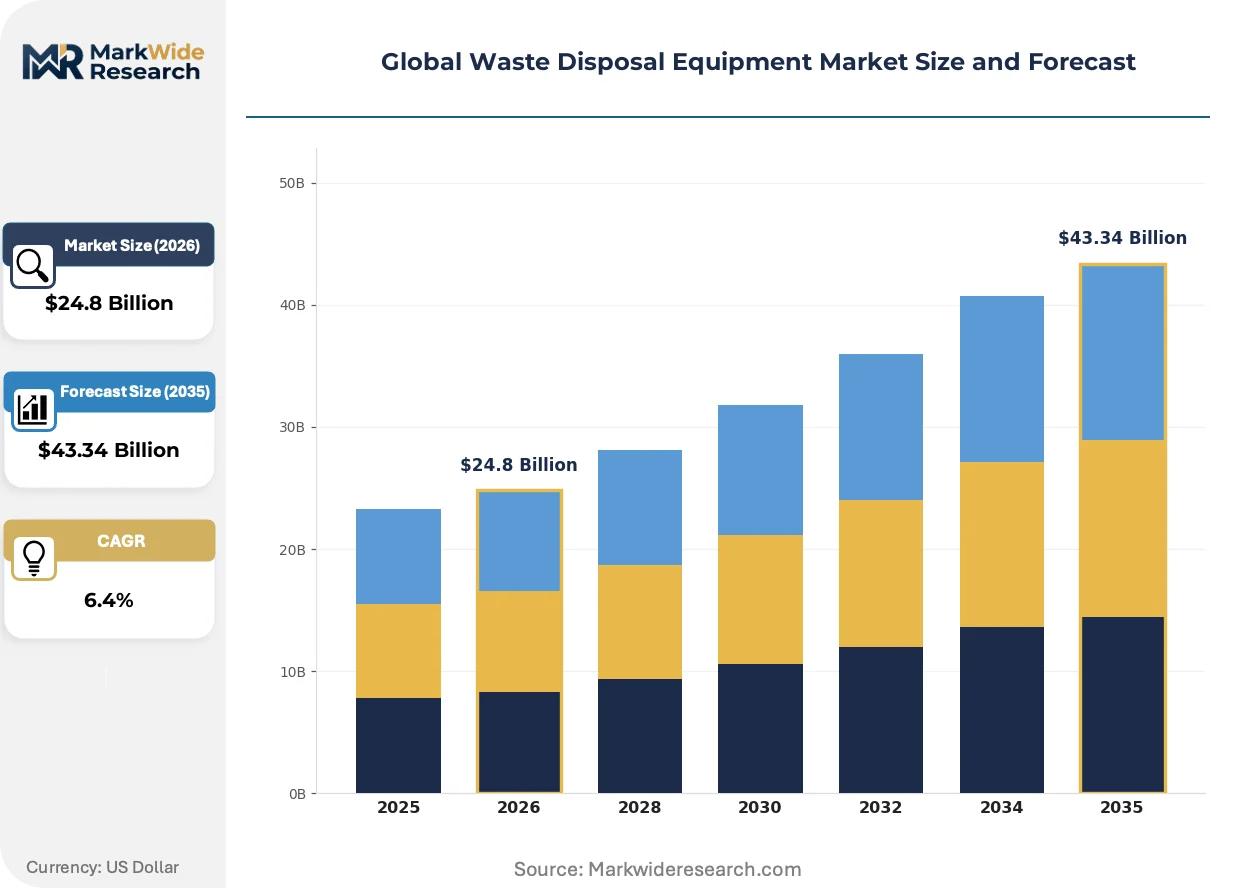
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compactors, Shredders, Incinerators, Balers, Crushers Technology: Mechanical, Hydraulic, Thermal, Pneumatic, Biological Application: Municipal Solid Waste, Construction Waste, Biomedical Waste, Electronic Waste, Agricultural Waste End User: Waste Management Companies, Recycling Facilities, Manufacturing Plants, Research Institutions, Government Agencies |
| Companies Covered | Wastequip, Dover Corporation, TOMRA Systems ASA, CP Manufacturing Inc., Bollegraaf Recycling Solutions, Terex Corporation, Caterpillar Inc., Metso Outotec, Steinert GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waste Disposal Equipment Market Shifts & Advancements
Equipment intelligence layers are migrating from standalone optical modules to integrated AI-orchestrated systems that dynamically adjust mechanical separation parameters based on real-time material composition feedback, compressing the gap between laboratory sorting efficiency and operational throughput.
Sensor fusion architectures combining near-infrared spectroscopy with X-ray transmission and 3D laser profiling are converging with cloud-based material databases to enable recognition of multi-layer packaging and composite materials previously routed to landfill. Nordic MRF operators in Sweden and Denmark are deploying these configurations at 25-40 ton per hour throughputs. The technology is converging with robotic sorting arms to reduce manual picking stations by 60-75 percent in new facility designs.
EPA enforcement of updated New Source Performance Standards for municipal waste combustors is mandating continuous emission monitoring systems and selective catalytic reduction retrofits that add 15-25 percent to thermal system capital costs. US medical waste incinerator operators in Texas and Florida are absorbing these upgrades through 7-10 year equipment financing structures. The regulation is compressing operating margins for sub-scale facilities below 50 ton per day capacity, accelerating consolidation.
Rental and leasing penetration for compaction and container equipment is displacing outright purchase in North American municipal and retail waste streams, with fleet management providers bundling preventive maintenance and telematics analytics into per-ton or per-pickup pricing. Grocery and big-box retail chains in California and New York are adopting these models to convert fixed equipment costs to variable operating expenses aligned with waste diversion performance metrics.
Global Waste Disposal Equipment Market Segmentation
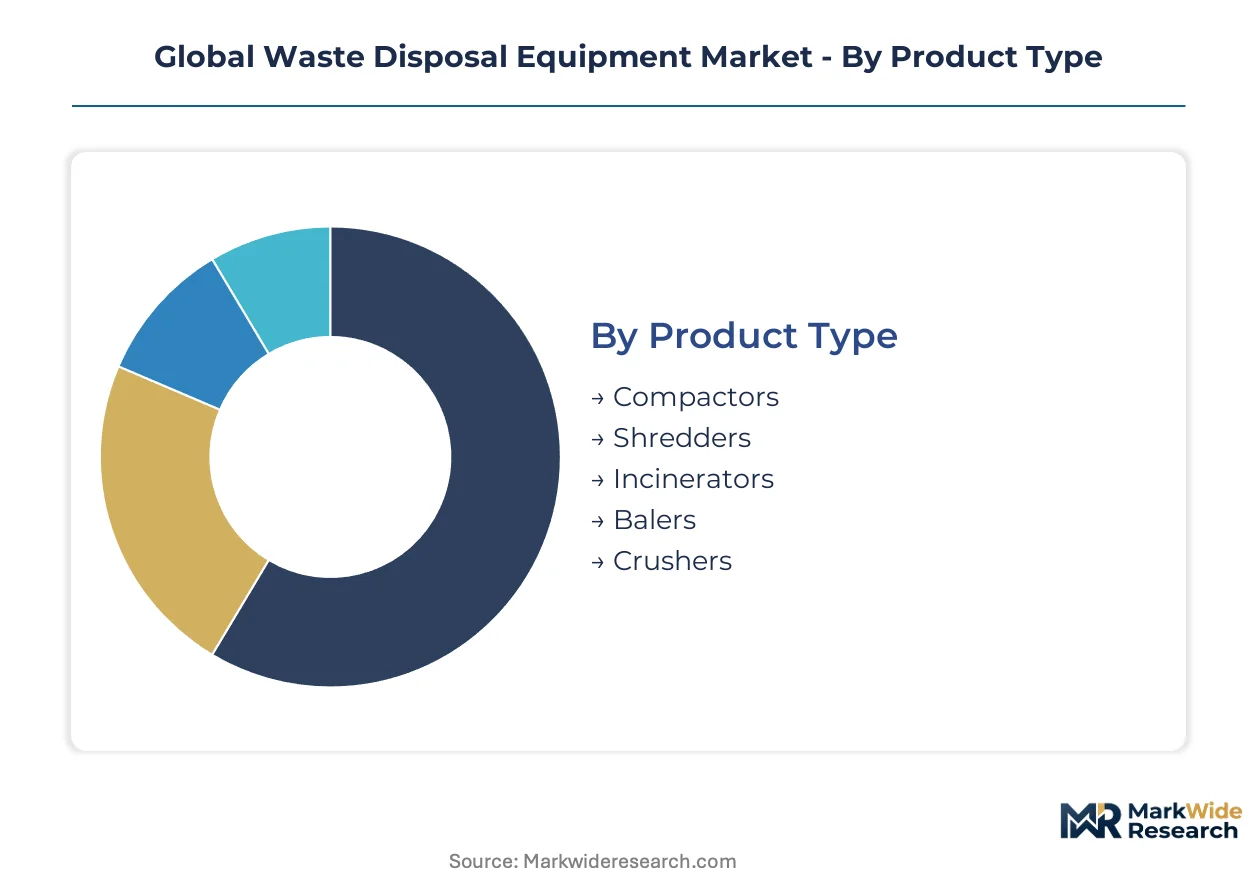
Waste disposal equipment segmentation reveals divergent capital allocation patterns between high-volume commodity machinery and precision-engineered premium systems. Equipment specification varies dramatically across waste stream chemistry, contamination tolerance, and regulatory compliance thresholds.
Product Type:
Volume deployment concentrates in standardized compaction fleets, while premium capture flows to emission-controlled thermal and precision shredding systems.
- Compactors:Stationary and self-contained units compress mixed waste streams through hydraulic force to achieve 4:1 to 6:1 volume reduction ratios. Demand clusters in North American retail and grocery chains where California and New York municipalities mandate commercial waste diversion tracking. Fleet leasing models now dominate procurement, converting capital expenditure to per-ton operating metrics.
- Shredders:High-torque rotary and hammer-mill configurations reduce particle size for downstream sorting or fuel preparation. Germany and Japan lead deployment of AI-augmented shredding lines that adjust blade speed based on real-time material density feedback from integrated sensor arrays.
- Incinerators:Controlled thermal oxidation systems for biomedical and hazardous streams operate at 850°C to 1,200°C with continuous emission monitoring. EPA New Source Performance Standards compliance adds 15-25 percent to capital costs for US medical waste operators.
- Balers:Horizontal and vertical compression units bundle recyclables into mill-ready densities. Paper and OCC recovery facilities in Nordic circular-economy clusters specify high-automation balers with wire-tying integration.
- Crushers:Jaw, cone, and impact configurations reduce construction and demolition debris to specified aggregate gradations. China's MEE enforcement of construction waste diversion mandates is accelerating mobile crusher deployment in Guangdong province.
Mature deployment sits with compactors and balers in established recycling infrastructure. Newer deployment is concentrated in sensor-integrated shredders and emission-compliant incinerators.
Technology:
Mechanical systems anchor installed base economics, while thermal and biological platforms command margin premiums in regulated waste streams.
- Mechanical:Conveyance, screening, and density separation through gravity, ballistic, and inertial forces. Municipal material recovery facilities in Brazil and India specify mechanical front-ends for 15-20 year O&M contract stability.
- Hydraulic:Fluid-power actuation for high-force compaction, shearing, and material densification. European energy-intensive steel supply constraints are elevating cylinder and pump replacement costs for German and French fleet operators.
- Thermal:Oxidation, pyrolysis, and gasification for pathogen destruction and energy recovery. Japan's METI-funded carbon-neutral port initiatives are driving RDF preparation line procurement in coastal industrial zones.
- Pneumatic:Vacuum and pressure conveyance for lightweight fraction transport and dust containment. Optical sorting pre-concentration stages in Swedish MRFs integrate pneumatic reject handling.
- Biological:Aerobic and anaerobic decomposition for organic waste stabilization and biogas capture. REACH substance restrictions on electrical components extend certification timelines for biological processing equipment by 8-14 months.
Mechanical and hydraulic systems retain the largest installed base. Thermal configurations are climbing the fastest as landfill diversion mandates tighten across EU and East Asian jurisdictions.
Application:
Municipal solid waste commands equipment volume, while biomedical and electronic waste streams justify specialized capital investment.
- Municipal Solid Waste:Mixed residential and commercial streams requiring front-end sorting, compaction, and transfer station optimization. EU Green Deal zero-landfill commitments are forcing German and French optical sorting line procurement.
- Construction Waste:Concrete, asphalt, wood, and gypsum debris processing for aggregate recovery and landfill diversion. China's dual carbon compliance timelines are retiring uncontrolled processing assets in Jiangsu province.
- Biomedical Waste:Sharps, pathological, and pharmaceutical residues requiring autoclave, shredder, or incinerator neutralization. Post-pandemic healthcare infrastructure buildouts in Brazil and India are expanding hazardous-capable equipment demand.
- Electronic Waste:Circuit boards, batteries, and mixed plastics demanding specialized metal recovery and precious element separation. Complex metal recovery streams in Germany leverage magnetic and induction sorting from specialized equipment providers.
- Agricultural Waste:Crop residue, manure, and food processing byproducts for compost or anaerobic digestion feedstock. India's Smart Cities Mission integrated material recovery facilities are incorporating agricultural co-processing capacity in Maharashtra.
Conventional deployment centers on municipal solid waste compaction and transfer. Emerging deployment is concentrating in electronic waste precision separation and biomedical thermal treatment.
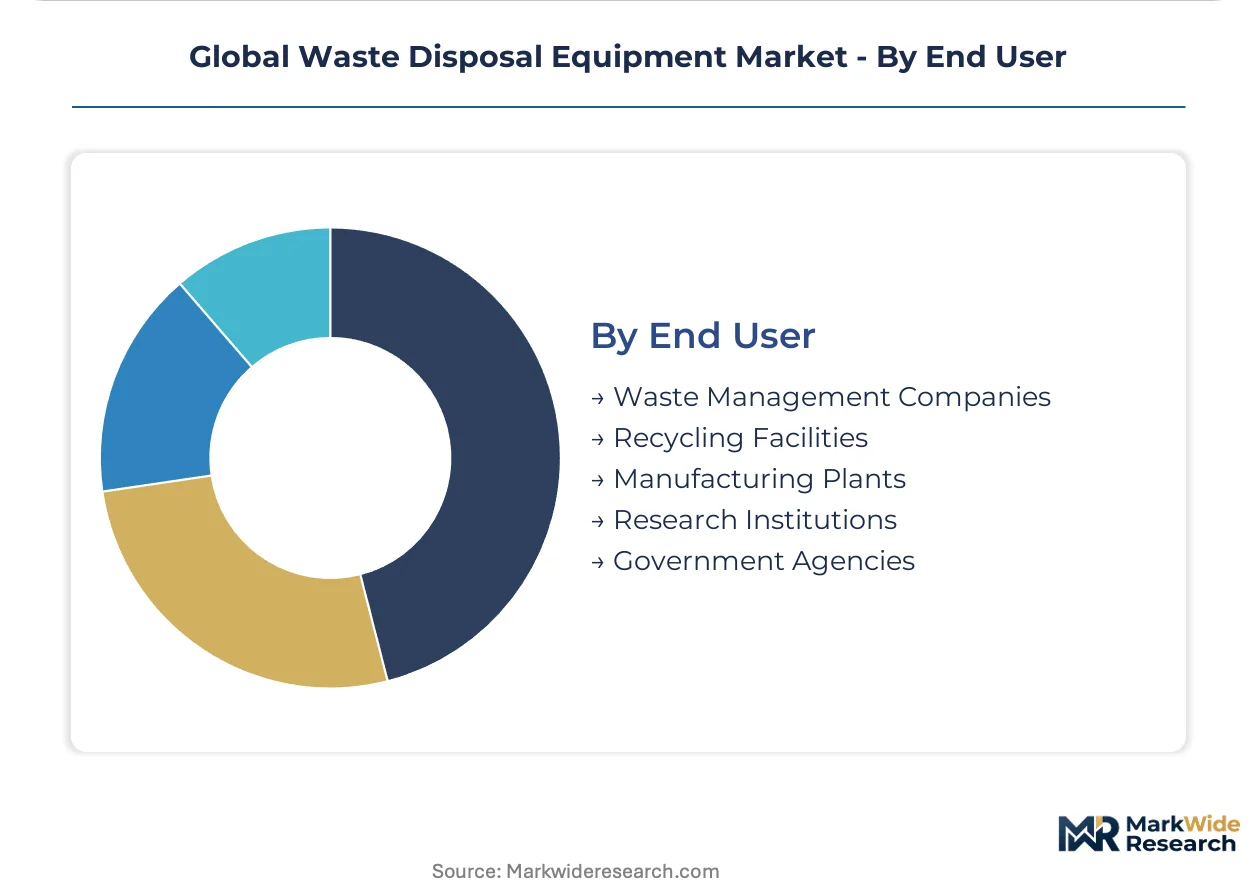
End User:
Waste management companies consolidate fleet purchasing power, while recycling facilities drive technology specification for material purity.
- Waste Management Companies:Integrated collection, transfer, and disposal operators specifying standardized container and compactor fleets. North American rental fleet telematics retrofitting faces interoperability gaps with 1990s-era hydraulic architectures.
- Recycling Facilities:Material recovery and commodity preparation operations requiring optical sorting, eddy current separation, and baling precision. Nordic operators in Sweden and Denmark deploy sensor fusion architectures at 25-40 ton per hour throughputs.
- Manufacturing Plants:Industrial waste generators seeking closed-loop scrap recovery and packaging waste densification. Japanese automotive suppliers specify high-capacity shredders for production scrap-to-RDF conversion.
- Research Institutions:Pilot-scale testing and technology validation facilities requiring modular, reconfigurable equipment platforms. University partnerships in Tamil Nadu support India's Smart Cities Mission tender development.
- Government Agencies:Municipal procurement authorities and environmental regulators setting equipment standards and fleet replacement schedules. EPA enforcement shapes specification requirements across US municipal procurement cycles.
Established procurement flows through waste management companies and recycling facilities. Government agency direct purchasing is gaining share fastest as public-sector circular economy mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta industrial corridor anchors procurement velocity for emission-compliant thermal systems as China's MEE enforces dual carbon retirement timelines across Jiangsu and Zhejiang provinces.
United States
EPA New Source Performance Standards enforcement is mandating continuous emission monitoring retrofits for medical waste incinerators across Texas and Florida. California and New York municipalities drive commercial compactor fleet leasing with mandated diversion tracking. The Southeast manufacturing belt absorbs telematics retrofitting costs for legacy hydraulic container fleets.
Germany
EU Green Deal zero-landfill commitments are accelerating optical sorting line procurement in Bavaria and North Rhine-Westphalia. ECHA REACH substance restrictions extend certification timelines for thermal processing equipment by 8-14 months. The Ruhr industrial cluster hosts dense concentrations of magnetic separator fabrication facing neodymium cost volatility.
China
MEE dual carbon compliance timelines are retiring uncontrolled incineration assets in Guangdong province. Construction waste diversion mandates accelerate mobile crusher deployment across the Pearl River Delta. State-backed port initiatives in Jiangsu create demand for high-capacity RDF preparation lines in coastal zones.
Japan
METI-funded carbon-neutral port initiatives drive maritime waste-to-energy cluster development in Nagoya and Osaka bays. Automotive suppliers in Aichi prefecture specify production scrap-to-RDF conversion shredders. Kanto region MRF operators deploy sensor fusion architectures at 25-40 ton per hour throughputs.
India
Maharashtra and Tamil Nadu municipal corporations tender integrated material recovery facilities under Smart Cities Mission 15-20 year O&M contracts. Post-pandemic healthcare infrastructure buildouts expand hazardous-capable shredder demand in Bengaluru and Hyderabad. University partnerships in Tamil Nadu support tender development for modular equipment platforms.
Global Waste Disposal Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology intensity, with sensor-integrated sorting systems commanding pricing multiples over standard compaction fleets. The vendor base stratifies between North American manufacturing scale, European precision engineering, and Nordic optical technology leadership. Three archetypes dominate: integrated waste service conglomerates, specialized sorting technology houses, and heavy equipment diversifiers. Consolidation pressure concentrates among sub-scale thermal operators below 50 ton per day capacity, while strategic partnerships between equipment OEMs and MRF operators reshape procurement channels.
Within the precision-engineering tier, Steinert GmbH and TOMRA Systems ASA exemplify technology leadership through magnetic induction and optical sorting specializations respectively. Wastequip anchors the North American commodity segment through manufacturing scale in standardized container and compactor production. Dover Corporation represents diversified industrial conglomerate positioning with waste equipment holdings nested within broader infrastructure portfolios.
| Leading Market Players |
|---|
| Wastequip |
| Dover Corporation |
| TOMRA Systems ASA |
| CP Manufacturing Inc. |
| Bollegraaf Recycling Solutions |
| Terex Corporation |
| Caterpillar Inc. |
| Metso Outotec |
| Steinert GmbH |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up fleet operators in North America and Europe exercise pricing discipline through captive leasing platforms that bundle maintenance telemetry with per-ton equipment charges, compressing margins for independent compactor distributors while locking in long-term service revenue streams.
Pricing Analysis
Value-based pricing anchored to throughput guarantees and uptime commitments dominates optical sorting and AI-augmented separation systems, with TOMRA and Steinert commanding premiums tied to yield recovery rates rather than capital cost alone. Three-tier pricing structure across premium sensor-integrated, standard mechanical, and economy hydraulic tiers reflects certification grade divergence between EU CE-marked emission-compliant units and uncontrolled incineration assets facing retirement. Pricing pressure stems from neodymium magnet cost volatility squeezing magnetic separator margins. Municipal procurement offices exhibit highest price sensitivity, while biomedical waste operators absorbing EPA compliance retrofits show lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Domestic-content mandates in India's Smart Cities Mission and China's MEE enforcement timelines are reshaping sourcing patterns for integrated material recovery facilities, forcing foreign OEMs to localize fabrication or forfeit tender eligibility. Component supply concentrates in Germany for precision optical sensors, Japan for near-infrared detector modules, and China for hydraulic actuation systems. Raw material dependencies span European energy-intensive steel for compaction cylinders, Australian rare-earth concentrates for magnetic separators, and South Korean semiconductor substrates for machine vision processors. Single-source vulnerability runs through Japanese and German optical detector suppliers. Distribution runs through OEM-direct channels for premium sorting systems and rental fleet aggregators for standardized compaction equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-orchestrated sensor fusion is displacing legacy mechanical-only separation lines, compressing replacement cycles and reallocating capital toward integrated robotics platforms.
For Market Incumbents: Anchor service revenue through predictive maintenance telemetry retrofits of legacy hydraulic fleets, converting one-time equipment sales into recurring per-ton contracts. Deepen backward integration into neodymium magnet recycling to defend magnetic separator margins against rare-earth price swings. Prioritize certification pre-clearance under REACH substance restrictions to capture 8-14 month lead times over non-compliant competitors. For New Entrants and Emerging Players: AI-augmented contamination detection modules offer the most penetrable wedge for sub-scale specialists targeting single-stream MRF retrofits in Nordic and Japanese markets. Target India's Maharashtra and Tamil Nadu municipal tenders where 15-20 year O&M contracts reduce incumbent switching costs. Pursue university partnership channels for pilot-scale validation to bypass capital-intensive reference site requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor sub-scale thermal operators below 50 ton per day capacity in Texas and Florida facing EPA New Source Performance Standards compliance cliffs. Long-term viability hinges on emission-control retrofit bundling capability and regional consolidation execution. Watch for MEE enforcement acceleration in Guangdong and Jiangsu provinces as inflection signal for Chinese thermal asset replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Combines NIR spectroscopy with X-ray transmission to enable multi-layer packaging recognition at 25-40 ton per hour Swedish MRF throughputs. |
| Telematics Fleet Retrofit Program | Converts 1990s-era hydraulic container architectures to route-optimization hardware for California and New York diversion tracking mandates. |
| Domestic Manufacturing Joint Venture | Secures Smart Cities Mission tender eligibility through localized fabrication partnerships in Maharashtra and Tamil Nadu corridors. |
| Rare-Earth Magnet Recycling Scale-Up | Captures neodymium recovery from end-of-life separators to hedge supply volatility facing German magnetic equipment fabricators. |
| Emission Control Certification Pre-Clearance | Accelerates REACH-compliant thermal equipment market entry ahead of 8-14 month ECHA restriction timelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with MRF operations directors, municipal procurement officers, OEM aftermarket service heads, and hydraulic fleet maintenance technicians. EPA enforcement databases, EU ECHA restriction updates, and China MEE compliance bulletins provided regulatory trajectory validation. Bottom-up equipment shipment tallies by product category reconciled against top-down waste generation and diversion rate projections across the analysis window.
Data-stream reconciliation between vendor order backlogs, tender award announcements, and import-export trade flows informed segmentation modeling across product type, technology platform, application stream, and end-user archetype dimensions. CAGRs derived from weighted regression of historical replacement cycles against regulatory mandate acceleration curves. Industry-specific forecast inputs incorporated neodymium price volatility indices and EU landfill diversion timeline enforcement probability.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, abrupt rare-earth export quota revisions, and pandemic-scale healthcare waste surge events. Forecasts reflect documented assumptions regarding MEE and EPA enforcement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
Middle-East and Africa Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Recycled Ocean Plastics Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
Scrap Metal Recycling Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
Qatar Waste Management Market
Waste Management & Pollution Control
Incinerator Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Waste Management Market