
 Asia-Pacific Waste Management Market | 2026-2036
Asia-Pacific Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Waste Management Market Insights
Municipal governments are rotating procurement toward integrated service providers capable of handling collection through final treatment. Veolia Environmental Services leverages its incineration technology leadership across Southeast Asian urban contracts. Cleanaway Waste Management anchors Australasian market share through landfill remediation and resource recovery infrastructure. Daiseki Co. Ltd specializes in industrial waste treatment, sustaining margins via chemical processing capabilities that smaller competitors cannot replicate.
Asia-Pacific waste management encompasses the collection, transportation, treatment, and disposal of municipal solid waste, industrial byproducts, hazardous materials, and electronic scrap through mechanical, thermal, biological, or containment processes designed to minimize environmental contamination and recover secondary materials. The primary purpose is regulatory compliance with public health standards while extracting energy, metals, and recyclables from discarded material streams. Collection services dominate revenue volume across the region, though treatment and recycling segments capture disproportionate margin pools as tipping fees rise and circular economy policies mature. Hazardous waste and e-waste categories are expanding fastest, driven by electronics manufacturing clusters and tightening disposal restrictions under multiple national frameworks.
China's Ministry of Ecology and Environment enforces dual carbon targets that cap landfill methane emissions and mandate waste-to-energy capacity additions. India's Central Pollution Control Board implements Extended Producer Responsibility rules for plastic and e-waste, forcing brand owners to fund reverse logistics networks. Japan's METI maintains strict industrial waste tracking through manifest systems that create compliance-driven demand for certified treatment operators. Stakeholders must monitor how cross-border waste import bans and domestic processing subsidies reshape competitive boundaries between local specialists and multinational service platforms.
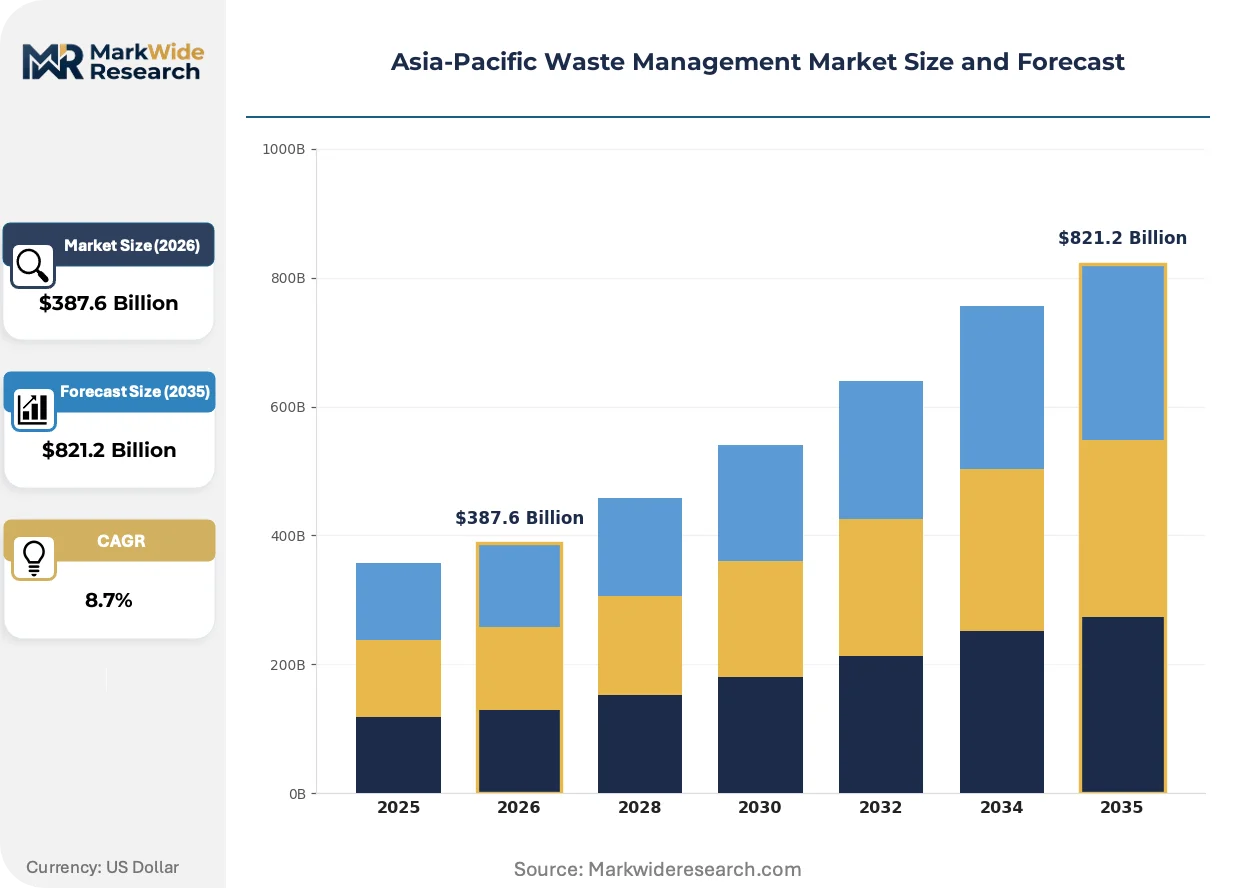
Market Dynamics
China's dual carbon goals and India's Extended Producer Responsibility mandates are compressing landfill diversion timelines, forcing municipal governments and industrial generators to accelerate procurement of integrated treatment infrastructure before compliance deadlines tighten further.
Growth Catalysts
- Extended Producer Responsibility frameworks:India's Central Pollution Control Board mandates brand owners to fund reverse logistics for plastic and e-waste, creating guaranteed revenue streams for certified collection networks.
- Urban density concentration:Southeast Asian municipal governments are expanding outsourced collection contracts as metropolitan populations exceed infrastructure carrying capacity in Jakarta, Manila, and Ho Chi Minh City.
- Waste-to-energy technology deployment:China's Ministry of Ecology and Environment caps landfill methane emissions, driving capacity additions for incineration and anaerobic digestion plants across provincial industrial zones.
Market Restraints
- Capital intensity for hazardous treatment:Chemical processing facilities require specialized containment infrastructure that locks up capital for 15-20 year depreciation cycles.
- Feedstock supply fragmentation:Collection networks across Indonesia, Philippines, and Vietnam remain dominated by informal sector operators, creating feedstock quality inconsistency for mechanized sorting plants.
- Cross-border waste import prohibitions:China's National Sword policy and subsequent ASEAN restrictions have eliminated offshore disposal options for domestic generators lacking local treatment capacity.
Strategic Opportunities
- Industrial corridor expansion:Gujarat and Maharashtra in India exhibit hazardous waste generation rates that substantially exceed installed chemical treatment capacity.
- Digital manifest integration:Japan's METI industrial waste tracking systems create compliance-driven demand for software-enabled logistics platforms that smaller competitors cannot replicate.
- Electronics manufacturing cluster proximity:E-waste collection networks positioned near semiconductor fabrication facilities in South Korea and Taiwan capture high-value precious metal recovery streams.
Industry Challenges
- Specialized technician scarcity:Chemical processing and emissions control operations require certified operators that vocational training systems in Vietnam, Indonesia, and Philippines have not scaled to produce.
- Legacy landfill remediation liability:Australasian operators face decades-long post-closure monitoring obligations that distort capital allocation toward liability management rather than new capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Waste Management Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Disposal, Treatment, Recycling Waste Type: Municipal Solid Waste, Industrial Waste, Hazardous Waste, E-Waste Technology: Mechanical Sorting, Thermal Treatment, Biological Treatment, Landfilling End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Veolia Environmental Services, Suez Environment S.A., Waste Management Inc., Cleanaway Waste Management, Daiseki Co. Ltd, BRISEA Group, Inc., Remondis AG & Co. KG, Hitachi Zosen Corporation, Stericycle Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Waste Management Market Trends and Innovations
Mechanical sorting systems and biological treatment platforms are converging with digital tracking infrastructure, compressing the traditional separation between collection logistics and final material recovery.
Plasma gasification is decomposing complex industrial waste streams at temperatures exceeding 3,000°C, eliminating residual ash disposal requirements. Chemical manufacturers in Japan and South Korea are piloting units for halogenated solvent destruction. This thermal process is decomposing the cost advantage that cement kiln co-processing previously held for hazardous organic waste.
China's Ministry of Ecology and Environment enforces dual carbon targets that cap landfill methane emissions and mandate waste-to-energy capacity additions. Provincial state-owned enterprises must retrofit existing dumpsites with gas capture systems or face operational suspension. Municipal governments in Jiangsu and Zhejiang are responding by accelerating procurement of integrated incineration plants with district heating output.
Buyer consolidation among electronics original equipment manufacturers is compressing vendor qualification timelines for e-waste recovery services. Brand owners in Taiwan and South Korea now mandate single-source accountability across collection, data destruction, and precious metal refining. This procurement compression is most visible in semiconductor supply chains where circular economy commitments require auditable mass balance documentation from tier-one recyclers.
Asia-Pacific Waste Management Market Segmentation
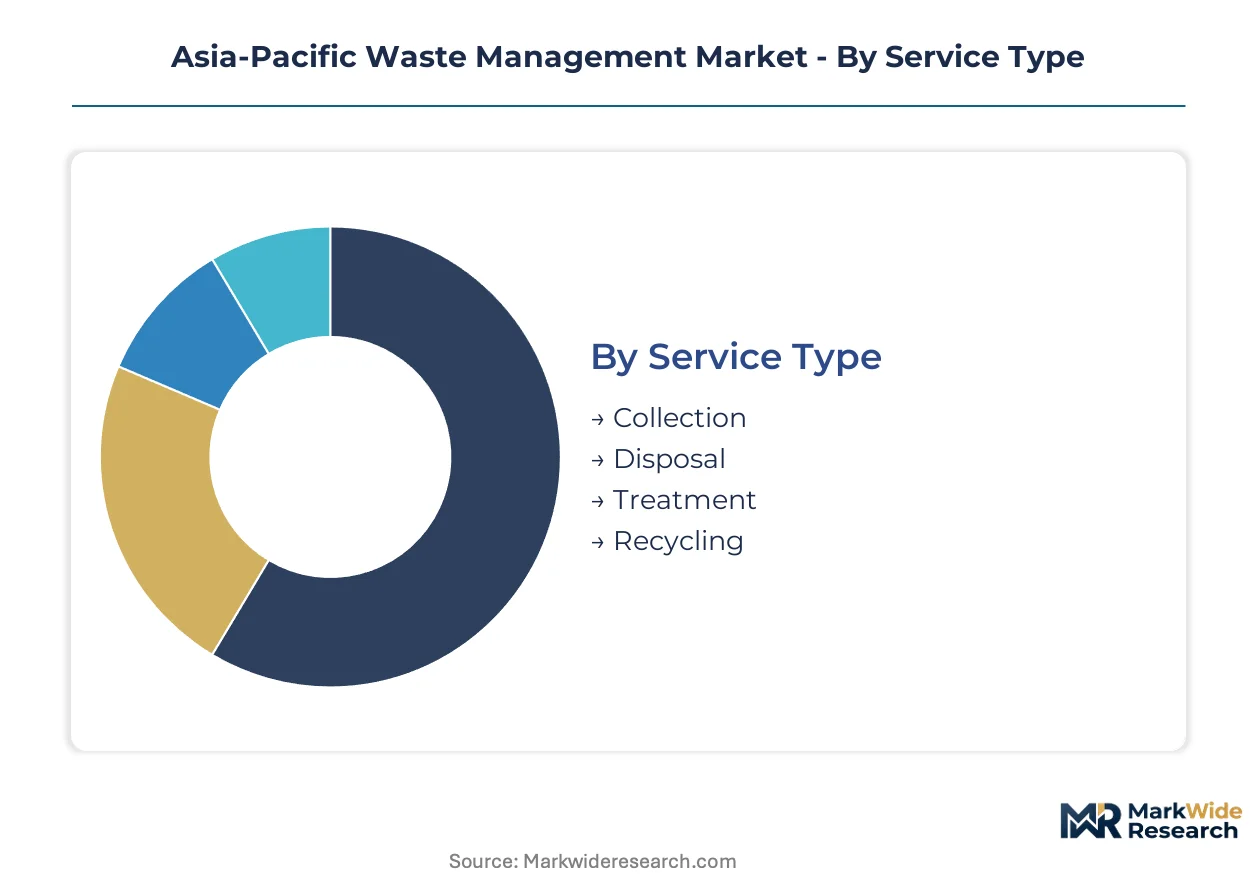
Waste management procurement in Asia-Pacific fragments across service tiers, material hazards, and regulatory compliance obligations. Municipal governments and industrial generators select providers based on feedstock composition, treatment technology, and end-use recovery potential rather than generic service bundling.
Service Type:
Collection faces the strongest substitution pressure from informal sector operators across Southeast Asian urban corridors, while integrated treatment commands premium pricing through regulatory compliance lock-in.
- Collection:Door-to-door and containerized pickup services for municipal and industrial generators. Demand concentrates in Jakarta, Manila, and Ho Chi Minh City where metropolitan density exceeds formal infrastructure capacity and municipalities expand outsourced contracts.
- Disposal:Landfill operations and engineered containment for non-recoverable residuals. India's Central Pollution Control Board landfill diversion mandates are compressing volume growth in Gujarat and Maharashtra industrial corridors.
- Treatment:Chemical processing, stabilization, and neutralization of hazardous streams. Japan's METI manifest tracking systems create compliance-driven demand for certified operators that smaller competitors cannot replicate.
- Recycling:Material recovery facilities and secondary commodity production. China's dual carbon goals under MEE accelerate procurement of integrated sorting infrastructure with district heating output.
Collection anchors the volume base while Treatment gains share at the steepest rate.
Waste Type:
Cost tier differentiation separates high-margin hazardous streams from commoditized municipal flows, with hazardous and e-waste categories capturing disproportionate margin pools.
- Municipal Solid Waste:Residential and commercial discards including organics, paper, and plastics. Collection networks across Indonesia, Philippines, and Vietnam remain dominated by informal sector operators creating feedstock quality inconsistency.
- Industrial Waste:Manufacturing byproducts from chemical, textile, and metallurgical operations. Generation rates in India's Gujarat and Maharashtra industrial corridors substantially exceed installed chemical treatment capacity.
- Hazardous Waste:Flammable, corrosive, toxic, and reactive materials requiring specialized containment. Chemical processing facilities require capital locked up for 15-20 year depreciation cycles.
- E-Waste:Discarded electronics containing precious metals and regulated substances. Semiconductor fabrication clusters in South Korea and Taiwan position collectors for high-value recovery streams.
Municipal Solid Waste anchors the volume base while E-Waste climbs the fastest as electronics manufacturing expands and India's Extended Producer Responsibility mandates tighten.
Technology:
Application maturity varies sharply, with thermal treatment displacing biological platforms for complex industrial streams while mechanical sorting scales for municipal recovery.
- Mechanical Sorting:Automated separation of recyclables using optical, magnetic, and density-based systems. Jiangsu and Zhejiang municipalities accelerate procurement of integrated plants with district heating output.
- Thermal Treatment:Incineration, pyrolysis, and gasification for energy recovery and volume reduction. Plasma gasification pilots in Japan and South Korea decompose halogenated solvents at temperatures exceeding 3,000°C.
- Biological Treatment:Anaerobic digestion and composting for organic fraction stabilization. China's MEE caps on landfill methane emissions drive capacity additions across provincial industrial zones.
- Landfilling:Engineered containment with leachate and gas management systems. Australasian operators face decades-long post-closure monitoring obligations that distort capital allocation.
Landfilling anchors the volume base while Thermal Treatment expands most quickly under carbon reduction mandates.
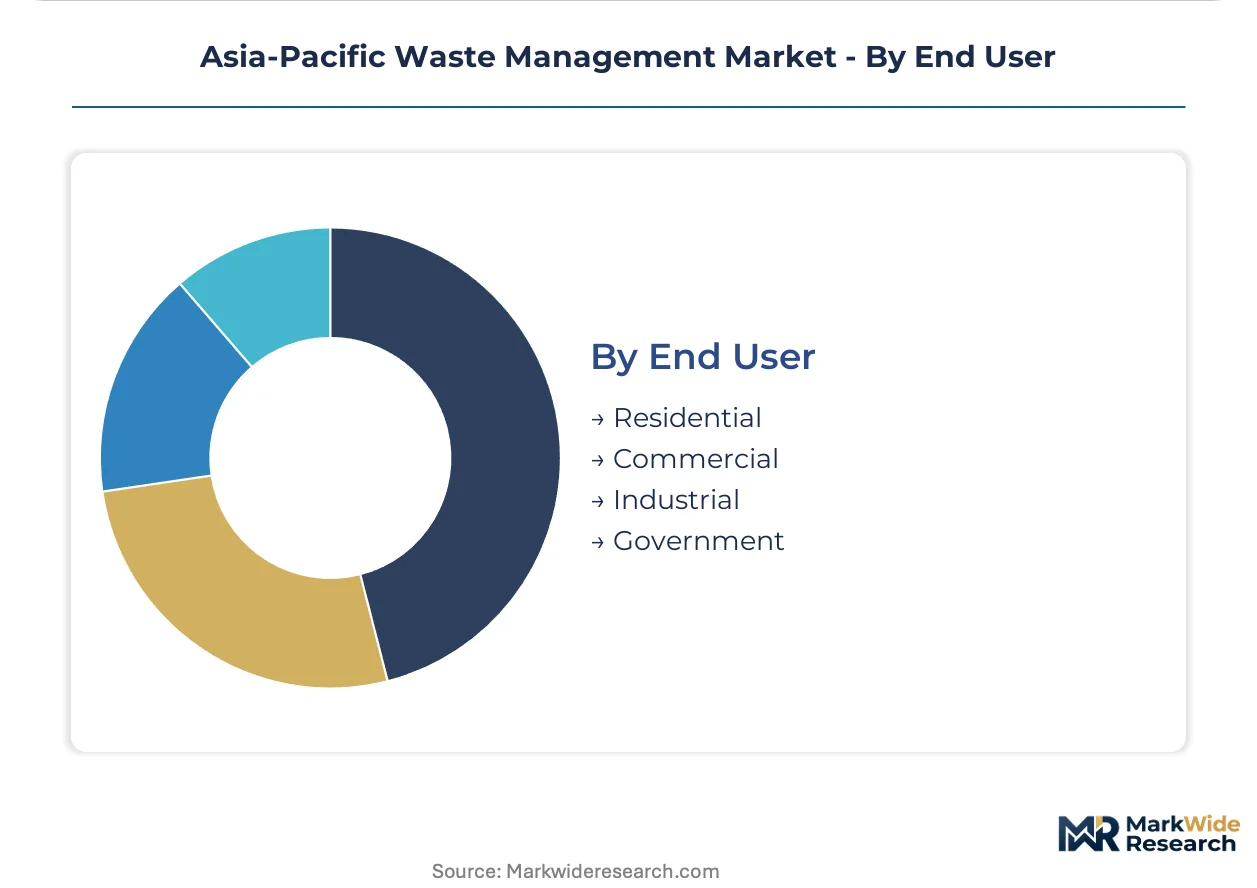
End User:
Customer type determines procurement structure, with industrial generators demanding single-source accountability and residential programs relying on municipal subsidy.
- Residential:Household waste collection and processing funded through municipal rates. Urban density in Southeast Asian metropolitan areas exceeds infrastructure carrying capacity.
- Commercial:Retail, hospitality, and office sector waste services. India's Extended Producer Responsibility rules for plastic force brand owners to fund reverse logistics networks.
- Industrial:Manufacturing and processing facility waste management. Buyer consolidation among Taiwan and South Korea electronics OEMs compresses vendor qualification timelines.
- Government:Public infrastructure, healthcare, and defense sector contracts. Municipal procurement is rotating toward integrated service providers capable of handling collection through final treatment.
Residential anchors the volume base while Industrial gains share fastest as manufacturing clusters expand and compliance requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated incineration capacity clusters in China's coastal provinces while hazardous treatment specialists concentrate in Japan's industrial prefectures. India's chemical processing corridors face acute capacity deficits against generation rates. Municipal outsourcing contracts are expanding fastest across Southeast Asian megacities where informal collection networks dominate feedstock supply.
China
Jiangsu and Zhejiang municipalities are accelerating procurement of waste-to-energy plants with district heating output as the Ministry of Ecology and Environment enforces dual carbon targets. Provincial state-owned enterprises must retrofit dumpsites with gas capture systems or face suspension. Shanghai's Yangtze River Delta corridor anchors thermal treatment investment under tightening landfill methane caps.
Japan
Industrial waste tracking through METI manifest systems creates compliance-driven demand for certified treatment operators. Chemical manufacturers in Osaka's Kansai region pilot plasma gasification units for halogenated solvent destruction. Tokyo's Kanto industrial belt sustains premium pricing for hazardous processing capabilities that smaller competitors cannot replicate.
India
Gujarat and Maharashtra industrial corridors exhibit hazardous waste generation rates substantially exceeding installed chemical treatment capacity. The Central Pollution Control Board's Extended Producer Responsibility mandates force brand owners to fund reverse logistics networks. Mumbai-Pune manufacturing clusters drive procurement compression for integrated collection-to-treatment providers.
South Korea
Semiconductor fabrication facilities in the Seoul Capital Area position e-waste collectors for high-value precious metal recovery streams. Buyer consolidation among electronics OEMs compresses vendor qualification timelines for auditable mass balance documentation. Busan-Ulsan's chemical processing belt sustains demand for specialized containment infrastructure.
Australia
Landfill remediation obligations distort capital allocation toward liability management rather than new capacity across New South Wales and Victoria. Cleanaway Waste Management anchors market share through resource recovery infrastructure. Post-closure monitoring requirements spanning decades constrain competitive entry for specialized treatment operators.
Asia-Pacific Waste Management Market Competitive Landscape
Concentration sits with integrated multinational platforms capable of spanning collection through final treatment. The vendor base separates into three tiers: global environmental services conglomerates with incineration technology leadership, regional specialists dominating hazardous chemical processing, and municipal contractors securing outsourced collection contracts. Competitive moves center on strategic partnerships for technology licensing and geographic expansion through long-term service concessions.
Among Asia-Pacific-based operators, Daiseki Co. Ltd exemplifies the industrial waste specialist archetype through chemical processing capabilities. Veolia Environmental Services and Cleanaway Waste Management anchor the integrated services tier across Southeast Asian urban contracts and Australasian landfill remediation respectively. Suez Environment S.A. occupies a position within the multinational platform segment serving municipal procurement rotations toward single-source accountability.
| Leading Market Players |
|---|
| Veolia Environmental Services |
| Suez Environment S.A. |
| Waste Management Inc. |
| Cleanaway Waste Management |
| Daiseki Co. Ltd |
| BRISEA Group, Inc. |
| Remondis AG & Co. KG |
| Hitachi Zosen Corporation |
| Stericycle Inc |
| Others |
Pricing and Supply Chain Analysis
Incineration plant scale economies in China's Jiangsu and Zhejiang provinces compress unit treatment costs below regional competitors, concentrating pricing power among operators with district heating integration and locking price floors at levels that smaller, non-integrated facilities cannot match.
Pricing Analysis
Three-tier pricing structure across premium hazardous treatment, standard municipal collection, and economy landfill disposal segments governs procurement. Price differentiation rests on certification grade under Japan's METI manifest systems and volume scale for industrial corridor contracts. Cost compression in standard municipal tiers is intensifying because informal sector competition in Jakarta and Manila erodes formal operator margins. Industrial generators exhibit least price sensitivity due to compliance-driven procurement, while residential municipalities face acute budget constraints.
Supply Chain Analysis
Container availability constraints across the Shanghai-Singapore trade lane elevate inbound logistics costs for specialized treatment chemicals and emissions control equipment. Equipment manufacturing concentrates in China, Japan, and South Korea, with chemical processing vessels and incineration grate systems drawing from German and Italian component suppliers. Single-source vulnerability sits with plasma gasification catalysts sourced exclusively from Japanese chemical manufacturers. Distribution runs through state-owned enterprise procurement channels in China and private industrial service integrators in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as China's dual carbon enforcement deadlines and India's Extended Producer Responsibility compliance windows synchronize procurement acceleration across municipal and industrial segments.
For Market Incumbents: Secure long-term service concessions in Gujarat and Maharashtra before chemical treatment capacity deficits force emergency procurement at premium rates. Deepen backward integration into plasma gasification technology licensing to neutralize emerging Japanese specialist competition. Cement relationships with China's provincial state-owned enterprises ahead of district heating mandate expansions.
For New Entrants and Emerging Players: Differentiate on digital manifest integration capabilities that Japan's METI compliance requirements have made mandatory but incumbent platforms have underinvested in. Target Vietnam and Philippines e-waste collection networks where informal sector fragmentation creates white-space for certified precious metal recovery operations. Pursue joint venture structures with local municipal governments lacking capital for integrated infrastructure buildout.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hazardous treatment specialists with proprietary chemical processing capabilities over commoditized collection operators. The five-to-ten year viability window rewards platforms with demonstrated compliance track records under tightening landfill diversion mandates. Monitor India's Central Pollution Control Board enforcement intensity as the inflection signal for capacity shortage pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Gasification Technology Licensing | Japanese chemical manufacturers in Osaka's Kansai region are piloting units that eliminate residual ash disposal for halogenated solvents. |
| Integrated Service Concession Expansion | Veolia Environmental Services leverages incineration leadership to anchor Southeast Asian urban contracts spanning collection through final treatment. |
| Digital Manifest Platform Development | Software-enabled logistics integration creates compliance-driven demand that smaller Japanese competitors cannot replicate under METI tracking mandates. |
| Hazardous Capacity Buildout in Industrial Corridors | Gujarat and Maharashtra generation rates substantially exceed installed chemical treatment capacity, creating deficit pricing opportunities. |
| E-Waste Collection Network Proximity Strategy | Positioning near South Korean and Taiwanese semiconductor clusters captures high-value precious metal recovery streams under tightening EPR rules. |
Research Methodology
Cross-validation between regulatory filing analysis and operator capacity databases anchors the qualitative findings in this study. Primary interviews with municipal procurement officers, hazardous treatment plant managers, industrial waste generators, and reverse logistics coordinators were combined with secondary validation from China's Ministry of Ecology and Environment enforcement notices, India's Central Pollution Control Board EPR registration data, Japan's METI manifest system disclosures, and ASEAN customs trade statistics. Bottom-up facility capacity enumeration and top-down generation rate modeling were triangulated to establish market sizing boundaries.
Sensitivity analysis around feedstock supply fragmentation and carbon credit valuation assumptions informs the projection framework across the analysis window. Segmentation dimensions modeled include service type tier, waste hazard classification, treatment technology maturity, and end-user procurement structure. CAGRs were derived from capacity addition pipelines against enforcement timeline scenarios, with waste-to-energy deployment rates and E-waste collection network densification serving as key industry-specific forecast inputs.
Material uncertainties — regulatory enforcement intensity variations, informal sector displacement velocity, and cross-border equipment tariff disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance deadline adherence and subsidy continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
Trash Rakes Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Polyfluoroalkyl Substances (PFAS) Waste Management Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market