
 Personal Transporter Market | 2026-2036
Personal Transporter Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Transporter Market Outlook
The EU Green Deal is realigning cost-of-entry calculus for personal transporter manufacturers exporting into Europe. Segway Inc. leverages its patent portfolio to sustain premium positioning in self-balancing vehicle categories. Beijing Ninebot Electric Vehicle Technology Co. Ltd. anchors global production scale through captive manufacturing in China. Honda Motor Co. Ltd. differentiates via automotive-grade engineering standards applied to compact mobility platforms.
Personal transporters encompass electrically powered micro-mobility devices designed for individual transport over short to medium distances, typically incorporating lithium-ion battery packs, brushless DC motors, and gyroscopic stabilization systems with load capacities ranging from 100 to 150 kilograms and top speeds between 20 and 45 kilometers per hour. These devices serve commercial purposes spanning urban commuting, tourism fleet operations, and campus logistics. Electric scooters lead product type volume due to lower unit costs and broader demographic accessibility, while e-bikes command higher margin pools through premium battery technology segments. Smart features including GPS tracking and mobile app integration represent the fastest-growing technology dimension as rental services and fleet operators demand real-time asset management capabilities.
The US Consumer Product Safety Commission and NHTSA shape domestic market access through mandatory safety certifications and roadway classification rules that determine where devices may legally operate. Europe's CE marking and MDR frameworks enforce electromagnetic compatibility and battery safety standards that filter out non-compliant imports. China's GB standards and MIIT regulations govern domestic manufacturing quality while SAMR oversees market surveillance for product recalls. Stakeholders must monitor evolving municipal ordinances that alternately restrict or permit sidewalk operation, as these local rules determine addressable market size more precisely than national sales forecasts.
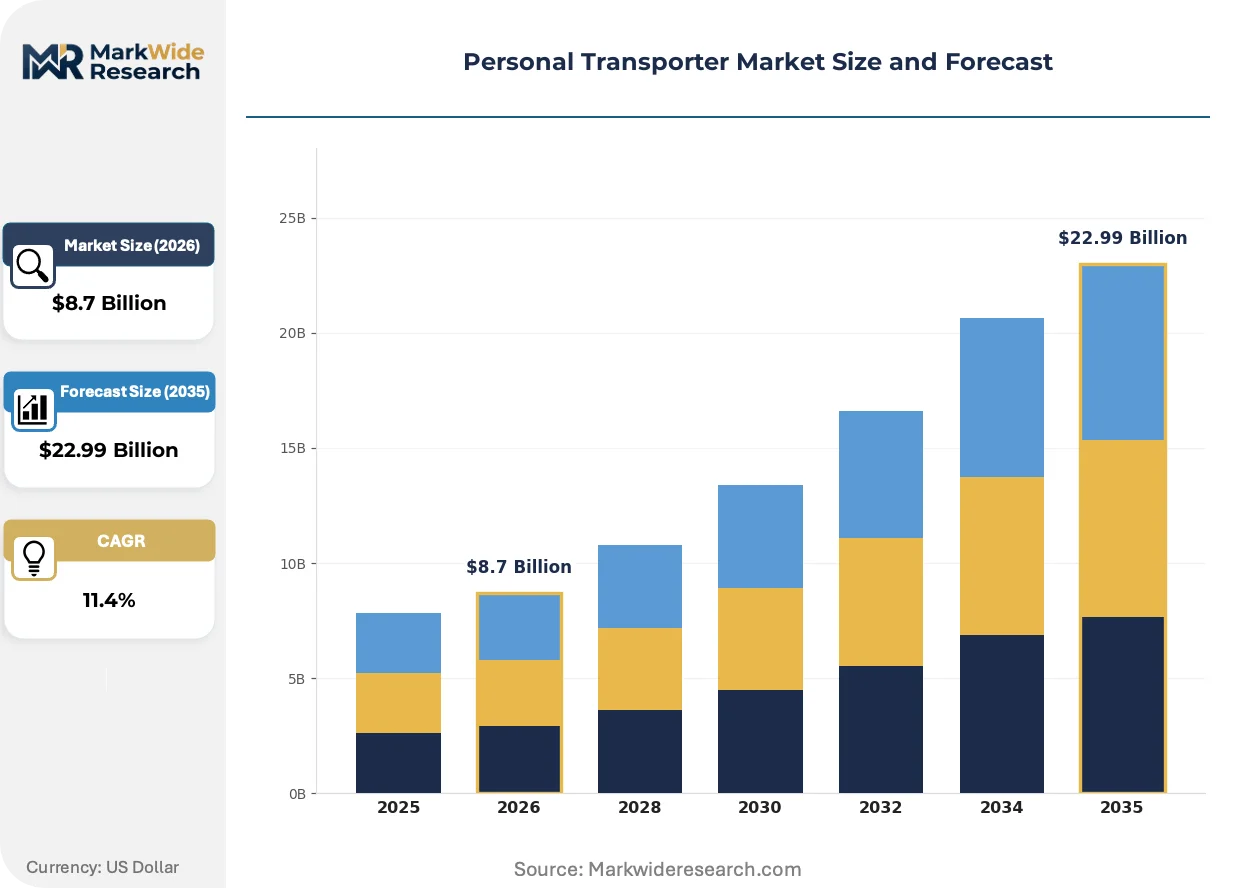
Market Dynamics
Urban congestion pricing schemes and zero-emission zone mandates are compressing the total cost of ownership for electric micro-mobility against internal combustion alternatives. Battery pack energy density improvements are simultaneously extending range capabilities while reducing unit weight.
Growth Catalysts
- EU Green Deal mobility targets:Member state incentive programs for zero-emission vehicles are accelerating fleet electrification timelines across municipal procurement channels.
- Lithium-ion manufacturing scale:Concentrated cell production in China is compressing battery pack costs for original equipment manufacturers.
- Last-mile logistics demand:E-commerce fulfillment networks are integrating electric scooters into urban delivery operations for time-sensitive parcel distribution.
Market Restraints
- Critical mineral supply concentration:Cobalt and lithium refining capacity clusters in China and the Democratic Republic of Congo create input price volatility exposure.
- Roadway classification fragmentation:Municipal ordinances in Germany, France, and the United Kingdom impose inconsistent operating permissions that limit addressable route networks.
- Pedestrian safety liability exposure:Sidewalk collision incidents generate insurance premium escalation and operator certification requirements.
Strategic Opportunities
- India's urban mobility corridors:Metro rail expansion in Delhi, Mumbai, and Bangalore creates first-mile-last-mile connectivity gaps for electric two-wheeler deployment.
- Battery-as-a-service models:Swappable pack architectures eliminate upfront capital barriers for price-sensitive commuter segments.
- ISO 15118-20 vehicle-grid integration:Bidirectional charging standards enable personal transporters to participate in distributed energy resource markets.
Industry Challenges
- Embedded systems cybersecurity certification:Connected vehicle platforms require penetration testing and over-the-air update validation that extends product development cycles.
- Cross-border type approval harmonization:Divergent electromagnetic compatibility testing protocols between CE marking and FCC Part 15 regimes duplicate compliance expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Transporter Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Scooters, Hoverboards, Segways, E-Bikes End User: Individuals, Commuters, Tourists, Students Technology: Smart Features, Battery Technology, Connectivity, Electric Motors Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Rental Services |
| Companies Covered | Beijing Ninebot Electric Vehicle Technology Co. Ltd., Hangzhou CHIC Intelligent Technology Co. Ltd., Segway Inc., Xiaomi Corporation, Onewheel, INMOTION TECHNOLOGIES CO. LTD., Airwheel Holding Limited, RazorUSA LLC, Honda Motor Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Transporter Market Strategic Shifts
Electrification architectures are converging with connectivity stacks to transform personal transporters from mechanical commodities into software-defined mobility platforms. This convergence is compressing product lifecycles and redefining competitive differentiation.
Solid-state battery chemistries are consolidating energy storage leadership for next-generation personal transporters by eliminating thermal runaway risks while doubling volumetric energy density. Tier-one automotive suppliers are licensing ceramic electrolyte formulations to micro-mobility original equipment manufacturers under technology transfer agreements. This consolidation is compressing the performance gap between premium electric scooters and entry-level electric motorcycles.
Europe's Machinery Regulation 2023/1230 is mandating functional safety assessments for autonomous balancing systems that incorporate artificial intelligence-based stabilization algorithms. Manufacturers exporting into the European Economic Area must demonstrate compliance with ISO 13849-1 performance levels for control system reliability. Self-balancing vehicle categories face the steepest certification burden, with notified body queue times extending twelve to eighteen months.
Fleet operators are unbundling hardware procurement from energy and maintenance services through subscription-based utilization contracts. Rental service providers in Barcelona, Paris, and Berlin are shifting from unit sales to per-minute revenue models that transfer residual value risk to manufacturers. This restructuring is most visible in Southern European markets where seasonal demand fluctuation makes fixed asset ownership economically unattractive.
Personal Transporter Market Segmentation
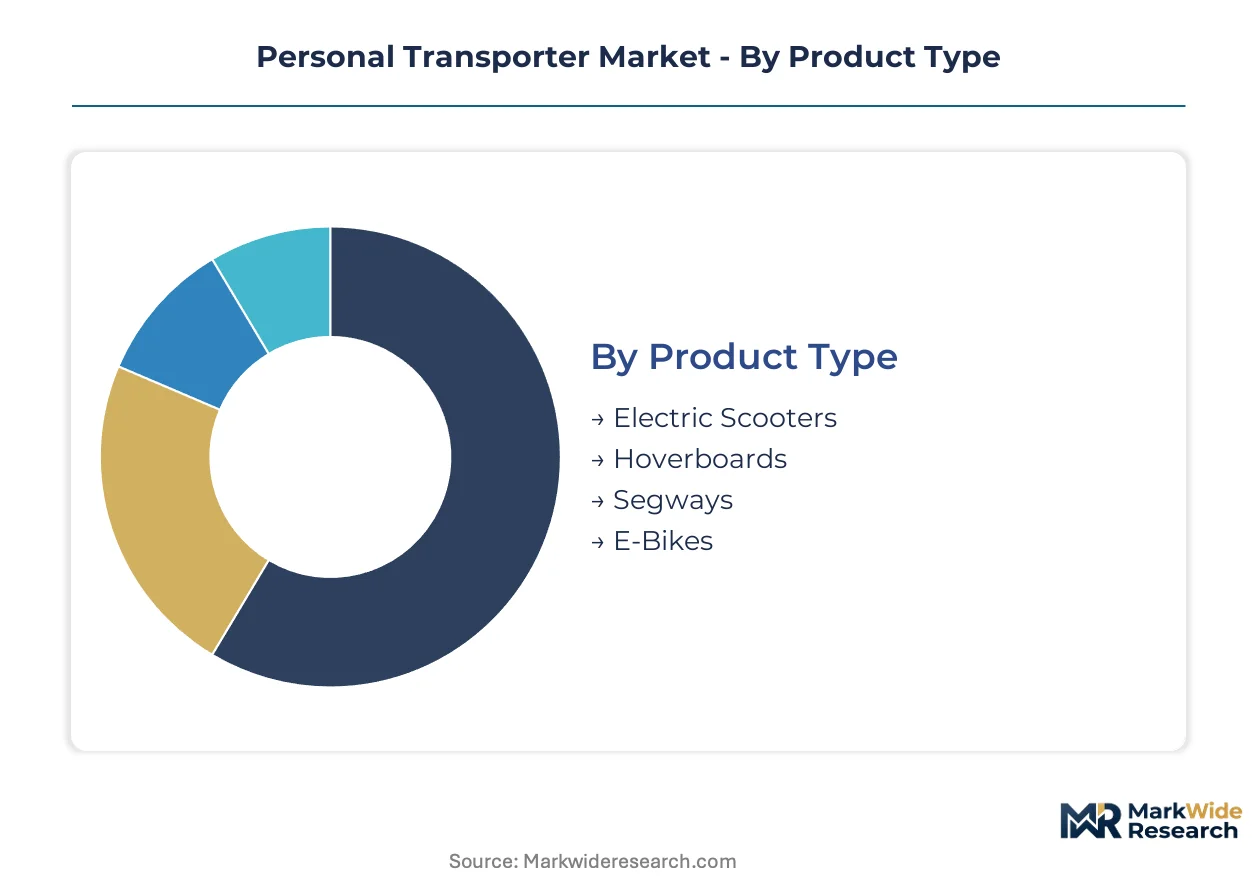
Personal transporter manufacturers calibrate production capacity and margin targets around distinct product-performance tiers rather than uniform scaling. Segmentation reveals where battery cost curves intersect with consumer willingness-to-pay across commuting, tourism, and campus mobility contexts.
Product Type:
Volume leadership concentrates in low-barrier entry categories, while premium positioning clusters around extended-range and stabilization-intensive formats.
- Electric Scooters:Foldable aluminum-frame designs with 250-500W brushless motors dominate urban commuting corridors in Barcelona, Paris, and Berlin. Fleet operators prioritize these units for per-minute rental economics due to sub-15kg curb weight and sub-$500 procurement points.
- E-Bikes:Pedal-assist architectures with 400-700Wh lithium-ion packs command higher margin pools through premium battery technology segments. German KBA type-approval requirements for road-legal operation filter out low-specification imports, concentrating demand among automotive-grade suppliers.
- Hoverboards:Self-balancing two-wheel platforms with gyroscopic stabilization target recreational users in North American and European markets. UL 2272 certification mandates constrain vendor participation following historical battery fire incidents.
- Segways:Upright dual-wheel configurations with redundant motor systems serve security patrol and guided tourism applications. Patent-protected control algorithms limit competitive entry in this category.
Mature deployment sits with electric scooters. Newer deployment is concentrated in e-bikes.
End User:
Demand fragmentation across customer types forces divergent distribution and service strategies.
- Commuters:Daily urban travelers integrating personal transporters with metro and bus networks in congested metropolitan areas. Range anxiety and charging infrastructure access dominate purchase criteria for this segment.
- Tourists:Short-duration users accessing rental fleets at destination cities. Seasonal demand fluctuation in Southern European markets makes fixed asset ownership economically unattractive for service providers targeting this group.
- Individuals:Private owners seeking recreational mobility or last-mile connectivity solutions. Price sensitivity varies sharply by metropolitan density and parking cost structures.
- Students:Campus-based users operating within controlled geographic boundaries. University procurement channels favor durability and theft-deterrence features over premium performance specifications.
Procurement centralization characterizes commuter and student segments. Fragmented individual purchasing dominates volume.
Technology:
Component-level differentiation is compressing product lifecycles and redefining competitive positioning.
- Battery Technology:Lithium-ion cell chemistry variations determine range, weight, and thermal safety profiles. Solid-state formulations are consolidating energy storage leadership for next-generation platforms by eliminating thermal runaway risks.
- Smart Features:GPS tracking and mobile app integration represent the fastest-growing technology dimension as rental services demand real-time asset management. ISO 15118-20 vehicle-grid integration standards enable bidirectional charging participation.
- Connectivity:Cellular and Bluetooth stacks supporting over-the-air updates and telemetry transmission. Embedded systems cybersecurity certification requirements extend product development cycles for connected platforms.
- Electric Motors:Brushless DC architectures with regenerative braking capabilities. Power output segmentation aligns with municipal speed limit regulations that vary across operating jurisdictions.
Hardware maturity concentrates in motor and battery segments. Software-defined feature expansion is accelerating in connectivity and smart systems.
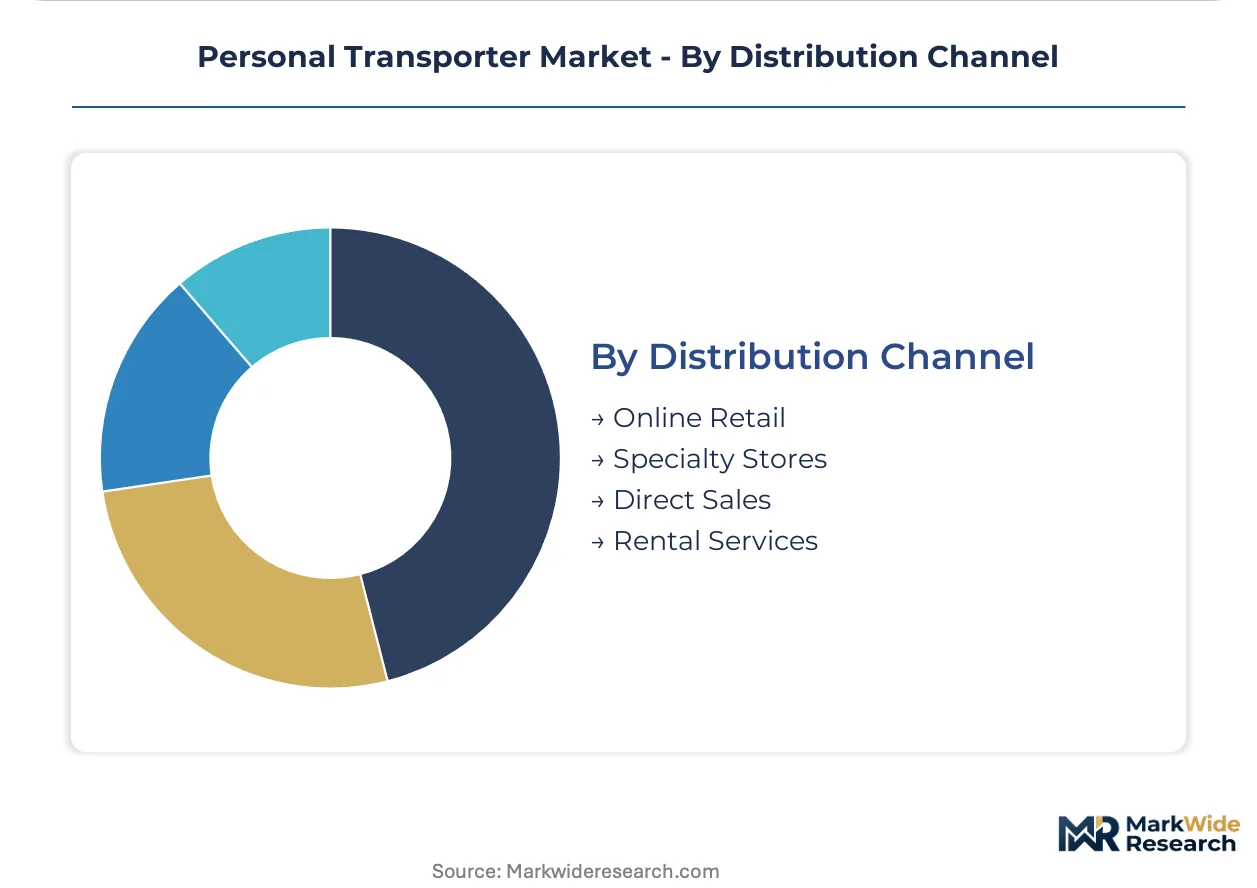
Distribution Channel:
Channel selection determines customer acquisition cost structures and post-sale service obligations.
- Rental Services:Per-minute utilization models transferring residual value risk to manufacturers. Barcelona, Paris, and Berlin operators are shifting from unit sales to subscription-based contracts.
- Online Retail:Direct-to-consumer platforms capturing price-sensitive segments with minimal touch requirements. Return logistics complexity limits category participation for heavy-format transporters.
- Specialty Stores:Physical showrooms enabling test-ride validation and maintenance service bundling. Premium positioning depends on trained technical staff for battery and motor diagnostics.
- Direct Sales:Manufacturer-owned channels capturing full margin stack in enterprise and municipal fleet procurement. Long sales cycles require dedicated account management resources.
Asset-heavy rental models dominate urban deployment scaling. Direct sales concentrate in institutional and fleet segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban commuters in congested metropolitan areas across Germany, China, the United States, France, and India are embracing electric scooters and e-bikes for last-mile connectivity. Municipal procurement channels and zero-emission zone mandates are compressing total cost of ownership calculations in these demand centers.
United States
Campus logistics and security patrol applications sustain institutional demand for upright dual-wheel configurations. The US Consumer Product Safety Commission and NHTSA shape domestic market access through mandatory safety certifications and roadway classification rules. Greater Boston and Pacific Northwest tech corridors concentrate early adoption of connected fleet management platforms for rental service operators.
Germany
Pedal-assist architectures with premium battery specifications command strong commuter adoption in Berlin, Munich, and Hamburg. KBA type-approval requirements for road-legal operation filter out low-specification imports, concentrating demand among automotive-grade suppliers. Baden-Württemberg's industrial base anchors engineering partnerships between tier-one automotive suppliers and micro-mobility original equipment manufacturers.
China
Manufacturing concentration for lithium-ion battery packs and electric motor assemblies dominates global supply capacity. MIIT regulations and GB standards govern domestic production quality while SAMR oversees market surveillance for product recalls. The Yangtze River Delta and Pearl River Delta clusters host captive production facilities serving export markets across Europe and North America.
France
Parisian rental service providers are shifting from unit sales to per-minute revenue models that transfer residual value risk to manufacturers. CE marking and MDR frameworks enforce electromagnetic compatibility and battery safety standards that filter non-compliant imports. Île-de-France's dense metro network creates first-mile-last-mile connectivity gaps for electric scooter deployment.
India
Metro rail expansion in Delhi, Mumbai, and Bangalore creates first-mile-last-mile connectivity gaps for electric two-wheeler deployment. BIS standards and state-level electric vehicle policies shape product certification requirements for domestic market entry. Maharashtra and Karnataka concentrate startup activity in battery-as-a-service and swappable pack architectures for price-sensitive commuter segments.
Personal Transporter Market Competitive Environment
Chinese producers anchor the scale-driven tier; US and Japanese specialists hold premium positioning in patented stabilization systems. The vendor base stratifies across three performance tiers defined by battery chemistry sophistication and connectivity integration depth. Automotive-grade engineering standards differentiate established mobility conglomerates from commodity assemblers. Competitive moves concentrate on technology licensing agreements and backward integration into lithium-ion cell sourcing.
Within the patent-protected stabilization tier, Segway Inc. and Beijing Ninebot Electric Vehicle Technology Co. Ltd. occupy positions defined by intellectual property control over self-balancing algorithms. Among diversified mobility conglomerates, Honda Motor Co. Ltd. exemplifies the application of automotive-grade engineering standards to compact platforms. Xiaomi Corporation represents the consumer electronics-origin archetype leveraging supply chain scale and direct-to-consumer distribution infrastructure.
| Leading Market Players |
|---|
| Beijing Ninebot Electric Vehicle Technology Co. Ltd. |
| Hangzhou CHIC Intelligent Technology Co. Ltd. |
| Segway Inc. |
| Xiaomi Corporation |
| Onewheel |
| INMOTION TECHNOLOGIES CO. LTD. |
| Airwheel Holding Limited |
| RazorUSA LLC |
| Honda Motor Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Fleet operator procurement concentration in Barcelona, Paris, and Berlin anchors subscription-based utilization contracts that transfer residual value risk to manufacturers. This buyer archetype dominance compresses upfront unit pricing while elevating lifetime service revenue as the primary margin pool.
Pricing Analysis
Short lead-time premiums for UL 2272-certified hoverboards and CE-marked e-bikes run 15-25 percent above spot inventory pricing for equivalent uncertified units. Three-tier pricing structure across premium automotive-grade, standard fleet-specification, and economy direct-import levels segments the market by certification burden and after-sales service bundling. Cost compression in the economy tier is intensifying because Chinese OEMs are bypassing European notified body queues through parallel standard-grade channels. Individual consumers exhibit the sharpest price sensitivity, while municipal procurement programs prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with lithium-ion cell production concentrated in China, South Korea, and Japan, where cathode active material refining clusters create input bottlenecks. The personal transporter supply chain draws from cobalt and lithium feedstocks anchored in the Democratic Republic of Congo and Chile, with graphite anode production tethered to Heilongjiang province operations. Tariff exposure on Chinese-assembled battery packs threatens margin stability for European and North American brands without captive cell sourcing. Distribution runs through Yangtze River Delta export hubs into Rotterdam and Long Beach container terminals, with final-mile fulfillment handled by direct-to-consumer platforms and rental service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell production capacity constraints in China's Yangtze River Delta prop pricing premiums for automotive-grade lithium-ion packs, sustaining margin pools for manufacturers with secured supply agreements.
For Market Incumbents: Extend patent-protected stabilization algorithms into adjacent form factors including seated mobility platforms and cargo-capable three-wheel architectures. Secure backward integration into solid-state electrolyte sourcing through technology licensing agreements with tier-one automotive suppliers before ceramic formulation patents consolidate. Counter emerging consumer electronics-origin entrants by embedding ISO 15118-20 vehicle-grid integration as a standard feature, raising certification barriers for commodity assemblers. For New Entrants and Emerging Players: Direct-to-consumer platforms offer the lowest customer acquisition cost entry vector for price-sensitive individual segments in India and Southeast Asian metros. Campus mobility procurement channels present the most penetrable institutional segment, with durability and theft-deterrence specifications favoring new engineering-focused entrants over rental service incumbents. Target battery-as-a-service subscription models in Maharashtra and Karnataka to eliminate upfront capital barriers for commuter adoption. For Investors and Strategic Acquirers: The window for entry favors vertically integrated cell-to-vehicle specialists with captive lithium-ion production and automotive-grade quality systems. Long-term viability hinges on positioning ahead of solid-state chemistry transitions that will displace incumbent liquid electrolyte architectures. Watch notified body queue times for Machinery Regulation 2023/1230 compliance as the inflection indicator for European market access bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from Yangtze River Delta producers ahead of capacity constraints. |
| Solid-State Technology Licensing | Transfers ceramic electrolyte formulations from tier-one automotive suppliers to micro-mobility platforms. |
| CE Marking Acceleration | Compresses notified body queue times for Machinery Regulation 2023/1230 autonomous balancing compliance. |
| Vehicle-Grid Integration Investment | Enables ISO 15118-20 bidirectional charging participation in European distributed energy markets. |
| Campus Procurement Partnership | Locks university channel demand through durability specifications and theft-deterrence feature bundling. |
Study Parameters
Independent corroboration across fleet operator procurement directors, OEM platform engineers, and lithium-ion cell sourcing managers underwrites the qualitative findings in this study. Primary interviews with rental service operators in Barcelona, Paris, and Berlin were cross-referenced against secondary validation from MIIT production disclosures, SAMR recall databases, and KBA type-approval registries. Bottom-up unit shipment estimates triangulated against top-down battery pack procurement volumes anchor the market sizing.
Comparable historical periods spanning electrification adoption curves in adjacent micro-mobility categories anchored the forecast window calibration. The analytical framework models product type, end user segment, battery chemistry tier, and connectivity integration depth across the projection horizon. CAGRs were derived from segment-level growth rate differentials weighted by addressable route network expansion under municipal ordinance scenarios. Forecast inputs incorporate EU Green Deal incentive trajectory assumptions and solid-state battery commercialization timelines without specific year anchoring.
Inputs from notified body certification queues and lithium carbonate spot market indices were available through the study window; gaps in municipal sidewalk ordinance enforcement data introduce uncertainty bands around addressable market calculations. Forecasts reflect documented assumptions regarding battery cost curve trajectories and regulatory harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
E-Bike Rental Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Nordic Bike Sharing Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Global Smart Highway Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Global Smart Parking Solutions Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Smart Fleet-On-Board Devices Market