
 Road Asset Management Software Market | 2026-2036
Road Asset Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Road Asset Management Software Market Intelligence
The gap between enterprise-grade road asset platforms and basic spreadsheet-driven tools is realigning procurement patterns across public infrastructure agencies. IBM Maximo leverages decades of enterprise asset management heritage to anchor large-scale state DOT deployments. ManagerPlus competes on specialized fleet-and-road bundling for mid-sized municipalities. UpKeep differentiates through mobile-first work order interfaces that appeal to field inspection crews.
Road asset management software encompasses digital systems that inventory pavement condition, bridge structural health, signage, and drainage assets using GIS-linked databases, predictive deterioration models, and automated work order generation. These platforms integrate inspection frequency standards such as PASER ratings or bridge element condition states to prioritize capital spending across distributed linear networks. The deployment model dimension shows cloud-based and SaaS configurations capturing the fastest expansion as agencies shed on-premises server burdens, while on-premises installations retain footholds where cybersecurity policies restrict external data hosting. Among end users, transport authorities and government agencies represent the deepest budget pools, though municipalities represent the broadest addressable base across thousands of separate procurement jurisdictions.
The Federal Highway Administration's MAP-21 and IIJA reporting frameworks, alongside ISO 55000 asset management standards, compel agencies to adopt auditable, data-driven decision architectures rather than reactive maintenance calendars. State-level DOTs in the US must now submit standardized performance metrics to FHWA, creating direct procurement pressure for software with embedded compliance dashboards. Stakeholders should monitor how quickly smaller municipalities consolidate vendor selections around platforms that bundle federal reporting automation with native GIS integration.
Market Dynamics
Federal infrastructure reporting mandates are compressing procurement cycles for state DOTs and municipalities, forcing rapid modernization of legacy pavement inventory systems ahead of compliance deadlines.
Growth Catalysts
- MAP-21 Performance Management:US state DOTs must submit standardized metrics to FHWA, creating direct software procurement pressure for platforms with embedded compliance dashboards.
- Cloud Migration:Municipal agencies are shedding on-premises server burdens, accelerating SaaS adoption for distributed linear network management.
- ISO 55000 Adoption:Asset management standards compel auditable, data-driven decision architectures rather than reactive maintenance calendars.
Market Restraints
- Cybersecurity Policy Fragmentation:Agencies with strict data sovereignty requirements block external hosting, preserving on-premises installations despite higher total cost of ownership.
- Interoperability Gaps:Legacy GIS formats and proprietary data structures create vendor lock-in that slows platform consolidation across multi-jurisdictional networks.
- Budget Cyclicality:Municipal capital programs tied to fuel tax revenues face volatility that defers enterprise software commitments.
Strategic Opportunities
- IIJA Implementation Wave:Infrastructure investment and jobs act disbursements unlock federal funding streams for integrated asset management platforms.
- Mobile-First Field Operations:Inspection crews demand smartphone-native work order interfaces that bypass traditional desktop-centric deployments.
- Predictive Deterioration Convergence:Machine learning models fused with PASER rating datasets enable condition-based maintenance prioritization.
Industry Challenges
- Geospatial Talent Scarcity:GIS specialists capable of configuring linear referencing systems for distributed road networks command premium compensation that strains agency hiring.
- Legacy System Integration:Decades-old pavement management databases require costly data migration and schema normalization before cloud platforms achieve full functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Asset Management Software Market |
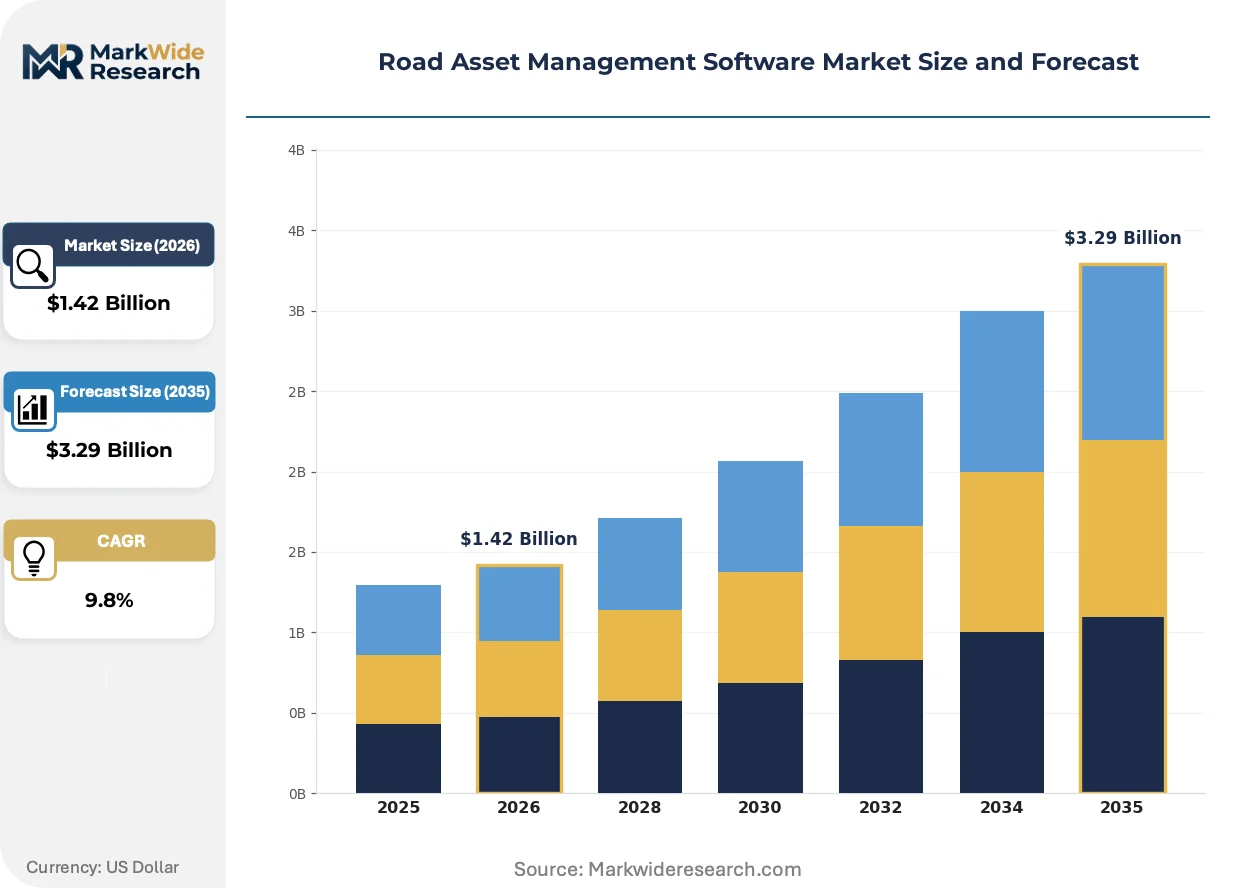
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.29 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Management, Performance Monitoring, Budget Planning, Maintenance Scheduling End User: Government Agencies, Construction Firms, Municipalities, Transport Authorities Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS Integration Level: API Integration, Mobile Integration, GIS Integration, ERP Integration |
| Companies Covered | Asset Infinity, Fiix, IBM Maximo, ServiceNow ITAM, ManagerPlus, Dynamics 365 Field Service, UpKeep, Asset Panda, SAP EAM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Asset Management Software Market Strategic Shifts & Innovations
Software architectures are fragmenting into composable components that let agencies purchase only the modules matching their asset classes and compliance obligations.
Digital twin technology is modularizing how state DOTs simulate pavement deterioration scenarios. Texas and California transportation departments now deploy physics-based models alongside empirical performance curves. This convergence is compressing capital planning cycles from annual to quarterly refresh intervals.
FHWA's standardized performance metric requirements are forcing vendor roadmaps toward embedded reporting automation. Software providers must pre-configure dashboards that map directly to federal submission templates. State agencies with the most complex bridge inventories face the steepest reconfiguration demands.
Buying committees are consolidating vendor selections around platforms bundling federal compliance with native GIS integration. Mid-sized municipalities that previously managed spreadsheets now issue RFPs requiring Esri-compatible data layers. This concentration favors suppliers with pre-built connectors to state data repositories.
Road Asset Management Software Market Segmentation
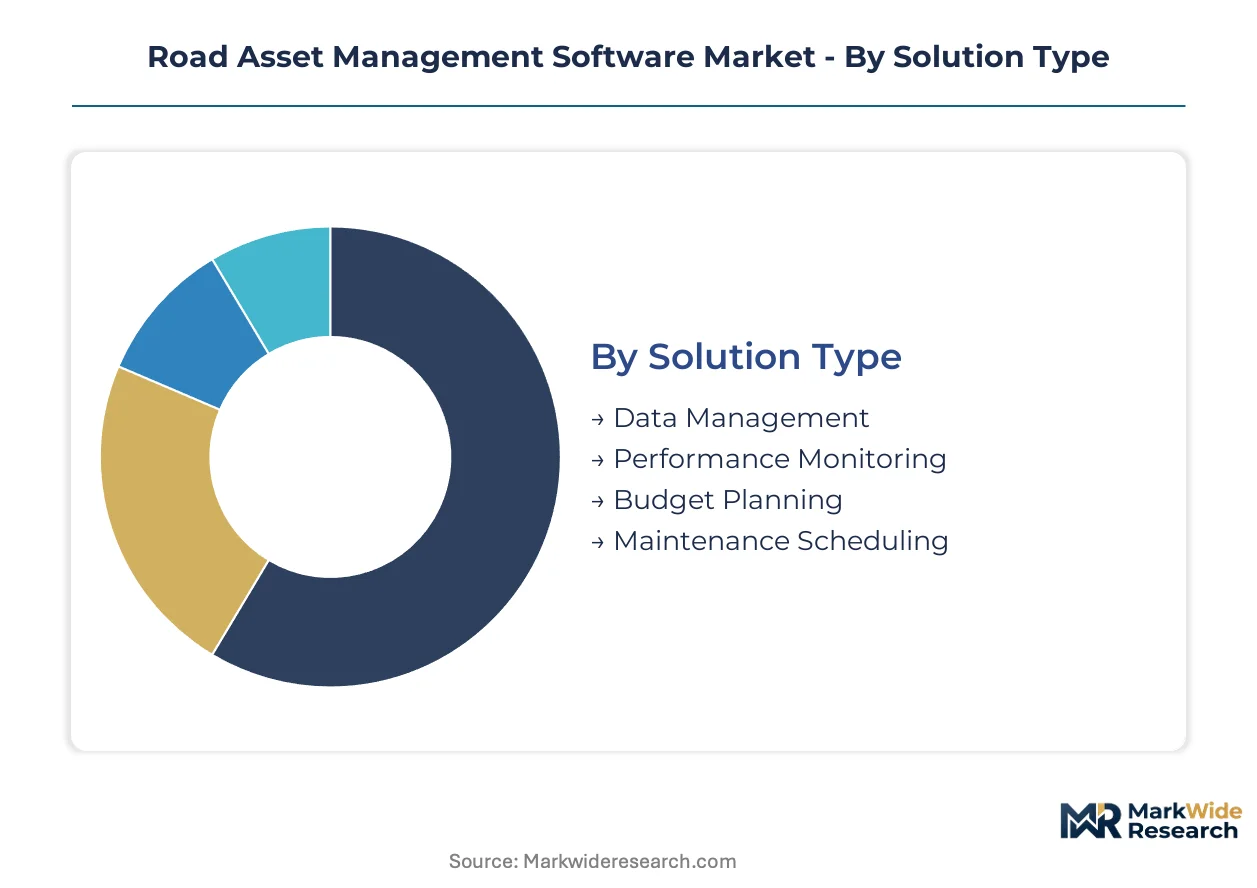
Road asset management software procurement varies sharply by agency size and technical maturity. Segmentation reveals where federal compliance pressure concentrates versus where budget constraints force modular adoption.
Solution Type:
Capital intensity escalates from basic data repositories to predictive systems with embedded machine learning.
- Data Management:Core GIS-linked databases inventory pavement condition, bridge structural health, signage, and drainage assets using standardized schemas. State DOTs in the United States prioritize these foundations for FHWA MAP-21 reporting compliance, though legacy schema migration drains implementation budgets.
- Performance Monitoring:Real-time dashboards track PASER ratings and bridge element condition states against deterioration curves. Municipalities in California and Texas deploy these modules to compress capital planning cycles from annual to quarterly intervals.
- Budget Planning:Scenario modeling tools align maintenance spending with projected asset lifecycles. Mid-sized agencies favor this segment for IIJA funding allocation transparency.
- Maintenance Scheduling:Automated work order generation routes crews based on priority algorithms. Field operations teams demand smartphone-native interfaces here.
Most installed capacity flows through Data Management. Expansion is steepest in Performance Monitoring.
End User:
Procurement authority and compliance obligation intensity separate these customer tiers.
- Government Agencies:Federal and state transportation departments command the deepest budgets for enterprise deployments. The Federal Highway Administration's standardized performance metrics create direct procurement pressure for platforms with embedded compliance dashboards.
- Transport Authorities:Regional toll road and transit operators prioritize revenue-risk modeling alongside asset condition tracking. These entities lead adoption of predictive deterioration convergence.
- Municipalities:Thousands of separate procurement jurisdictions represent the broadest addressable base. Cloud migration accelerates here as agencies shed on-premises server burdens.
- Construction Firms:Contractors managing design-build-maintain contracts require handoff protocols for as-built data. This segment trails in software sophistication.
Transport Authorities deploy the most advanced predictive modules. Municipalities are expanding most quickly as spreadsheet-driven systems reach end-of-life.
Deployment Model:
Total cost of ownership calculations diverge based on cybersecurity policy strictness and IT staffing levels.
- Cloud-Based:External hosting eliminates server maintenance overhead. Agencies with flexible data sovereignty policies favor this model for distributed linear network management.
- SaaS:Subscription pricing aligns software costs with annual budget cycles. State DOTs modernizing legacy pavement inventory systems ahead of MAP-21 deadlines prefer this option.
- On-Premises:Air-gapped installations satisfy agencies with strict cybersecurity policies blocking external hosting. Higher total cost of ownership persists here.
- Hybrid:Sensitive bridge inventory data stays local while work order systems migrate to cloud. This configuration addresses fragmented policy environments.
SaaS configurations claim the majority of new procurement. Hybrid deployments are gaining share fastest among agencies with mixed security clearance requirements.
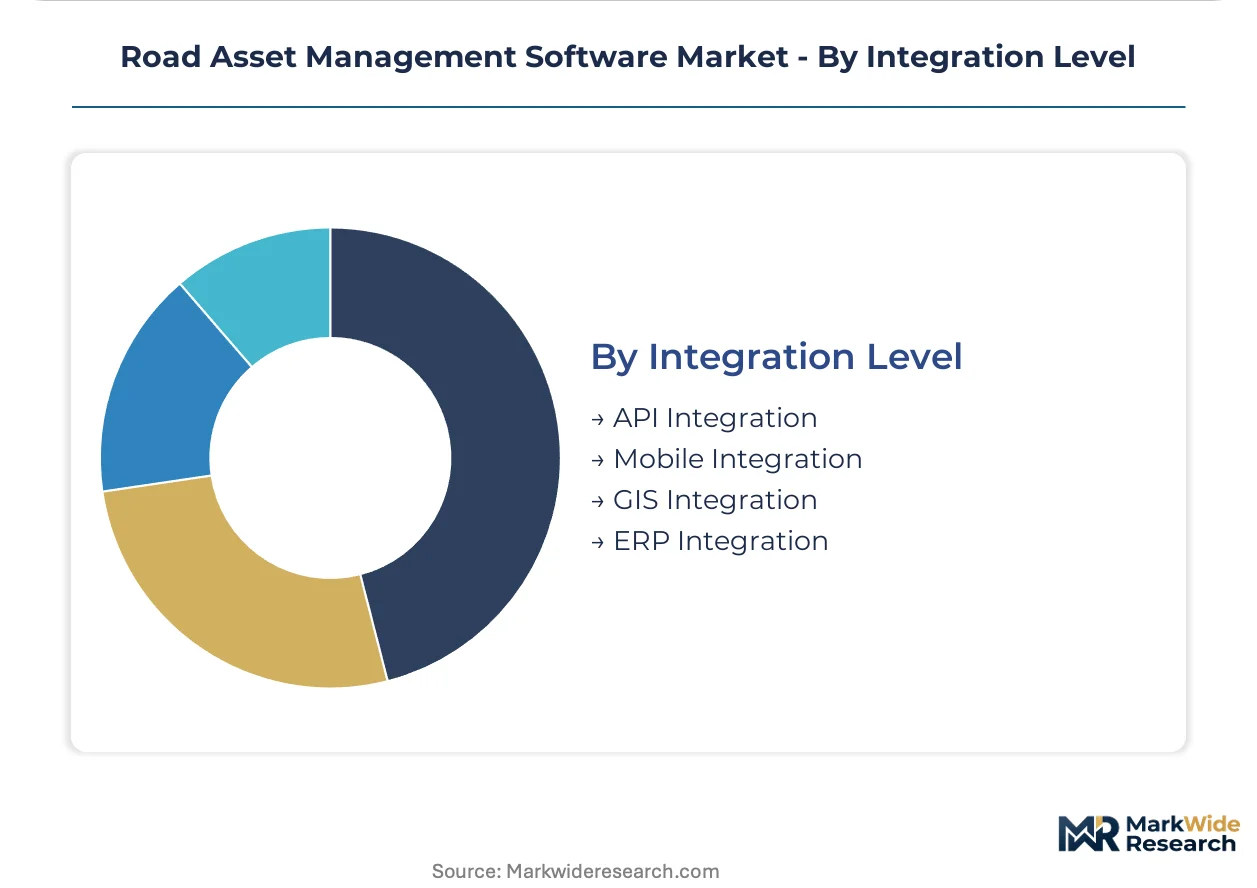
Integration Level:
Interoperability depth determines whether platforms achieve full functionality or remain siloed point solutions.
- GIS Integration:Native Esri-compatible data layers enable linear referencing systems for distributed road networks. Buying committees now mandate this capability in municipal RFPs.
- API Integration:Standardized data exchange protocols connect asset platforms to state repositories. This capability reduces vendor lock-in risks.
- Mobile Integration:Smartphone-native interfaces bypass traditional desktop-centric deployments for inspection crews. Field adoption rates hinge on this feature.
- ERP Integration:Financial system connectivity automates capital program accounting. Enterprise-grade deployments require this layer.
GIS Integration anchors the largest installed base. Mobile Integration is climbing the fastest as field crew demographics shift toward digital-native workforces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GIS specialists and pavement engineers concentrate procurement authority in jurisdictions with the most complex linear network inventories. Federal compliance mandates reshape software deployment patterns unevenly across geographies.
United States
State DOTs in Texas and California drive enterprise platform adoption for MAP-21 performance reporting. The Federal Highway Administration mandates standardized metrics submission, compressing procurement cycles for legacy system replacements. Municipal clusters in the Midwest and Southeast accelerate cloud migration as fuel tax revenues stabilize.
Canada
Provincial transportation ministries prioritize climate-resilient infrastructure tracking across vast northern networks. Transport Canada guidelines align with ISO 55000 asset management standards, favoring auditable decision architectures. Ontario and Quebec municipalities lead SaaS adoption for distributed bridge and roadway inventories.
Germany
Autobahn maintenance authorities demand predictive deterioration models for high-volume freight corridors. The KBA and federal transport ministry enforce strict data sovereignty requirements, preserving hybrid deployment configurations. Industrial clusters in Bavaria and North Rhine-Westphalia pilot digital twin integration for capital planning.
United Kingdom
Local highway authorities consolidate vendor selections around Esri-compatible platforms for pavement condition tracking. UK national standards for road maintenance data exchange create procurement pressure for API-integrated systems. Greater London and Midlands municipalities drive mobile-first field operation adoption.
Australia
State road agencies in New South Wales and Victoria modernize asset registries ahead of federal infrastructure auditing requirements. The country's national transport regulator emphasizes standardized condition rating protocols. Metropolitan councils accelerate cloud procurement to manage sprawling suburban road networks.
Road Asset Management Software Market Key Industry Players
Capital-heavy enterprise software producers compete with asset-light SaaS specialists for municipal procurement contracts. The vendor base segments into three tiers: legacy EAM platforms with decades of DOT relationships, mobile-native challengers capturing field crew adoption, and mid-market bundlers serving fleet-road hybrid needs. Consolidation pressure intensifies as buying committees demand pre-built federal compliance connectors alongside native GIS integration. Strategic moves center on API ecosystem expansion and predictive analytics module acquisition.
Within the enterprise platform tier, IBM Maximo and SAP EAM anchor large-scale state transportation department deployments. UpKeep exemplifies the mobile-first challenger archetype, capturing inspection crew preference through smartphone-native interfaces. ManagerPlus occupies the mid-market bundling position, serving municipalities seeking unified fleet and roadway asset tracking. These three anchors represent divergent responses to federal compliance compression and cloud migration acceleration.
| Leading Market Players |
|---|
| Asset Infinity |
| Fiix |
| IBM Maximo |
| ServiceNow ITAM |
| ManagerPlus |
| Dynamics 365 Field Service |
| UpKeep |
| Asset Panda |
| SAP EAM |
| Others |
Cost & Logistics Intelligence
GIS specialists in Texas and California command premium compensation that widens pricing-tier spreads between enterprise deployments and mid-market SaaS configurations. Labor-cost differentials between these technical talent clusters and secondary metropolitan markets directly shape how vendors structure subscription tiers across state DOT and municipal procurement segments.
Pricing Analysis
The bundled-vs-unbundled service split separates enterprise platforms with embedded federal compliance modules from modular SaaS offerings. Three-tier pricing structure across premium, standard, and economy levels tracks integration depth and GIS sophistication. Price differentiation hinges on Esri-native compatibility and pre-built MAP-21 dashboard configurations. Cost compression in the economy tier intensifies as spreadsheet-dependent municipalities consolidate vendor selections. Municipal procurement committees exhibit highest price sensitivity; state DOTs with IIJA funding streams demonstrate lowest.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data centers concentrated in the United States, Ireland, and Singapore. Core platform development draws from specialized GIS engineering talent pools, open-source geospatial libraries, and Esri partnership ecosystems. Single-source vulnerability concentrates around Esri's ArcGIS platform for linear referencing functionality. Distribution runs through direct enterprise sales teams for state DOTs and value-added resellers serving municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement committees prioritize platforms bundling federal compliance automation with native GIS integration over point solutions. Demand is shifting toward premium specifications that embed predictive deterioration models and machine learning-enabled PASER rating analysis.
For Market Incumbents: To counter mobile-native challengers capturing field crew preference, deepen API ecosystem expansion to reduce vendor lock-in friction and accelerate pre-built connector development for state data repositories. Vertical integration into predictive analytics modules addresses the steepest reconfiguration demands from agencies with complex bridge inventories. For New Entrants and Emerging Players: Launch via channel partnerships with municipal IT cooperatives and purchasing consortiums to bypass lengthy individual RFP cycles. White-space targets include mid-sized municipalities in the Midwest and Southeast transitioning from spreadsheet systems, and construction firms managing design-build-maintain contracts requiring as-built data handoff protocols. A mobile-first field operations angle bypasses entrenched desktop-centric deployments. For Investors and Strategic Acquirers: Enterprise asset management software conglomerates are the most active acquirer in this space, seeking predictive analytics capabilities and federal compliance automation modules. Long-term viability favors platforms with embedded machine learning deterioration models and native Esri integration. The signal to watch is consolidation velocity among municipal buying committees around bundled compliance-GIS offerings versus sustained fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Esri compatibility and MAP-21 dashboard pre-configuration accelerate state DOT procurement cycles. |
| Acquisition of Specialist Firm | Predictive analytics module purchases address bridge inventory complexity and PASER rating convergence demands. |
| Geographic Expansion | Midwest and Southeast municipal clusters offer spreadsheet-replacement opportunities as fuel tax revenues stabilize. |
| Strategic Partnership | Hyperscaler alliances reduce infrastructure costs for SaaS configurations serving distributed linear networks. |
| Product Launch | Mobile-native work order interfaces capture inspection crew preference and bypass desktop-centric deployment friction. |
Research Approach
Direct dialogue with state DOT asset management directors, municipal public works IT officers, Esri integration specialists, and FHWA compliance consultants anchored qualitative insights. Secondary validation drew from FHWA MAP-21 guidance documents, state transportation department procurement databases, municipal RFP archives, and IIJA funding disbursement records. Bottom-up and top-down triangulation cross-checked vendor-reported deployment scales against agency budget documentation.
Bottom-up modeling aggregated individual procurement jurisdiction adoption curves across deployment model, organization size, and integration complexity dimensions. Top-down analysis calibrated aggregate market expansion against federal compliance mandate timelines and infrastructure funding authorization levels. CAGRs derived from slope consistency across annual procurement velocity indicators and vendor revenue trajectory patterns. Forecast inputs included PASER rating standardization progress and cloud migration policy relaxation rates among cybersecurity-constrained agencies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended IIJA disbursement delays or accelerated state-level data sovereignty legislation. Forecasts reflect documented assumptions regarding federal reporting mandate enforcement intensity and municipal IT staffing recovery. A small set of triggers—including FHWA dashboard template revisions and Esri licensing cost movements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
Fleet Management Solution Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Smart Vehicle Cabin Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Physical Internet (PI) Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Europe Hyperloop Technology Market