
 Traffic Signal Controller Market | 2026-2036
Traffic Signal Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Traffic Signal Controller Market Analysis
China is reconfiguring global supply chains for traffic signal controllers through expanded semiconductor packaging and PCB assembly capacity in Shenzhen and Suzhou. Siemens Mobility leverages its European rail signaling heritage to anchor intelligent intersection management systems across German and Austrian deployments. SWARCO competes through specialized optical lens manufacturing that sustains premium positioning in Nordic markets with extreme weather requirements. Econolite dominates North American municipal procurement through deep channel relationships with state DOTs and city traffic engineering departments.
A traffic signal controller is an embedded electronic system that manages intersection signal phases through programmable timing plans, typically operating on 24V DC power with NEMA TS2 or ATC firmware architectures, designed to optimize vehicle throughput and pedestrian safety. Adaptive control systems now represent the fastest-expanding product category as machine-vision detection and real-time optimization algorithms displace fixed-time legacy installations. LED technology occupies the dominant technology position due to energy efficiency mandates, while smart sensors are capturing disproportionate growth from vehicle-to-infrastructure integration pilots. Urban traffic applications concentrate the largest installed base, though highway management segments offer superior margin pools from longer procurement cycles and stricter certification requirements.
The US Federal Highway Administration's MUTCD guidelines and NEMA TS2 standards shape hardware interoperability requirements, while the EU Green Deal and F-Gas Regulation indirectly accelerate LED retrofit demand by linking municipal infrastructure grants to carbon reduction targets. India's BIS certification and Smart Cities Mission funding create structured procurement pathways that favor vendors with domestic manufacturing partnerships. Stakeholders must monitor evolving V2X communication standards and cybersecurity mandates as regulatory bodies in multiple jurisdictions draft connectivity requirements that will determine next-generation controller architecture choices.
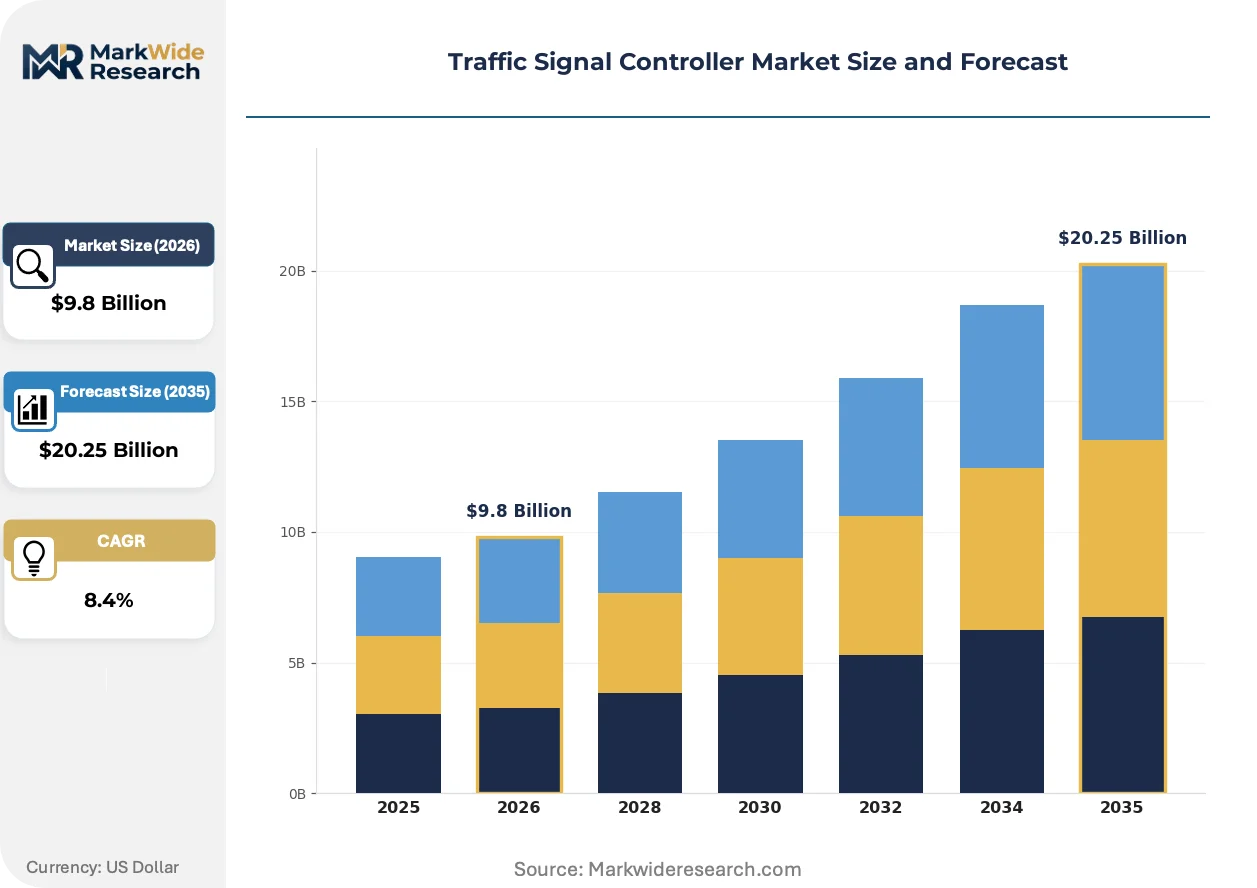
Market Dynamics
Federal infrastructure funding in the United States and EU Green Deal conditionality are restructuring procurement priorities away from hardware replacement cycles toward connected, adaptive intersection management platforms that require continuous software integration.
Growth Catalysts
- Adaptive Signal Algorithms:Real-time traffic optimization using machine-vision detection is replacing fixed-timing plans at municipal intersections across Germany and Austria, compressing deployment timelines for intelligent transportation systems.
- IRA Infrastructure Allocations:The Inflation Reduction Act channels dedicated funding toward smart city deployments in US metropolitan areas, mandating V2X-ready controller architectures for federal reimbursement eligibility.
- LED Retrofit Mandates:National energy efficiency directives in India and China are accelerating replacement of incandescent signal heads, creating synchronized demand for compatible controller firmware upgrades.
Market Restraints
- Semiconductor Supply Concentration:Controller PCB assembly depends on packaging capacity concentrated in Shenzhen and Suzhou, exposing procurement timelines to geographic supply disruptions.
- NEMA TS2 Certification Friction:Hardware interoperability testing against evolving Transportation Management Center protocols extends product validation cycles by 8-14 months for new market entrants.
- Legacy Infrastructure Lock-in:Fixed-time electromechanical controllers installed in North American municipalities during the 1990s require complete intersection rewiring for adaptive system compatibility, inflating project costs.
Strategic Opportunities
- Vehicle-to-Infrastructure Integration:Convergence of DSRC and C-V2X communication protocols creates first-mover advantage for controllers supporting dual-stack connectivity at highway management installations.
- Smart Cities Mission Procurement:India's structured tender pathways favor vendors with domestic manufacturing partnerships, opening volume contracts for LED-based adaptive systems in tier-2 urban centers.
- Cybersecurity Certification Services:Emerging mandates from US DOT and EU agencies for connected infrastructure security auditing create recurring revenue streams beyond hardware sales.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware development for ATC architectures requires specialized expertise in real-time operating systems that municipal traffic engineering departments cannot source internally.
- Multi-Agency Coordination Complexity:Intersection upgrades involving state DOTs, municipal public works, and utility companies fragment decision authority and compress vendor margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traffic Signal Controller Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Control, Centralized Control, Isolated Control, Hybrid Control Technology: LED, Smart Sensors, GSM, Ethernet Application: Urban Traffic, Highway Management, Emergency Services, Intersections End User: Cities, Municipalities, Transportation Agencies, Contractors |
| Companies Covered | Sumitomo Electric Industries, Aldridge Traffic Controllers, Siemens Mobility, Indra Sistemas, Yunex Traffic, Econolite, Johnson Controls International, Traffic Technologies, SWARCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traffic Signal Controller Market Emerging Trajectories
Software-defined signal control is supplanting hardware-centric legacy architectures, while edge computing deployment at intersection cabinets enables processing latency reductions that real-time optimization algorithms require.
Machine-vision detection systems using thermal and optical sensor fusion are digitizing traffic data collection at intersection approaches. Municipal transportation agencies in Nordic markets with extreme weather requirements are deploying these systems at 40% of new installations. The technology is digitizing how vehicle presence, classification, and pedestrian movement data flow into signal timing engines, eliminating inductive loop maintenance costs.
The EU F-Gas Regulation and linked municipal infrastructure grants are accelerating LED retrofit demand by conditioning carbon reduction targets on signal head efficiency standards. German and Austrian deployments now require interoperability certification against evolving smart city data exchange protocols. Controller vendors are responding by embedding open API architectures that Transportation Management Centers can integrate without proprietary gateway hardware.
Outcome-based maintenance contracts are displacing traditional capital procurement for signal system upgrades. State DOTs in the United States are bundling hardware, software licensing, and 10-year field service into per-intersection annual fees. This shift is most visible in California and Texas, where municipal budget constraints favor operational expenditure classification over bonded infrastructure debt.
Traffic Signal Controller Market Segmentation
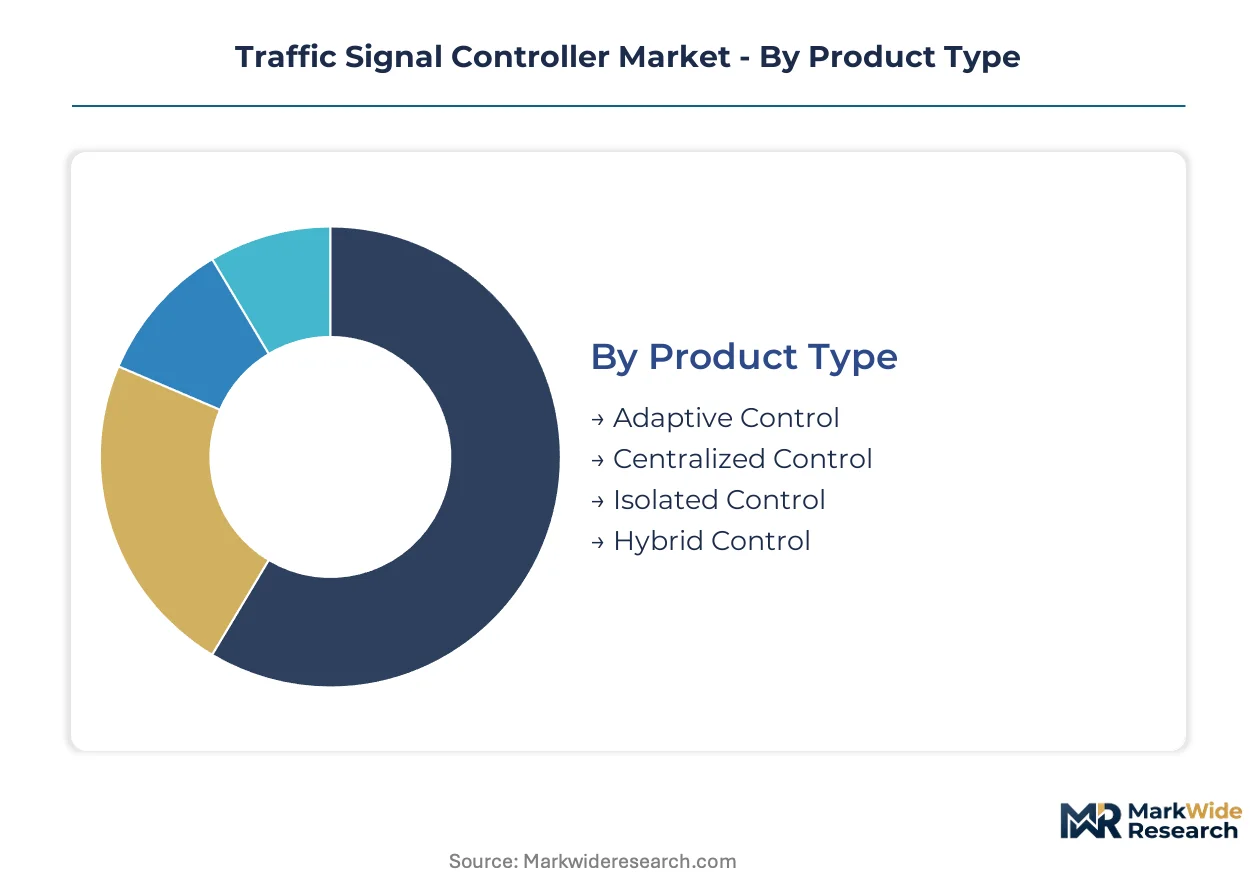
Traffic signal controller procurement patterns diverge sharply across deployment contexts. Cycle times, certification requirements, and integration complexity create distinct commercial profiles for each segment category.
Product Type:
Replacement cycles stretch from 15-year electromechanical installations to 3-5 year software refresh schedules for connected adaptive platforms.
- Adaptive Control:Real-time optimization engines process machine-vision and sensor inputs to adjust signal phasing dynamically. German and Austrian municipal deployments are compressing installation timelines as federal infrastructure funding prioritizes intelligent intersection management over fixed-timing legacy systems.
- Centralized Control:Networked architectures synchronize multiple intersections through Transportation Management Center oversight. State DOTs in the United States favor these systems for highway corridor management where coordinated signal progression reduces congestion.
- Isolated Control:Standalone intersection units operate independent timing plans without external communication links. These systems persist in smaller municipalities with constrained IT infrastructure and limited maintenance staffing.
- Hybrid Control:Dual-mode units switch between centralized and isolated operation based on network availability. This architecture addresses resilience requirements in regions with intermittent connectivity.
Isolated Control dominates installed base. Adaptive Control is where expansion concentrates.
Technology:
Cost tiers separate mature commodity components from emerging premium sensor platforms with embedded processing capabilities.
- LED:Solid-state signal heads consume 85% less energy than incandescent predecessors while delivering superior visibility and maintenance intervals. India's BIS certification mandates and national energy efficiency directives are synchronizing demand for compatible controller firmware across tier-2 urban centers.
- Smart Sensors:Thermal-optical fusion devices classify vehicles, detect pedestrians, and queue lengths at intersection approaches. Nordic municipalities with extreme weather requirements are deploying these systems at 40% of new installations to eliminate inductive loop maintenance.
- GSM:Cellular communication modules enable remote monitoring and over-the-air firmware updates for distributed controller networks. This technology serves as a bridge infrastructure where fiber deployment remains uneconomical.
- Ethernet:Wired connectivity supports high-bandwidth data exchange between intersection cabinets and central traffic management platforms. Highway management installations specify these interfaces for real-time coordination across extended corridor distances.
LED technology commands volume leadership. Smart Sensors are climbing the fastest on vehicle-to-infrastructure integration pilots.
Application:
Margin structures invert between high-volume urban deployments and certification-intensive highway corridors.
- Urban Traffic:Dense intersection networks in metropolitan cores generate the largest hardware volumes. Municipal procurement in China and India concentrates here, with Shenzhen and Suzhou manufacturing clusters supplying LED-based controller assemblies.
- Highway Management:Extended procurement cycles and stringent NEMA TS2 certification requirements sustain superior margin pools. Federal infrastructure bills in the United States are reshaping funding availability for these corridor-scale installations.
- Emergency Services:Preemption systems override standard signal timing to clear paths for fire, ambulance, and police vehicles. These specialized applications require hardened communication protocols and redundant activation mechanisms.
- Intersections:Individual junction upgrades constitute the fundamental unit of deployment. Legacy fixed-time electromechanical controllers from the 1990s require complete rewiring for adaptive compatibility, inflating project costs.
Urban Traffic anchors shipment volumes. Highway Management offers the steepest expansion trajectory on adaptive corridor investments.
End User:
Decision authority fragments across organizational boundaries with divergent procurement authority and technical capabilities.
- Cities:Municipal traffic engineering departments manage dense downtown networks with constrained capital budgets. Outcome-based maintenance contracts are displacing traditional hardware procurement in California and Texas.
- Municipalities:Smaller urban jurisdictions prioritize reliability and low maintenance over advanced optimization features. These buyers favor isolated control systems with predictable replacement cycles.
- Transportation Agencies:State and provincial DOTs coordinate multi-jurisdictional corridor projects with standardized specifications. The US Federal Highway Administration's MUTCD guidelines shape their interoperability requirements.
- Contractors:System integrators and installation firms influence component selection through design-build contracts. Their recommendations carry weight where municipal engineering departments lack embedded systems expertise.
Transportation Agencies control premium highway segments. Cities are gaining share fastest on smart city deployment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Federal Highway Administration's MUTCD guidelines and NEMA TS2 standards anchor procurement protocols across North American municipal transportation agencies. Federal infrastructure bills are accelerating adaptive signal system deployments in metropolitan corridors.
United States
State DOTs in California and Texas are bundling hardware, software licensing, and field service into per-intersection annual fees. The Inflation Reduction Act channels dedicated funding toward smart city deployments, mandating V2X-ready controller architectures for federal reimbursement eligibility. Municipal procurement concentrates in these two states due to outcome-based contract innovation.
Germany
Federal infrastructure funding prioritizes intelligent intersection management over fixed-timing legacy systems across German metropolitan networks. The EU Green Deal and F-Gas Regulation condition municipal infrastructure grants on carbon reduction targets, accelerating LED retrofit demand. Siemens Mobility leverages its European rail signaling heritage to anchor deployments across German and Austrian corridors.
China
National energy efficiency directives are accelerating replacement of incandescent signal heads, creating synchronized demand for compatible controller firmware upgrades. MIIT standards shape domestic manufacturing protocols for embedded traffic systems. Shenzhen and Suzhou manufacturing clusters dominate semiconductor packaging and PCB assembly capacity for LED-based controller exports.
India
BIS certification mandates and Smart Cities Mission funding create structured procurement pathways that favor vendors with domestic manufacturing partnerships. The national Smart Cities Mission prioritizes tier-2 urban centers for LED-based adaptive system deployments. Manufacturing partnerships in Gujarat and Maharashtra position vendors for volume contracts in emerging municipal markets.
Austria
Real-time traffic optimization using machine-vision detection is replacing fixed-timing plans at municipal intersections, compressing deployment timelines for intelligent transportation systems. EU Green Deal conditionality links federal infrastructure grants to interoperability certification against evolving smart city data exchange protocols. Vienna and Salzburg metropolitan areas concentrate adaptive corridor investments.
Traffic Signal Controller Market Vendor Landscape
Industrial conglomerates and specialized traffic technology firms split the market between scale-driven municipal procurement and premium adaptive system integration. The vendor base concentrates around three strategic archetypes: diversified industrial groups with rail signaling heritage, dedicated intelligent transportation specialists with optical manufacturing capabilities, and regional system integrators with deep state DOT channel relationships. Competitive positioning hardens through M&A consolidation of firmware capabilities and strategic partnerships for V2X communication stack integration.
Among diversified industrial groups, Siemens Mobility and Sumitomo Electric Industries occupy positions that leverage cross-modal signaling expertise into intersection management platforms. Within the specialized tier, Econolite anchors North American municipal procurement through channel relationships with state DOTs and city traffic engineering departments. SWARCO exemplifies the optical specialization archetype through lens manufacturing capabilities that sustain premium positioning in Nordic markets with extreme weather requirements.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Aldridge Traffic Controllers |
| Siemens Mobility |
| Indra Sistemas |
| Yunex Traffic |
| Econolite |
| Johnson Controls International |
| Traffic Technologies |
| SWARCO |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Shenzhen and Suzhou semiconductor packaging facilities is compressing controller PCB assembly margins while simultaneously extending supplier payment terms for tier-2 municipal buyers. This utilization dynamic forces North American and European vendors to absorb cost volatility through firmware differentiation rather than hardware premiumization.
Pricing Analysis
Price spreads between German-engineered adaptive systems and Chinese-manufactured LED controllers exceed three-to-one at the municipal procurement tier. Three-tier pricing structure across premium adaptive platforms, standard centralized architectures, and economy isolated units dominates contract structures. Price differentiation rests on NEMA TS2 certification grade and bundled cybersecurity audit services. Cost compression in the standard tier is intensifying because Indian and Chinese vendors are flooding tier-2 urban markets with BIS-compatible alternatives. Municipal traffic engineering departments exhibit highest price sensitivity; state DOTs with federal infrastructure allocations show least.
Supply Chain Analysis
Silicon feedstock for controller microprocessors draws from Taiwan, South Korea, and the United States. PCB substrate materials and LED driver components hinge on Chinese manufacturing clusters in Guangdong and Jiangsu provinces. Single-source vulnerability around advanced node semiconductor packaging creates procurement timeline exposure for adaptive system vendors. Distribution runs through state DOT-approved system integrators who influence municipal specification compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based maintenance contracts are expanding faster than hardware shipments as California and Texas municipalities shift capital budgets to operational expenditure classification. Firmware-as-a-service layers now generate recurring revenue streams that hardware margins cannot match.
For Market Incumbents: Insulate adaptive algorithm portfolios through captive machine-vision sensor development and exclusive Transportation Management Center integration partnerships. Open API architectures from emerging European vendors threaten proprietary gateway hardware revenue. Certification investment in dual-stack DSRC and C-V2X protocols locks in highway corridor deployments before federal reimbursement eligibility windows narrow. For New Entrants and Emerging Players: Tier-2 Indian urban centers with Smart Cities Mission funding represent the most penetrable entry point for LED-adaptive hybrid controllers with domestic manufacturing partnerships. Nordic municipalities with extreme weather requirements offer white-space for thermal-optical fusion detection systems where SWARCO's optical heritage has not fully penetrated. Go-to-market through Gujarat and Maharashtra manufacturing joint ventures bypasses BIS certification friction for volume contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors bundling 10-year field service with per-intersection annual fees rather than transactional hardware sales. Long-term viability over the next decade favors acquisition targets with embedded systems firmware capabilities and existing state DOT channel relationships. The signal to watch is Transportation Management Center procurement standardization around open API architectures versus proprietary protocol lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | US DOT and EU agency mandates create recurring audit revenue beyond controller hardware sales. |
| Domestic Manufacturing Partnership | Indian Smart Cities Mission procurement pathways favor vendors with Gujarat and Maharashtra production presence. |
| Open API Architecture Deployment | German and Austrian smart city data exchange protocols require interoperability without proprietary gateway hardware. |
| Dual-Stack V2X Integration | DSRC and C-V2X protocol support captures first-mover advantage at federal infrastructure-funded highway installations. |
| Machine-Vision Sensor Fusion Development | Thermal-optical detection eliminates inductive loop maintenance costs in Nordic extreme weather deployments. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with municipal traffic engineering directors, state DOT procurement officers, intelligent transportation system integrators, and embedded systems firmware architects; and secondary validation through FHWA MUTCD guideline revisions, NEMA TS2 certification databases, EU Green Deal infrastructure grant disclosures, and Indian Smart Cities Mission tender documentation. Bottom-up shipment triangulation against top-down municipal budget allocation analysis anchored volume estimates.
Forecast inputs considered adaptive versus fixed-time controller replacement cycles, LED retrofit mandate compliance timelines, and V2X communication standard adoption curves across the projection horizon. Segmentation dimensions modeled include control architecture type, signal head technology tier, application context from urban intersection to highway corridor, and end-user procurement authority from municipal engineering departments to state transportation agencies. CAGRs were derived from intersection installation run rates and firmware refresh schedules rather than extrapolated macro trends.
Macroeconomic conditions sit as an overlay; deviation in federal infrastructure appropriation levels, semiconductor packaging capacity utilization, and municipal bond market access would shift the trajectory. Forecasts reflect documented assumptions around NEMA TS2 certification timeline stability and V2X protocol standardization convergence. Cross-checking against state DOT 10-year capital improvement plan disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
Global Smart Parking Solutions Market
Smart Transportation Solutions
Smart Rail Suite Solutions Market
Smart Transportation Solutions
Physical Internet (PI) Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Smart Parking Systems Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Global Electric Public Transport Market