
 Air Taxi Market | 2026-2036
Air Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Air Taxi Market Intelligence
Modular aircraft configurations, where manufacturers unbundle propulsion, avionics, and cabin systems, is expanding buyer choice across procurement models. Joby Aviation leverages composite airframe manufacturing to sustain its position in full-stack vehicle integration. EHang Holdings anchors its presence through autonomous flight software that controls multi-rotor coordination. Lilium competes with a fixed-wing electric jet design that differentiates its range profile against tilt-rotor alternatives.
An air taxi is a short-range, electrically propelled aircraft designed for on-demand passenger or cargo transport within and between urban areas, typically operating at cruise speeds between 110 and 200 knots with battery capacities exceeding 140 kWh. These vehicles employ distributed electric propulsion with six to twelve rotors to achieve vertical lift and transition to wing-borne flight, serving the primary purpose of reducing ground congestion through three-dimensional mobility corridors. Electric propulsion systems currently lead development investment due to their direct contribution to operating cost reduction, while autonomous flight technology represents the fastest-growing capability segment as regulators in multiple jurisdictions draft certification pathways for pilotless operations. Battery storage remains the margin-critical subsystem, with energy density improvements determining viable route lengths and payload economics.
The FAA oversees type certification and operational rules for urban air mobility in the United States, while EASA establishes equivalent safety standards across European airspace, and China's CAAC coordinates low-altitude flight zone designations that shape market access timelines. These regulators collectively determine airworthiness requirements, pilot qualification thresholds, and vertiport infrastructure standards that gate commercial deployment. Stakeholders must monitor certification milestone progress against operational rulemaking schedules to time fleet commitments and infrastructure investments.
Market Dynamics
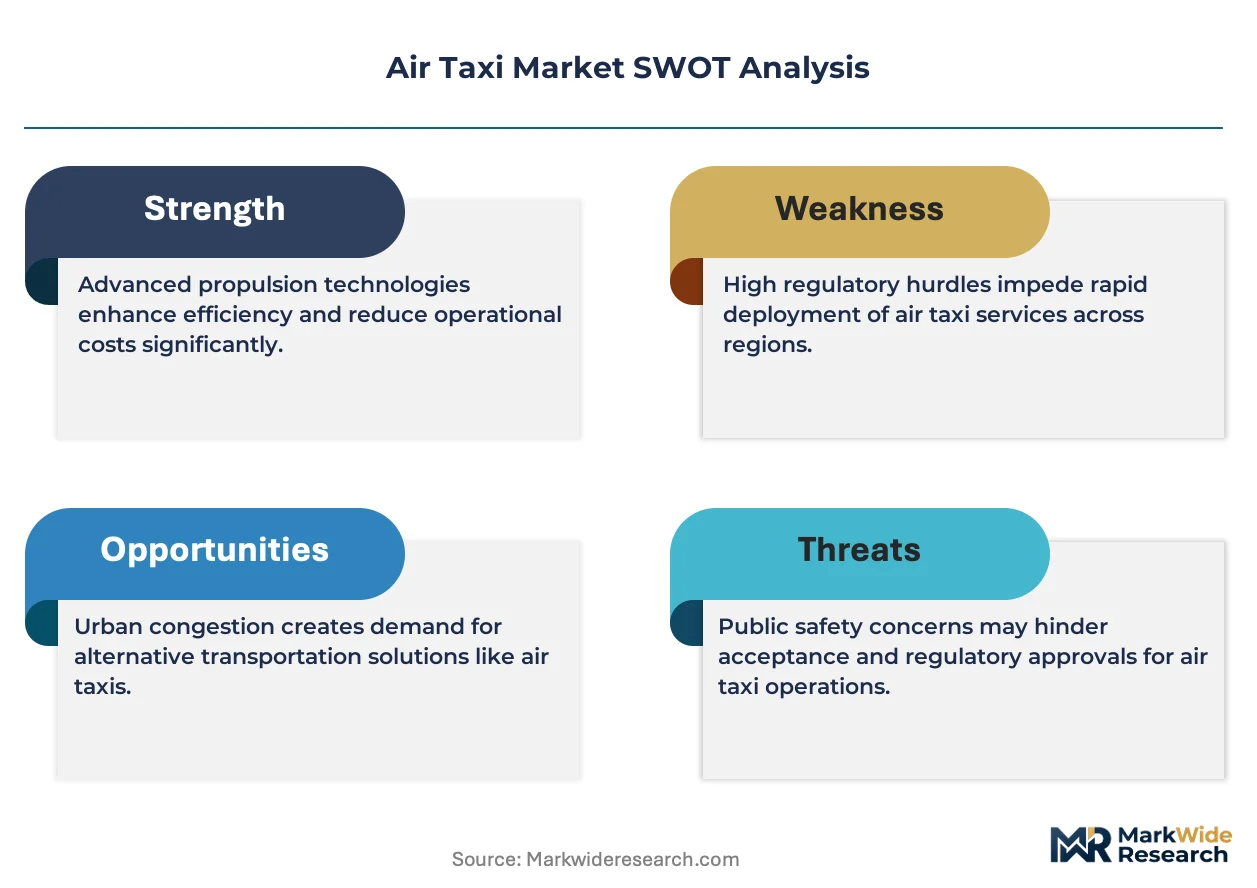
Battery energy density improvements are compressing certification timelines as the FAA and EASA accelerate type validation protocols for electric vertical take-off and landing aircraft.
Growth Catalysts
- FAA Part 23 Certification Pathway:The streamlined airworthiness framework for small aircraft is reducing validation cycles for electric propulsion systems in the United States.
- Vertiport Infrastructure Mandates:City governments in Germany and the United Arab Emirates are issuing construction approvals for urban landing facilities that enable fleet deployment.
- Autonomous Flight Software:Multi-rotor coordination algorithms are expanding operational envelopes without proportional pilot cost increases.
Market Restraints
- Lithium-Ion Supply Concentration:Cathode material processing capacity clusters in China, creating input cost volatility for battery pack assembly.
- Airspace Integration Friction:The FAA's operational rulemaking for urban air mobility remains incomplete, delaying commercial service authorizations.
- Helicopter Substitution Threat:Conventional rotorcraft maintain payload flexibility and established maintenance networks for inter-city routes.
Strategic Opportunities
- United Arab Emirates Low-Altitude Zones:Dubai's designated flight corridors offer regulatory sandbox conditions for pilotless operation trials.
- Medical Emergency Application:Organ transport and trauma response services present premium pricing potential for dedicated fleet segments.
- Solid-State Battery Convergence:Next-generation cell chemistry paired with thermal management systems could double viable route distances.
Industry Challenges
- Certified Pilot Shortage:The FAA's type rating requirements for electric aircraft lack established training pipelines, constraining crew availability.
- Vertiport Real Estate Intensity:Urban land acquisition for take-off and landing facilities demands capital commitments before revenue generation.
- Air Traffic Control Integration:Legacy radar and communication systems require software upgrades to coordinate autonomous vehicle separation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Taxi Market |
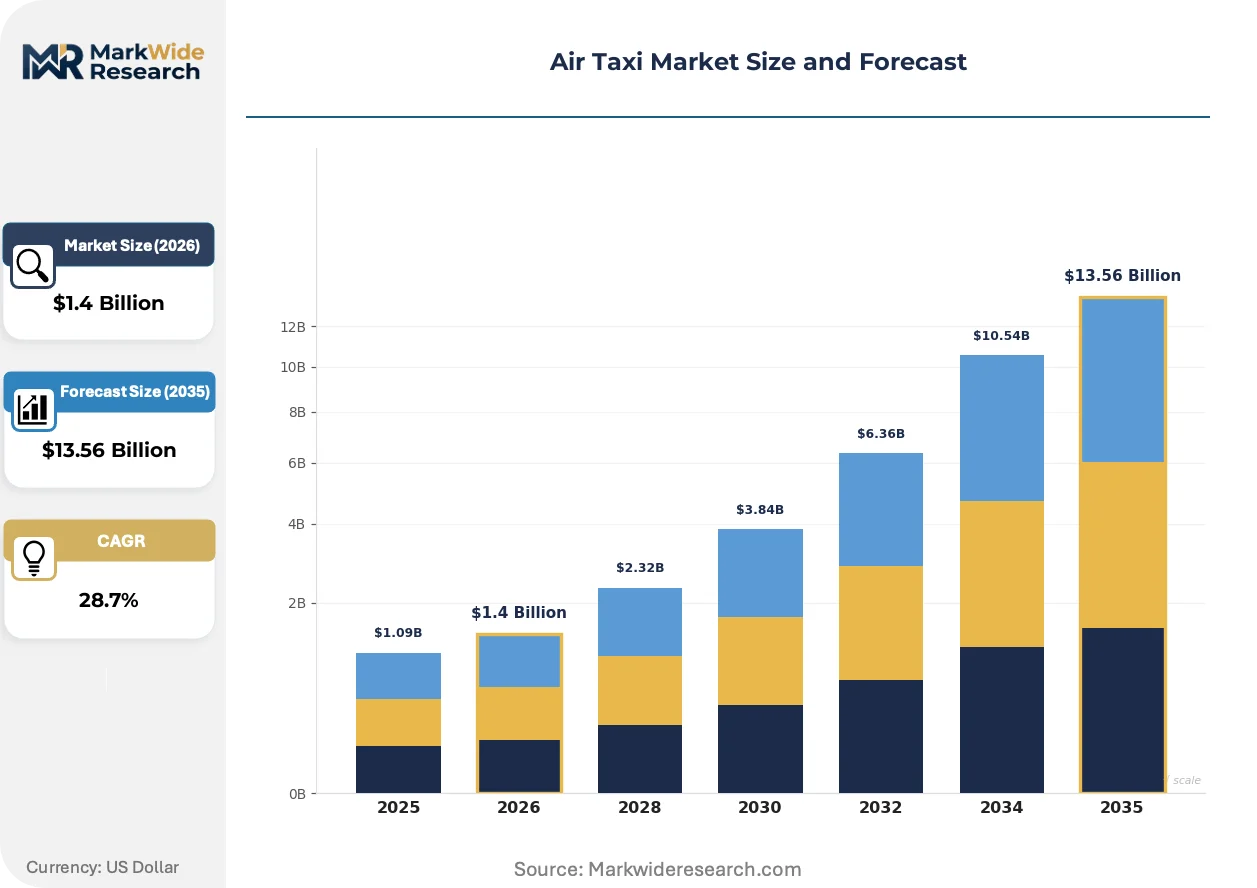
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Drone, Vertical Take-Off and Landing, Hybrid Aircraft, Electric Aircraft Service Type: Intercity Travel, Urban Transport, Emergency Services, Freight Transport Technology: Autonomous Flight, Electric Propulsion, Avionics Systems, Battery Storage Customer Type: Private Passengers, Corporate Clients, Government Entities, Tourists |
| Companies Covered | Volocopter, Wisk Aero, Joby Aviation, Flycopter, Sarla Aviation, Archer Aviation, Lilium, Vertiflier, EHang Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Taxi Market Strategic Shifts & Innovations
Distributed electric propulsion architectures are displacing conventional powertrain designs across vehicle development programs, while regulatory bodies draft certification pathways that accommodate autonomous systems.
Solid-state battery cells are integrating silicon-anode configurations that achieve energy densities exceeding 400 Wh per kilogram. Aircraft manufacturers in Germany and the United States are adopting these packs for prototype flight testing. This chemistry transition is integrating extended-range route planning into commercial service models previously limited by lithium-ion constraints.
EASA's Special Condition for small-category vertical take-off aircraft is establishing noise certification thresholds below seventy decibels during approach. European manufacturers are redesigning rotor geometries to meet these acoustic limits. Urban operators in Germany and France are prioritizing these quieter platforms for night flight approvals.
Corporate fleet managers are consolidating procurement decisions through direct manufacturer relationships rather than regional aviation service providers. Large employers in Dallas and Shenzhen are negotiating dedicated capacity agreements that bypass traditional charter intermediaries. This channel compression is most pronounced in technology and financial services verticals where executive time valuation supports premium pricing.
Air Taxi Market Segmentation
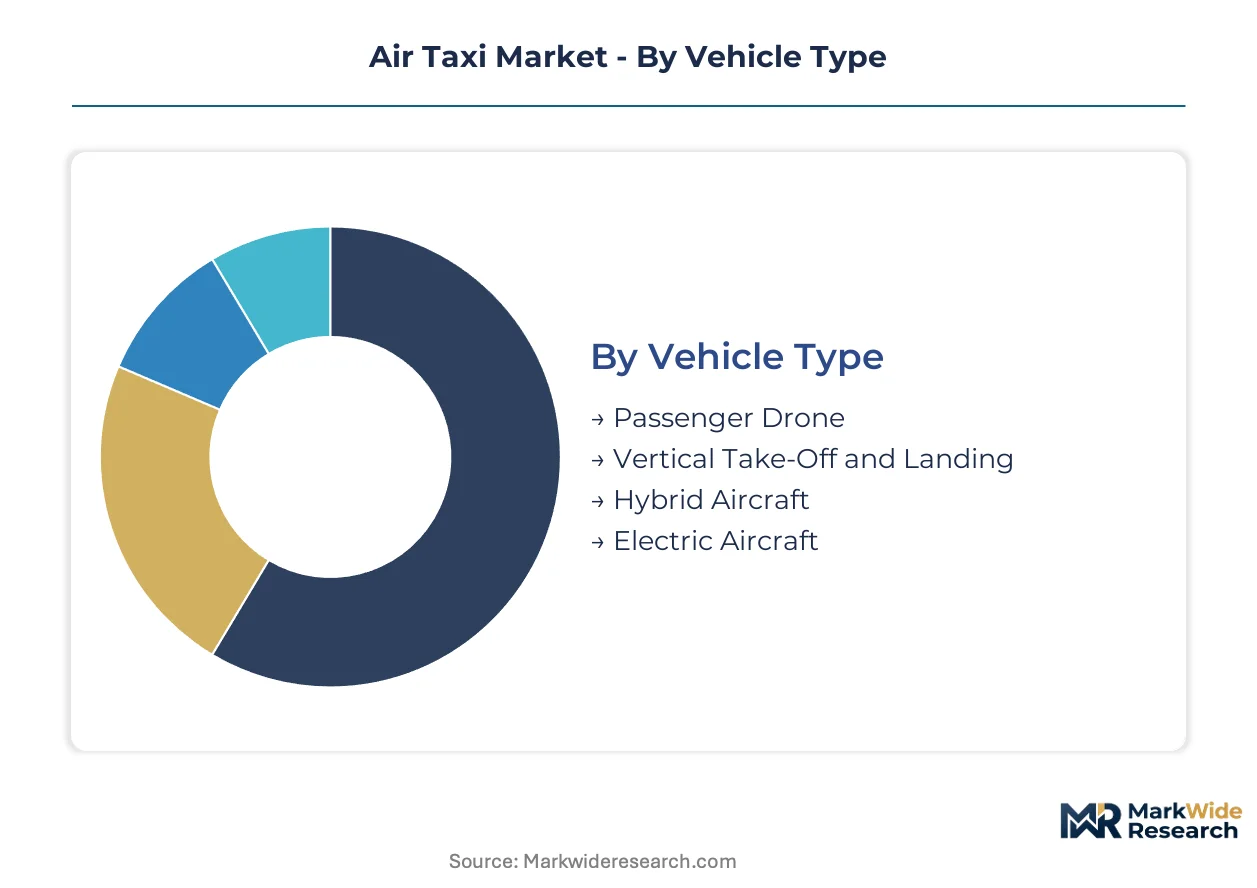
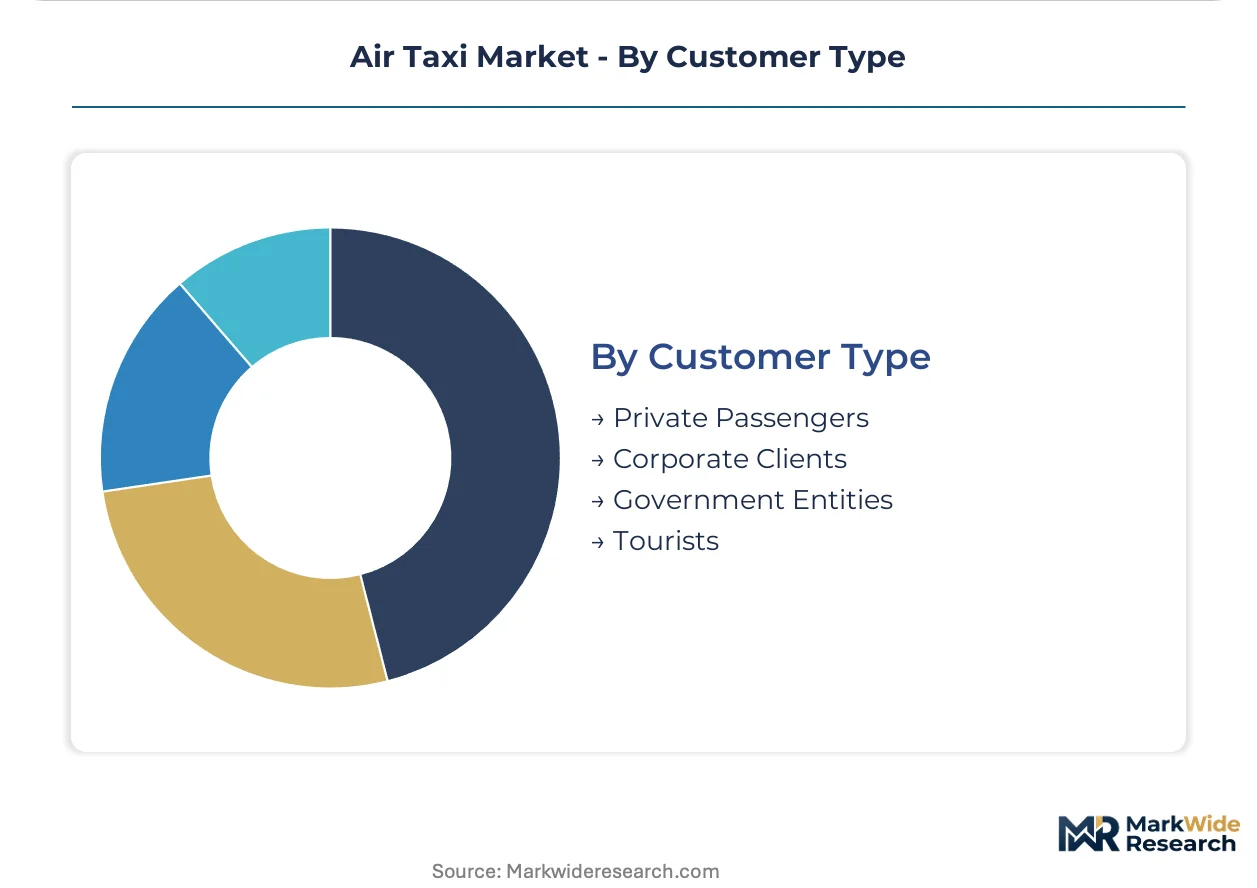
Air taxi market segmentation reveals how procurement decisions split across vehicle architectures, operational missions, and buyer risk profiles. Fleet managers weight range requirements against vertiport compatibility when selecting platforms, while service providers calibrate pricing tiers to passenger willingness-to-pay for time savings.
Vehicle Type:
Buyers differentiate primarily by range requirements and infrastructure dependencies rather than upfront capital cost alone.
- Vertical Take-Off and Landing:Tilt-rotor configurations dominate current fleet commitments due to their ability to transition between hover and wing-borne flight. Dallas and Shenzhen corporate shuttle contracts favor these platforms for their 150-kilometer operational radius without runway access.
- Electric Aircraft:Fixed-wing electric designs with distributed propulsion achieve superior energy efficiency on longer corridors. German operators prioritize these for inter-city routes where dedicated airstrip access exists.
- Passenger Drone:Compact multi-rotor vehicles serve last-mile connectivity in dense urban cores.
- Hybrid Aircraft:Range-extended configurations using turbine generators address battery density limitations for rural deployment.
Vertical Take-Off and Landing leads volumes today; Electric Aircraft is gaining share fastest.
Service Type:
Mission profiles determine fleet utilization rates and regulatory pathway complexity.
- Urban Transport:Point-to-point commuter services command the highest trip frequency with predictable demand patterns. Dubai's designated low-altitude corridors enable pilotless trials that compress operating costs below helicopter alternatives.
- Emergency Services:Medical evacuation and organ transport contracts secure premium pricing through guaranteed response windows. United States hospital networks in Texas and California are negotiating dedicated capacity agreements.
- Intercity Travel:Regional connections compete with rail and road for business travelers.
- Freight Transport:Time-critical cargo applications exploit payload flexibility for logistics consolidation.
Urban Transport leads volumes today; Emergency Services is expanding most quickly.
Technology:
Development investment concentrates on subsystems that determine certification timelines and operating economics.
- Battery Storage:Energy density above 400 watt-hours per kilogram enables viable commercial routes. Solid-state silicon-anode prototypes from German and United States manufacturers are entering flight testing.
- Autonomous Flight:Multi-rotor coordination algorithms reduce crew costs and extend operational hours. EASA and FAA pathway drafts for pilotless certification are accelerating software investment.
- Electric Propulsion:Distributed motor architectures replace conventional turbine powertrains.
- Avionics Systems:Sense-and-avoid integration enables airspace deconfliction without ground radar dependency.
Battery Storage leads volumes today; Autonomous Flight is climbing the fastest.
Customer Type:
Purchasing authority and budget cycles shape contract structures and fleet customization requirements.
- Corporate Clients:Technology and financial services firms in Dallas and Shenzhen negotiate direct manufacturer relationships for executive shuttle services. These buyers prioritize schedule reliability over unit cost minimization.
- Government Entities:Public procurement frameworks emphasize safety certification depth and domestic content requirements. China's CAAC coordinates low-altitude zone designations that gate market access for state-affiliated operators.
- Private Passengers:Individual bookings through app-based platforms demand price transparency.
- Tourists:Sightseeing and experience-driven consumption supports premium positioning in Dubai and Paris.
Corporate Clients leads volumes today; Government Entities is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The air taxi industry traces its commercial origins to German engineering clusters that pioneered electric vertical take-off and landing prototypes, with subsequent scaling concentrated in United States technology corridors and Chinese manufacturing hubs.
United States
Dallas and Los Angeles corporate shuttle contracts drive fleet pre-orders from technology and financial services firms. The FAA's Part 23 certification pathway for small aircraft accelerates type validation timelines for electric propulsion systems. Joby Aviation anchors manufacturing in Northern California with composite airframe production for full-stack vehicle integration.
Germany
Inter-city route demand from business travelers favors fixed-wing electric designs with dedicated airstrip access. EASA's Special Condition for small-category vertical take-off aircraft establishes noise certification thresholds below seventy decibels. Lilium exemplifies the Munich-area cluster developing fixed-wing electric jet configurations for extended range profiles.
China
Shenzhen-based employers negotiate direct manufacturer capacity agreements for executive transport services. The CAAC coordinates low-altitude flight zone designations that shape market access timelines for state-affiliated operators. EHang Holdings anchors Guangdong province presence through autonomous flight software controlling multi-rotor coordination.
United Arab Emirates
Dubai's designated low-altitude corridors enable pilotless operation trials that compress operating costs below helicopter alternatives. MOHAP and Dubai's aviation authority issue vertiport construction approvals for urban landing facilities. Volocopter leverages these regulatory sandbox conditions to advance commercial service deployment.
France
Paris metropolitan area operators prioritize quieter platforms for night flight approvals in dense urban cores. The ANSM noise certification framework aligns with EASA acoustic limits for rotor geometry redesign. Toulouse and Bordeaux aerospace clusters concentrate engineering talent for distributed electric propulsion development.
Air Taxi Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and manufacturing integration levels. The vendor base clusters around three strategic archetypes: full-stack vehicle integrators controlling airframe and propulsion design, autonomous flight software specialists commanding multi-rotor coordination, and fixed-wing electric jet developers pursuing range differentiation. Consolidation pressure operates through strategic partnerships for vertiport infrastructure access and technology licensing agreements for battery subsystem integration.
Within the full-stack integration tier, Joby Aviation and Archer Aviation represent the capital-intensive vehicle manufacturing archetype. EHang Holdings occupies a position exemplifying autonomous software-centric positioning. Lilium anchors the fixed-wing electric jet specialization vector. Volocopter and Wisk Aero sit within the European and United States-based certification-advanced cohort respectively.
| Leading Market Players |
|---|
| Volocopter |
| Wisk Aero |
| Joby Aviation |
| Flycopter |
| Sarla Aviation |
| Archer Aviation |
| Lilium |
| Vertiflier |
| EHang Holdings |
| Others |
Cost & Logistics Intelligence
Lithium carbonate spot indices cascading through cathode material contracts compress battery pack margins and force tiered pricing stratification across vehicle procurement models. Aircraft manufacturers absorb input volatility through long-term offtake agreements with Chinese and South Korean cell suppliers, while fleet operators pass residual cost exposure to corporate shuttle clients through utilization-linked subscription structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification depth and after-sales bundling intensity. Premium tiers command spreads for FAA type-certified platforms with dedicated pilot pools, while standard tiers target EASA Special Condition approvals with shared crew models. Cost compression in economy tiers intensifies as Chinese manufacturers flood prototype markets with uncertified multi-rotor alternatives. Corporate shuttle buyers in Dallas and Shenzhen exhibit lowest price sensitivity, prioritizing schedule reliability over unit economics.
Supply Chain Analysis
Freight costs for composite airframe assemblies from Northern California to German final assembly facilities add logistics burden atop already capital-intensive manufacturing. Cathode precursor processing concentrates in China, South Korea, and Japan, with aircraft battery packs drawing from this concentrated refining base. Single-source vulnerability in solid-state electrolyte materials threatens next-generation cell ramp timelines. Distribution runs through direct manufacturer relationships with fleet operators, bypassing traditional aviation service intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air taxi market compounds steadily as urban congestion costs force municipal governments to sanction three-dimensional mobility corridors. Regulatory sandbox deployments in Dubai and Shenzhen validate operational economics ahead of Western certification timelines.
For Market Incumbents: Deploy backward integration into composite airframe manufacturing to defend margin position against emerging fixed-wing electric jet developers. Lock vertiport real estate through municipal concession agreements before infrastructure competition intensifies. Prioritize FAA Part 23 certification depth as a barrier against uncertified Chinese entrants flooding price-sensitive segments.
For New Entrants and Emerging Players: Capture medical emergency service contracts in Texas and California where hospital networks negotiate guaranteed response windows at premium pricing. Target government procurement frameworks in the United Arab Emirates and China where state-affiliated operators prioritize domestic content requirements over unit cost. Lead with autonomous flight software demonstrations to differentiate against pilot-dependent incumbents.
For Investors and Strategic Acquirers: Asymmetric upside sits with autonomous software specialists controlling multi-rotor coordination algorithms rather than capital-intensive vehicle integrators. Five-to-ten-year viability hinges on solid-state battery convergence timelines rather than lithium-ion incrementalism. Watch EASA pilotless certification pathway drafts as the inflection signal for autonomous fleet deployment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Vertiport Infrastructure Partnership | Municipal concession agreements in Dubai and Shenzhen gate fleet deployment timelines. |
| Solid-State Battery Supply Agreement | German and United States cell manufacturers anchor next-generation range extension. |
| Autonomous Flight Certification Pathway | FAA and EASA draft rules determine pilotless operational economics. |
| Corporate Shuttle Capacity Contract | Direct manufacturer relationships with Dallas technology firms compress channel margins. |
| Medical Emergency Fleet Segment | Texas hospital network agreements secure premium pricing through response guarantees. |
Research Approach
Bottom-up fleet commitment modeling reconciled against top-down battery supply tracking forms the analytical core of this study. Primary interviews with aircraft certification engineers, vertiport infrastructure planners, corporate fleet procurement managers, and low-altitude zone regulators combined with secondary validation against FAA type certification databases, EASA Special Condition filings, CAAC flight zone designations, and customs records for lithium-ion cell imports. Triangulation across these sources calibrated vehicle deployment timelines against regulatory milestone schedules.
Historical trendline analysis of electric aircraft development programs established baseline progression rates across the projection horizon. Segmentation modeling incorporated vehicle architecture, service mission profile, technology subsystem, and customer purchasing authority dimensions. CAGRs derived from fleet pre-order trajectories weighted by certification pathway probability, with battery energy density improvement curves and autonomous software readiness scores as industry-specific forecast inputs.
Regulatory approval delays, cathode material supply disruptions, and airspace integration friction are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about certification timeline acceleration and infrastructure permitting velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
Fleet Management Solution Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
Connected Parking Solutions Market
Smart Transportation Solutions
Global Intelligent Traffic Management System Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Parking Space Management Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Road Profile Laser Sensor Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Global Automated Fare Collection Market