
 Europe Smart Parking Market | 2026-2036
Europe Smart Parking Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Parking Market Foresight
The capability gap between hardware-heavy incumbents and software-native entrants is rotating competitive capital allocation across the Europe smart parking landscape. Flowbird SASU leverages its manufacturing scale and pay-and-display heritage to dominate street-level meter deployments in France and Southern Europe. SKIDATA sustains technology leadership in barrier-controlled access systems for airports and commercial garages. EasyPark Group AB differentiates through mobile-first platform architecture that aggregates payment flows across fragmented municipal contracts.
Europe smart parking encompasses integrated systems combining ultrasonic or camera-based occupancy detection, dynamic pricing algorithms, and cloud-connected payment gateways to optimize vehicle storage in constrained urban space. Sensor accuracy typically achieves detection rates above detection thresholds sufficient for enforcement-grade reliability, while edge computing nodes process occupancy signals locally before transmitting aggregated status to central management platforms. IoT Solutions and Sensor-Based Systems anchor hardware procurement cycles as municipalities replace mechanical meters with networked infrastructure, though Mobile Applications capture expanding margin pools through recurring transaction fees and data monetization. Cloud Platforms represent the fastest-expanding deployment category as operators seek centralized analytics across distributed asset portfolios without on-premise server maintenance.
The EU Green Deal and F-Gas Regulation shape equipment standards by restricting refrigerants in enclosed parking ventilation systems while mandating emissions-linked congestion pricing in member states. EMA and national regulators such as Germany's KBA influence automated vehicle interface protocols where smart parking infrastructure must accommodate emerging autonomous valet functions. Stakeholders should monitor how CE marking requirements evolve for AI-enabled license plate recognition systems and whether the EU AI Act imposes additional conformity burdens on predictive parking availability algorithms.
Market Dynamics
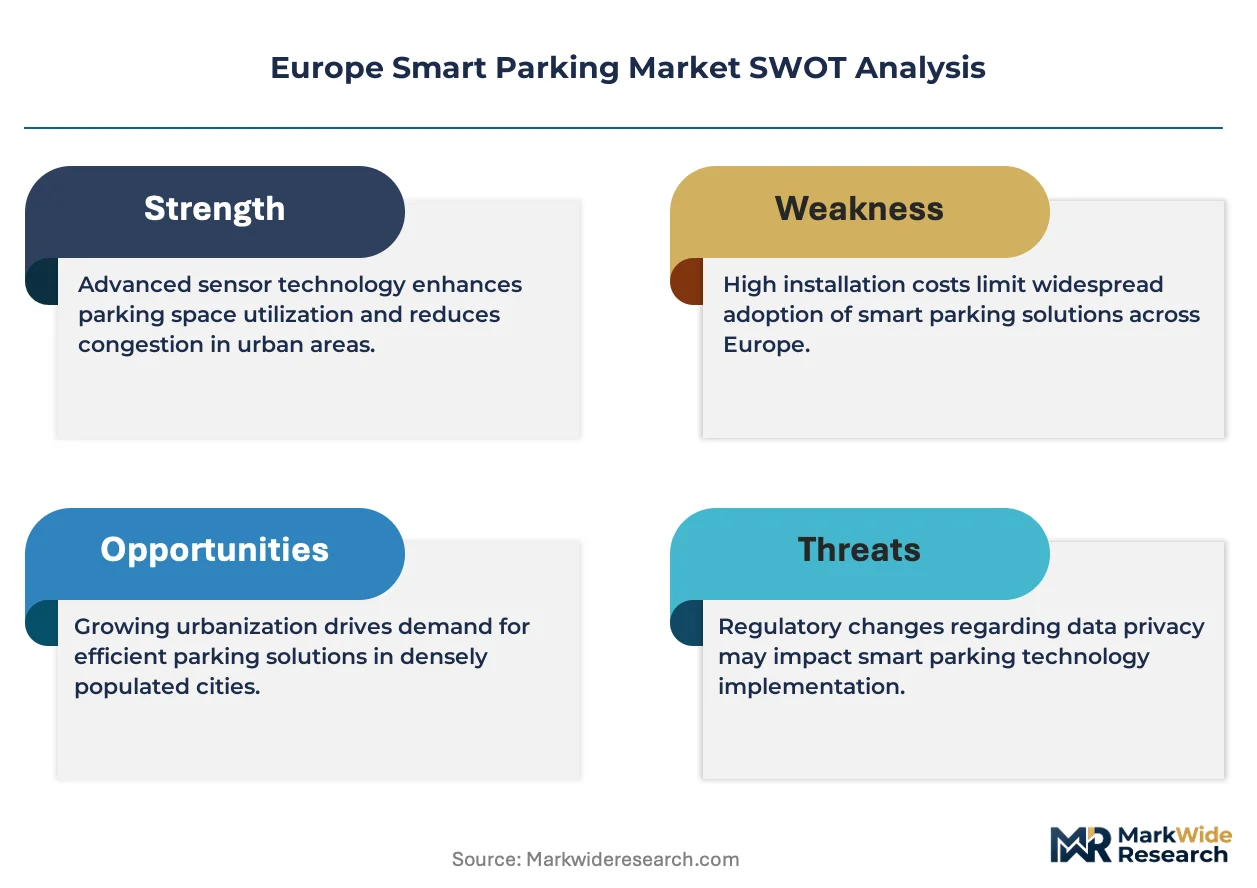
The EU Green Deal's congestion pricing mandates are forcing municipalities to replace mechanical parking infrastructure with networked sensor systems that integrate real-time occupancy data into multimodal transport platforms.
Growth Catalysts
- EU Green Deal mandates:Member states must deploy emissions-linked congestion pricing mechanisms that require connected parking platforms for enforcement-grade data capture.
- Edge computing nodes:Local processing of ultrasonic and camera-based occupancy signals reduces latency for real-time space availability updates.
- German metropolitan procurement:Cities including Berlin and Munich are bundling smart parking contracts with public transit digitization initiatives.
Market Restraints
- CE marking complexity:AI-enabled license plate recognition systems face evolving conformity assessment timelines that delay deployment.
- Semiconductor input volatility:Sensor manufacturing depends on specialized chip supply chains concentrated in East Asian foundries.
- Legacy meter stranded assets:Municipalities with recent pay-and-display investments resist full infrastructure replacement cycles.
Strategic Opportunities
- Polish urban corridors:Warsaw and Krakow lag Western European digitization, creating first-mover advantages for integrated platform providers.
- Autonomous valet interfaces:Automated vehicle protocols require parking infrastructure with vehicle-to-infrastructure communication capabilities.
- Data monetization channels:Aggregated occupancy patterns enable predictive analytics services for urban logistics and retail site selection.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for low-power IoT sensors competes with broader automotive electronics talent pools.
- Interoperability certification:Multi-vendor platform integration requires testing against divergent municipal API standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Parking Market |
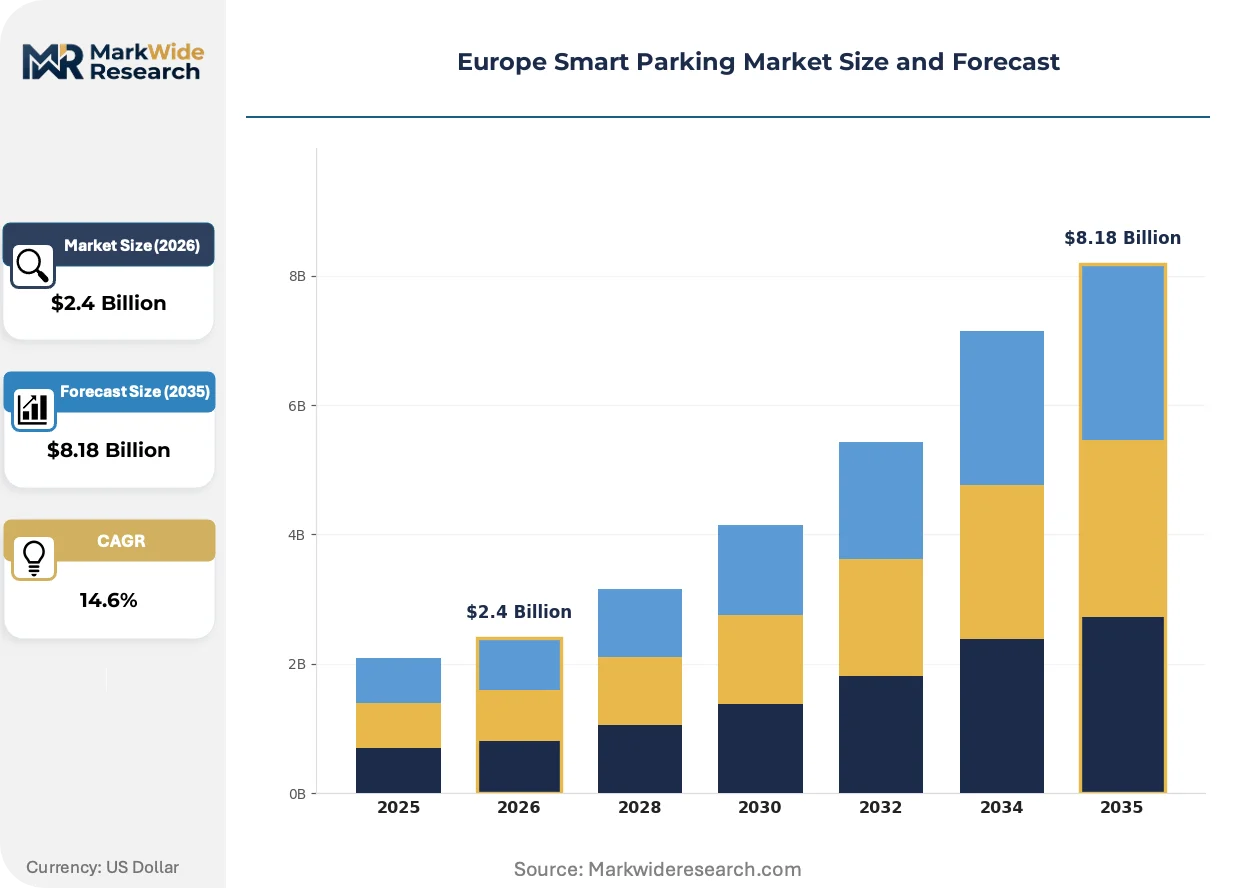
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Sensor-Based Systems, Mobile Applications, Cloud Platforms Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Municipalities, Commercial Parking Operators, Fleet Operators, Private Users Service Type: Backend Management, Customer Support, Installation Services, Maintenance |
| Companies Covered | Flowbird SASU, Urbiotica SL, Indigo Group S.A., SWARCO, Cleverciti Systems GmbH, Q-Park NV, Daimler Mobility, SKIDATA, EasyPark Group AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Parking Market Shifts & Advancements
Edge-to-cloud architecture is decomposing traditional hardware-software bundles in parking infrastructure, enabling modular procurement that separates sensor hardware from analytics platforms.
Ultrasonic detection arrays paired with camera-based verification systems is decomposing single-sensor reliability constraints. German airport operators and French municipal garages are adopting redundant detection stacks to achieve enforcement-grade accuracy thresholds. This convergence is compressing maintenance windows while expanding permissible use cases to fine issuance and automated barrier control.
The EU AI Act's risk classification framework for automated decision systems is imposing algorithmic transparency requirements on predictive parking availability engines. Operators must document training data provenance and model performance metrics for municipal procurement compliance. French and Dutch regulators are piloting conformity assessment protocols that will likely extend to license plate recognition modules by 2026.
Fleet managers and logistics operators are consolidating parking procurement through centralized platforms that aggregate fragmented municipal contracts. This aggregation bypasses traditional meter-specific payment silos and captures volume-based transaction fee reductions. The pattern is most pronounced in German commercial corridors where last-mile delivery density justifies enterprise-grade parking subscriptions over ad-hoc consumer payments.
Europe Smart Parking Market Segmentation
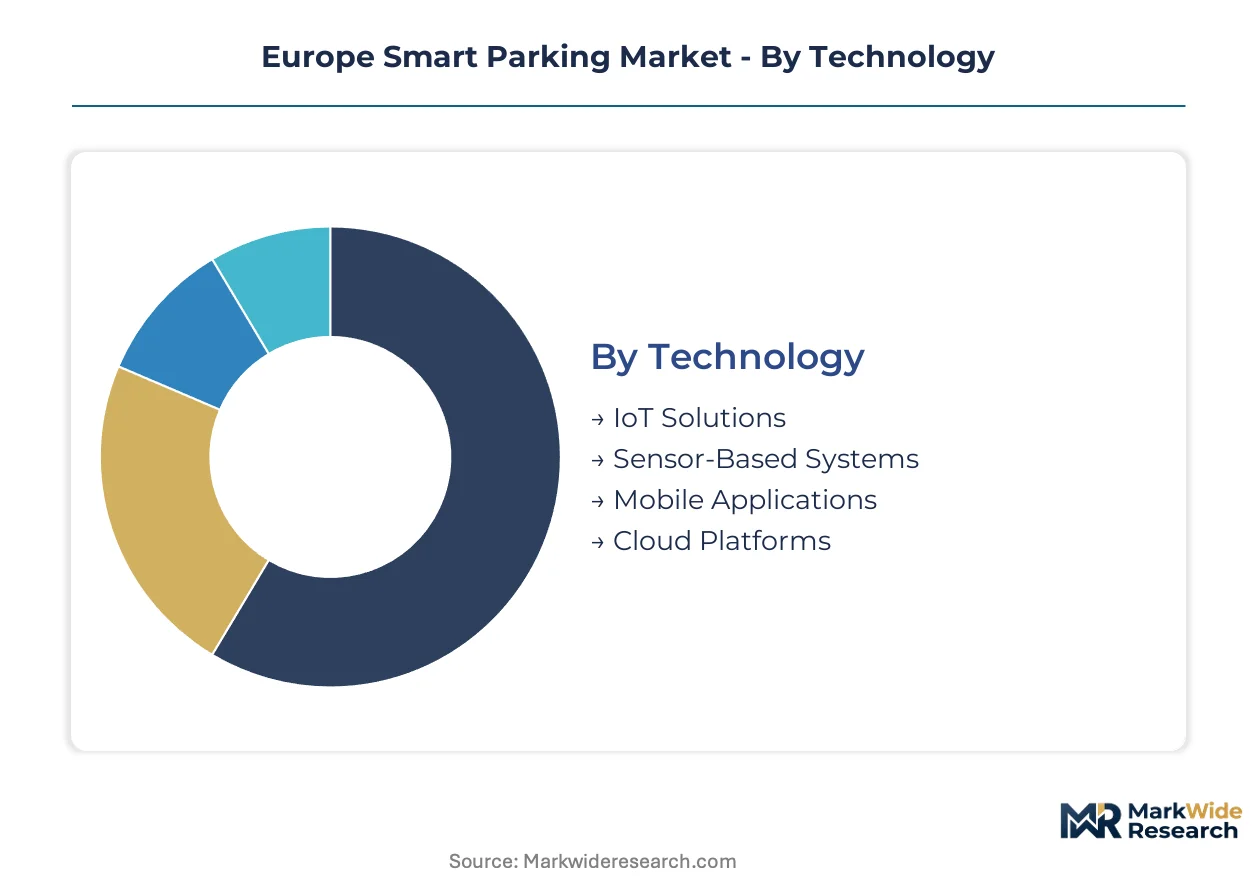
Technology heterogeneity across European smart parking creates distinct procurement channels where hardware-heavy segments flow through municipal tender processes while software-native offerings monetize via recurring SaaS contracts. Deployment architecture further fragments competitive positioning between legacy infrastructure retrofit opportunities and greenfield connected platforms.
Technology:
Hardware-centric segments dominate municipal procurement channels through capital expenditure cycles, while software layers capture recurring revenue via transaction fees and platform subscriptions.
- IoT Solutions:Networked sensor arrays combining ultrasonic detection with low-power wide-area connectivity enable real-time occupancy monitoring across distributed urban assets. German metropolitan authorities in Berlin and Munich are consolidating procurement of these systems with multimodal transport digitization initiatives driven by EU Green Deal compliance timelines.
- Sensor-Based Systems:Standalone detection hardware using magnetic, infrared, or camera-based technologies provides enforcement-grade reliability for fine issuance and barrier control. French municipal garages and German airport operators are deploying redundant detection stacks to achieve accuracy thresholds required for automated enforcement.
- Mobile Applications:Consumer-facing payment aggregation platforms bypass traditional meter-specific silos through unified digital wallets.
- Cloud Platforms:Centralized analytics infrastructure enables remote asset management without on-premise server maintenance.
By volume, Sensor-Based Systems leads procurement cycles. By growth pace, Cloud Platforms are expanding most quickly.
Deployment:
Cost tier stratification separates premium edge-computing deployments from standardized cloud migrations, with hybrid architectures capturing mid-budget municipal transitions.
- On-Premise:Legacy server infrastructure maintained within municipal IT facilities retains control over sensitive enforcement data but requires dedicated technical staffing. Eastern European municipalities with constrained cloud adoption timelines continue procuring these systems for regulatory data sovereignty compliance.
- Cloud-Based:Fully outsourced infrastructure eliminates capital expenditure for server hardware while enabling rapid scaling across distributed parking portfolios. Dutch and French operators are migrating toward these deployments to reduce maintenance overhead and accelerate feature deployment cycles.
- Hybrid:Split architectures process sensitive occupancy data locally while pushing anonymized analytics to centralized cloud repositories.
- Edge Computing:Distributed processing nodes at sensor locations minimize latency for real-time availability updates.
By installed base, On-Premise retains dominance. By replacement velocity, Cloud-Based deployments are gaining share fastest.
End User:
Customer type concentration varies sharply across contract structures, with municipalities driving multi-year tender volumes while fleet operators consolidate fragmented purchasing through enterprise platforms.
- Municipalities:Public sector procurement accounts for street-level infrastructure deployment through competitive tender processes governed by EU public procurement directives. German and French cities are bundling smart parking contracts with broader urban mobility platform integrations.
- Commercial Parking Operators:Private garage and lot managers prioritize revenue optimization through dynamic pricing algorithms and frictionless payment flows. Airport operators across France and Germany represent high-value deployment targets for barrier-controlled access systems.
- Fleet Operators:Logistics and delivery companies aggregate parking procurement across municipal boundaries through centralized subscription platforms.
- Private Users:Individual motorists access parking services through ad-hoc mobile payments or prepaid wallet balances.
By contract value, Municipalities anchor procurement volumes. By platform engagement growth, Fleet Operators show the steepest expansion trajectory.
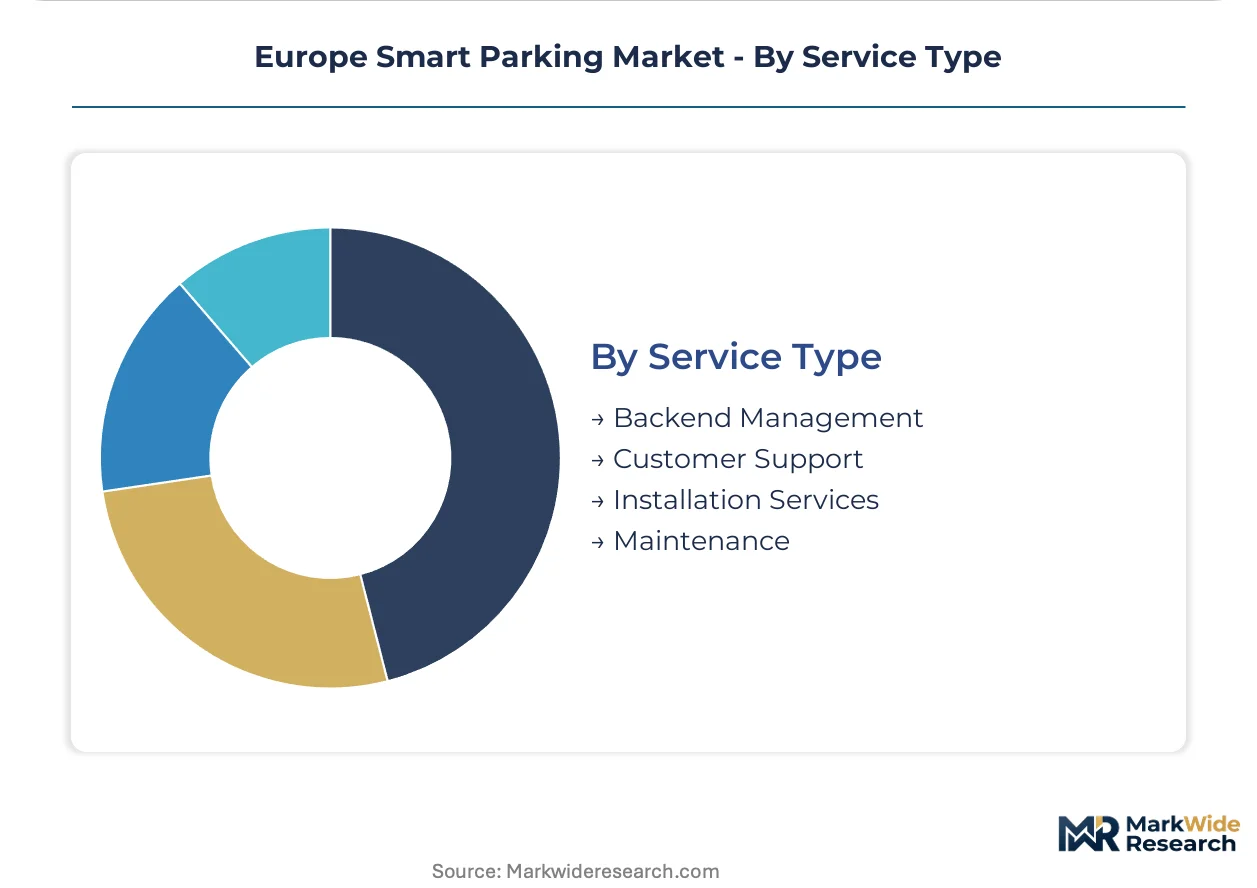
Service Type:
Margin concentration shifts from installation toward recurring maintenance and backend management as hardware commoditization compresses upfront project economics.
- Backend Management:Centralized platform administration encompassing occupancy analytics, pricing optimization engines, and enforcement workflow coordination commands premium recurring fees. Polish and Spanish operators are outsourcing these functions to specialized providers as internal IT capacity constraints persist.
- Customer Support:End-user assistance for payment disputes, account management, and technical troubleshooting scales with platform user base expansion.
- Installation Services:Physical deployment of sensors, barriers, and networking infrastructure faces margin pressure from standardized hardware commoditization.
- Maintenance:Field service contracts for sensor calibration, firmware updates, and hardware replacement generate predictable revenue streams.
By revenue stability, Maintenance contracts provide the most recurring visibility. By margin expansion, Backend Management is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's smart parking trade flows reflect a technology surplus concentrated in German and French engineering exports, while Eastern European municipalities import integrated platforms to bridge digitization gaps. The regional market fragments across procurement maturity tiers, with Western capitals replacing legacy infrastructure and Central European cities pursuing first-generation connected deployments.
Germany
Berlin and Munich are bundling smart parking tenders with multimodal transport digitization, driven by KBA protocols for automated vehicle interfaces. The EU Green Deal's congestion pricing mandates force municipalities to replace mechanical meters with sensor-based enforcement systems. Bavaria's airport operators and North Rhine-Westphalia's commercial garage networks anchor demand for barrier-controlled access platforms.
France
Paris and Lyon are expanding procurement of redundant detection stacks combining ultrasonic and camera-based verification for enforcement-grade accuracy. ANSM and CNIL pilot conformity assessments for AI-enabled license plate recognition under the EU AI Act risk classification framework. Flowbird SASU leverages its manufacturing heritage to dominate street-level deployments across Île-de-France and Southern France.
United Kingdom
London's congestion charging zone extensions require real-time occupancy data integration with multimodal transport platforms. GDPR compliance shapes cloud migration timelines for municipal parking data, with hybrid architectures processing sensitive signals locally. Greater Manchester and Birmingham are consolidating fragmented payment silos through mobile-first aggregation platforms.
Netherlands
Amsterdam and Rotterdam are migrating toward fully cloud-based deployments to reduce maintenance overhead and accelerate feature cycles. Dutch operators lead edge-to-cloud architecture adoption, separating sensor hardware procurement from analytics platform subscriptions. Randstad municipalities bundle smart parking with cycling infrastructure digitization under national mobility targets.
Poland
Warsaw and Krakow lag Western European digitization, creating first-mover advantages for integrated platform providers entering greenfield markets. Polish operators outsource backend management functions to specialized providers amid internal IT capacity constraints. The country's urban corridors represent the fastest-expanding procurement frontier for connected parking infrastructure.
Europe Smart Parking Market Competitive Landscape
Concentration sits with hardware-software hybrid specialists that combine manufacturing scale with platform architecture capabilities. The vendor base stratifies across three tiers: meter manufacturing incumbents with pay-and-display heritage, barrier-system specialists focused on commercial access control, and mobile-native platforms aggregating fragmented municipal contracts. Strategic moves center on modular procurement unbundling and cloud migration partnerships that separate sensor deployment from recurring SaaS revenue capture.
Within the manufacturing heritage tier, Flowbird SASU and SWARCO exemplify European engineering scale applied to street-level infrastructure deployment. SKIDATA anchors the commercial access control segment through barrier-system specialization for airports and high-volume garages. EasyPark Group AB occupies the mobile-native platform position, aggregating payment flows across municipal contract fragmentation. These three archetypes capture distinct margin pools: capital equipment cycles, recurring maintenance contracts, and transaction fee monetization respectively.
| Leading Market Players |
|---|
| Flowbird SASU |
| Urbiotica SL |
| Indigo Group S.A. |
| SWARCO |
| Cleverciti Systems GmbH |
| Q-Park NV |
| Daimler Mobility |
| SKIDATA |
| EasyPark Group AB |
| Others |
Supply & Pricing Matrix
Edge computing module substitution for centralized server architectures is redistributing procurement spend toward semiconductor-rich sensor assemblies while compressing margin pools for legacy meter manufacturers across German and French municipal supply chains.
Pricing Analysis
Municipal procurement officers anchor pricing negotiations through competitive tender processes governed by EU public procurement directives. Three-tier pricing structure across premium enforcement-grade, standard occupancy-monitoring, and economy retrofit tiers reflects certification complexity and integration depth. Cost compression in standard-tier hardware is intensifying because Asian semiconductor foundries dominate sensor chip supply. Fleet operators exhibit lowest price sensitivity due to enterprise subscription scale, while Eastern European municipalities with constrained budgets drive hardest bargain terms.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes periodically strain inbound logistics for sensor chip assemblies and ultrasonic detection modules. Manufacturing concentrates in Germany, France, and Taiwan for specialized IoT hardware, with firmware development anchored in Nordic engineering clusters. Supply chains draw from silicon wafer substrates, low-power wide-area network chipsets, and aluminum enclosure materials. Single-source vulnerability in advanced node semiconductor fabrication creates procurement risk. Distribution runs through municipal tender channels and direct commercial operator sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against mobile-native platform substitution that threatens to disintermediate hardware-heavy meter manufacturers from recurring transaction revenue streams.
For Market Incumbents: Compound manufacturing scale advantages through captive production of edge computing nodes for sensor integration, locking in municipal retrofit cycles. Deepen backward integration into ultrasonic detection chip supply to buffer Taiwan foundry concentration risk. Prioritize CE marking pre-certification for AI-enabled license plate recognition modules ahead of EU AI Act enforcement timelines.
For New Entrants and Emerging Players: Differentiate on cloud-native platform architecture that unbundles hardware procurement from SaaS analytics subscriptions. Target Polish urban corridors where Warsaw and Krakow lag Western digitization maturity. Pursue fleet operator segment with enterprise-grade parking aggregation contracts bypassing fragmented municipal payment silos.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors software-native platforms with recurring revenue visibility over hardware-dependent project economics. Acquisition targets should demonstrate municipal contract renewal rates above industry median and API integration depth with multimodal transport platforms. Monitor EU AI Act conformity assessment timeline acceleration as inflection signal for compliance-capability premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fragmented municipal payment silos under single cloud architecture for fleet operators. |
| Acquisition of Specialist Firm | Captures embedded firmware engineering talent scarce in broader automotive electronics labor pools. |
| Geographic Expansion | Establishes first-mover position in Polish urban corridors before Western European saturation. |
| Strategic Partnership | Links parking occupancy data with public transit digitization under EU Green Deal mandates. |
| Product Launch | Deploys redundant detection stacks achieving enforcement-grade accuracy for automated fine issuance. |
Research Methodology
Initial hypotheses were tested against primary input from municipal parking directors, IoT platform engineers, fleet procurement managers, and commercial garage operators and refined through secondary validation against EU public procurement databases, CE marking conformity records, KBA automated vehicle interface protocols, and customs trade data for sensor hardware imports. Bottom-up deployment counts triangulated against top-down municipal budget allocation estimates across the analysis window.
Variance decomposition across technology segments, deployment architectures, and end-user categories shaped the analytical framework. Modeled dimensions encompassed hardware-software bundling patterns, cloud migration velocity, and municipal versus commercial procurement channel mix. CAGRs derived from segment-level unit economics and pricing trajectory assumptions, incorporating edge computing adoption curves and EU Green Deal compliance timeline acceleration as industry-specific inputs.
Decision-makers should treat outputs as directional under stable semiconductor supply availability and continued EU regulatory enforcement commitment; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Transportation Predictive Analytics Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Advanced Traffic Management System (ATMS) Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Global Smart Commute Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Mobility Technologies Market