
 Physical Internet (PI) Market | 2026-2036
Physical Internet (PI) Market Size, Share, and Industry Trends Forecast 2026-2036
Physical Internet (PI) Market Analytics
Multi-sourced logistics orchestration is recalibrating how enterprises design fulfillment architecture. Amazon.com Inc. leverages its captive last-mile density to test open-network parcel exchanges. UPS anchors North American hub capacity through proprietary routing algorithms that interface with PI protocols. Maersk competes by extending maritime container standardization into intermodal PI corridors.
The Physical Internet denotes an open, interconnected logistics system where standardized modular containers, shared network protocols, and collaborative routing algorithms enable goods to flow through neutral nodes analogous to digital data packets. Its primary purpose is eliminating empty haul miles and asset underutilization across fragmented supply chains. Freight forwarding currently occupies the largest service value pool, while blockchain solutions within the technology dimension are attracting disproportionate capital allocation due to trust-verification requirements in multi-party networks. AI optimization tools are gaining fastest traction among e-commerce platforms seeking dynamic load-matching capabilities.
The EU Green Deal and F-Gas Regulation are tightening emissions accountability for cross-border freight, directly conditioning market access on interoperable carbon tracking. The EPA in the United States is parallelly pressing for heavy-duty transport emission disclosures that favor shared-load PI architectures over dedicated fleet models. Stakeholders must now decide whether to build proprietary PI nodes or integrate into emerging neutral infrastructure consortia before network standards crystallize.
Market Dynamics
The Physical Internet market pivots on regulatory carbon mandates forcing freight networks toward shared-load architectures and open-container interoperability standards.
Growth Catalysts
- EU Green Deal emissions frameworks:Binding carbon accountability across cross-border freight corridors is compelling fleet operators toward PI-compliant shared routing protocols.
- E-commerce fulfillment density:Parcel volume concentration in urban last-mile zones creates network effects that reward modular container handoffs between competing carriers.
- Blockchain trust verification:Distributed ledger implementations resolve multi-party liability disputes in neutral-node freight exchanges, accelerating consortia formation.
Market Restraints
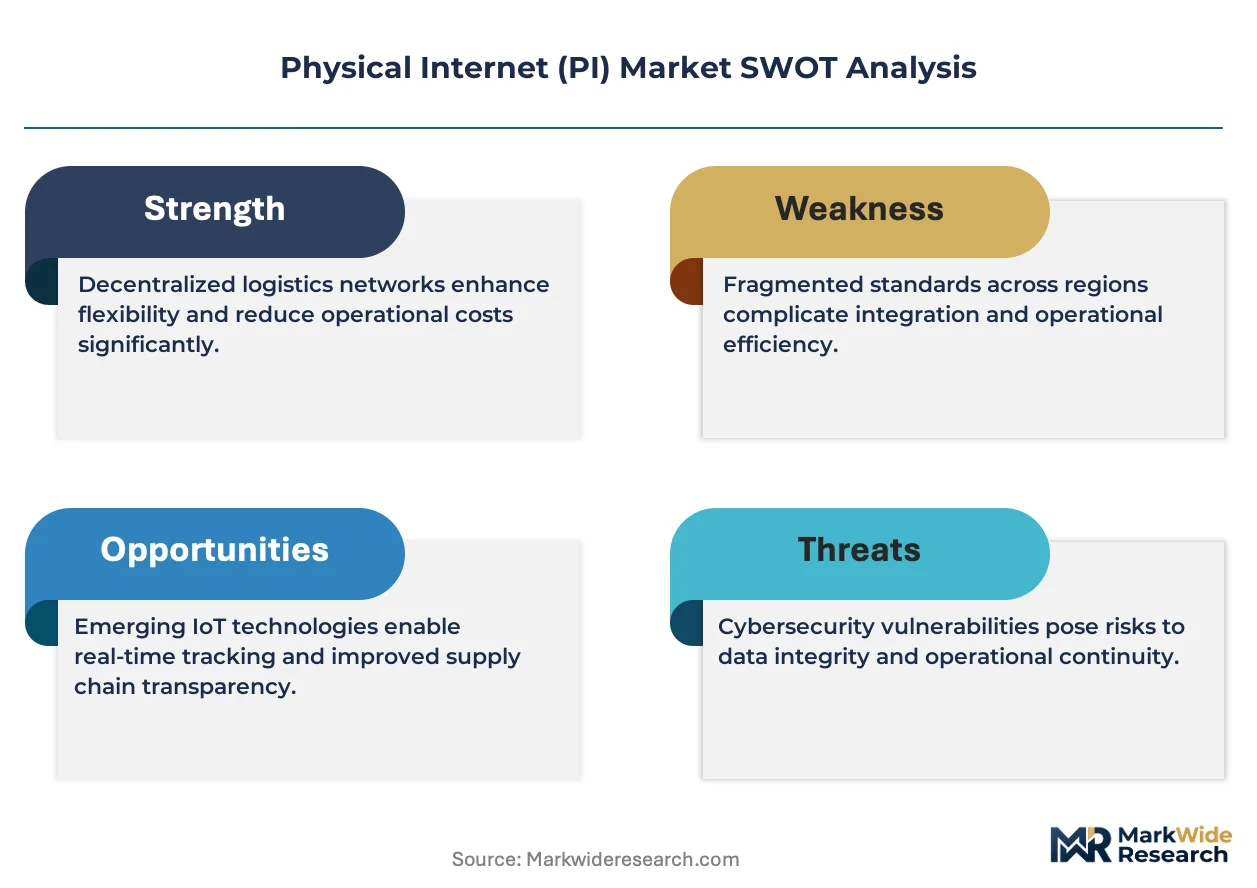
- Container standardization sunk costs:Existing proprietary fleet investments in non-modular equipment create asset-stranding risk for early PI adopters.
- German logistics cluster concentration:Hamburg and Frankfurt pilot dominance concentrates interoperability protocol development in a single regulatory jurisdiction.
- Intermodal handoff latency:Physical container transfers between rail, road, and maritime modes impose dwell-time penalties that erode PI efficiency gains.
Strategic Opportunities
- India freight digitization gaps:Underpenetrated long-haul corridors between Mumbai, Delhi, and Chennai offer first-mover advantage for PI network architects.
- AI-dynamic load matching:Convergence of predictive demand algorithms with real-time GPS fleet positioning enables empty-mile elimination at sub-hour dispatch cycles.
- F-Gas Regulation refrigerant tracking:Cold-chain PI containers gain regulatory preference through embedded emissions monitoring that satisfies EU temperature-controlled transport mandates.
Industry Challenges
- Legacy TMS integration complexity:Enterprise transportation management systems require API-layer middleware to interface with PI routing protocols, extending deployment timelines.
- Neutral-node governance disputes:Consortia participants struggle to allocate infrastructure capex and operational control across competing freight carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical Internet (PI) Market |
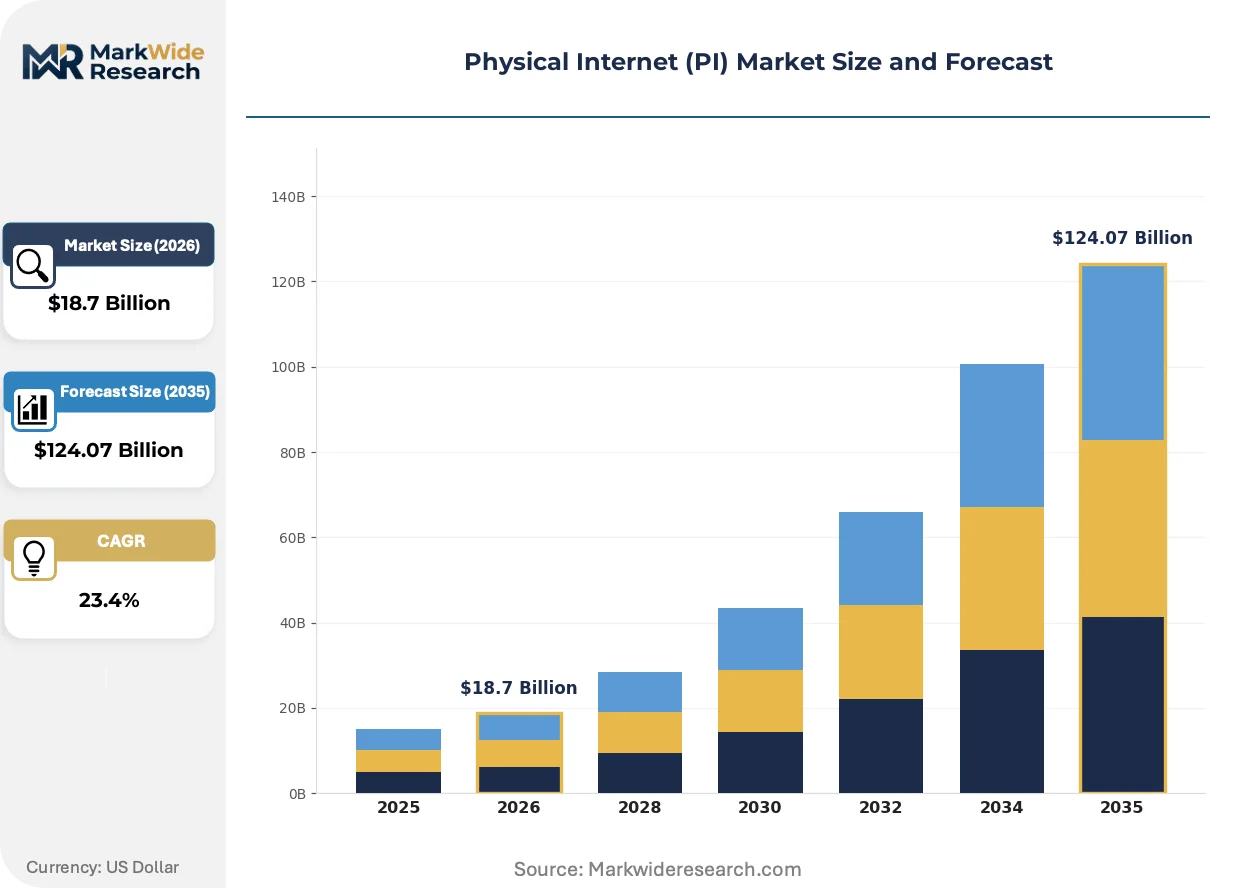
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $124.07 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Last Mile Delivery, Warehousing, Intermodal Transport Technology: IoT Devices, Blockchain Solutions, AI Optimization, Automation Tools End User: Manufacturers, Retailers, E-commerce Platforms, Logistics Providers Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Applications |
| Companies Covered | Amazon.com Inc., UPS, FedEx Corporation, DHL, Maersk, Kuehne + Nagel, DB Schenker, SF Express Co. Ltd., XPO Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical Internet (PI) Market Evolving Landscape
Algorithmic orchestration is displacing static hub-and-spoke planning as the dominant freight architecture logic, compressing decision cycles from days to minutes.
Digital twin simulation is automating container routing decisions across multi-modal networks. E-commerce platforms deploy these virtual replicas to pre-position inventory before demand spikes materialize. The technology is automating load-matching workflows that previously required human dispatch coordination.
The EPA's heavy-duty transport emission disclosure requirements are conditioning fleet access to California and Northeast corridor markets on interoperable carbon tracking. Operators must now demonstrate shared-load utilization rates to qualify for preferential lane access. Heavy freight forwarders in the US Midwest are retrofitting existing fleets with telematics that feed PI-protocol carbon registries.
Shippers are consolidating vendor relationships around carriers offering PI-compatible open-network access rather than dedicated capacity contracts. This procurement compression favors neutral-node operators over asset-heavy dedicated fleets. German automotive parts distributors represent the most advanced practitioners of this contract restructuring.
Physical Internet (PI) Market Segmentation
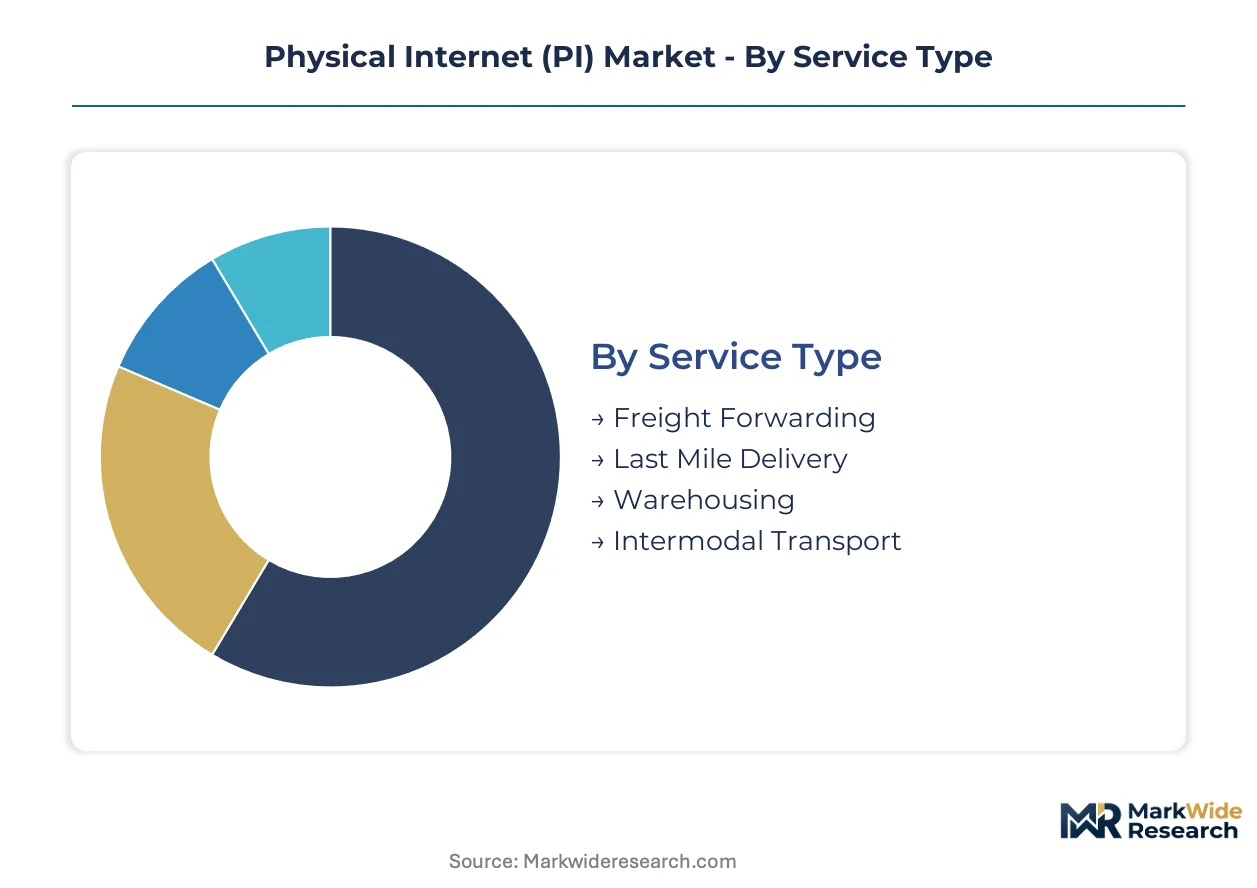
Physical Internet market segmentation reveals how value migrates between asset-heavy infrastructure plays and algorithmic coordination layers. Service type determines capital intensity, while technology choices separate proprietary stack builders from protocol-agnostic integrators.
Service Type:
Cost tier separates asset-light orchestrators from balance-sheet-heavy operators in this category.
- Freight Forwarding:Neutral intermediaries aggregate fragmented carrier capacity across multi-modal corridors. Demand concentrates among German automotive parts distributors seeking open-network container handoffs under EU Green Deal carbon accountability frameworks. This segment captures the largest value pool through consortia-based load consolidation.
- Last Mile Delivery:Urban parcel density enables competing carriers to exchange modular containers at neutral micro-hubs. Amazon.com Inc. pilots open-network protocols in high-volume metropolitan zones where e-commerce fulfillment concentration creates network effects. Regulatory pressure on emissions disclosures favors shared-load architectures over dedicated fleet models.
- Warehousing:Shared storage nodes function as PI protocol handoff points between inbound freight and outbound last-mile segments.
- Intermodal Transport:Rail-road-maritime container exchanges impose dwell-time penalties that erode efficiency gains without standardized modular equipment.
Volume sits with Freight Forwarding; growth tilts toward Last Mile Delivery.
Technology:
Application maturity divides proven operational tools from emerging trust-verification layers.
- Blockchain Solutions:Distributed ledger implementations resolve multi-party liability disputes in neutral-node freight exchanges. Capital allocation concentrates here due to consortia formation requirements across Hamburg and Frankfurt logistics clusters. Smart contracts automate settlement workflows that previously required manual reconciliation between competing carriers.
- AI Optimization:Predictive demand algorithms converge with real-time GPS fleet positioning to eliminate empty miles at sub-hour dispatch cycles. E-commerce platforms deploy these tools for dynamic load-matching capabilities. This segment gains fastest traction among parcel networks seeking algorithmic orchestration over static hub-and-spoke planning.
- IoT Devices:Embedded sensors track container location, condition, and carbon emissions across handoff points.
- Automation Tools:Robotic sortation and autonomous yard equipment reduce container transfer latency at PI nodes.
Revenue concentrates in Blockchain Solutions; capability expansion centers on AI Optimization.
End User:
Customer type shapes procurement patterns between captive network builders and open-protocol adopters.
- E-commerce Platforms:Parcel volume concentration drives investment in modular container standards and neutral-node access. These buyers recalibrate fulfillment architecture around multi-sourced logistics orchestration rather than dedicated capacity contracts. Urban last-mile density rewards open-network parcel exchanges between competing carriers.
- Logistics Providers:Asset-heavy operators face sunk-cost risk from proprietary fleet investments while navigating interoperability standards. Maersk extends maritime container standardization into intermodal PI corridors. These incumbents must decide between building proprietary PI nodes or integrating into emerging neutral infrastructure consortia.
- Manufacturers:Industrial shippers consolidate vendor relationships around PI-compatible open-network access.
- Retailers:Omnichannel fulfillment requirements push adoption of shared-load routing protocols.
Procurement volume favors E-commerce Platforms; contract restructuring momentum sits with Logistics Providers.
Deployment:
Margin profile distinguishes subscription-based SaaS orchestration from capex-intensive on-premise infrastructure.
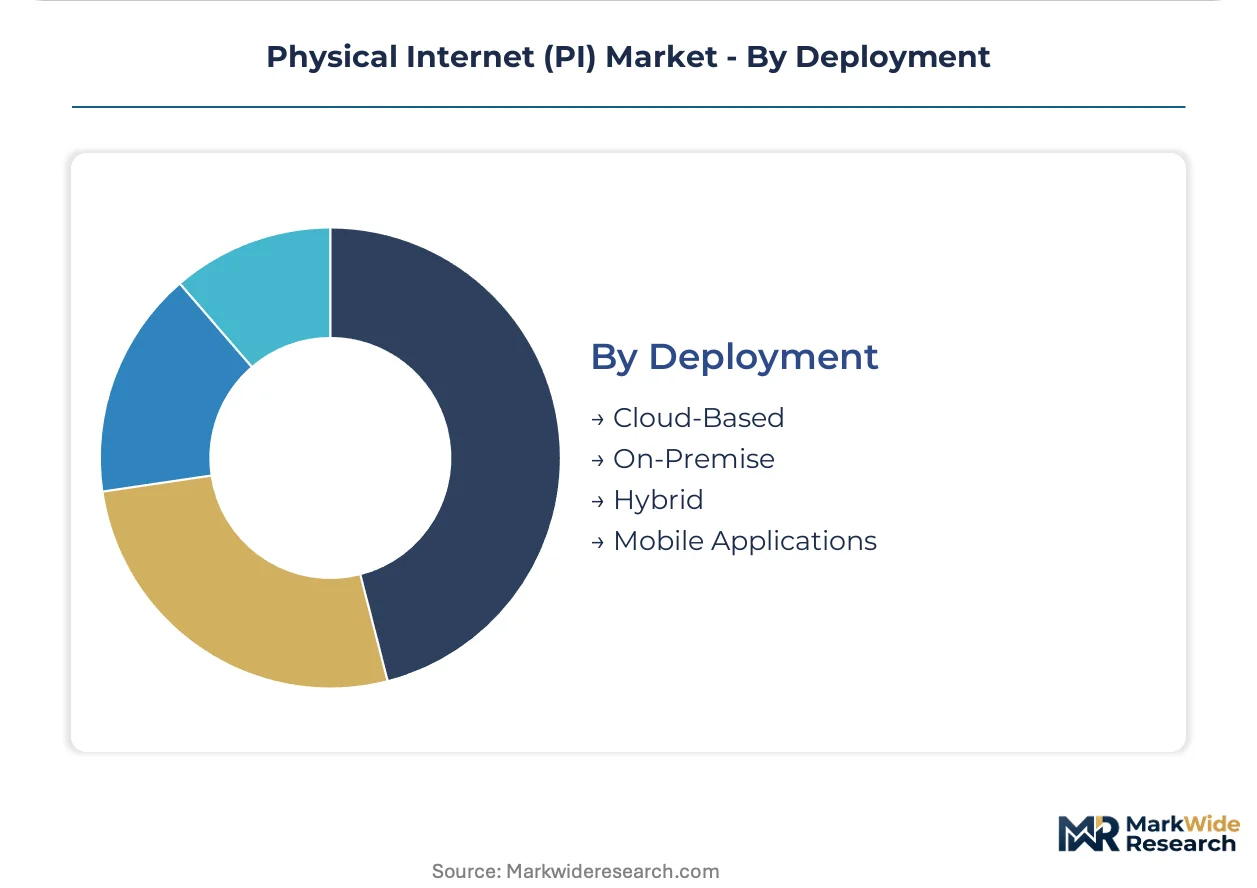
- Cloud-Based:API-layer middleware enables rapid integration with legacy transportation management systems. Deployment timelines compress as neutral-node operators offer protocol-as-a-service models. These solutions dominate among mid-market freight forwarders lacking internal development resources.
- Hybrid:Enterprises retain sensitive routing algorithms on-premise while leveraging cloud-based load-matching marketplaces. This architecture addresses governance disputes over operational control in multi-party consortia.
- On-Premise:Large carriers maintain proprietary PI protocol stacks to defend competitive differentiation.
- Mobile Applications:Driver-facing tools enable real-time container handoff confirmations and carbon registry updates.
Adoption volume clusters in Cloud-Based; strategic positioning moves toward Hybrid architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German logistics clusters anchor the Physical Internet infrastructure rollout. Hamburg and Frankfurt pilot open-network container protocols that are reshaping freight orchestration across the EU.
United States
EPA heavy-duty transport emission disclosures favor shared-load PI architectures over dedicated fleet models. Midwest freight forwarders retrofit existing fleets with telematics feeding PI-protocol carbon registries. California and Northeast corridor markets condition fleet access on interoperable carbon tracking.
Germany
EU Green Deal emissions mandates accelerate interoperability standards across freight networks. F-Gas Regulation refrigerant tracking gives cold-chain PI containers regulatory preference through embedded emissions monitoring. Hamburg and Frankfurt logistics clusters dominate pilot development for open-network protocols.
China
Dual carbon goals under MEE oversight push logistics operators toward asset-sharing models. GB standards for smart logistics containers enable cross-carrier interoperability. Yangtze River Delta manufacturing hubs test PI-compatible container exchanges between competing freight operators.
India
PLI scheme incentives for logistics digitization create first-mover opportunities in underpenetrated long-haul corridors. DGFT cross-border trade facilitation rules favor standardized container protocols. Mumbai-Delhi-Chennai freight corridors attract PI network architects seeking greenfield deployment.
Japan
METI smart logistics initiatives promote neutral-node infrastructure for e-commerce fulfillment density. JIS standards for modular containers enable inter-carrier handoffs in Tokyo-Osaka corridors. Kanto region parcel networks test algorithmic load-matching at sub-hour dispatch cycles.
Physical Internet (PI) Market Competitive Landscape
Strategic partnerships dominate the current landscape as operators position for network standardization. The vendor base clusters around three tiers: asset-heavy maritime carriers extending into intermodal corridors, parcel networks leveraging captive last-mile density, and neutral freight forwarders orchestrating consortia-based load consolidation. Two archetypes define competitive positioning: proprietary PI node builders defending differentiated routing algorithms, and protocol-agnostic integrators aggregating across emerging neutral infrastructure. Technology licensing and geographic expansion through consortia membership represent the dominant competitive moves.
Within the maritime-intermodal archetype, Maersk occupies a position exemplifying container standardization extension. Among parcel-network operators, Amazon.com Inc. and UPS sit within the tier leveraging urban last-mile density for open-network protocol testing. These three companies represent the spectrum from asset-heavy infrastructure control to algorithmic coordination layers, with each anchoring a distinct strategic approach to PI market development.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| UPS |
| FedEx Corporation |
| DHL |
| Maersk |
| Kuehne + Nagel |
| DB Schenker |
| SF Express Co. Ltd. |
| XPO Logistics |
| Others |
Value Network & Pricing Analysis
Diesel fuel price indices in Rotterdam and Singapore anchor cost structures across PI network operators, cascading through freight forwarding margins into subscription-tier pricing for cloud-based orchestration platforms serving e-commerce fulfillment clusters.
Pricing Analysis
Service-level bundling separates carbon-tracking compliance from base platform access, with EU Green Deal-mandated emissions verification commanding premium tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, API integration complexity, and dedicated support availability. Cost compression in mid-market SaaS tiers is intensifying because neutral-node consortia are consolidating procurement volume. E-commerce platforms exhibit lowest price sensitivity due to fulfillment density returns, while regional freight forwarders face acute margin pressure from legacy TMS retrofit requirements.
Supply Chain Analysis
Direct-to-consortium channels handle hyperscale carrier demand for modular container protocols, bypassing traditional equipment leasing intermediaries. Manufacturing concentrates in Germany, China, and South Korea for smart container sensors and telematics hardware. Component supply draws from semiconductor foundries in Taiwan, lithium-cell producers in South Korea, and steel fabrication in China. Single-source vulnerability sits with EU-exclusive pilot development in Hamburg and Frankfurt logistics clusters. Distribution runs through neutral-node infrastructure consortia rather than carrier-captive networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon mandates are compressing margins for asset-heavy operators lacking PI-protocol compatibility, forcing consolidation among regional freight forwarders unable to fund interoperability investments.
For Market Incumbents: Hedge proprietary fleet exposure by accelerating API-layer middleware development that bridges legacy TMS stacks to emerging neutral-node protocols. Maersk's maritime standardization extension into intermodal corridors offers a template for defending routing algorithm differentiation against algorithmic orchestration entrants. Prioritize consortia membership in Hamburg and Frankfurt pilot clusters before interoperability standards crystallize. For New Entrants and Emerging Players: EPA heavy-duty transport emission disclosures in the United States open a window for cloud-based PI orchestration platforms targeting Midwest freight forwarders retrofitting carbon-registry telematics. Underpenetrated Mumbai-Delhi-Chennai corridors in India offer white-space deployment for greenfield neutral-node infrastructure. Lead with protocol-as-a-service pricing to bypass incumbent sunk-cost advantages in container standardization. For Investors and Strategic Acquirers: Distressed-cycle entries favor algorithmic coordination-layer specialists with proven AI-dynamic load matching in Germany and Japan. Long-term viability hinges on consortia governance rights rather than captive asset ownership. Watch for EPA emission disclosure enforcement intensity in California and Northeast corridor markets as inflection signal for shared-load architecture preference over dedicated fleet models.| Strategic Initiative | Industry Significance |
|---|---|
| Consortia Membership Expansion | Secures governance rights in Hamburg and Frankfurt pilot protocols before standardization locks in. |
| API Middleware Development | Enables legacy TMS integration for mid-market freight forwarders lacking internal development resources. |
| AI Load-Matching Acquisition | Accelerates sub-hour dispatch capability against static hub-and-spoke planning incumbents. |
| Cold-Chain Container Certification | Captures F-Gas Regulation preference through embedded emissions monitoring for EU temperature-controlled transport. |
| India Corridor Greenfield Deployment | Exploits PLI scheme incentives before domestic logistics operators consolidate digitization investments. |
Research Methodology
Independent corroboration across freight forwarding executives, neutral-node infrastructure architects, and e-commerce platform logistics directors underwrites the qualitative findings, validated against EU Green Deal regulatory filings, EPA emission disclosure dockets, and customs trade flow databases. Primary fieldwork with transportation management system vendors and IoT sensor manufacturers combined with secondary triangulation across SEC filings from listed logistics operators and port authority throughput statistics. Bottom-up carrier capacity assessments and top-down regulatory impact modeling converge in segment-level value projections.
Comparable-period anchoring to pre-mandate baseline freight network utilization established the forecast reference frame across the analysis window. Segmentation dimensions include service type tier, technology maturity stage, deployment architecture, and end-user procurement pattern, with cross-modal container velocity and consortia formation velocity as industry-specific forecast inputs. CAGRs derive from logistic curve adoption modeling for interoperability standards penetration.
The model assumes a particular technology adoption path; alternative pathways for blockchain trust verification would alter the outlook if distributed ledger implementations face latency constraints at intermodal handoff points. Forecasts reflect assumptions regarding EU regulatory enforcement consistency and carrier consortia governance stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Vehicle Parking Meter Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Road Asset Management Software Market