
 Global Log Cabins or Log Homes Market | 2026-2036
Global Log Cabins or Log Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Log Cabins or Log Homes Market Outlook
Multi-source timber procurement is repositioning supply strategies across the log home industry as volatile lumber costs and sustainability certifications reshape vendor relationships. Honka Log Homes leverages its Finnish timber base to sustain premium positioning in engineered wood systems. Katahdin Cedar Log Homes anchors its competitive stance through cedar-specific specialization in the northeastern United States. Palmako AS dominates prefabricated export channels across Northern Europe with standardized modular platforms.
Log cabins and log homes are permanent residential structures built from horizontally stacked natural or engineered timbers, typically featuring interlocking corner notching and chinking seals to achieve thermal and moisture barriers; laminated logs with glued-laminated timber cores now achieve R-values exceeding traditional solid logs while resisting twist and settlement. Prefabricated and modular product types capture the fastest growth trajectory as factory-controlled milling reduces on-site labor and waste, though custom-built designs retain the deepest margin pools among high-net-worth buyers in resort markets. Engineered wood and laminated log materials are displacing conventional solid timber in markets where building codes mandate enhanced seismic and fire resistance.
CE marking under the EU Construction Products Regulation governs structural timber sales across European member states, while the US International Residential Code and ICC-400 standards dictate log wall assembly requirements in North America. ISO 9001 quality management and FSC chain-of-custody certification increasingly function as market-access prerequisites rather than optional differentiators. Stakeholders must monitor evolving embodied-carbon accounting rules in the EU and emerging US state-level mass timber amendments that could accelerate or constrain laminated log adoption.
Market Dynamics
Prefabricated manufacturing systems are compressing construction timelines and labor dependency across the log home sector, while EU Green Deal building codes and laminated timber engineering advances simultaneously tighten thermal performance mandates and extend structural durability.
Growth Catalysts
- EU Green Deal building codes:Mandatory energy-efficiency thresholds for new residential construction are accelerating laminated log adoption across Finland, Sweden, and Germany.
- Vacation home buyers:Remote-work normalization has intensified second-home demand in Scandinavian lake districts and Rocky Mountain resort corridors.
- Laminated log engineering:Glued-laminated timber cores now achieve superior R-values and seismic resistance, expanding addressable markets in earthquake-prone zones.
Market Restraints
- Volatile softwood lumber costs:North American spruce and fir price swings squeeze manufacturer margins and destabilize project quoting.
- Finnish and Baltic timber concentration:Overreliance on specific Nordic milling clusters creates vulnerability to regional weather events and export quota shifts.
- Concrete and steel substitution:Urban multi-family developers in dense markets favor conventional materials for fire-code compliance and height allowances.
Strategic Opportunities
- Japanese alpine resort zones:Underdeveloped log home penetration in Nagano and Hokkaido ski regions offers first-mover positioning for engineered timber specialists.
- Net-zero retrofit mandates:Germany's Building Energy Act and similar French regulations are creating renovation demand for thermally upgraded log envelope systems.
- Direct-to-consumer digital platforms:Configurator-driven sales channels are bypassing traditional dealer networks and capturing margin previously lost to intermediaries.
Industry Challenges
- Certified log-craft skill scarcity:Traditional hand-notching expertise is aging out faster than vocational programs in Finland and Canada can replenish.
- CE marking timeline compression:EU Construction Products Regulation compliance documentation is extending product development cycles for laminated log innovators.
- Multi-material integration complexity:Hybrid builds combining solid logs, glulam, and SIP panels demand coordination across previously siloed trades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Log Cabins or Log Homes Market |
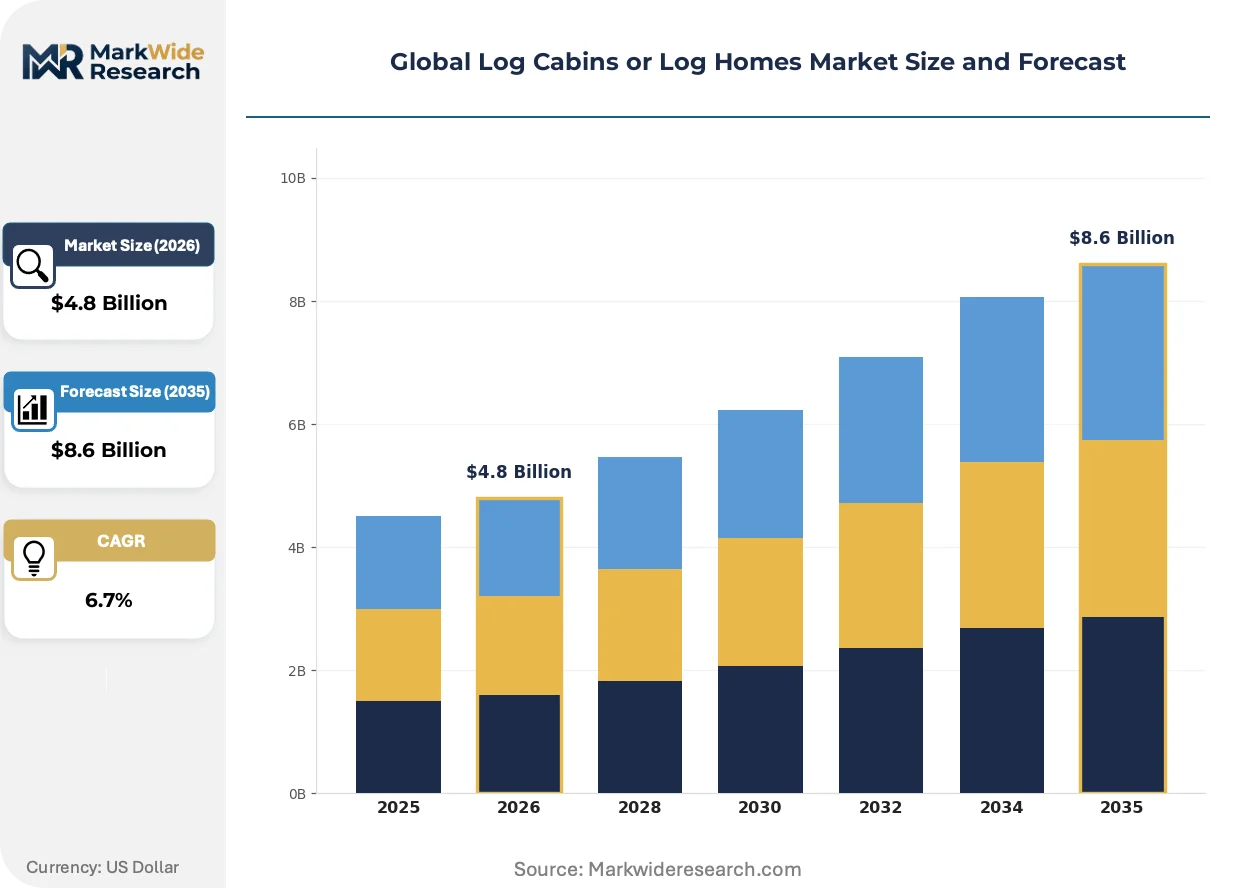
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prefabricated, Custom-Built, Modular, Kit Homes Material: Timber, Engineered Wood, Laminated Logs, Composite Materials Design Style: Traditional, Modern, Rustic, Contemporary End User: Residential, Vacation Homes, Commercial, Eco-Tourism |
| Companies Covered | Lindal Cedar Homes, Honka Log Homes, Satterwhite Log Homes, Honkarakenne Oyj, Pioneer Log Homes of British Columbia, Palmako AS, Katahdin Cedar Log Homes, Timberhaven Log & Timber Homes, Artisan Log and Timber Homes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Log Cabins or Log Homes Market Strategic Shifts
Factory-controlled manufacturing and regulatory carbon accounting are rewiring competitive advantage sources across the log home value chain, compressing the advantage window for pure on-site builders.
Cross-laminated timber and glued-laminated log cores are absorbing market share from traditional solid timber in markets where building codes mandate enhanced seismic performance and fire resistance. Resort developers in California and British Columbia are specifying engineered logs for multi-story lodge structures. The technology is absorbing premium pricing previously reserved for custom solid-log craftsmanship while delivering superior dimensional stability.
REACH chemical restrictions and the EU Deforestation Regulation are tightening chain-of-custody documentation requirements for structural timber imports into European member states. Manufacturers must now demonstrate geolocation-verified sourcing for all virgin wood inputs. Finnish and Estonian exporters are investing in blockchain-tracked inventory systems to preserve market access.
Buyer preference for turnkey cabin packages is displacing traditional material-only supply contracts across recreational property markets. Scandinavian manufacturers are bundling foundation, MEP, and interior finish specifications into standardized modular platforms. This pattern is most pronounced in Norway and Colorado, where remote site access costs amplify the value of pre-integrated delivery.
Global Log Cabins or Log Homes Market Segmentation
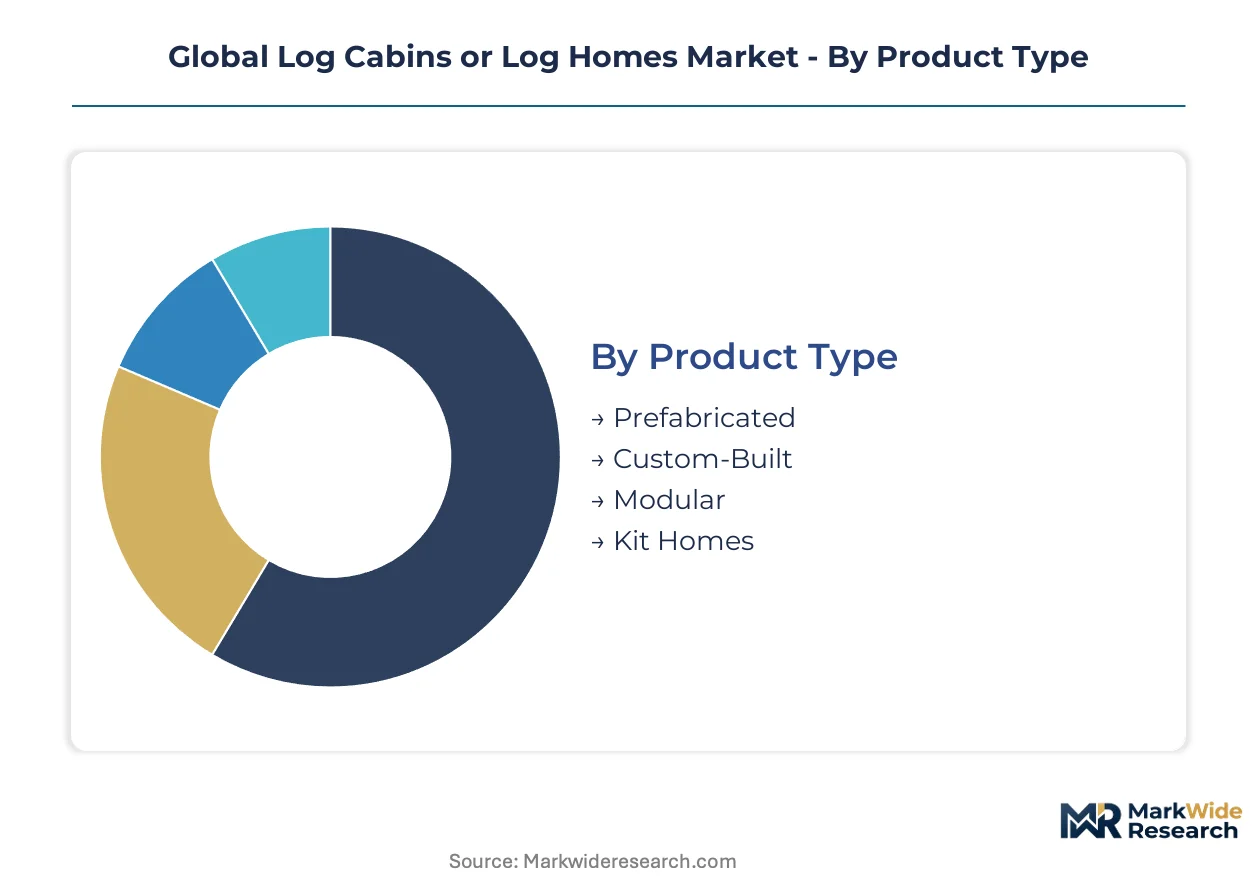
Log cabin buyers navigate trade-offs between construction speed, thermal performance, and architectural authenticity. Segmentation reveals how prefabricated systems capture volume while custom craftsmanship commands premium positioning in resort corridors.
Product Type:
Buyers weigh speed-to-occupancy against personalization depth when selecting construction methodology.
- Prefabricated:Factory-milled wall sections with pre-cut notching reduce on-site labor by 60-70% versus traditional methods. Finnish manufacturers dominate export channels to Norway and Colorado ski regions where remote site access costs amplify pre-integrated value.
- Custom-Built:Hand-notched corner joinery and site-specific timber selection preserve artisanal heritage. Wealthy buyers in British Columbia and the Swiss Alps commission these for multi-generational lodge properties where architectural distinction justifies 18-24 month build timelines.
- Modular:Volumetric units complete with MEP rough-ins enable winter construction in harsh climates.
- Kit Homes:Flat-packed component packages suit owner-builder projects with limited budgets.
Prefabricated leads on scale; custom-built leads on momentum in luxury resort markets.
Material:
Regulatory thermal mandates and seismic codes are displacing conventional solid timber in high-performance applications.
- Engineered Wood:Cross-laminated and glued-laminated timber cores achieve R-values exceeding solid logs while resisting twist and settlement. California and British Columbia developers specify these for multi-story lodge structures where ICC-400 and local seismic amendments apply.
- Laminated Logs:Glued-laminated cores with natural wood veneers deliver dimensional stability across humidity extremes. German and Austrian manufacturers leverage these for net-zero retrofit projects under the Building Energy Act.
- Timber:Traditional solid logs retain cost advantage in rural markets with permissive building codes.
- Composite Materials:Wood-fiber and resin blends address fire-resistance gaps in urban-adjacent builds.
Engineered wood commands the steepest expansion trajectory; timber retains the largest installed base.
Design Style:
Aesthetic preference splits along buyer age cohort and property use case rather than geography.
- Modern:Clean lines, extensive glazing, and flat roof planes attract urban second-home buyers in Norway and Colorado. These designs command 15-25% pricing premiums over traditional equivalents through specification of triple-pane curtain walls and integrated solar arrays.
- Contemporary:Hybrid forms blending rustic massing with refined material palettes.
- Traditional:Dovetail notching, chinking seals, and gabled rooflines persist in heritage-conscious markets.
- Rustic:Reclaimed timber and hand-hewn surfaces target experiential eco-tourism operators.
Modern styling gains share fastest among remote-work vacation buyers; traditional designs defend volume in heritage markets.
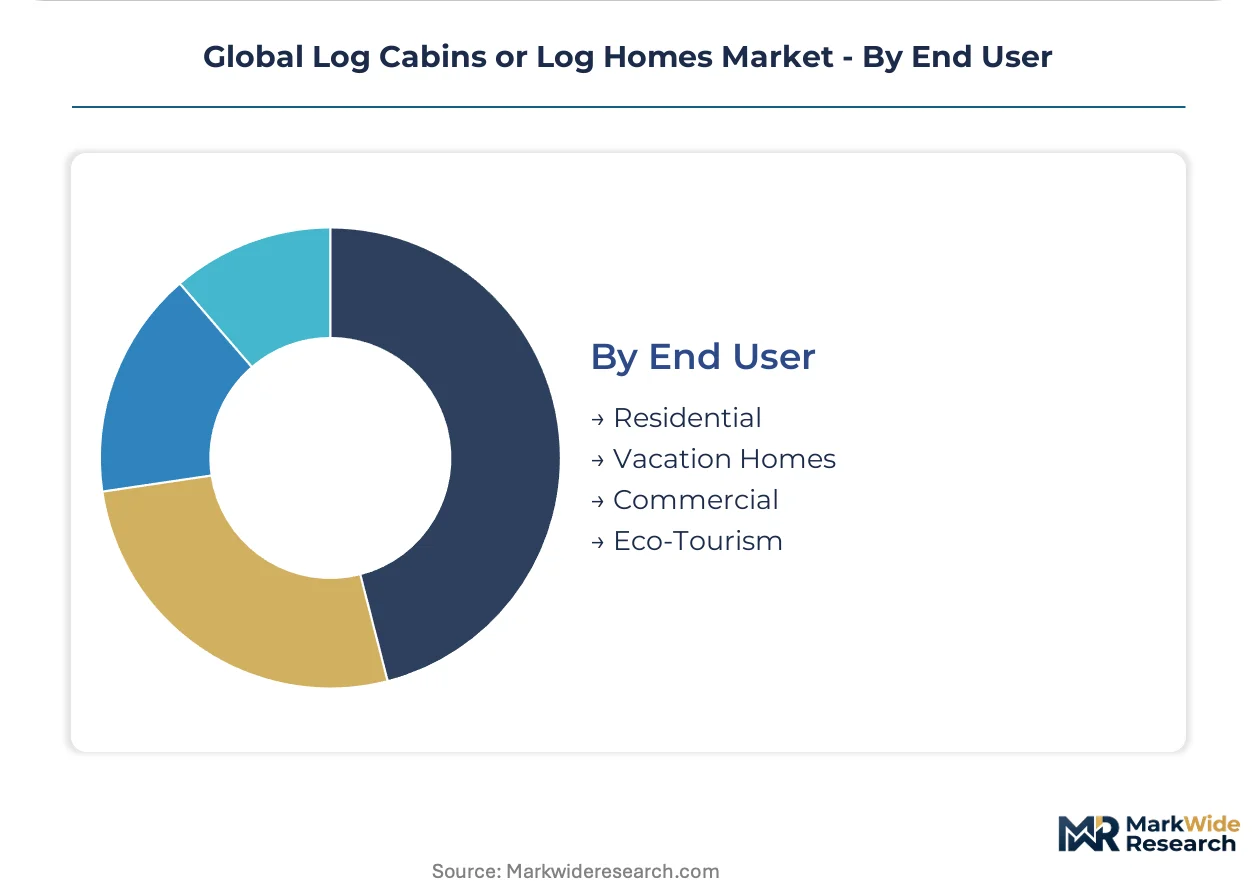
End User:
Property use determines structural specifications, foundation requirements, and amenity integration complexity.
- Vacation Homes:Remote-work normalization has intensified demand in Scandinavian lake districts and Rocky Mountain corridors. Buyers prioritize turnkey packages with pre-integrated smart-home infrastructure and off-grid power compatibility.
- Residential:Primary dwellings require full building-code compliance including accessibility and energy certification.
- Eco-Tourism:Glamping operators and wilderness lodges specify low-impact foundations and composting systems.
- Commercial:Restaurants and retail in resort zones employ log construction for brand differentiation.
Vacation homes lead on absolute volume; eco-tourism climbs fastest as sustainability tourism expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish timber clusters anchor production capacity for engineered log systems, while Scandinavian lake districts and North American mountain corridors concentrate vacation-home demand. Regulatory pressure from Brussels and seismic codes in California are reshaping material specifications across export markets.
United States
Vacation-home buyers in Colorado and the Rocky Mountain states are accelerating prefabricated cabin purchases for remote-work retreats. The ICC-400 standard and state-level mass timber amendments in California dictate log wall assembly requirements for seismic zones. Katahdin Cedar Log Homes anchors cedar-specific specialization in the northeastern states where traditional craftsmanship persists.
Finland
EU Green Deal building codes are tightening energy-efficiency thresholds for new residential construction across lake districts. The Construction Products Regulation mandates CE marking for structural timber sales into continental markets. Honka Log Homes leverages its domestic timber base to sustain premium positioning in engineered wood systems exported to Germany and Austria.
Canada
Volatile spruce and fir costs are squeezing manufacturer margins in British Columbia while resort developers specify engineered logs for multi-story lodge structures. The National Building Code and provincial seismic amendments govern tall wood construction in earthquake-prone zones. Pioneer Log Homes of British Columbia exemplifies custom-built positioning for multi-generational lodge properties.
Germany
The Building Energy Act is creating renovation demand for thermally upgraded log envelope systems in alpine regions. REACH chemical restrictions and the EU Deforestation Regulation tighten chain-of-custody documentation for structural timber imports. Bavarian and Baden-Württemberg fabricators are bundling foundation and MEP specifications into turnkey packages for net-zero retrofits.
Japan
Underdeveloped log home penetration in Nagano and Hokkaido ski regions offers positioning opportunities for engineered timber specialists targeting alpine resort zones. METI standards and local fire codes shape material specifications for multi-story hospitality structures. Prefabricated manufacturers from Finland and Estonia are probing export channels through demonstration projects in mountain corridors.
Global Log Cabins or Log Homes Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer digital platforms and net-zero retrofit specializations. The vendor base spans vertically integrated Nordic exporters, cedar-focused regional fabricators, and modular platform operators. Three archetypes dominate: heritage craftsmen emphasizing hand-notched joinery, engineered-wood specialists leveraging laminated timber cores, and prefabricated platform operators compressing construction timelines. Competitive moves concentrate on strategic partnerships for multi-material integration and geographic expansion into underpenetrated alpine resort zones.
Among Finnish manufacturers, Honka Log Homes and Honkarakenne Oyj exemplify the engineered-wood archetype with premium positioning in glued-laminated systems. Palmako AS represents the prefabricated export platform model dominating standardized modular channels across Northern Europe. These three anchors illustrate how Nordic timber access, CE marking compliance, and factory-controlled manufacturing combine to capture share in markets where building codes mandate enhanced thermal performance.
| Leading Market Players |
|---|
| Lindal Cedar Homes |
| Honka Log Homes |
| Satterwhite Log Homes |
| Honkarakenne Oyj |
| Pioneer Log Homes of British Columbia |
| Palmako AS |
| Katahdin Cedar Log Homes |
| Timberhaven Log & Timber Homes |
| Artisan Log and Timber Homes |
| Others |
Value Chain & Pricing Dynamics
Family-owned Finnish and Estonian timber specialists anchor production clusters, translating Nordic milling heritage into pricing discipline through captive spruce and pine reserves. Their ownership structure insulates margin pools from quarterly earnings pressure while enabling long-term supply contracts that stabilize project quoting for vacation-home developers.
Pricing Analysis
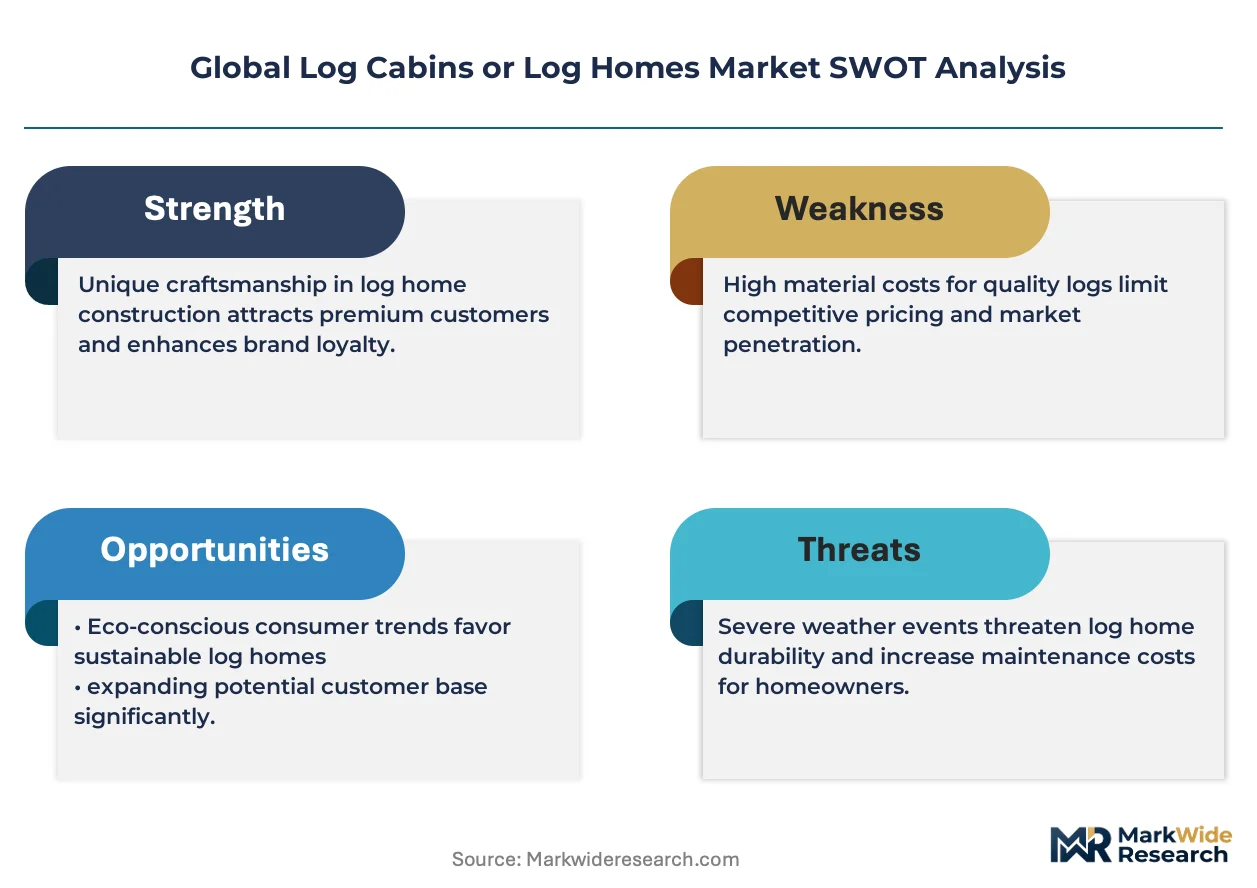
Input-cost pass-through from volatile North American spruce and fir markets squeezes manufacturer margins, forcing three-tier pricing structure across premium, standard, and economy levels. CE marking compliance and FSC chain-of-custody certification command 12-18% price premiums over uncertified equivalents. Cost compression in standard-tier prefabricated units intensifies because Baltic producers expand factory-controlled output. Owner-builder kit buyers exhibit highest price sensitivity; custom-built resort lodge clients demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from German and Austrian developers mandate multi-supplier qualification across Finnish, Estonian, and Canadian timber bases. Raw material dependencies center on slow-grown Nordic spruce, western red cedar, and laminated timber adhesives. Single-source vulnerability concentrates in Baltic milling clusters exposed to regional weather disruptions. Distribution runs through prefabricated export platforms for Northern Europe, direct-to-consumer digital channels for North American recreational buyers, and dealer networks for custom craftsmanship segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-controlled manufacturing and laminated timber engineering are compressing cost structures while premium-tier vacation-home buyers absorb specification upgrades, expanding addressable margin pools across the projection horizon.
For Market Incumbents: To counter emerging direct-to-consumer digital platforms, deepen backward integration into certified Nordic timber reserves and anchor dealer network exclusivity in Rocky Mountain and Scandinavian lake district corridors. Invest in CE marking documentation capacity to compress product development cycles for laminated log innovations. For New Entrants and Emerging Players: Configurator-driven sales channels enable bypass of traditional intermediary networks and capture margin previously lost to dealer markups. Target Japanese alpine resort zones in Nagano and Hokkaido where log home penetration remains underdeveloped. Pursue net-zero retrofit specialization under Germany's Building Energy Act as the most penetrable regulatory-driven demand segment. For Investors and Strategic Acquirers: Valuations sit cheapest among modular platform operators with standardized product architectures and export-channel scale. Five-to-ten year viability favors engineered-wood specialists with laminated timber core capabilities over pure solid-log craftsmen. Monitor EU Deforestation Regulation enforcement stringency as the signal indicating accelerated consolidation among non-compliant Baltic suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Timber Reserves | Captive Nordic spruce supply insulates margins from volatile North American lumber markets. |
| CE Marking Compliance Investment | EU Construction Products Regulation documentation preserves market access across member states. |
| Direct-to-Consumer Digital Platform Launch | Configurator-driven sales capture margin previously lost to dealer intermediaries in recreational markets. |
| Net-Zero Retrofit Specialization | Germany's Building Energy Act creates renovation demand for thermally upgraded log envelope systems. |
| Japanese Alpine Resort Expansion | Demonstration projects in Nagano and Hokkaido establish first-mover positioning in underpenetrated ski regions. |
Study Parameters
Coverage spans Finland, Canada, the United States, Germany, and Japan, with primary inputs from each market combining structured interviews with log home manufacturer executives, timber procurement directors, vacation-home developers, and building code officials alongside secondary validation. Trade data from Finnish Forest Industries Federation, US International Trade Commission lumber monitoring, and EU Construction Products Regulation compliance databases anchored supply-side analysis. Bottom-up project pipeline tracking and top-down residential construction forecasts were triangulated against laminated timber engineering adoption curves.
Granularity-level modeling disaggregated volume and value across product type, material composition, design style, and end-use application throughout the forecast period. Cross-laminated timber and glued-laminated log core penetration rates, EU Green Deal building code implementation timelines, and remote-work vacation-home demand elasticity shaped scenario-weighted CAGRs. Prefabricated manufacturing capacity expansion schedules and certified log-craft labor availability constraints informed supply-side bounds.
Volatile softwood lumber costs, Finnish and Baltic timber export quota shifts, and laminated adhesive chemistry restrictions under REACH are the dominant revision risks to modeled outputs. Deviation in EU Deforestation Regulation geolocation verification enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
UK Residential Real Estate Market