
 North America Thermal Protector Market | 2026-2036
North America Thermal Protector Market Size, Share, and Industry Trends Forecast 2026-2036
North America Thermal Protector Market Analytics
Multi-source procurement is broadening across the North America thermal protector supply base as OEMs reduce dependency on single vendors for critical safety components. Sensata Technologies leverages its vertical integration in bimetallic switch manufacturing to sustain price competitiveness against smaller rivals. Portage Electric Products anchors its position through specialized production of custom thermal cutoffs for appliance OEMs.
A thermal protector is an electromechanical or solid-state device that interrupts electrical current when temperatures exceed calibrated thresholds, typically employing bimetallic strips, thermistors, or electronic sensing circuits to achieve response times under ten seconds. Its primary purpose is preventing fire hazards and equipment damage in motor-driven systems, heating elements, and power electronics. Bimetallic thermal switches dominate unit volumes due to their mechanical simplicity and cost structure, while electronic thermal switches capture expanding margin pools in precision applications such as EV battery management systems. The automotive end-user segment exhibits the fastest trajectory as electrification multiplies thermal protection points per vehicle.
UL certification requirements enforced by OSHA-aligned safety frameworks govern product approval across the United States, while Canada's CSA standards create a parallel compliance pathway for cross-border suppliers. NHTSA automotive safety regulations and EPA appliance efficiency mandates are tightening thermal protection specifications, effectively raising barriers for uncertified imports. Stakeholders must monitor evolving harmonization between UL and CSA test protocols to optimize single-platform certification strategies.
Market Dynamics
Electrification of transportation and industrial systems is multiplying thermal protection points per platform while tightening response-time tolerances, forcing component suppliers to bridge the gap between legacy bimetallic architectures and solid-state sensing topologies.
Growth Catalysts
- NHTSA Battery Safety Mandates:Federal automotive safety rules now mandate redundant thermal cutoff systems in high-voltage battery packs, creating standardized demand pull across EV platforms.
- EPA Appliance Efficiency Standards:Tightening energy consumption thresholds for HVAC and refrigeration equipment require precision thermal management, expanding specification-grade protector volumes.
- Ohio-Michigan Manufacturing Corridor:Concentrated appliance and automotive OEM presence in the Great Lakes industrial belt generates dense procurement clusters for thermal safety components.
Market Restraints
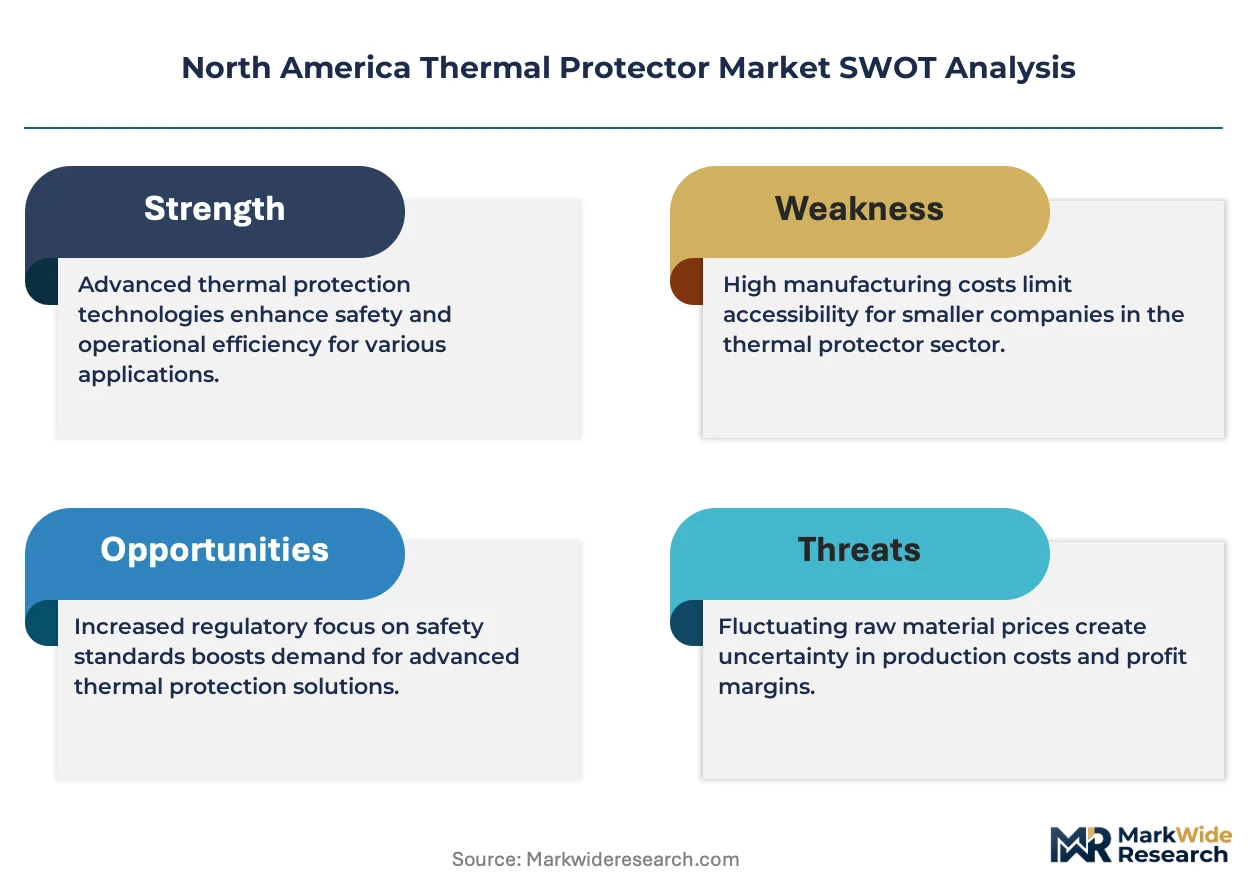
- Copper-Nickel Alloy Volatility:Bimetallic strip production depends on copper and nickel price stability, with input cost swings compressing margin predictability for mechanical switch manufacturers.
- Single-Source Certification Dependency:UL 60730 and CSA C22.2 approval processes create 18-24 month lock-in periods with designated test laboratories, limiting supplier agility.
- Solid-State Sensor Substitution:Thermistor-based electronic protection circuits in EV battery management systems threaten to displace electromechanical switches in high-value applications.
Strategic Opportunities
- Mexico Nearshoring Expansion:Appliance and automotive OEMs relocating assembly capacity to Baja California and central Mexico require localized thermal protector supply chains.
- Grid-Scale Energy Storage:Utility battery installations need distributed thermal monitoring architectures, opening new specification channels beyond traditional motor protection.
- IRA Clean Energy Tax Credits:Domestic content requirements for federally subsidized EV and renewable energy projects favor North American-certified thermal component suppliers.
Industry Challenges
- Cross-Disciplinary Engineering Talent:Convergence of electromechanical design with embedded firmware development creates acute hiring pressure for mechatronics specialists.
- Legacy System Integration Friction:Retrofitting precision electronic thermal switches into established appliance architectures requires redesign of mounting geometries and electrical interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Thermal Protector Market |
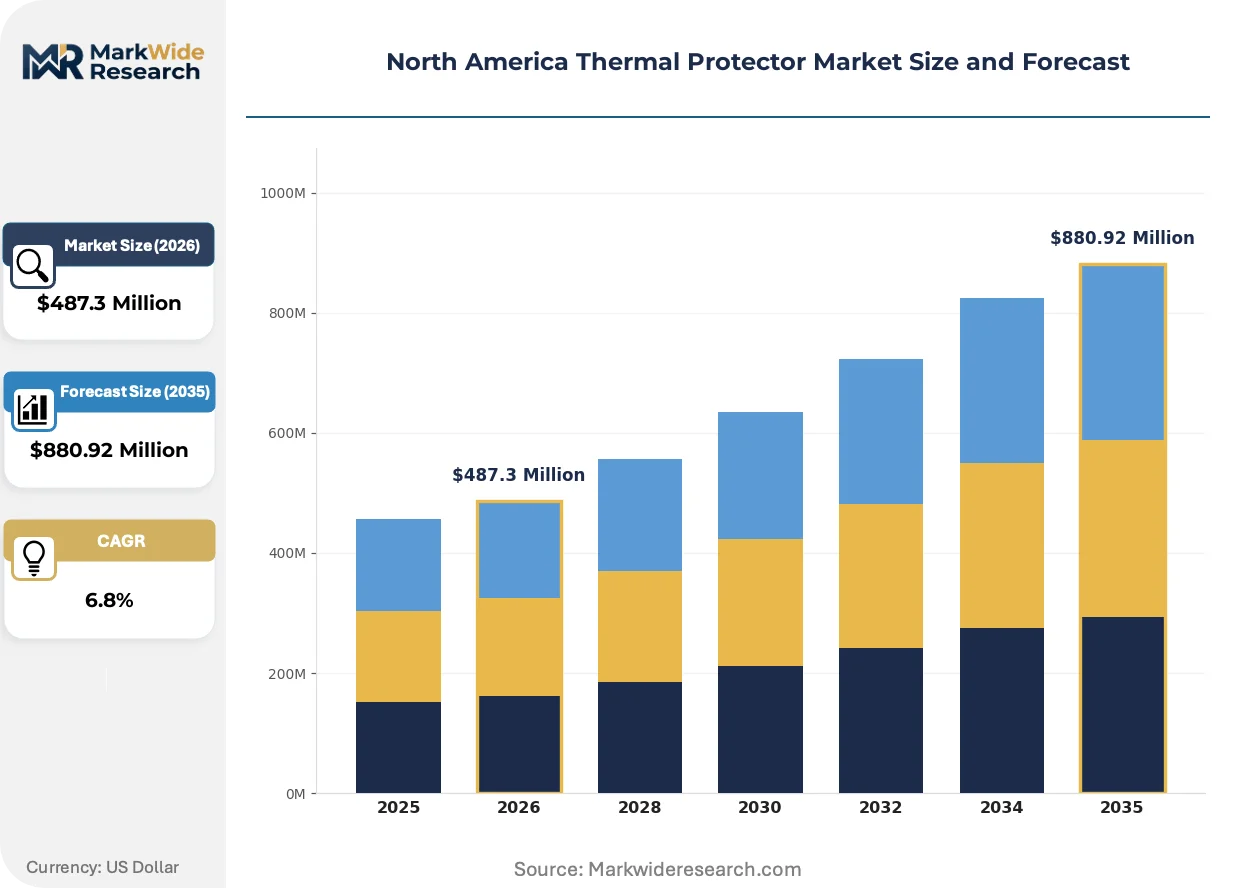
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitance Thermal Switch, Bimetallic Thermal Switch, Electronic Thermal Switch, Thermistor End User: Home Appliances, Automotive, HVAC Systems, Industrial Equipment Application: Overheating Protection, Temperature Control, Safety Devices, Energy Management Installation: Embedded, Panel Mounted, Standalone, Integrated |
| Companies Covered | Sensata Technologies, Portage Electric Products, Thermtrol Corporation, Calco Electric, Farnell, Bourns, Schneider Electric, Mersen, Thermal Management Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Thermal Protector Market Evolving Landscape
Solid-state sensing architectures are displacing mechanical trip mechanisms across premium application tiers, while regulatory pressure on response-time precision accelerates specification divergence between commodity and performance-grade product lines.
Silicon-based temperature sensors with integrated signal conditioning are integrating directly into EV battery cell monitoring units, replacing discrete bimetallic switches in high-voltage zones. Tier 1 automotive suppliers are adopting these modules at scale for 800V architectures. This integration is compressing the addressable market for traditional electromechanical protectors in electrified powertrains.
OSHA-aligned UL 60730 safety standard revisions are mandating shorter thermal response windows for motor-operated appliances, forcing redesign of bimetallic strip geometries. Manufacturers serving the HVAC and compressor segments are reformulating alloy compositions to maintain mechanical reliability under tighter calibration tolerances. The residential appliance sector bears the heaviest compliance burden, with certification retesting consuming 12-18 month development cycles.
Multi-source qualification requirements from appliance OEMs are fragmenting procurement volumes across three to four approved vendors per platform, displacing sole-source relationships that dominated the 2015-2020 period. Distributor-managed inventory programs are replacing direct mill shipments for standard thermal cutoffs. This pattern is most pronounced in the United States Midwest, where Whirlpool, Trane, and Carrier procurement teams have consolidated supplier panels.
North America Thermal Protector Market Segmentation
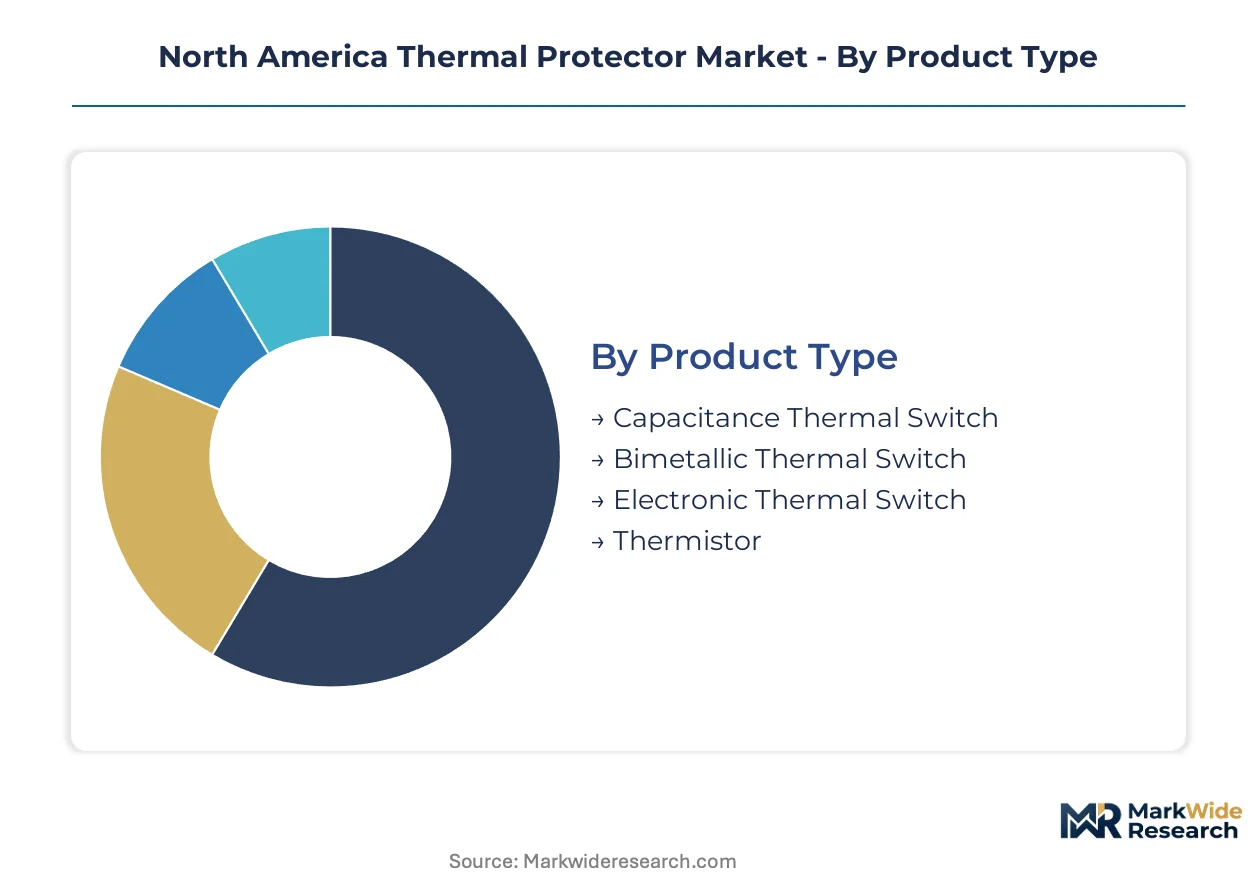
Thermal protector segmentation in North America reflects divergent technical requirements across electrification platforms. Specification-grade solid-state sensors command premium positioning in automotive battery management, while mechanical switches retain volume dominance in cost-sensitive appliance segments.
Product Type:
Bimetallic architectures anchor commodity production volumes, while electronic sensing topologies capture specification-grade margins in precision applications.
- Bimetallic Thermal Switch:Mechanical trip mechanisms employ copper-nickel alloy strips calibrated to deflect at specific temperature thresholds. Appliance OEMs in the Ohio-Michigan corridor specify these for compressor and motor windings where cost sensitivity outweighs precision requirements.
- Electronic Thermal Switch:Silicon-based sensors with integrated signal conditioning achieve sub-second response times for 800V EV battery architectures. Tier 1 automotive suppliers in Detroit and Silicon Valley procurement clusters are displacing mechanical alternatives in high-voltage zones.
- Capacitance Thermal Switch:Dielectric sensing elements detect thermal drift through capacitance variation rather than mechanical deformation.
- Thermistor:NTC and PTC ceramic components provide continuous temperature monitoring for closed-loop control systems in HVAC equipment.
Bimetallic thermal switches lead on scale; electronic thermal switches lead on momentum.
End User:
Automotive electrification multiplies protection points per vehicle, while appliance efficiency mandates sustain replacement demand in mature categories.
- Automotive:Battery thermal management systems require redundant cutoff circuits per NHTSA Federal Motor Vehicle Safety Standards. Each EV platform integrates 15-25 discrete protection nodes across pack, module, and cell-level architectures.
- Home Appliances:UL 60730 compliance drives specification upgrades for HVAC compressors and refrigeration systems. Whirlpool and Carrier procurement teams in the Midwest industrial belt manage multi-source qualification panels.
- HVAC Systems:Commercial and residential climate equipment deploy thermal protectors across compressor motors, fan assemblies, and heat exchanger circuits.
- Industrial Equipment:Motor control centers and variable frequency drives specify heavy-duty thermal cutoffs for continuous-duty applications.
Home appliances lead on scale; automotive leads on momentum.
Application:
Functional requirements separate commodity hardware from integrated safety systems in regulated environments.
- Overheating Protection:Fire-prevention mandates in OSHA-aligned safety frameworks require fail-safe interruption at calibrated thermal limits. Residential appliance manufacturers face 12-18 month UL recertification cycles for revised response windows.
- Temperature Control:Closed-loop regulation demands precision sensing for energy efficiency compliance with EPA appliance standards. HVAC OEMs specify tight-tolerance components to meet seasonal energy efficiency ratio thresholds.
- Safety Devices:Redundant cutoff architectures satisfy functional safety requirements in automotive and industrial machinery.
- Energy Management:Smart grid integration and demand-response systems incorporate thermal monitoring for load optimization.
Overheating protection leads on scale; temperature control leads on momentum.
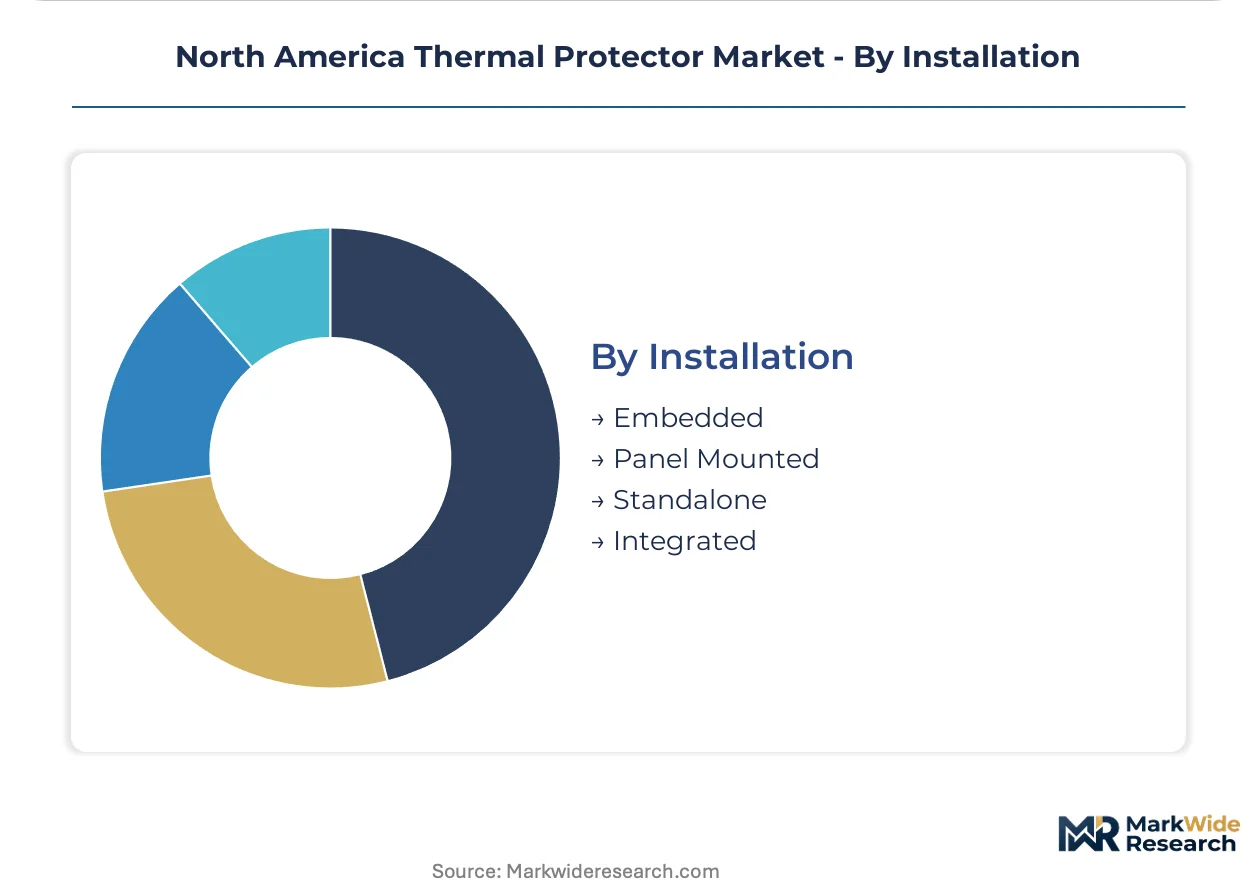
Installation:
Mounting configuration determines supply chain routing through OEM direct procurement versus distributor-managed inventory channels.
- Embedded:Direct integration into motor windings, battery cells, or semiconductor packages requires custom form factors and leadframe geometries. Automotive cell monitoring units specify these for space-constrained 800V architectures.
- Panel Mounted:Standardized housings with screw terminals or quick-connect interfaces serve aftermarket replacement and industrial maintenance channels.
- Standalone:Discrete units with independent enclosures address retrofit applications and legacy system upgrades.
- Integrated:Multi-function modules combine thermal protection with current sensing, arc detection, or communication interfaces for smart appliance platforms.
Panel mounted leads on scale; embedded leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration across North America tracks divergent compliance cost structures, with manufacturers arbitraging UL certification timelines against CSA approval pathways while positioning near automotive and appliance OEM clusters.
United States
EV battery thermal management systems and residential HVAC upgrades drive specification-grade demand. NHTSA Federal Motor Vehicle Safety Standards mandate redundant thermal cutoff architectures in high-voltage packs. The Ohio-Michigan industrial corridor concentrates procurement activity, with Detroit-area Tier 1 suppliers and Cleveland appliance manufacturers managing multi-source qualification panels.
Canada
Cross-border supplier certification harmonization creates competitive positioning advantages for CSA C22.2 pre-approved components. Health Canada safety frameworks align with OSHA-aligned UL protocols, reducing retesting burdens for integrated North American supply chains. Ontario's manufacturing belt around Toronto anchors appliance component distribution into US Midwest assembly plants.
Mexico
Nearshoring acceleration in Baja California and central Mexico generates localized thermal protector demand from relocated automotive and appliance assembly. IRA domestic content requirements for federally subsidized clean energy projects favor North American-certified suppliers serving Mexico-based OEMs. Querétaro and Nuevo León industrial parks concentrate new procurement clusters.
North America Thermal Protector Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state sensing architectures and EV battery integration partnerships. The vendor base organizes around three archetypes: vertically integrated bimetallic specialists, electronic sensing module developers, and diversified electrical component conglomerates. Capacity expansion and backward integration into copper-nickel alloy supply represent dominant competitive moves.
Among diversified electrical component groups, Sensata Technologies and Schneider Electric exemplify scale-driven positioning across automotive and industrial verticals. Portage Electric Products occupies a specialist niche within custom thermal cutoff fabrication for appliance OEMs. These three anchors illustrate the market's tiered structure: conglomerate breadth, mid-cap specialization, and emerging electronic architecture migration.
| Leading Market Players |
|---|
| Sensata Technologies |
| Portage Electric Products |
| Thermtrol Corporation |
| Calco Electric |
| Farnell |
| Bourns |
| Schneider Electric |
| Mersen |
| Thermal Management Technologies |
| Others |
Value Network & Pricing Analysis
Multi-source qualification mandates from appliance OEMs in the Ohio-Michigan corridor are compressing order volumes per supplier and forcing distributors to absorb inventory carrying costs, which reshapes margin allocation across mechanical switch tiers.
Pricing Analysis
Copper-nickel alloy cost pass-through dominates mechanical switch pricing, with bimetallic strip manufacturers indexing contracts to London Metal Exchange benchmarks. Price differentiation hinges on UL 60730 certification grade and volume scale, with uncertified imports facing 15-20 point margin disadvantages. Cost compression in commodity thermal cutoffs intensifies as Mexican nearshoring accelerates buyer consolidation. Appliance OEM procurement teams exhibit highest price sensitivity; Tier 1 automotive suppliers prioritize response-time precision over unit cost.
Supply Chain Analysis
Regional distribution centers in Cleveland, Detroit, and Toronto operate hub-and-spoke patterns serving the Great Lakes manufacturing belt. Production concentrates in the United States, Mexico, and Canada, with Querétaro industrial parks emerging as secondary sourcing nodes. Raw material feeds draw from Chilean copper and Indonesian nickel supply chains. Single-source certification dependency with UL and CSA laboratories creates 18-24 month lock-in vulnerability. Distribution runs through authorized distributor networks with consignment inventory programs replacing direct mill shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state sensor substitution in EV battery management systems is compressing electromechanical protector margins, yet backward integration into alloy supply and premium-tier electronic module development create offsetting expansion pathways.
For Market Incumbents: Extend bimetallic production scale in Mexico to capture IRA domestic content preference while accelerating firmware-capable electronic switch R&D to defend against silicon-based sensor displacement in 800V architectures. Lock in exclusive distributor consignment arrangements in the Midwest to forestall panel fragmentation. For New Entrants and Emerging Players: Capture grid-scale energy storage thermal monitoring specifications where incumbent electromechanical suppliers lack distributed sensing architectures. The most penetrable white space sits with utility battery installation contractors seeking North American-certified monitoring modules. Lead with integrated signal-conditioning modules that bypass traditional UL 60730 recertification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with electronic sensing module developers possessing embedded firmware capabilities and existing CSA pre-certification. Long-term viability favors suppliers bridging mechanical reliability with solid-state precision. Monitor NHTSA rulemaking on redundant thermal cutoff mandates as the inflection signal for specification-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper-Nickel Alloy Supply | Captive raw material sourcing insulates Sensata and Portage Electric from LME price volatility. |
| Electronic Sensing Module Development | Firmware-integrated thermal switches penetrate 800V EV battery architectures displacing mechanical alternatives. |
| Mexico Manufacturing Footprint Expansion | Querétaro and Nuevo León facilities qualify for IRA domestic content requirements on federally subsidized projects. |
| CSA Pre-Certification Investment | Parallel CSA C22.2 approval reduces cross-border retesting burdens for integrated North American supply chains. |
| Distributor Consignment Program Deployment | Inventory-bearing partnerships with Cleveland and Detroit distributors lock out emerging competitors from Midwest procurement panels. |
Research Methodology
Direct dialogue with thermal protector procurement managers at appliance OEMs, Tier 1 automotive supplier platform engineers, UL certification laboratory technical leads, and copper-nickel alloy distribution channel heads grounded qualitative findings. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standard filings, EPA appliance efficiency rulemaking dockets, UL 60730 standard revision records, and SEC 10-K disclosures from listed electrical component conglomerates. Bottom-up unit volume estimates triangulated against top-down market value reconstructions.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, end-user vertical, and installation configuration dimensions. Automotive content-per-vehicle thermal protection node counts and appliance OEM multi-source qualification panel sizes served as industry-specific forecast inputs. CAGRs derived from regression-weighted scenario analysis across electrification penetration curves and regulatory compliance timeline assumptions.
Copper-nickel price volatility, NHTSA rulemaking acceleration, and solid-state sensor substitution velocity are the dominant revision risks to baseline projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
Contactors Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
Fiberglass Electrical Enclosure Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Busbar Systems Market