
 Busbar Systems Market | 2026-2036
Busbar Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Busbar Systems Market Outlook
Shortages of certified electrical engineers and specialized busbar assembly technicians is reorganizing production timelines across the industry. Schneider Electric SE leverages its global manufacturing footprint to sustain delivery commitments amid labor constraints. Siemens AG anchors its position through intensive R&D in compact busway configurations. ABB Ltd competes on vertical integration from copper processing to finished systems.
A busbar system comprises rigid conductive bars, typically copper or aluminum, engineered to distribute electrical power within switchgear, distribution boards, and industrial facilities with current ratings from hundreds to thousands of amperes. Insulated busbars incorporate epoxy resin or PVC coatings to prevent accidental contact and reduce phase-to-phase clearance requirements. Bare busbars retain cost advantages in controlled indoor environments where space and touch protection are managed through enclosure design. Copper material commands premium positioning due to superior conductivity, while aluminum segments expand in price-sensitive utility-scale installations.
The U.S. National Electrical Code administered by NFPA shapes conductor sizing and ampacity requirements that manufacturers must satisfy for market access. European CE marking under the Low Voltage Directive and IEC 61439 standards govern short-circuit withstand and temperature-rise limits across EU member states. India's BIS certification mandates additional testing protocols for imported busbar assemblies. Stakeholders must monitor evolving efficiency benchmarks and local content rules as electrification policies diverge across major economies.
Market Dynamics
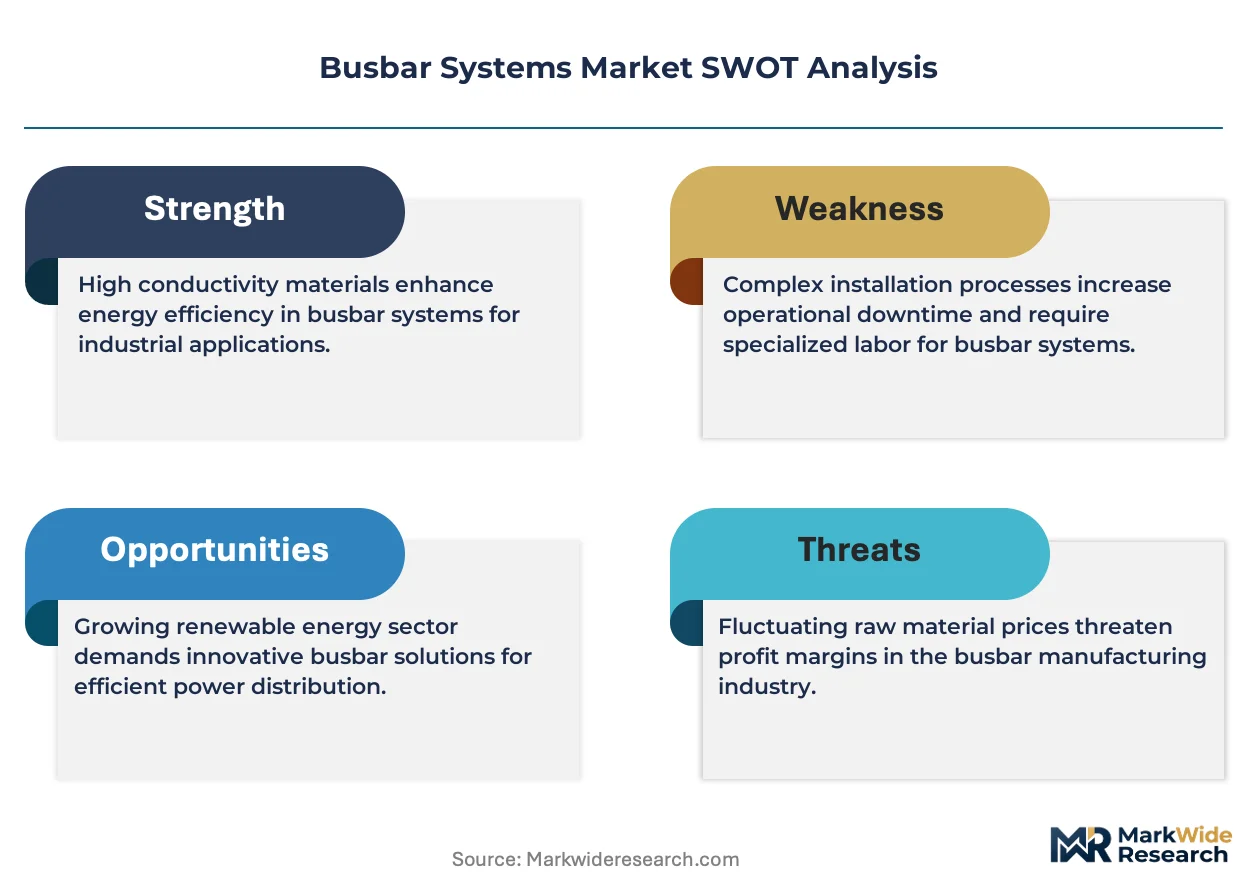
The EU Green Deal and U.S. IRA provisions are compressing procurement timelines as buyers requalify suppliers against stricter efficiency benchmarks, forcing manufacturers to accelerate low-loss design certification cycles.
Growth Catalysts
- Data Center Electrification:Hyperscale facilities in Virginia, Frankfurt, and Singapore are specifying copper-intensive busway configurations to handle 50kA+ fault currents from AI server racks.
- CE Marking Under IEC 61439:The Low Voltage Directive's tightened temperature-rise limits are filtering out non-compliant imports across EU member states, consolidating demand around certified domestic producers.
- Aluminum Substitution Economics:Utility-scale solar and wind installations in Rajasthan and Texas are adopting aluminum busbar assemblies where conductivity trade-offs are offset by 40% material cost savings.
Market Restraints
- Copper Price Volatility:LME copper contract swings above $9,000/tonne are compressing margin buffers for manufacturers without captive smelter arrangements or indexed customer contracts.
- Certified Engineer Scarcity:Germany's VDE certification pathway and India's CEA licensing requirements face 18-month backlogs, extending project commissioning timelines for complex busway installations.
- Cast Resin Lead Times:Epoxy resin suppliers concentrated in China's Jiangsu province are prioritizing semiconductor packaging demand, creating 12-week insulation material shortages for busbar coaters.
Strategic Opportunities
- Modular Plug-In Busway:Data center operators in Ashburn and Amsterdam are specifying tap-off box configurations that enable 72-hour capacity reconfiguration without shutdown, displacing traditional cable tray infrastructure.
- BIS Certification Arbitrage:Domestic Indian manufacturers with in-house testing laboratories are capturing import substitution demand as DGFT customs clearance timelines stretch for unregistered foreign suppliers.
- Digital Twin Integration:Siemens and ABB are embedding thermal monitoring sensors into busway enclosures, converging power distribution with predictive maintenance platforms for industrial facility operators.
Industry Challenges
- Short-Circuit Testing Bottlenecks:KEMA and CESI laboratory capacity constraints in Arnhem and Milan are extending IEC 61439-1 verification timelines from 8 weeks to 20 weeks for new product introductions.
- Legacy Switchgear Interoperability:Brownfield industrial sites in the U.S. Rust Belt and Germany's Ruhr region require custom adapter kits to interface new busway systems with 1970s-vintage breaker compartments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Busbar Systems Market |
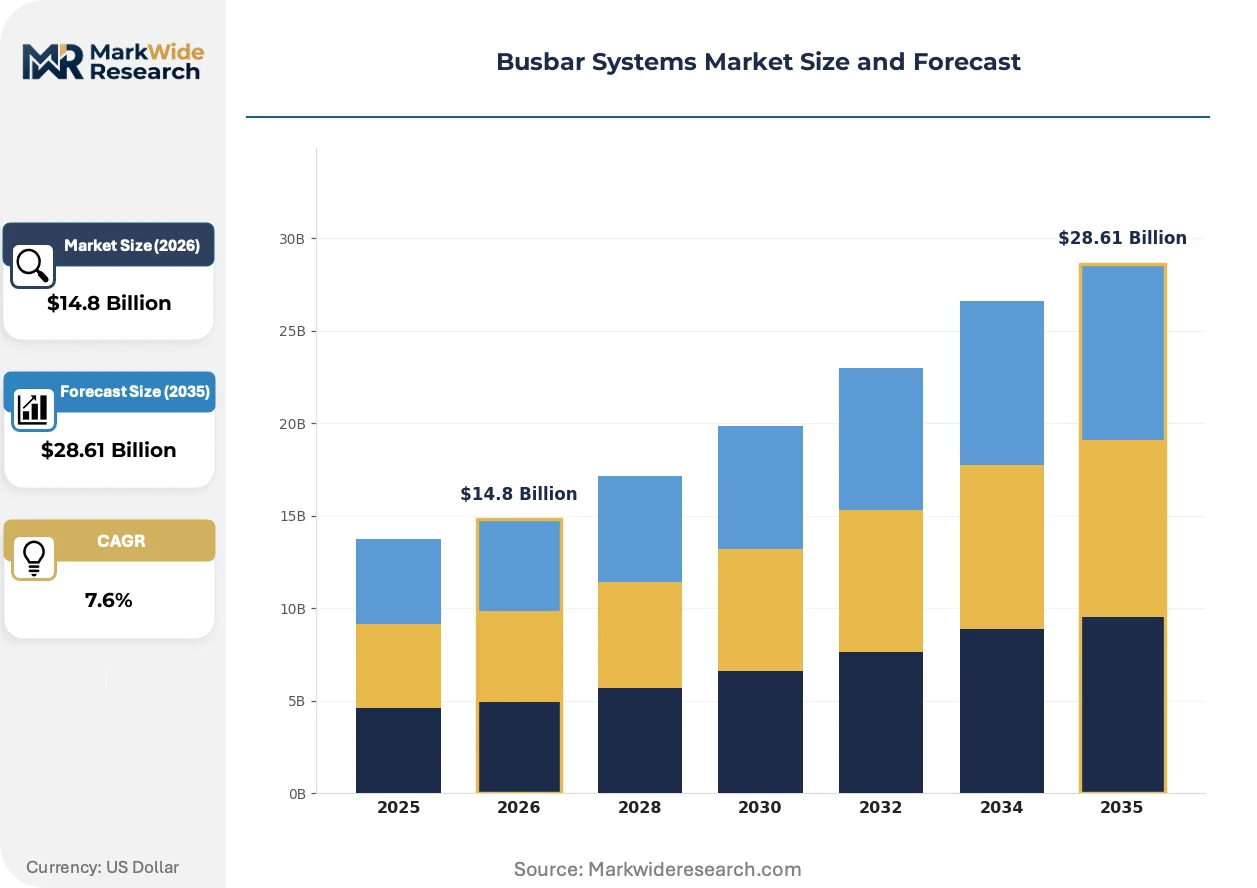
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Busbars, Bare Busbars, Busway, Bus Ducts End User: Commercial Buildings, Manufacturing Facilities, Power Plants, Data Centers Installation Type: Indoor, Outdoor, Wall-mounted, Free-standing Material: Copper, Aluminum, Steel, Brass |
| Companies Covered | ABB Ltd, Schneider Electric SE, Siemens AG, Eaton Corporation, Legrand SA, Mersen, General Electric Company, Rittal GmbH, Godrej & Boyce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Busbar Systems Market Strategic Shifts
Busbar system architecture is bifurcating between compact, sensor-embedded designs for space-constrained data centers and ruggedized, corrosion-resistant configurations for offshore renewable interconnects.
Epoxy resin vacuum-casting technology is fragmenting the insulation landscape. The process eliminates voids in thick-walled busbar coatings, improving dielectric strength for 36kV-rated systems. Offshore wind developers in the North Sea and Taiwan Strait are specifying cast-resin busduct for salt-laden environments. This material shift is fragmenting supplier tiers as coating specialists without vacuum equipment lose access to high-voltage marine contracts.
REACH Annex XVII restrictions on halogenated flame retardants are forcing reformulation of PVC-based busbar sleeving across EU manufacturing. Compounders in Belgium and Italy are accelerating phosphorous-nitrogen alternative validation. The transition is compressing formulation margins for small-batch insulation producers while favoring integrated manufacturers with captive polymer labs.
Engineering-procurement-construction firms are unbundling busway installation from equipment supply, creating direct relationships between end-users and certified assembly contractors. Data center developers in Singapore and Dublin are issuing separate tenders for busbar hardware and installation labor, bypassing traditional switchgear OEM channel structures. This disintermediation is visible most acutely in hyperscale projects where standardized designs reduce specification risk.
Busbar Systems Market Segmentation
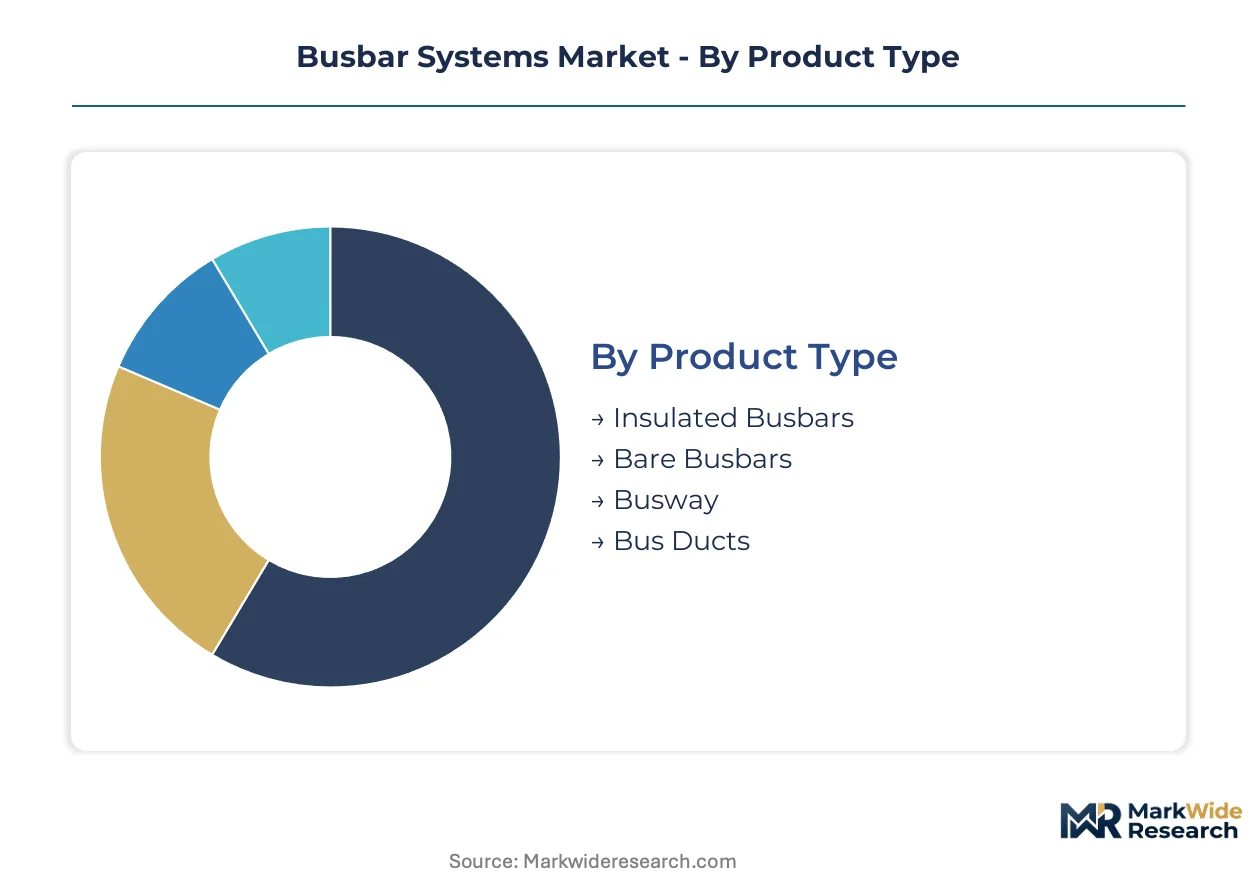
Busbar system specifications diverge sharply across installation environments and current-carrying requirements. Procurement criteria in this market are increasingly shaped by regional efficiency mandates and site-specific electrical codes rather than generic performance metrics.
Product Type:
IEC 61439-1 and UL 857 testing protocols create divergent certification pathways for each product configuration, filtering supplier participation by technical capability.
- Insulated Busbars:These incorporate epoxy resin or PVC-based coatings that prevent accidental contact and enable reduced phase-to-phase clearances. Data centers in Frankfurt and Singapore are specifying cast-resin insulated designs rated for 36kV to handle AI-driven fault current escalation. The REACH Annex XVII halogenated flame retardant ban is forcing compound reformulation across EU manufacturing.
- Busway:Modular plug-in configurations with tap-off box flexibility are displacing traditional cable tray infrastructure in hyperscale facilities. Operators in Ashburn and Amsterdam value 72-hour capacity reconfiguration without shutdown. This segment climbs fastest as digital infrastructure deployment accelerates.
- Bare Busbars:Uninsulated copper or aluminum bars retain cost advantages in controlled indoor environments where enclosure design manages touch protection.
- Bus Ducts:Enclosed feeder systems with integrated housing provide standardized power distribution for commercial and industrial switchgear applications.
Established volume favors bare busbars in legacy industrial infrastructure; emerging adoption favors busway in data center electrification.
End User:
Current density requirements and uptime specifications segment demand across facility types with radically different procurement timelines.
- Data Centers:Hyperscale operators in Virginia, Singapore, and Dublin specify copper-intensive configurations handling 50kA+ fault currents from AI server rack densities. Separate tendering for hardware and installation labor is disintermediating traditional switchgear OEM channels.
- Manufacturing Facilities:Brownfield sites in Germany's Ruhr region and the U.S. Rust Belt require custom adapter kits to interface new busway with 1970s-vintage breaker compartments, extending project complexity.
- Commercial Buildings:Standardized distribution boards and switchgear applications drive volume demand with moderate technical specification requirements.
- Power Plants:Utility-scale generation and substation interconnects prioritize short-circuit withstand ratings and temperature-rise performance under continuous load.
Data centers command premium pricing for high-current density; manufacturing facilities represent replacement-driven steady demand.
Installation Type:
Environmental exposure ratings and spatial constraints determine enclosure specifications and material selection priorities.
- Outdoor:Salt-laden environments in the North Sea and Taiwan Strait are specifying vacuum-cast epoxy resin busduct with corrosion-resistant housings. Offshore wind developers prioritize dielectric integrity under humidity cycling and temperature extremes.
- Indoor:Climate-controlled environments permit bare busbar deployment where enclosure design satisfies touch protection requirements without insulation coating costs.
- Wall-mounted:Space-constrained commercial and industrial facilities value vertical installation profiles that preserve floor area for production equipment.
- Free-standing:Heavy-current industrial applications require structural support independent of building infrastructure for maintenance access and seismic isolation.
Outdoor installations gain share fastest in renewable interconnect buildouts; indoor configurations retain cost advantage in controlled manufacturing environments.
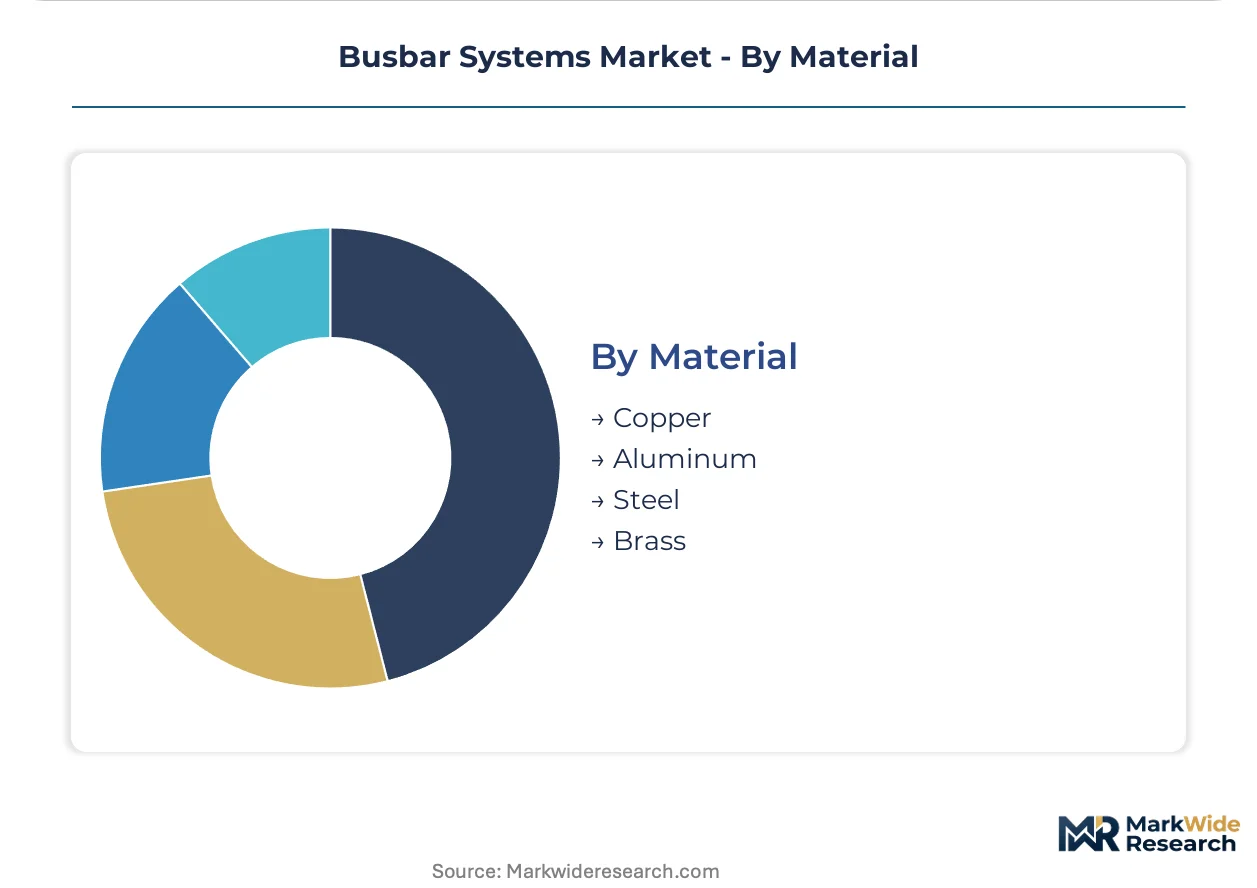
Material:
Conductivity requirements and commodity price exposure segment procurement across cost-performance tradeoffs.
- Copper:Superior electrical conductivity positions this material for high-current density applications where resistive losses compound operating costs. LME contract volatility above $9,000/tonne compresses margins for manufacturers lacking indexed customer contracts or captive smelter arrangements.
- Aluminum:Utility-scale solar and wind installations in Rajasthan and Texas are adopting aluminum assemblies where conductivity trade-offs are offset by material cost savings approaching 40 percent. This segment expands most quickly in price-sensitive renewable infrastructure.
- Steel:Structural and grounding applications leverage mechanical strength rather than optimized conductivity for specific protective functions.
- Brass:Specialized connector and termination applications utilize corrosion resistance and machinability for critical interface points.
Copper anchors premium positioning in fault-current-intensive applications; aluminum captures volume in utility-scale renewable deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial corridor while cost-sensitive procurement dominates India's utility-scale solar belt, creating a regional asymmetry that shapes manufacturer margin strategies across the forecast horizon.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives copper-intensive busway specifications for 50kA+ fault current handling. NFPA's National Electrical Code shapes conductor sizing mandates that filter supplier participation. Ashburn's server farm cluster commands premium configurations with 72-hour reconfiguration tap-off flexibility.
Germany
Ruhr region brownfield industrial sites require custom adapter kits for 1970s-vintage breaker interoperability. EU Green Deal efficiency benchmarks compress procurement timelines as buyers requalify suppliers. Frankfurt's data center corridor anchors European demand for cast-resin insulated 36kV-rated systems.
China
Jiangsu province's epoxy resin suppliers prioritize semiconductor packaging over busbar insulation, creating material shortages for domestic coaters. Dual carbon goals accelerate grid modernization programs. Yangtze River Delta manufacturing clusters concentrate low-loss busway production for export markets.
India
Rajasthan's utility-scale solar installations adopt aluminum busbar assemblies where material cost savings offset conductivity trade-offs. BIS certification mandates extend DGFT customs clearance timelines for unregistered imports. Gujarat's domestic manufacturers with in-house testing laboratories capture import substitution demand.
Singapore
Tropical data center operators specify corrosion-resistant housings for high-humidity environments. Separate tendering for hardware and installation labor disintermediates traditional switchgear OEM channels. The city-state's digital infrastructure hub status attracts modular plug-in busway configurations from regional suppliers.
Busbar Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated electrical conglomerates dominating premium specifications while regional fabricators capture price-sensitive utility installations. The market structure tiers around certification depth, manufacturing scale, and vertical control over copper processing. Three archetypes prevail: global switchgear OEMs with captive smelter arrangements, insulation specialists with vacuum-casting equipment, and domestic assemblers leveraging BIS or CE marking arbitrage. Capacity expansion and strategic partnerships represent the dominant competitive moves as laboratories face testing bottlenecks.
Among European-based conglomerates, ABB Ltd, Schneider Electric SE, and Siemens AG exemplify the integrated archetype spanning material processing through finished system delivery. These entities anchor premium positioning through captive supply chains and intensive R&D commitments. Regional specialists occupy tiered positions beneath this layer, with certification capabilities and geographic proximity determining access to data center and renewable interconnect projects.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric SE |
| Siemens AG |
| Eaton Corporation |
| Legrand SA |
| Mersen |
| General Electric Company |
| Rittal GmbH |
| Godrej & Boyce |
| Others |
Value Chain & Pricing Dynamics
Twelve-week epoxy resin lead times from Jiangsu province coaters are compressing margin buffers for insulated busbar manufacturers while simultaneously amplifying pricing power for vacuum-casting specialists with captive polymer supply. This inventory constraint feeds directly into procurement timelines for data center operators in Frankfurt and Singapore, forcing tiered sourcing strategies that separate premium cast-resin configurations from standard PVC-coated alternatives.
Pricing Analysis
The customization-premium spread between configured-to-order 36kV cast-resin busduct and standard bare copper busbars runs wide, with project-based pricing dominating large industrial installations while per-unit transactional models govern commercial building specifications. Price differentiation rests on IEC 61439-1 certification tier and copper content grade, with hyperscale data center buyers showing lowest sensitivity due to uptime requirements while utility-scale solar developers in Rajasthan exhibit highest price elasticity. Pricing pressure stems from LME copper volatility above $9,000/tonne, compressing margins for manufacturers lacking indexed customer contracts.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo port congestion and Red Sea container rerouting are elevating landed costs for European OEMs sourcing Chinese epoxy resin and Indian copper rod. Supply concentrates in China's Yangtze River Delta for busway fabrication, Germany's industrial corridor for precision assembly, and India's Gujarat belt for aluminum extrusion. Raw material dependencies center on LME copper cathodes, Jiangsu-sourced epoxy resin, and Chilean copper concentrate. Single-source vulnerability in semiconductor-packaging-competing resin supply creates structural risk. Distribution runs through EPC contractors and direct OEM channels to end-user facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Busbar system demand is fragmenting across voltage tiers and certification grades, creating niche opportunities for specialists as data center electrification diverges from utility-scale renewable deployment. This demand-side specialization rewards focused capabilities over broad portfolios.
For Market Incumbents: Fortify captive smelter arrangements or indexed copper contracts to offset LME volatility compression. Deepen backward integration into epoxy resin compounding to circumvent Jiangsu supplier prioritization of semiconductor packaging. Expand KEMA and CESI pre-certified product platforms to bypass 20-week laboratory bottlenecks for new introductions.
For New Entrants and Emerging Players: Differentiate on BIS certification arbitrage for Indian import substitution, leveraging in-house testing laboratories to capture DGFT clearance delays affecting unregistered foreign suppliers. Target aluminum busbar assemblies for Rajasthan and Texas utility-scale solar where conductivity trade-offs are accepted. Pursue direct EPC relationships in Singapore and Dublin where hardware-installation unbundling disintermediates traditional OEM channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized busbar divisions lacking vacuum-casting capabilities or data center certification depth. Long-term viability favors specialists with IEC 61439-1 testing infrastructure and hyperscale operator relationships over commodity bare busbar fabricators. Watch KEMA and CESI laboratory capacity expansion announcements as inflection indicators for new product introduction velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum-Casting Capacity Expansion | Captures offshore wind demand in North Sea and Taiwan Strait salt-laden environments. |
| Digital Twin Sensor Integration | Converges power distribution with predictive maintenance platforms for industrial operators. |
| Modular Plug-In Busway Development | Enables 72-hour capacity reconfiguration for hyperscale data centers without shutdown. |
| Backward Integration into Copper Processing | Insulates margin buffers from LME volatility above $9,000/tonne contract swings. |
| BIS Certification Laboratory Investment | Accelerates DGFT customs clearance for domestic Indian manufacturers versus import delays. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating procurement directors at hyperscale data center developers, EPC contractors in renewable interconnect projects, busbar manufacturing plant managers, and copper smelter sales executives. Secondary validation drew from IEC 61439-1 certification databases, LME copper contract filings, BIS registration records, and EU Green Deal efficiency benchmark documentation. Bottom-up installation volume estimates triangulated against top-down grid modernization expenditure allocations.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type (insulated busbar, busway, bare busbar, bus duct), material composition (copper, aluminum, steel, brass), installation environment (outdoor, indoor, wall-mounted, free-standing), and end-user vertical (data center, manufacturing facility, commercial building, power plant). CAGRs were derived from elasticity-adjusted adoption curves reflecting regulatory mandate timelines and infrastructure investment cycles. Industry-specific inputs included AI server rack density forecasts for fault current escalation and offshore wind capacity additions for marine-grade busduct demand.
Decision-makers should treat outputs as directional under base assumptions of sustained copper price volatility and laboratory certification bottlenecks; material deviation in resin supply normalization or testing capacity expansion would warrant model refresh. Forecasts embed assumptions around EU Green Deal implementation pace and U.S. IRA efficiency procurement timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
High Voltage Electric Insulators Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Flexible Heating Element Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
DC Contactor Market
Electrical Equipment
Heat Shrink Terminations Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
Saudi Arabia Electric Motor Market
Electrical Equipment
Motor Control Centers (MMC) Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
India Electrical Enclosures Market