
 Contactors Market | 2026-2036
Contactors Market Size, Share, and Industry Trends Forecast 2026-2036
Contactors Market Insights
Multi-source procurement for critical power components is hardening across OEM supply chains. ABB leverages its IEC-certified manufacturing footprint across Europe and Asia to anchor utility-scale contracts. Siemens competes through in-house production of vacuum interrupters, sustaining margin control amid copper price volatility. Schneider Electric differentiates via digital contactor lines with embedded condition monitoring, positioning its offer for predictive maintenance contracts in data centers.
A contactor is an electrically controlled switch designed for repeated make-and-break operations at currents typically exceeding 15 amperes, utilizing electromagnetic coils to actuate main contacts with auxiliary blocks for interlocking and signaling. Its primary industrial purpose is to control motor loads, capacitor banks, and resistive heating elements while providing isolation and overload protection in three-phase power systems. AC contactors still occupy the largest volume share across manufacturing plants and building automation, though DC contactors are gaining fastest in energy generation and transportation systems as solar inverter and EV charging deployments multiply. Electromechanical technology dominates installed base revenues, yet electronic and solid-state variants are capturing margin pools in telecommunications and data center applications where switching speed and arcless operation justify premium positioning.
FERC grid reliability standards, the EU Ecodesign Directive, and China's GB 14048 series collectively mandate higher electrical endurance and lower contact wear in power switching equipment. These frameworks compel manufacturers to redesign arc chambers and adopt silver-cadmium oxide alternatives, reshaping material sourcing and testing protocols. Stakeholders must monitor how IEC-UL convergence on DC switching ratings alters certification costs and market access timelines for hybrid and vacuum contactor platforms.
Market Dynamics
The electrification of transportation and renewable energy systems is forcing contactor manufacturers to redesign arc-quenching chambers and thermal management systems for DC switching loads. IEC 60947-4-1 and UL 60947-4-1 convergence on DC ratings is compressing certification timelines and reshaping R&D allocation across the supply base.
Growth Catalysts
- EV Charging Infrastructure Mandates:China's dual carbon goals and state grid modernization directives are accelerating procurement of high-voltage DC contactors for ultra-fast charging stations. Fleet operators and utilities in the country are specifying 1000V+ rated switching equipment.
- IEC-UL Standards Convergence:Harmonized testing protocols for arc endurance and electrical life are reducing duplicate certification costs. Manufacturers with dual-certified product lines are capturing utility-scale contracts in multiple jurisdictions.
- Silver-Cadmium Oxide Alternatives:Advances in silver-tin oxide and silver-nickel contact materials are meeting REACH environmental requirements while maintaining switching performance. Material suppliers are scaling production of cadmium-free alternatives for European OEMs.
Market Restraints
- Copper Price Volatility:Coil windings and busbar materials constitute 25-35% of contactor BOM costs. Smaller manufacturers lack hedging programs and face margin compression when London Metal Exchange copper prices spike.
- Vacuum Interrupter Supply Concentration:Production of ceramic vacuum bottles clusters in Japan and select European facilities. Buyers face extended lead times and sole-source risk for medium-voltage DC switching applications.
- Technical Limitation in DC Arc Interruption:Absence of natural current zero crossings in DC systems demands larger arc chambers and magnetic blowout coils. This increases unit weight and enclosure size for equivalent ampere ratings.
Strategic Opportunities
- Data Center Predictive Maintenance:Embedded condition monitoring with IoT-enabled contactors allows OEMs to attach recurring service revenue streams. Hyperscale operators in Northern Virginia and Frankfurt are piloting digital contactor fleets.
- India Solar Inverter Integration:The country's PLI scheme for solar manufacturing is creating demand for 1500V DC contactors in string inverter assemblies. Domestic assembly plants require localized supply chains.
- Telecommunications Solid-State Switching:Thyristor-based contactors eliminate arcing and mechanical wear for battery backup systems. 5G base station deployments in South Korea and Germany are specifying solid-state variants for 10+ year maintenance-free operation.
Industry Challenges
- DC Switching Certification Expertise Gap:Test engineers with IEC 60947-4-1 DC rating experience are scarce in North American laboratories. Third-party certification bodies face 6-9 month backlog for new product submissions.
- Legacy Electromechanical System Integration:Solid-state and hybrid contactors require redesigned control voltage interfaces and thermal management. Retrofit projects in industrial motor control centers encounter wiring incompatibility and technician retraining costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactors Market |
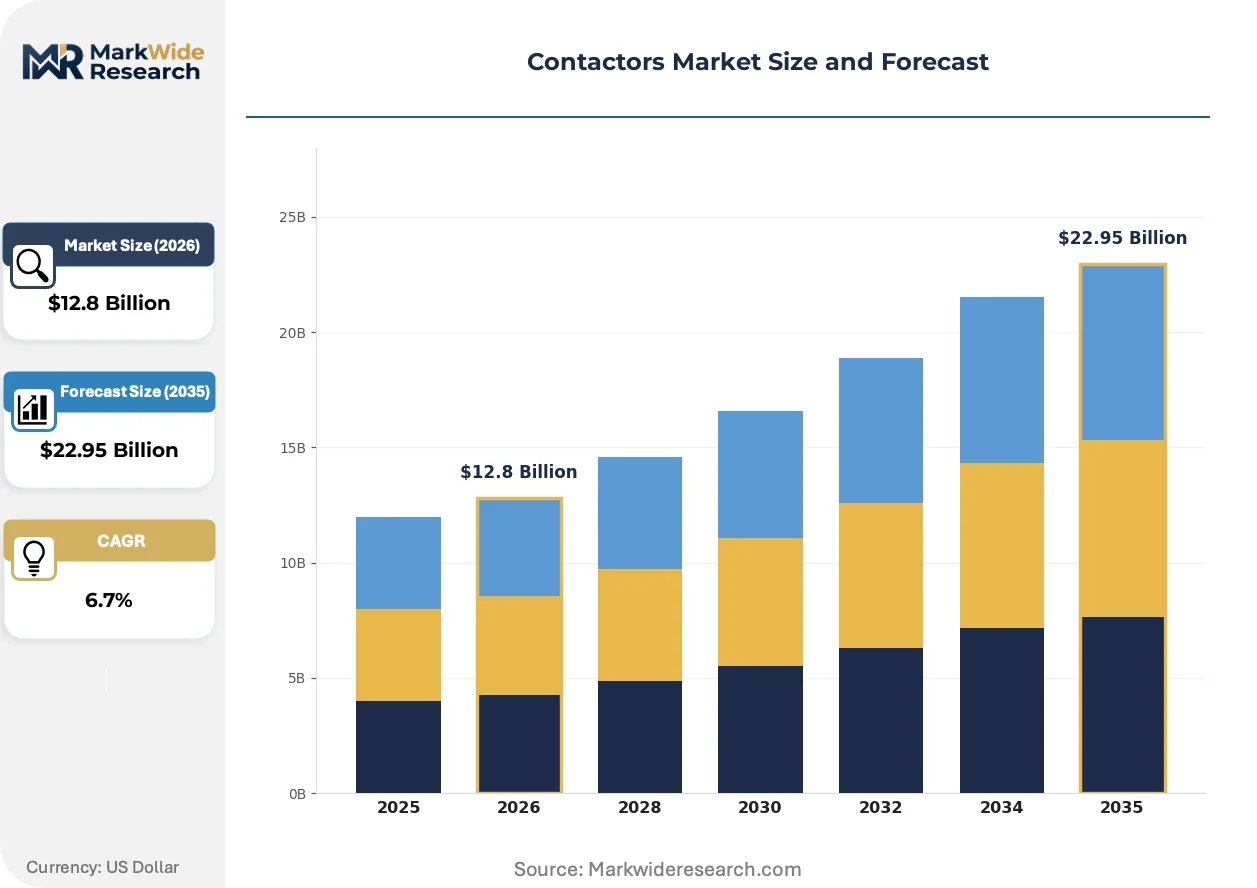
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Contactors, DC Contactors, Hybrid Contactors, Vacuum Contactors, Solid State Contactors Technology: Electromechanical, Magnetic, Thermal, Electronic, Mechanical Latching Application: Manufacturing Plants, Energy Generation, HVAC Systems, Transportation Systems, Building Automation End User Industry: Power Generation, Data Centers, Mining Operations, Commercial Facilities, Telecommunications |
| Companies Covered | ABB, Siemens, Schneider Electric, Eaton, Mitsubishi Electric, Rockwell Automation, Fuji Electric, Omron, Lovato Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactors Market Trends and Innovations
Contactor technology is bifurcating between high-performance DC switching for energy transition applications and intelligent electromechanical systems for predictive maintenance. Material science advances and embedded electronics are reshaping product architectures faster than replacement cycles in installed base equipment.
Hybrid contactor designs combining electromechanical main contacts with solid-state pre-charge circuits are expanding into solar inverter and energy storage applications. Inverter OEMs in China and Germany are specifying these units to eliminate inrush current damage to capacitor banks. The technology is expanding into 1500V DC string configurations where pure electromechanical solutions face endurance limitations.
EU Ecodesign Directive tightening on contactor electrical endurance and contact wear is forcing redesign of arc chamber geometries. Manufacturers must demonstrate 1-5 million electrical operations for premium product tiers under standardized load conditions. The regulation most affects suppliers serving industrial motor control markets in Germany and Italy, where end-users specify extended-life products for continuous process applications.
Buying patterns among utilities and fleet operators now favor multi-source qualification for critical power components over single-source relationships. Engineering-procurement firms in Texas and California are mandating second-source approval for contactor SKUs above defined voltage thresholds. This behavior is most visible in North American EV charging infrastructure rollouts, where project financiers require supply continuity assurances for 10-year operational horizons.
Contactors Market Segmentation
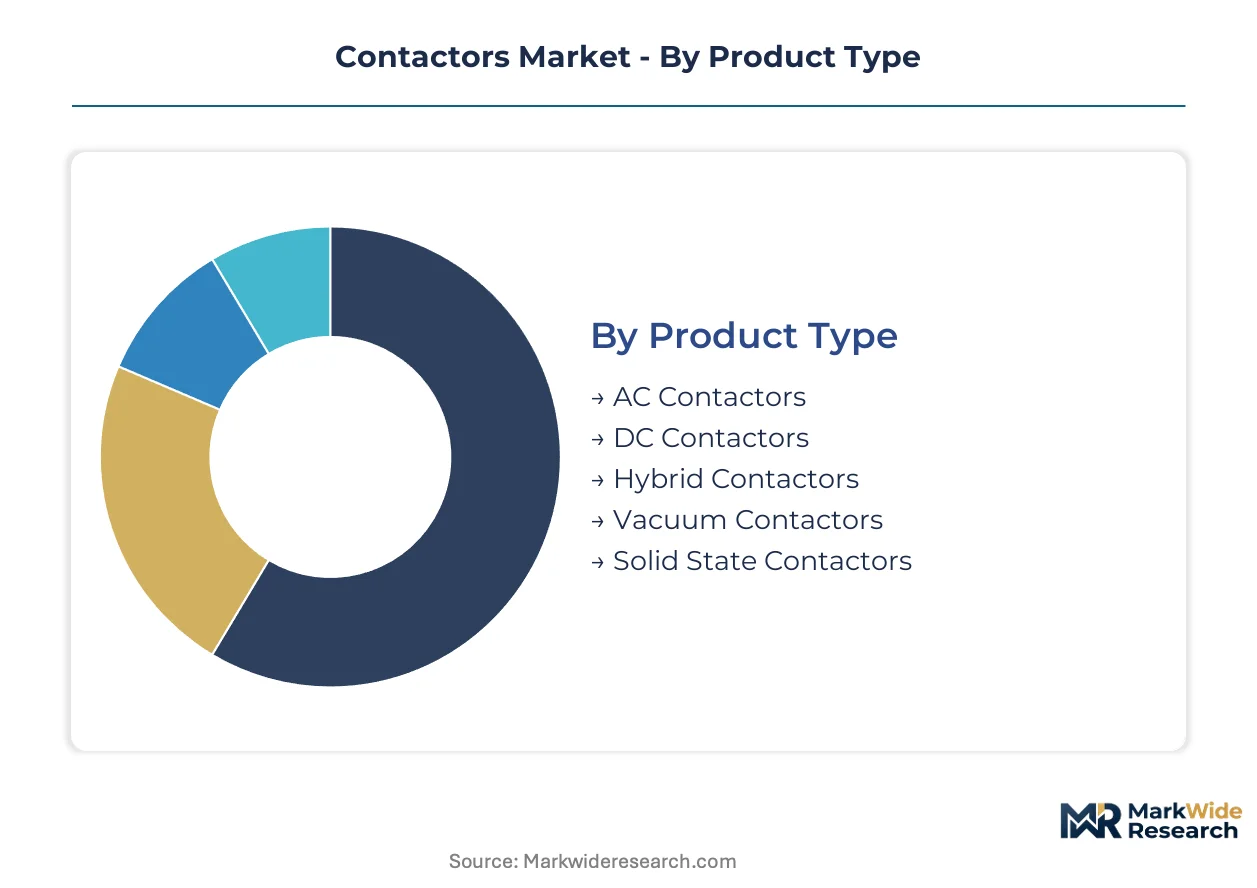
Contactor procurement patterns diverge sharply across product architectures and end-use environments. Capital allocation, certification requirements, and replacement cycles vary by segment, reshaping how manufacturers configure their product portfolios and geographic presence.
Product Type:
Capital intensity escalates with arc-quenching complexity and voltage ratings, placing vacuum and hybrid designs at the top of the investment hierarchy while AC contactors anchor volume production.
- AC Contactors:Three-phase electromechanical switches with laminated magnetic cores and silver alloy contacts dominate motor control centers and building automation. Demand concentrates in German automotive manufacturing plants where continuous process lines specify million-cycle electrical endurance ratings.
- DC Contactors:High-voltage switching equipment with magnetic blowout coils and reinforced arc chambers handles photovoltaic inverters and battery storage systems. Procurement is accelerating across Chinese ultra-fast EV charging stations where 1000V+ ratings are becoming standard.
- Hybrid Contactors:Electromechanical main contacts paired with solid-state pre-charge circuits eliminate inrush current damage. These units are gaining traction in 1500V solar string configurations where pure electromechanical solutions face durability constraints.
- Vacuum Contactors:Ceramic vacuum interrupters enable medium-voltage switching without arc gas emissions. Lead times extend 6-9 months due to concentrated production in Japanese and European facilities.
- Solid State Contactors:Thyristor-based switching eliminates mechanical wear and arcing entirely. South Korean 5G base station deployments specify these for decade-long maintenance-free operation.
Most installed capacity flows through AC Contactors. Expansion is steepest in DC Contactors.
Technology:
Technology selection determines coil power consumption, switching speed, and compatibility with legacy control voltages, creating distinct margin tiers across the supplier base.
- Electromechanical:Conventional electromagnetic actuation with copper windings and spring-loaded contact bridges. This technology retains dominant share across Indian cement plants and steel mills where technician familiarity reduces maintenance costs.
- Electronic:Microprocessor-controlled switching with programmable logic interfaces and energy monitoring. Data center operators in Northern Virginia pilot these units for predictive maintenance contracts.
- Magnetic:Permanent magnet-assisted actuation reduces holding power and coil heating. Japanese rail electrification projects specify magnetic contactors for tunnel installations with limited ventilation.
- Thermal:Bimetallic strip overload protection integrated into contactor housings. These units serve residential and light commercial HVAC markets where combined protection simplifies panel design.
- Mechanical Latching:Two-coil pulse-actuated designs maintain contact position without continuous power draw. Battery-backed telecommunications shelters in Germany favor latching contactors for energy conservation.
Electromechanical platforms carry the largest replacement parts revenue. Electronic variants are climbing the fastest.
Application:
Application context dictates enclosure ratings, pollution degree classifications, and duty cycle specifications, fragmenting procurement requirements across vertical markets.
- Manufacturing Plants:Motor control centers and conveyor systems require IEC 60947-4-1 Category AC-3 contactors with 600V ratings. Italian packaging machinery OEMs specify these with auxiliary contact blocks for interlocking safety circuits.
- Energy Generation:Solar inverters, wind turbine switchgear, and battery storage demand 1500V DC switching capability. Indian PLI scheme beneficiaries are localizing supply chains for string inverter assembly.
- HVAC Systems:Compressor and fan motor control in commercial buildings utilizes compact DIN-rail mounted contactors. Texas engineering-procurement firms mandate dual-source qualification for projects above 480V.
- Transportation Systems:Traction power and charging infrastructure requires vibration-resistant mounting and extended temperature ranges. Fleet operators in California specify sealed contactors for coastal salt exposure.
- Building Automation:Lighting control and elevator systems prioritize low coil consumption and quiet operation. Frankfurt commercial developments integrate digital contactors with building management system protocols.
Manufacturing Plants absorb the highest contactor volumes. Energy Generation is gaining share fastest.
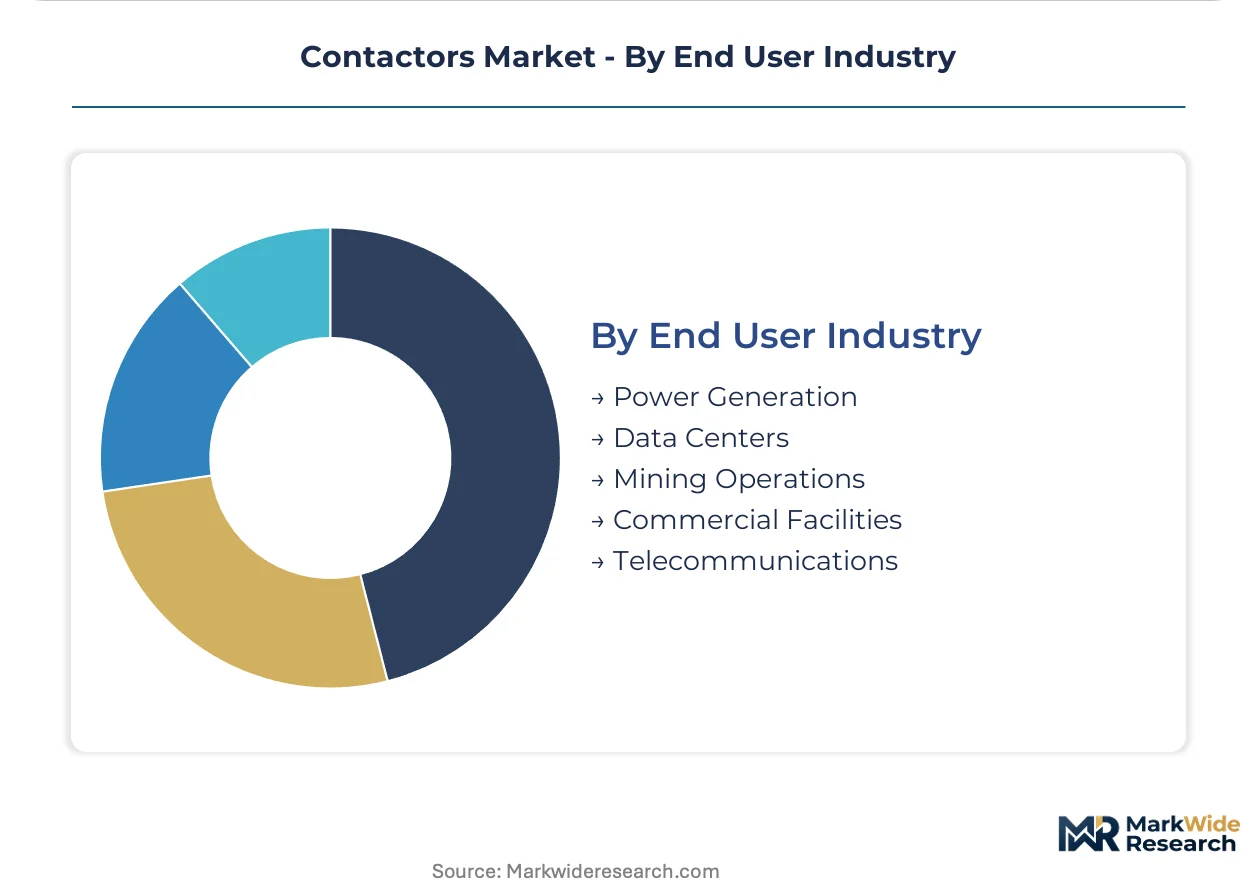
End User Industry:
End-user industry determines certification depth, with power generation and data centers imposing the most stringent traceability and testing protocols.
- Power Generation:Utility-scale solar and wind farms require contactors with documented arc endurance under IEC 60947-4-1 Annex H. Chinese state grid modernization directives are accelerating procurement of high-voltage DC switching equipment.
- Data Centers:Hyperscale facilities demand IoT-enabled contactors with embedded temperature and vibration sensors for predictive maintenance. Northern Virginia operators are piloting digital fleets with recurring service revenue attachments.
- Mining Operations:Underground and surface extraction equipment specifies flameproof enclosures and heavy-duty contact blocks. Australian iron ore producers prioritize suppliers with regional service networks.
- Commercial Facilities:Office buildings and retail centers utilize standard-duty contactors with basic overload protection. These applications face the strongest price pressure from commodity copper volatility.
- Telecommunications:Base station power systems favor solid-state and latching contactors for minimal heat generation and battery conservation. South Korean 5G rollouts specify decade-rated switching equipment.
Power Generation commands the highest unit values. Data Centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing contactor manufacturing capacity toward jurisdictions with streamlined certification pathways. IEC-UL convergence on DC switching standards has compressed compliance costs for dual-certified producers, while REACH-mandated material substitutions in Europe are elevating production expenses for cadmium-dependent contact lines.
China
State Grid Corporation's ultra-fast charging station rollout and dual carbon policy implementation are driving procurement of 1000V+ DC contactors. GB 14048 series standards mandate enhanced arc endurance for renewable integration equipment. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces are scaling silver-tin oxide contact material production to serve domestic inverter OEMs.
Germany
Industrial motor control centers in automotive manufacturing plants specify million-cycle electrical endurance ratings for continuous process lines. EU Ecodesign Directive tightening on contact wear compels arc chamber redesigns for premium product tiers. Bavarian automation suppliers are integrating predictive maintenance electronics into contactor housings for Frankfurt data center operators.
United States
FERC grid reliability standards and Texas engineering-procurement firm mandates for dual-source qualification above 480V are reshaping utility procurement patterns. EV charging infrastructure financiers require 10-year supply continuity assurances for critical switching components. Northern Virginia hyperscale data centers pilot IoT-enabled contactor fleets with embedded condition monitoring.
India
Production-linked incentive schemes for solar manufacturing are creating localized demand for 1500V DC contactors in string inverter assemblies. Central Electricity Authority regulations mandate traceability documentation for utility-scale power switching equipment. Gujarat and Tamil Nadu assembly plants are qualifying domestic suppliers to reduce import dependence from East Asian vacuum interrupter sources.
Japan
Rail electrification projects in tunnel installations specify permanent magnet-assisted contactors for reduced holding power and ventilation constraints. METI efficiency standards for industrial equipment are accelerating replacement cycles in aging steel mill motor control centers. Nagoya-area ceramic manufacturers maintain concentrated production of vacuum interrupter bottles for medium-voltage DC applications.
Contactors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state and hybrid architectures for energy transition applications. The supplier base organizes around three archetypes: diversified electrical conglomerates with captive component production, specialized contactor manufacturers with regional service networks, and semiconductor-originated firms entering solid-state switching. Competitive maneuvering concentrates on backward integration into vacuum interrupter and contact material production, alongside strategic partnerships with inverter OEMs for co-development of pre-charge circuit integration.
Among diversified electrical conglomerates, ABB, Siemens, and Schneider Electric exemplify distinct strategic positioning within the contactor value chain. ABB leverages its dual-certified manufacturing footprint across European and Asian facilities to anchor utility-scale contract awards. Siemens represents in-house production capabilities for vacuum interrupters, sustaining margin control amid raw material price fluctuations. Schneider Electric occupies a position emphasizing digital contactor portfolios with embedded sensing architectures, targeting predictive maintenance service attachments in critical infrastructure verticals.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Eaton |
| Mitsubishi Electric |
| Rockwell Automation |
| Fuji Electric |
| Omron |
| Lovato Electric |
| Others |
Pricing and Supply Chain Analysis
Test engineers with IEC 60947-4-1 DC rating certification cluster in German and Japanese testing laboratories, and this workforce concentration widens pricing spreads between premium dual-certified contactor tiers and standard AC-only product lines. Labor-cost differentials between these certification hubs and emerging Asian test facilities feed directly into tiered pricing structures that separate utility-grade from commercial-duty equipment.
Pricing Analysis
Distributor margins of 15-25% on electromechanical contactors compress to 8-12% for solid-state variants where direct OEM relationships dominate. Three-tier pricing structure across premium, standard, and economy levels separates million-cycle endurance ratings from basic motor control specifications, with IEC-UL dual certification commanding the widest spreads. Pricing pressure stems from copper price volatility in coil windings, with smaller manufacturers absorbing margin compression. Fleet operators in EV charging infrastructure prove least price-sensitive due to 10-year operational horizon requirements, while commercial HVAC contractors face acute sensitivity to spot copper movements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns for spare contactor inventories serving data center and utility maintenance windows. Manufacturing concentrates in China, Germany, and Japan, with ceramic vacuum interrupter production clustering exclusively in Japanese and European facilities. Silver-tin oxide contact materials, copper coil windings, and magnetic steel laminations constitute critical input dependencies. Single-source vulnerability in vacuum bottle supply creates extended lead time exposure for medium-voltage DC applications. Distribution runs through authorized electrical distributors with project-based stocking agreements for utility-scale contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement patterns shifting toward million-cycle endurance ratings and embedded condition monitoring that favor premium-tier suppliers over commodity producers.
For Market Incumbents: Hedge copper price exposure through long-term offtake agreements with Chilean and Peruvian mining consortiums rather than spot market exposure. Defend market position by deepening backward integration into silver-tin oxide contact material production, countering REACH-mandated cadmium substitution threats. Prioritize certification investment in IEC-UL dual-rated DC switching platforms to capture utility-scale EV charging contracts where second-source qualification requirements filter out smaller competitors. For New Entrants and Emerging Players: Solid-state thyristor-based switching platforms offer the most penetrable wedge for new competitors, with South Korean 5G base station deployments and German telecommunications shelters specifying decade-rated maintenance-free operation. Target Indian solar inverter assembly plants benefiting from PLI scheme localization mandates, where domestic supply chain gaps create white-space for 1500V DC contactor qualification. Pursue co-development partnerships with Chinese inverter OEMs for hybrid pre-charge circuit integration rather than direct competition in saturated AC motor control segments. For Investors and Strategic Acquirers: Electrical conglomerates with captive vacuum interrupter production are the most active acquirer in this space, seeking to consolidate medium-voltage DC switching capabilities. Five-to-ten year viability favors targets with established IEC-UL dual certification and silver-cadmium-free contact material portfolios. Watch for inflection in FERC grid reliability standard tightening timelines, which would accelerate replacement cycles in North American utility infrastructure and expand addressable market for premium endurance-rated products.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Materials | Captive silver-tin oxide production insulates margins from REACH-driven cadmium substitution mandates. |
| IEC-UL Dual Certification Investment | Harmonized testing protocols reduce compliance costs for utility-scale contracts across multiple jurisdictions. |
| Hybrid Contactor Co-Development | Pre-charge circuit integration partnerships with inverter OEMs lock in design-win positions for 1500V solar configurations. |
| Predictive Maintenance Service Attachment | IoT-enabled contactor fleets generate recurring revenue streams from Northern Virginia hyperscale data center operators. |
| Regional Distribution Center Expansion | Rotterdam and Singapore stocking hubs reduce lead time exposure for vacuum interrupter-dependent medium-voltage orders. |
Research Methodology
Direct dialogue with utility procurement managers, EV charging infrastructure engineering-procurement firms, contactor OEM product directors, and vacuum interrupter ceramic manufacturers grounded qualitative findings in operational realities. Secondary validation drew from FERC reliability filings, IEC 60947-4-1 testing protocol documentation, SEC 10-K disclosures from listed electrical equipment manufacturers, and Chinese State Grid procurement bulletins. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segment-level projections incorporated product type splits across AC, DC, hybrid, vacuum, and solid-state architectures alongside technology tiers from electromechanical through electronic and magnetic actuation. End-use applications spanning manufacturing plants, energy generation, HVAC systems, transportation infrastructure, and building automation fed into geographic allocation models. CAGRs derived from regression analysis against installed base replacement cycles and electrification-driven new demand formation, with copper price scenarios and certification timeline assumptions as sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IEC-UL convergence timelines, REACH material restriction phase-ins, and Chinese dual carbon policy implementation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High-Vacuum Fiber Feedthrough Flanges Market
Electrical Equipment
Consumer Electronics High Voltage Electric Capacitor Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
GCC Ceiling Fan Market
Electrical Equipment
Insulator Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Europe Electric Insulator Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
High Voltage Insulator Market