
 Fiberglass Electrical Enclosure Market | 2026-2036
Fiberglass Electrical Enclosure Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Electrical Enclosure Market Foresight
Market Context
The fiberglass electrical enclosure market is shifting between premium engineered solutions and commodity-grade alternatives as end-users weigh total cost of ownership against upfront procurement budgets. MEKCO leverages its specialized fabrication capabilities to serve harsh-environment applications where material specification trumps price. Stahlin Enclosures anchors its position through deep vertical integration in pultrusion manufacturing, controlling resin formulation and fiber orientation for consistent dielectric performance. Fibox Enclosure Systems competes on modular platform architectures that reduce engineering lead times for custom configurations.
Technical Definition and Segment Structure
A fiberglass electrical enclosure is a reinforced thermoset polymer housing manufactured through pultrusion, sheet molding compound, or hand lay-up processes, typically achieving NEMA 4X or IP66 ratings while providing galvanic isolation and UV resistance for outdoor electrical equipment protection. Wall-mounted and free-standing product types dominate current volume, though custom-built enclosures capture disproportionate margin pools in offshore wind and chemical processing applications where standard dimensions fail. The renewable energy application segment leads growth velocity as solar and battery storage deployments multiply, while power distribution maintains the largest installed base of legacy metal-to-composite conversions.
Regulatory Environment and Outlook
NEMA 250 and IEC 60529 enclosure classification standards directly shape material selection and testing protocols, with UL 50E supplemental requirements driving flame-retardant additive formulations in North American specifications. The EU Green Deal and REACH chemical regulations are pressuring manufacturers to eliminate halogenated flame retardants and validate recycled content claims for European market access. Stakeholders must monitor evolving grid interconnection codes and carbon border adjustment mechanisms that will redefine competitive positioning between regional supply bases.
Market Dynamics
NEMA 250 and IEC 60529 enclosure standards are tightening dielectric performance requirements, forcing manufacturers to reformulate resin systems and fiber architectures for outdoor electrical protection. This regulatory compression is accelerating material substitution away from legacy metal housings toward engineered thermoset composites.
Growth Catalysts
- Grid Modernization Mandates:Utilities in Germany and the United States are replacing aging metal switchgear with corrosion-resistant fiberglass housings to extend service life in coastal and industrial atmospheres.
- REACH Chemical Regulations:The EU Green Deal is phasing out halogenated flame retardants, creating certified demand for non-halogen thermoset formulations that maintain UL 50E ignition resistance.
- Offshore Wind Expansion:Turbine OEMs are specifying custom pultruded enclosures for nacelle power conversion equipment exposed to salt spray and UV degradation.
Market Restraints
- Resin Cost Volatility:Unsaturated polyester and vinyl ester feedstocks track benzene and styrene commodity cycles, compressing margin stability for enclosure fabricators.
- Pultrusion Capacity Concentration:North American and European pultrusion manufacturing clusters control critical fiber orientation and dielectric consistency capabilities.
- Stainless Steel Substitution:316-grade stainless retains preference in food-grade and pharmaceutical electrical installations where surface sanitization protocols dominate material selection.
Strategic Opportunities
- India Grid Electrification:Rural distribution infrastructure under the CEA mandates is creating volume demand for cost-optimized NEMA 3R-rated fiberglass housings.
- Battery Storage Integration:Lithium-ion grid-scale deployments require arc-flash-rated enclosures combining thermal management with dielectric isolation.
- Carbon Border Adjustment Mechanisms:EU CBAM implementation is incentivizing regional composite manufacturing with validated recycled glass fiber content.
Industry Challenges
- Pultrusion Die Engineering Talent:Specialized tool design for complex cross-sections with consistent wall thickness requires expertise concentrated among aging workforce cohorts.
- UL 50E Certification Timelines:Extended flame-spread and impact testing protocols delay product launches for North American utility specifications.
- Legacy Metal System Integration:Retrofit projects demand custom mounting patterns and cable entry configurations incompatible with standardized fiberglass platform architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Electrical Enclosure Market |
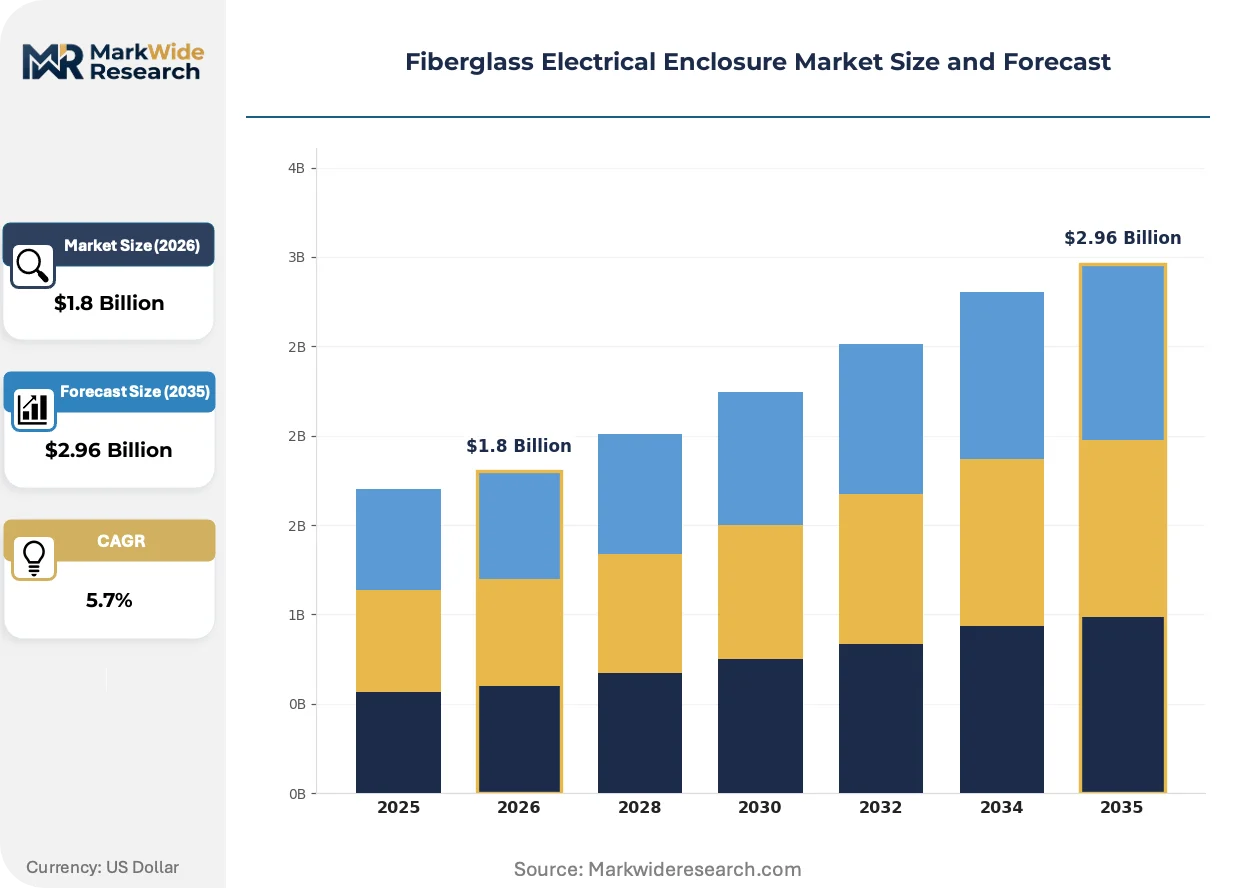
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Free-Standing, Portable, Custom-Built Application: Industrial Automation, Renewable Energy, Telecommunications, Power Distribution End User: Manufacturing, Utilities, Construction, Transportation Size: Small, Medium, Large, Extra Large |
| Companies Covered | MEKCO, nVent Hoffman, Stahlin Enclosures, Fiberglass Fabricators, Advanced Composites, Fibox Enclosure Systems, Saginaw Control and Engineering, Signature Enclosures, AttaBox Industrial Enclosures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Electrical Enclosure Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are compressing traditional enclosure design cycles. Manufacturers are integrating predictive modeling and sustainable formulations to capture specification authority before procurement finalizes.
Continuous fiber-reinforced thermoplastic tapes are converging with pultruded fiberglass architectures to create hybrid enclosures combining impact resistance with post-forming flexibility. Wind turbine OEMs in Denmark and Germany are piloting these hybrid systems for nacelle power distribution units. The convergence is compressing tooling lead times for complex geometries while maintaining NEMA 4X sealing integrity.
REACH Annex XVII restrictions on halogenated flame retardants are mandating phosphorus-nitrogen intumescent systems in European market-bound enclosures. Manufacturers serving EU grid interconnection projects must reformulate resin matrices and revalidate UL 94 V-0 ratings under revised test protocols. German utilities are accelerating qualification timelines for non-halogen alternatives to maintain project schedules.
Engineering-procurement-construction firms are consolidating vendor panels and demanding lifecycle cost documentation beyond upfront unit pricing. Solar developers in the United States are unbundling enclosure supply from turnkey installation contracts to capture direct material sourcing advantages. This behavior is most visible in Texas and California utility-scale deployments where procurement teams maintain dedicated composite specification engineers.
Fiberglass Electrical Enclosure Market Segmentation
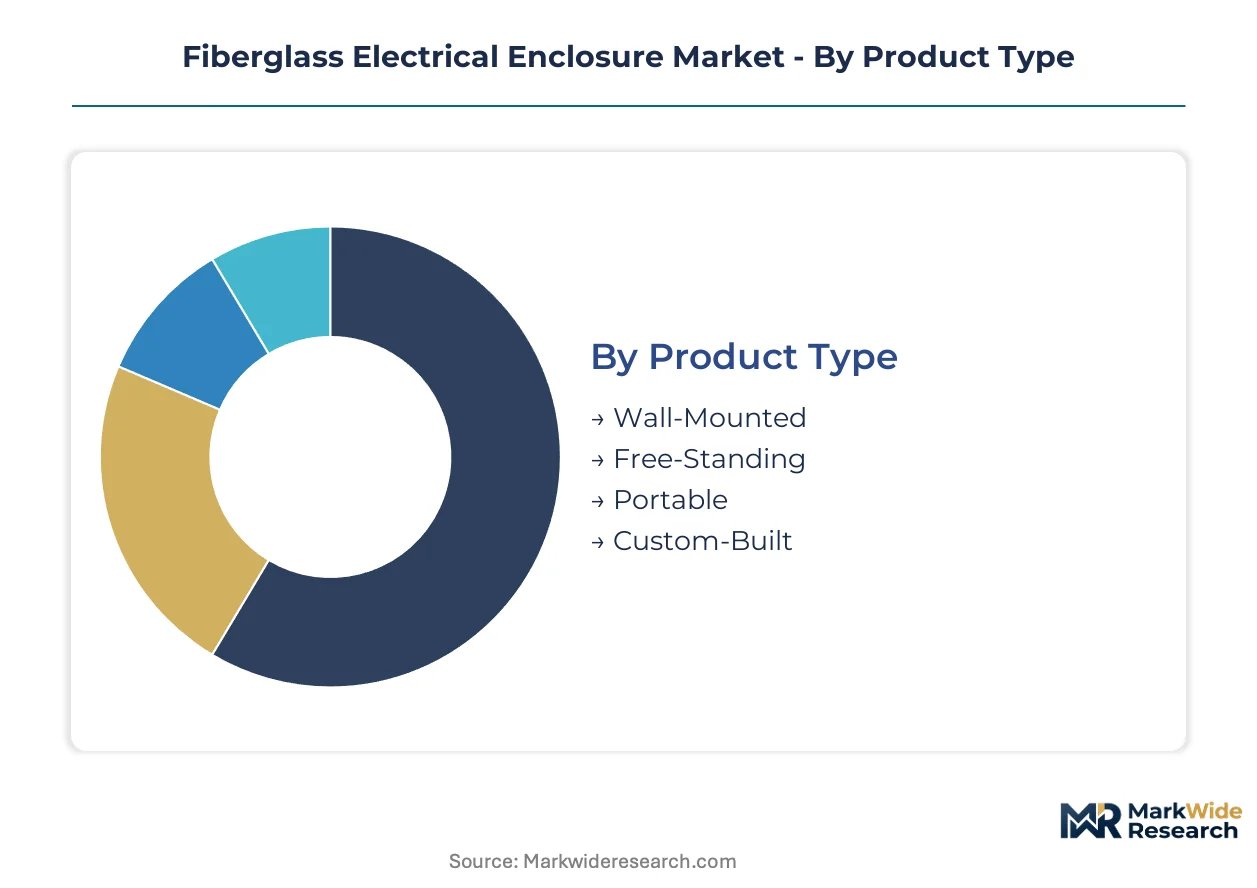
Segmentation in fiberglass electrical enclosures reveals how specification authority shifts between procurement teams and engineering departments across installation environments. Buyers prioritize corrosion resistance ratings in coastal utilities while weight and modularity dominate manufacturing automation deployments.
Product Type:
Mounting configuration determines structural reinforcement requirements and sealing complexity, directly influencing material thickness and pultrusion die engineering.
- Wall-Mounted:Compact housings with integrated mounting flanges achieve NEMA 4X ratings through continuous gasket compression. Demand concentrates in German industrial automation retrofits where floor space constraints drive specification. REACH-compliant resin formulations are displacing legacy halogenated alternatives in EU-bound shipments.
- Free-Standing:Floor-mounted cabinets with reinforced base frames accommodate heavier transformer and switchgear loads. United States utilities specify these for coastal substations exposed to salt-laden atmospheres where galvanized steel fails within seven years. UL 50E flame-spread certification extends procurement timelines for North American projects.
- Portable:Lightweight housings with lifting provisions serve temporary construction power and event infrastructure.
- Custom-Built:Engineered-to-order enclosures capture premium margins in offshore wind nacelles and chemical processing where standard dimensions fail.
Volume sits with Wall-Mounted; growth tilts toward Custom-Built.
Application:
End-use environment dictates dielectric performance thresholds and UV stabilization requirements, compressing acceptable material variance windows.
- Industrial Automation:Control panel housings with EMI shielding provisions protect PLCs and variable frequency drives in manufacturing floors. China’s smart factory investments under MIIT guidelines are standardizing IP66-rated composite enclosures over painted steel. Vibration resistance specifications are tightening for robotic workcell integrations.
- Renewable Energy:Inverter and battery storage housings combine arc-flash containment with thermal management. Solar developers in Texas and California are unbundling enclosure supply from EPC contracts to capture direct sourcing advantages. NEMA 250 revision cycles are accelerating qualification timelines for utility-scale deployments.
- Telecommunications:Small cell and fiber distribution cabinets require RF-transparent formulations and padlock security features.
- Power Distribution:Switchgear housings maintain the largest installed base of metal-to-composite conversions in legacy grid infrastructure.
Revenue concentrates in Power Distribution; expansion accelerates fastest in Renewable Energy.
End User:
Procurement sophistication varies sharply between centralized utility buyers and fragmented construction contractors, reshaping channel configuration.
- Manufacturing:Automotive and electronics producers specify color-matched enclosures with integrated cable management for cleanroom and production line environments. German OEMs are mandating recycled glass fiber content validation under EU Green Deal procurement guidelines. Total cost of ownership calculations now span fifteen-year depreciation horizons.
- Utilities:Grid operators in the United States and Germany drive standardization through NEMA 250 and IEC 60529 compliance mandates. FERC interconnection rules and CEA technical standards in India are creating divergent certification requirements for multinational suppliers. Coastal corrosion failures are accelerating replacement cycles beyond original depreciation schedules.
- Construction:Temporary power and permanent infrastructure projects demand cost-optimized NEMA 3R-rated housings with rapid availability.
- Transportation:Rail signaling and EV charging infrastructure specify impact-resistant formulations for vandalism-prone installations.
Procurement scale favors Utilities; specification velocity runs highest in Manufacturing.
Size:
Dimensional tiering correlates with manufacturing process selection—pultrusion dominates small-to-medium volumes while hand lay-up and SMC compression serve larger formats.
- Small:Junction boxes and terminal enclosures under 0.1 cubic meters leverage continuous pultrusion for cost efficiency. Electronics OEMs in Japan specify JIS-compliant compact housings for control cabinet density optimization. Miniaturization trends in industrial IoT are compressing internal component clearances.
- Medium:Distribution panel housings between 0.1 and 1.0 cubic meters balance modularity with structural load capacity. Chinese solar inverter manufacturers are standardizing medium-format platforms across 50-250 kW product lines. Modular platform architectures reduce engineering lead times for custom configurations.
- Large:Primary switchgear and transformer housings exceed 1.0 cubic meters, requiring segmented construction and field assembly.
- Extra Large:Custom-engineered enclosures for offshore substations and data center power modules demand specialized logistics and installation protocols.
Production volume centers on Medium; engineering complexity peaks in Extra Large.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American demand for corrosion-resistant electrical housings, with Gulf Coast petrochemical clusters and offshore wind staging ports driving specification volumes for NEMA 4X-rated fiberglass enclosures.
United States
Texas and California utility-scale solar deployments require arc-flash-rated enclosures for battery storage integration. FERC interconnection rules mandate dielectric performance validation for grid-tied equipment. Houston-Galveston petrochemical corridors specify pultruded housings for salt-laden coastal atmospheres where galvanized steel fails prematurely.
Germany
Offshore wind nacelle manufacturers in Bremerhaven and Cuxhaven demand custom-engineered enclosures for power conversion equipment. EU Green Deal procurement guidelines enforce recycled glass fiber content validation. Bavarian industrial automation clusters specify REACH-compliant resin formulations for control panel retrofits.
China
MIIT smart factory investments standardize IP66-rated composite enclosures over painted steel for robotic workcell integration. Yangtze River Delta solar inverter manufacturers consolidate medium-format platform specifications across 50-250 kW product lines. Qingdao and Tianjin port zones accelerate metal-to-composite conversions in coastal substations.
India
Rural distribution infrastructure under CEA technical standards creates volume demand for cost-optimized NEMA 3R-rated housings. Gujarat and Maharashtra industrial corridors specify fiberglass switchgear for chemical processing environments. Tamil Nadu renewable energy zones drive qualification timelines for utility-scale solar enclosure deployments.
Fiberglass Electrical Enclosure Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specification and certification complexity, with specialized fabricators capturing disproportionate returns in offshore wind and chemical processing applications. The vendor base stratifies between integrated pultrusion operators controlling resin formulation and fiber orientation, modular platform architects reducing engineering lead times, and regional job shops serving cost-optimized infrastructure tenders. Three archetypes dominate: vertically integrated compounders, application-specific engineers, and scale-driven commodity suppliers. Competitive moves concentrate on backward integration into resin systems and strategic partnerships with turbine OEMs for nacelle specification authority.
Within the application-engineering tier, MEKCO and Stahlin Enclosures exemplify specialized fabrication capabilities for harsh-environment installations where material specification outweighs upfront procurement budgets. Fibox Enclosure Systems occupies a position among modular platform architects serving manufacturing automation retrofits with reduced configuration lead times. These three anchors represent distinct competitive vectors: custom-engineered solutions, vertical integration in pultrusion manufacturing, and standardized modular architectures.
| Leading Market Players |
|---|
| MEKCO |
| nVent Hoffman |
| Stahlin Enclosures |
| Fiberglass Fabricators |
| Advanced Composites |
| Fibox Enclosure Systems |
| Saginaw Control and Engineering |
| Signature Enclosures |
| AttaBox Industrial Enclosures |
| Others |
Supply & Pricing Matrix
Pultrusion die engineering talent concentrated in Michigan and Ohio establishes labor-cost differentials that widen pricing-tier spreads between custom-engineered and commodity-grade fiberglass enclosures. These specialized tool designers command premium wages that manufacturers pass through to buyers specifying complex cross-sections with tight dielectric tolerances.
Pricing Analysis
Performance-based pricing anchored to field failure rates and extended service life separates premium pultruded enclosures from standard alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade—UL 50E flame-spread ratings versus basic NEMA 3R compliance—and customization depth. Price differentiation stems from resin formulation complexity and fiber orientation control. Cost compression in economy tiers is intensifying because Chinese manufacturers are scaling medium-format platform production for solar inverter applications. Solar developers in Texas exhibit highest price sensitivity; offshore wind turbine OEMs prioritize material specification over unit cost.
Supply Chain Analysis
UL 50E and REACH compliance certification gates restrict supply base participation to manufacturers with validated flame-retardant formulation capabilities and third-party testing relationships. Manufacturing concentrates in the United States, Germany, and China, each serving distinct regulatory clusters. Raw material dependencies center on unsaturated polyester resin, vinyl ester feedstocks, and continuous glass fiber roving. Supply chain risk manifests as single-source vulnerability for specialized phosphorus-nitrogen intumescent additives under REACH Annex XVII restrictions. Distribution runs through electrical wholesale distributors and direct EPC contractor relationships for utility-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as REACH chemical regulations and extended UL certification timelines force capital-constrained regional fabricators toward exit or acquisition. Regulatory compliance burdens favor scaled operators with dedicated certification engineering staff.
For Market Incumbents: Cement specification authority in offshore wind nacelle applications through captive pultrusion capacity and turbine OEM partnership structures. Deepen backward integration into non-halogen flame-retardant resin systems to secure supply continuity under REACH pressure. Acquire distressed regional job shops in India and Southeast Asia to capture CEA-mandated rural electrification volume before local competitors consolidate.
For New Entrants and Emerging Players: EU Green Deal procurement guidelines in Germany open a window for recycled glass fiber content validation services and carbon footprint auditing tools. Target battery storage integration projects in California and Texas where arc-flash-rated enclosure demand outstocks established supply. Pursue direct EPC contractor relationships rather than distributor channels to bypass incumbent wholesale lock-in.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated compounders controlling resin formulation and fiber orientation given EU CBAM implementation and carbon border adjustment mechanisms. Five-to-ten-year viability favors operators with validated recycled content supply chains and multi-regional certification portfolios. The signal to watch is qualification timeline compression for non-halogen alternatives as German utilities accelerate project schedules.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Systems | Captive supply of REACH-compliant formulations insulates margin from benzene-styrene commodity cycles. |
| Joint Venture with Turbine OEM | Nacelle specification authority locks in multi-year offtake for custom pultruded enclosures in Bremerhaven cluster. |
| Green Certification Program | Validated recycled glass fiber content secures EU Green Deal procurement preference in Bavarian automation retrofits. |
| Capacity Expansion in India | Local pultrusion footprint captures CEA-mandated rural distribution infrastructure under cost-optimized NEMA 3R specifications. |
| Long-term Supply Agreement | Contracted resin volumes stabilize input costs for solar inverter manufacturers in Yangtze River Delta. |
Research Methodology
Multi-period observation of NEMA 250 revision cycles, REACH regulatory amendments, and metal-to-composite conversion rates anchored the trend analysis, supplemented by interviews with pultrusion plant managers, utility procurement officers, EPC contractor specification engineers, and resin system technical directors. Secondary validation drew from FERC interconnection filings, ECHA restriction proposals, MIIT smart factory investment disclosures, and customs trade data for fiberglass electrical enclosure imports. Bottom-up project pipeline analysis triangulated against top-down utility capital expenditure forecasts.
Segment-weighting across product type, application, end user, and size dimensions informed volume and value outputs across the projection horizon. Mounting configuration, dielectric performance tier, and regional regulatory cluster served as primary stratification variables. CAGRs were derived from installed base replacement velocity and new-build penetration assumptions. Forecast inputs included resin feedstock price indices, UL certification backlog durations, and offshore wind turbine deployment schedules.
The model assumes a particular technology adoption path; alternative pathways for continuous fiber-reinforced thermoplastic hybrid enclosures would alter the outlook if wind turbine OEMs accelerate qualification beyond current pilot phases. Forecasts reflect assumptions regarding REACH enforcement consistency and FERC interconnection rule stability. A model refresh is warranted upon material change in EU CBAM implementation scope or benzene-styrene feedstock supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
United States Frequency Converter Market
Electrical Equipment
Asia-Pacific Vacuum Circuit Breakers Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
DC Contactor Market
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
United States Busbar Market
Electrical Equipment
Motor Protection Devices Market
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
Passover Humidifiers Market
Electrical Equipment
Global EMC Filtration Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
North America Circuit Breakers Market