
 Porcelain Insulators Market | 2026-2036
Porcelain Insulators Market Size, Share, and Industry Trends Forecast 2026-2036
Porcelain Insulators Market Intelligence
High-voltage testing and certification services are rewriting the margin structure for incumbent manufacturers, shifting value from pure product sales. Siemens AG leverages its integrated grid technology portfolio to bundle insulators within broader substation automation and control system projects. NGK Insulators sustains its premium position through proprietary advancements in ceramic material science and ultra-high-purity production. Hubbell Incorporated competes effectively through its vast distribution network and a comprehensive catalog serving utility and industrial end-users.
A porcelain insulator is a vitrified ceramic component engineered to electrically isolate conductors from their physical supports, such as towers and poles. Composed of materials like clay, quartz, and feldspar fired at high temperatures, it achieves high dielectric strength and superior mechanical resistance to environmental stress. Suspension insulators, critical for high-voltage transmission lines, represent the dominant product type due to grid expansion projects. Pin insulators and transformer insulators serve vital roles in medium-voltage distribution networks and power substations, respectively.
Performance and safety benchmarks are set by global standards from the International Electrotechnical Commission (IEC), which influence design and testing protocols worldwide. In key national markets, specific regulations like China's GB standards and India's Bureau of Indian Standards (BIS) certification are mandatory for market access. These frameworks enforce stringent quality control and material specifications. The key strategic decision for manufacturers involves managing investments in porcelain capacity against the rising adoption of composite and glass insulator alternatives.
Market Dynamics
The market's core dynamic is the immense demand from utility-led grid expansion, particularly in India, clashing with the persistent material science advancements of composite and glass insulator alternatives. This challenges porcelain's long-held dominance in high-voltage applications, creating a competitive tension between cost-effective incumbency and performance-driven substitution.
Growth Catalysts
- Grid Modernization Programs:Investments in smart grid technologies and substation automation by utilities in developed economies necessitate higher-performance insulators to ensure grid reliability and support bidirectional power flow.
- National Electrification Policies:Government-led initiatives, such as India's extensive grid expansion projects under its national frameworks, create sustained, large-volume demand for transmission and distribution insulators to improve electricity access.
- Ultra-High-Voltage (UHV) Lines:The construction of UHV DC and AC transmission corridors, especially in China, requires insulators with superior mechanical strength and dielectric properties, favoring advanced porcelain designs.
Market Restraints
- Substitution by Composite Insulators:The adoption of polymer and composite insulators presents a significant threat, as they offer advantages in weight, resistance to vandalism, and performance in high-pollution areas.
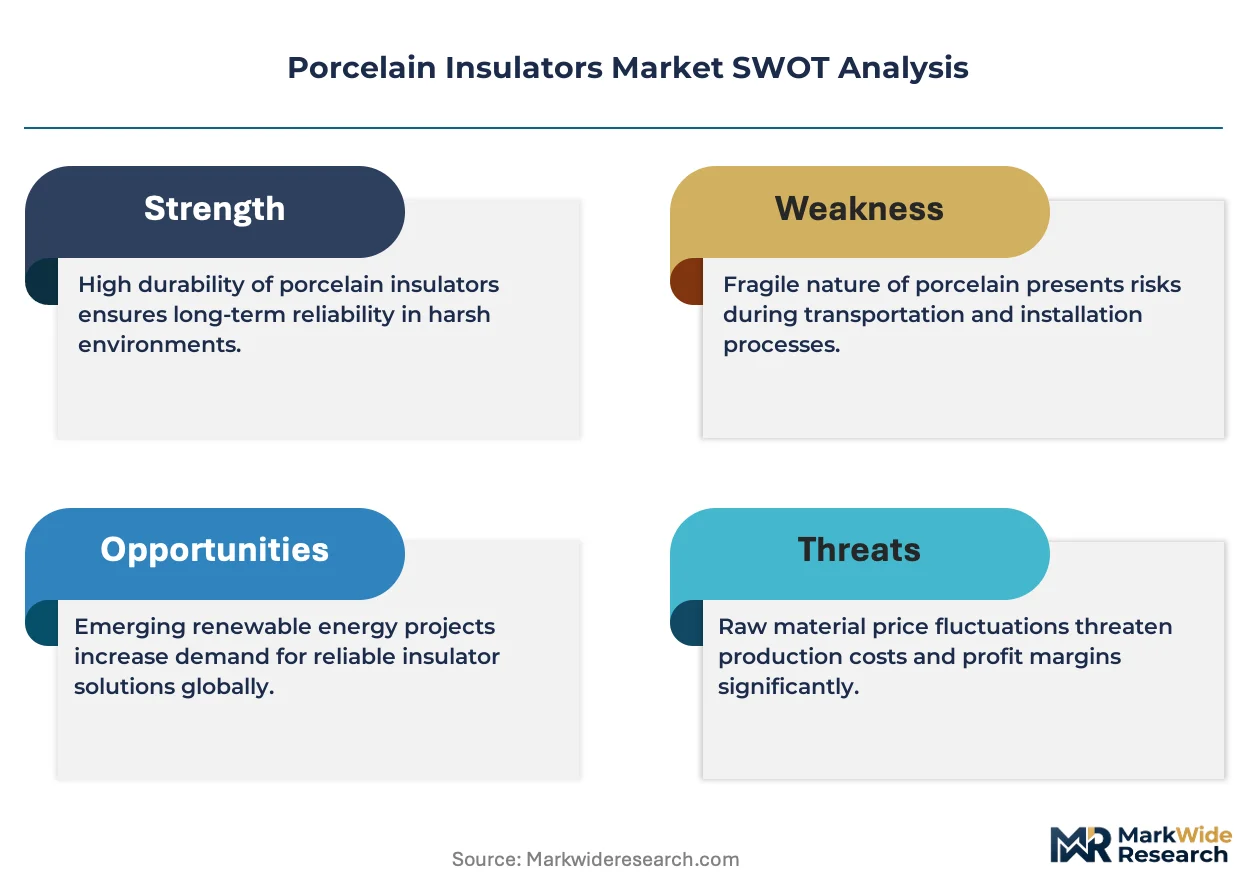
- Raw Material Price Volatility:Manufacturer margins are exposed to price fluctuations in key mineral inputs like high-purity quartz, clay, and feldspar, which are influenced by mining and logistics costs.
- High Transportation and Handling Costs:The inherent weight and fragility of porcelain insulators increase logistical expenses and the risk of damage during transport and installation compared to lighter alternatives.
Strategic Opportunities
- Specialized Anti-Pollution Designs:There is an opportunity to develop and market insulators with advanced glaze formulations optimized for severe environmental conditions, such as coastal salt spray or industrial pollutants.
- Railway Electrification Sector:Expanding railway networks, particularly in India and parts of Europe, offer a dedicated, high-volume application segment for specialized traction and catenary line insulators.
- Hybrid Insulator Development:Combining porcelain's compressive strength and rigidity with the hydrophobic surface properties of silicone rubber creates hybrid products that capture benefits from both material classes.
Industry Challenges
- Lengthy Certification Cycles:The time and expense required to secure mandatory certifications, such as those from the Bureau of Indian Standards (BIS), can create significant delays for market entry and product introductions.
- Energy-Intensive Production:The high-temperature firing process in kilns makes manufacturers vulnerable to volatile natural gas and electricity prices, as well as emerging carbon taxation or emissions regulations.
- Scarcity of Specialized Expertise:A shortage of skilled ceramic engineers and technicians with experience in high-voltage testing protocols can constrain production quality and new product development efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Porcelain Insulators Market |
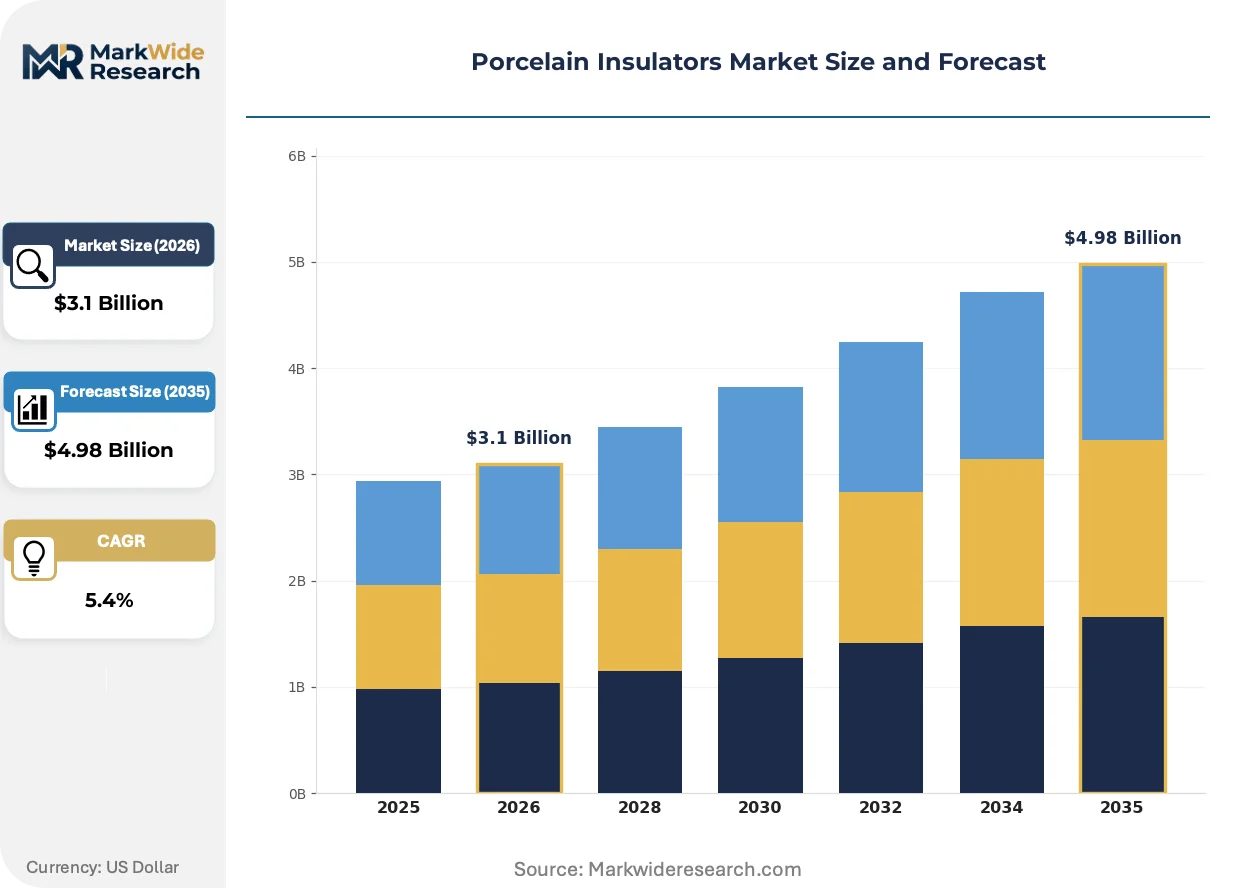
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pin Insulators, Suspension Insulators, Shackle Insulators, Transformer Insulators Application: Transmission Lines, Distribution Lines, Power Plants, Substations End User: Utilities, Industrial, Commercial, Residential Technology: High Voltage, Medium Voltage, Low Voltage, Smart Grid |
| Companies Covered | Hubbell Incorporated, MacLean Power Systems, NGK Insulators, Bharat Heavy Electricals Limited, PPC Insulators, Lapp Insulators, ABB Ltd., Dalian Insulator Group, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Porcelain Insulators Market Strategic Shifts & Innovations
Product evolution is driven by the dual requirements of supporting ultra-high-voltage transmission and withstanding severe environmental conditions. This pressure forces innovation in material composition and surface treatments to defend porcelain's position against the performance gains of alternative materials like composites and glass.
Advanced hydrophobic glazes and coatings are applied to porcelain insulators to improve performance in high-pollution and coastal areas. Utilities are specifying these for new transmission lines and critical replacement cycles to reduce flashover incidents. This technology is rendering obsolete standard, untreated porcelain insulators in applications where maintenance access is difficult and reliability is paramount.
The International Electrotechnical Commission's IEC 60815 standard guides the selection of insulators for polluted environments. It compels utilities to adopt a more scientific approach to specification, linking insulator choice directly to site-specific pollution severity. Suspension insulators for coastal or industrial transmission corridors are most affected, requiring higher creepage distances or specialized materials.
A preference for turnkey project execution is altering purchasing behavior away from individual component procurement. System integrators and EPC contractors are increasingly sourcing insulators as part of a bundled substation or transmission line package. This shift is most prominent in new grid infrastructure projects across Southeast Asia and the Middle East, disrupting traditional component sales channels.
Porcelain Insulators Market Segmentation
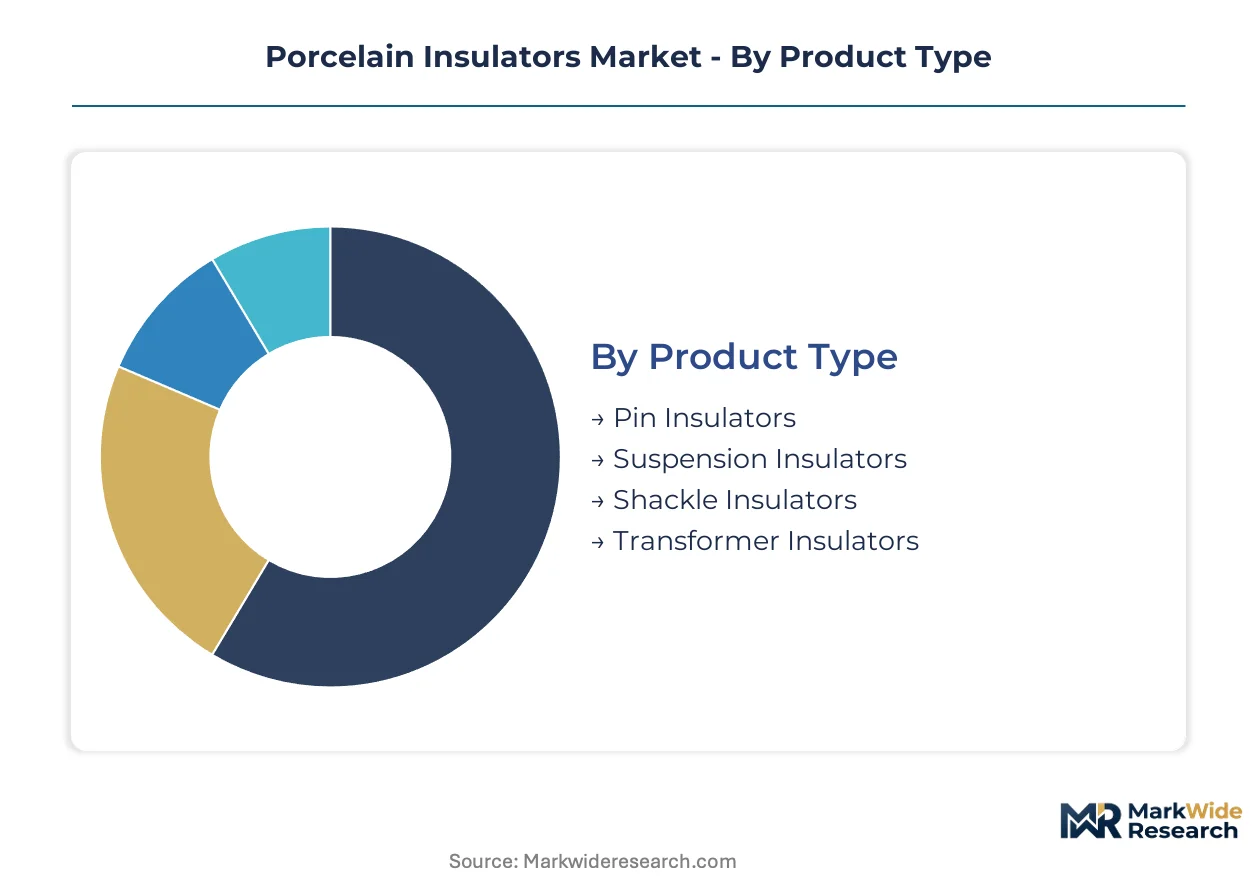
Understanding market segmentation for porcelain insulators illuminates distinct demand patterns and technological requirements across various grid infrastructure components. This granular view enables manufacturers to align product development and market strategies with specific end-user needs and application complexities, optimizing resource allocation.
Product Type:
The maturity spectrum within porcelain insulator product types reveals established designs alongside specialized components addressing evolving grid demands.
- Suspension Insulators:Essential for high-voltage transmission lines, these components support conductors from towers, enduring significant mechanical and electrical stress. Demand concentrates in India due to extensive national grid expansion projects.
- Transformer Insulators:Designed for electrical isolation within power transformers, these insulators manage high internal voltages and thermal loads. Their specification is critical for substation reliability and efficiency in developed economies.
- Pin Insulators:These robust insulators are commonly used for medium-voltage distribution lines, securing conductors to utility poles.
- Shackle Insulators:Employed for low-voltage distribution and service connections, shackle insulators provide insulation at sharp turns or dead-end points.
Suspension Insulators retain volume leadership; Transformer Insulators hold the steepest expansion curve.
Application:
Application-based segmentation highlights where the largest volumes of porcelain insulators are deployed, reflecting critical infrastructure needs.
- Transmission Lines:These applications involve long-distance, high-voltage power transfer, requiring insulators with superior mechanical strength and dielectric properties. Investments in upgrading and expanding transmission lines, particularly in China, drive significant demand.
- Substations:Porcelain insulators are integral to substations, providing insulation for switchgear, transformers, and busbars to ensure safe and reliable power distribution. Modernization of substation infrastructure in Europe demands advanced insulator designs.
- Distribution Lines:Insulators for distribution lines manage medium and low voltages, connecting substations to end-users over shorter distances.
- Power Plants:Within power generation facilities, insulators isolate high-voltage equipment, ensuring operational safety and efficiency.
Utilities prioritize insulator reliability across Transmission Lines and Substations to maintain grid stability.
End User:
End-user segmentation differentiates demand based on the operational scale and specific requirements of various electricity consumers.
- Utilities:National and regional utility companies represent the primary end-users, procuring insulators for vast transmission and distribution networks. Grid modernization programs in the United States necessitate high-performance insulators for these operators.
- Industrial:Industrial facilities with high power consumption, such as manufacturing plants and heavy industries, require specialized insulators for their internal power distribution and machinery. Their demand is driven by expansion in industrial zones across Southeast Asia.
- Commercial:Commercial establishments, including large offices and retail centers, utilize porcelain insulators in their building's electrical infrastructure.
- Residential:Residential applications involve lower voltage insulators for household power connections and local distribution.
Utilities dictate insulator specifications, while Industrial users present a growing niche for robust solutions.
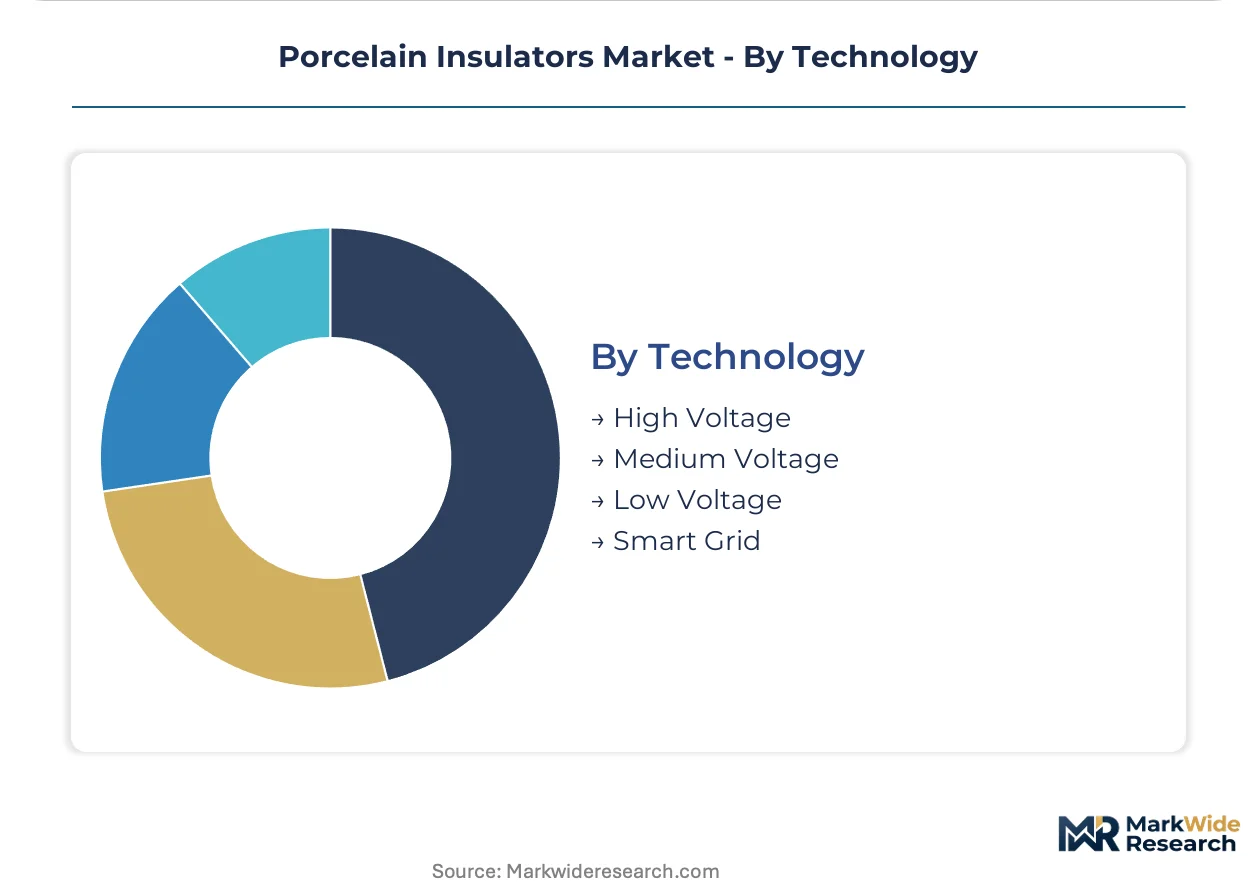
Technology:
Technology segmentation reflects the varying electrical demands and functional complexity across different voltage levels and grid intelligence.
- High Voltage:This segment covers insulators designed for transmission lines operating at 100 kV and above, demanding exceptional dielectric strength and mechanical integrity. The construction of UHV lines in China drives advanced porcelain insulator development.
- Smart Grid:Insulators for smart grid applications must integrate with advanced monitoring systems and support bidirectional power flow, requiring enhanced reliability and performance. Investments in smart grid infrastructure by European utilities stimulate demand.
- Medium Voltage:Medium voltage insulators are employed in distribution networks, typically ranging from 1 kV to 69 kV, facilitating local power delivery.
- Low Voltage:This segment includes insulators for applications below 1 kV, primarily serving residential and commercial connections.
Innovation is concentrated in Smart Grid and High Voltage technologies to meet future energy demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for porcelain insulators contrasts sharply across global markets. Cost-sensitive buyers in developing economies prioritize volume and affordability for basic grid expansion. Developed regions, conversely, emphasize performance and reliability, integrating insulators into advanced smart grid systems.
India
India's porcelain insulator demand is fueled by extensive national grid expansion projects aimed at improving electricity access. The Bureau of Indian Standards (BIS) certification is mandatory for all market access, ensuring quality and material specifications. New infrastructure development in states like Maharashtra drives significant demand for transmission and distribution insulators.
China
China's construction of Ultra-High-Voltage (UHV) DC and AC transmission corridors drives demand for advanced porcelain insulators. GB standards influence all design and testing protocols within the country, enforcing stringent quality control. The Yangtze River Delta region, with its dense industrial activity, requires robust substation and transmission components.
United States
Utility investments in upgrading and expanding transmission lines necessitate high-performance insulators across the United States. Federal Energy Regulatory Commission (FERC) guidelines shape grid reliability requirements, influencing insulator specifications. Grid modernization efforts in California demand advanced insulator designs for renewable energy integration and wildfire mitigation.
Germany
Substation modernization initiatives and smart grid infrastructure development drive porcelain insulator demand in Germany. The EU Green Deal influences specifications for sustainable and efficient grid components, promoting advanced material use. Industrial hubs like North Rhine-Westphalia require reliable insulators for complex power distribution networks and industrial applications.
Porcelain Insulators Market Key Industry Players
Capability concentration sits with specialized material science players, while scale advantage sits with large, diversified industrial conglomerates. The market exhibits a tiered structure, with a few global leaders and numerous regional specialists. Strategic archetypes include integrated solution providers and niche high-performance material innovators. Companies increasingly engage in bundling products with broader grid technology offerings and expanding distribution networks.
On the premium-tier vector, NGK Insulators exemplifies the archetype of a specialized material science innovator, leveraging proprietary advancements in ceramic material science and ultra-high-purity production. Siemens AG occupies the position of an integrated grid technology provider, bundling insulators within broader substation automation and control system projects, showcasing a strategy of offering comprehensive solutions. Hubbell Incorporated anchors the market through its vast distribution network, representing a comprehensive catalog provider serving diverse utility and industrial end-users across various voltage applications, ensuring broad market penetration.
| Leading Market Players |
|---|
| Hubbell Incorporated |
| MacLean Power Systems |
| NGK Insulators |
| Bharat Heavy Electricals Limited |
| PPC Insulators |
| Lapp Insulators |
| ABB Ltd. |
| Dalian Insulator Group |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Raw material price volatility for high-purity quartz and feldspar determines both porcelain insulator pricing tier spreads and supply chain shape. This cost pressure influences manufacturer margins and global sourcing decisions for key inputs.
Pricing Analysis
High-voltage testing and certification services drive significant lifetime value for porcelain insulator manufacturers. The dominant pricing model is project-based, often bundled within broader substation or transmission line packages. Price differentiation stems from rigorous certification levels, such as BIS standards, and specialized designs for severe environmental conditions, though margin pressure intensifies due to energy-intensive production and composite alternatives. Cost-sensitive buyers in India prioritize affordability, while developed economies emphasize performance.
Supply Chain Analysis
Stringent national quality controls, such as China's GB standards and India's BIS certification, limit market access and influence supply chain flows. Global production concentrates in countries like China, India, and Japan, which possess specialized manufacturing capabilities. The supply chain draws from high-purity quartz, clay, and feldspar, exposing manufacturers to raw material price volatility and high transportation costs for fragile products. Distribution increasingly runs through system integrators and EPC contractors for turnkey grid infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The porcelain insulators market sits at a platform-economics inflection, driven by the shift towards integrated grid technology portfolios and turnkey project execution. This transition reshapes how components are sourced and deployed within broader substation and transmission line ecosystems.
For Market Incumbents: Insulate core product lines against substitution by composite and glass insulator alternatives through continuous R&D in ceramic material science. Incumbents should invest in advanced glaze formulations optimized for severe environmental conditions, securing premium positions. Deepen vertical integration into high-purity raw material sourcing to mitigate price volatility. Furthermore, leverage existing distribution networks and comprehensive catalogs to bundle insulators within broader grid technology offerings, as Siemens AG does.
For New Entrants and Emerging Players: Pursue niche applications with high barriers to entry, leveraging specialized material science expertise. The railway electrification sector in India and Europe presents a dedicated, high-volume segment for specialized traction insulators. Focus on developing hybrid insulator products, combining porcelain's compressive strength with silicone rubber's hydrophobic surface properties for performance in polluted environments. Target medium-voltage distribution networks in industrial zones across Southeast Asia with robust, application-specific solutions.
For Investors and Strategic Acquirers: The market sits at a modernization and expansion phase that favors integrated solution providers and niche technology innovators. Long-term grid infrastructure investments, particularly in UHV and smart grid technologies, ensure sustained demand over the next decade. Acquisition targets include specialized material science players with proprietary ceramic advancements or regional manufacturers with strong BIS or GB certification advantages. The signal to watch is the adoption rate of hybrid insulator solutions in critical infrastructure projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Glaze Formulations | Improves insulator performance in severe pollution, reducing flashover incidents for utilities. |
| Develop Hybrid Insulator Products | Combines porcelain's strength with silicone's hydrophobic properties, capturing benefits from both material classes. |
| Expand Turnkey Project Capabilities | Aligns with utility purchasing behavior shifting towards bundled substation and transmission line packages. |
| Secure High-Purity Raw Material Contracts | Mitigates manufacturer exposure to raw material price volatility in key mineral inputs like quartz. |
| Pursue Railway Electrification Opportunities | Taps into a high-volume application segment for specialized traction and catenary line insulators in India. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a comprehensive market perspective. Primary interviews with utility planning officers, EPC contractors, substation engineers, and ceramic R&D specialists provided critical insights. This was validated through secondary research, leveraging IEC standards, national grid expansion reports, mineral input market analyses, and company filings. A robust bottom-up and top-down triangulation approach ensured data accuracy.
Quantitative models were calibrated using historical market data and future infrastructure development plans. The analytical framework segmented the market by product type, application, end user, technology, and regional infrastructure spending. Compound annual growth rates were projected based on these calibrated models and industry growth trajectories. Key forecast inputs included utility investment cycles and UHV transmission line construction schedules.
Sensitivities concentrate around raw material price volatility, evolving regulatory frameworks, and the adoption rate of composite insulators. Forecasts reflect assumptions regarding utility investment stability and grid modernization timelines. Material shifts in global energy policy or grid technology adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Busbar Trunking Market
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
Global Medium Voltage Surge Arresters Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
Terminal Block Market
Electrical Equipment
Asia-Pacific Circuit Breakers Market
Electrical Equipment
Insulator Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
Low Voltage Motor Control Centers Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
Waveguide Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
Ground Fault Circuit Interrupter Market