
 Global General Purpose Contactor Market | 2026-2036
Global General Purpose Contactor Market Size, Share, and Industry Trends Forecast 2026-2036
Global General Purpose Contactor Market Analysis
EU Ecodesign Directive revisions are consolidating the cost-of-entry calculus for general purpose contactor manufacturers serving European industrial clients. Schneider Electric leverages its deep channel presence in IEC-standard markets to sustain pricing power across premium electromagnetic lines. Siemens anchors its position through captive semiconductor supply for solid state contactor modules. ABB competes on system integration, bundling contactors with variable frequency drives to control project specification.
A general purpose contactor is an electrically operated switch designed to make and break power circuits carrying currents typically from 9 A to over 2000 A, using an electromagnetic coil to actuate main contacts with specified AC-3 or AC-4 utilization categories. Its primary purpose is reliable motor control and power distribution in repetitive switching cycles across industrial environments. Electromagnetic contactors still occupy the largest volume share due to their cost structure and field-service familiarity, though solid state variants are capturing the fastest growth in precision HVAC and semiconductor fabrication applications where arcless switching reduces maintenance. Smart contactors integrating IoT-enabled thermal monitoring and predictive diagnostics are pulling margin pools upward as end-users shift from replacement cycles to condition-based asset management.
The US National Electrical Code administered by NFPA shapes contactor enclosure ratings and fault-current withstand requirements across North American installations. China's GB standards and NMPA-adjacent quality certifications enforce dielectric testing and mechanical endurance benchmarks for domestic and export-bound production. IEC 60947-4-1 harmonization through European notified bodies streamlines cross-border market access but raises compliance documentation burdens for smaller manufacturers. Stakeholders must decide whether to absorb certification costs for multi-standard portfolios or specialize in single-regulation dominance as regulatory fragmentation between efficiency mandates and digital interoperability requirements intensifies.
Market Dynamics
Electromagnetic contactor manufacturers face intensifying pressure from the EU Ecodesign Directive's phase-out mandates, which force coil redesigns while solid-state alternatives capture precision switching applications in semiconductor fabrication and HVAC systems.
Growth Catalysts
- Industrial Electrification:Automotive assembly plants across Germany and China are accelerating IEC-rated contactor procurement for automated production lines. Motor control contactor demand concentrates in China's eastern manufacturing corridor where smart factory investments require millions of units annually.
- IoT-Enabled Thermal Monitoring:Smart contactors integrating predictive diagnostics are pulling margin pools upward as end-users shift from replacement cycles to condition-based asset management in critical infrastructure applications.
- REACH and RoHS Compliance:European environmental regulations are consolidating cost-of-entry calculus for manufacturers serving industrial clients, favoring suppliers with established multi-standard certification portfolios.
Market Restraints
- Copper and Silver Contact Material Volatility:Input cost swings for precious metal contact alloys compress gross margins for electromagnetic contactor producers during commodity price spikes.
- Semiconductor Supply Concentration:Solid-state contactor module production depends on captive silicon carbide and IGBT supply chains concentrated in East Asian foundries, creating vulnerability for Western OEMs.
- AC-4 Utilization Category Limitations:Electromechanical contactors face switching frequency ceilings in high-cycle applications, ceding ground to solid-state alternatives in repetitive motor starting scenarios.
Strategic Opportunities
- Underpenetrated Indian Manufacturing Base:India's PLI scheme for industrial automation creates procurement windows for contactor suppliers as domestic motor control component production scales.
- Convergence of VFD-Contactor Systems:Bundling variable frequency drives with contactor assemblies enables specification control in process industries seeking integrated motor control solutions.
- Digital Interoperability Mandates:IEC 61850 and related industrial communication standards in European smart grid deployments open specification channels for contactors with embedded networking capabilities.
Industry Challenges
- Multi-Standard Certification Burden:Smaller manufacturers struggle with documentation requirements for simultaneous IEC 60947-4-1, UL 508, and GB standard compliance, forcing portfolio specialization decisions.
- Legacy System Integration Friction:Smart contactor deployment in brownfield industrial sites requires protocol bridging with existing SCADA architectures, extending commissioning timelines and technical support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global General Purpose Contactor Market |
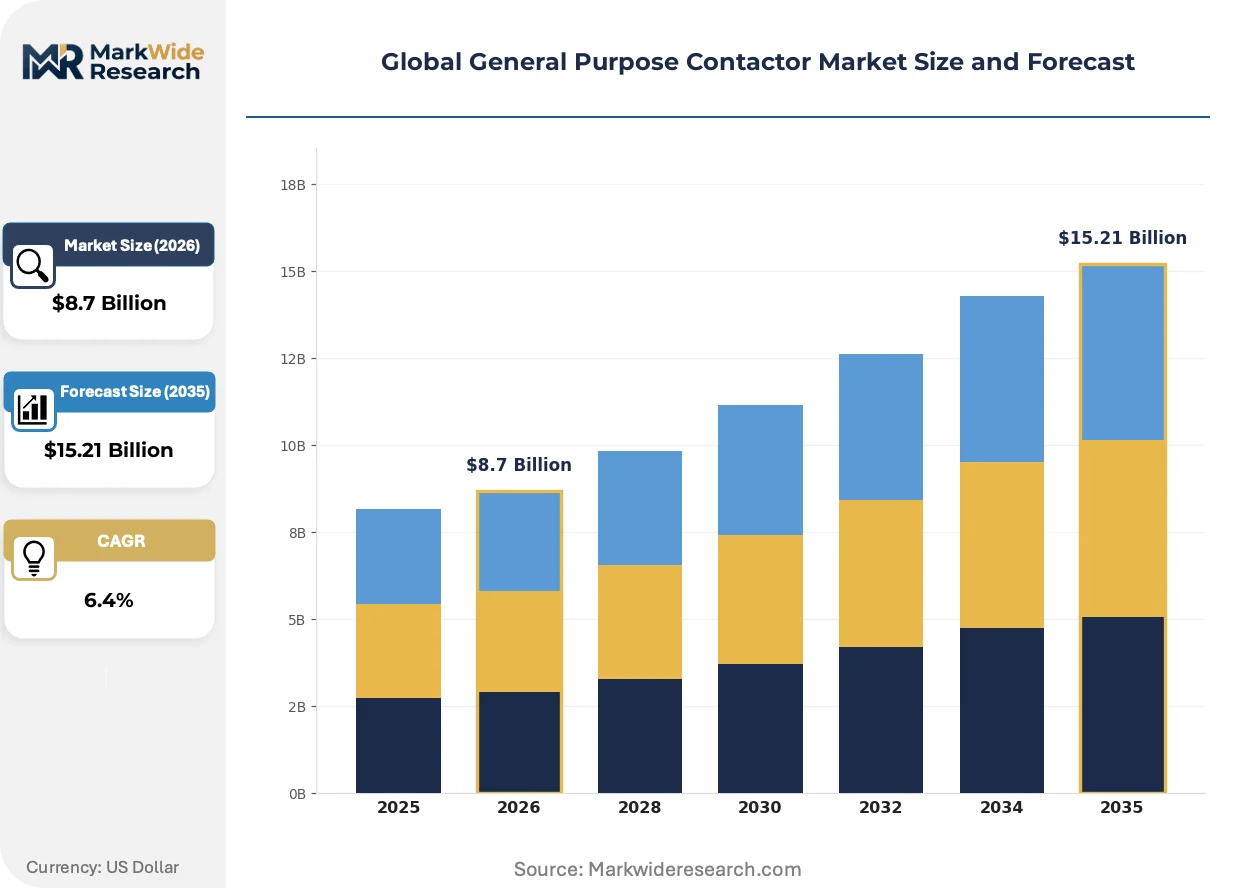
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Contactors, Solid State Contactors, Relay Contactors, Miniature Contactors Application: Industrial Automation, HVAC Systems, Power Distribution, Motor Control End User: Manufacturing, Construction, Transportation, Oil & Gas Technology: Smart Contactors, Conventional Contactors, Digital Contactors, Hybrid Contactors |
| Companies Covered | Eaton, Mitsubishi Electric, ABB, Fuji Electric, Rockwell Automation, Schneider Electric, TE Connectivity, LS Electric, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global General Purpose Contactor Market Emerging Trajectories
Solid-state switching technologies are compressing the addressable market for traditional electromagnetic contactors while regulatory efficiency mandates and buyer behavior shifts reshape competitive positioning across industrial channels.
Silicon carbide-based solid-state contactors is overtaking electromechanical alternatives in semiconductor fabrication cleanrooms and precision HVAC systems where arcless switching eliminates particulate contamination and maintenance downtime. Medical device manufacturers and data center operators are adopting these modules fastest, compressing replacement part revenue pools for incumbent electromagnetic suppliers while enabling predictive thermal management through integrated sensor feedback.
The EU Ecodesign Directive's 2027 efficiency thresholds are forcing coil assembly redesigns across European industrial supply chains, eliminating legacy electromechanical switchgear from approved vendor lists. OEMs serving German automotive and French process industries must absorb compliance documentation costs or cede specification authority to pre-certified competitors with established notified body relationships.
Condition-based procurement contracts are displacing traditional replacement-cycle purchasing in North American heavy industry and European utilities, unbundling hardware sales from predictive maintenance service subscriptions. Mining operations in Australia and oil-and-gas facilities in the US Gulf Coast now specify contactor performance guarantees tied to thermal monitoring data rather than calendar-based replacement intervals, compressing spot-market volumes while elongating supplier-customer contractual relationships.
Global General Purpose Contactor Market Segmentation
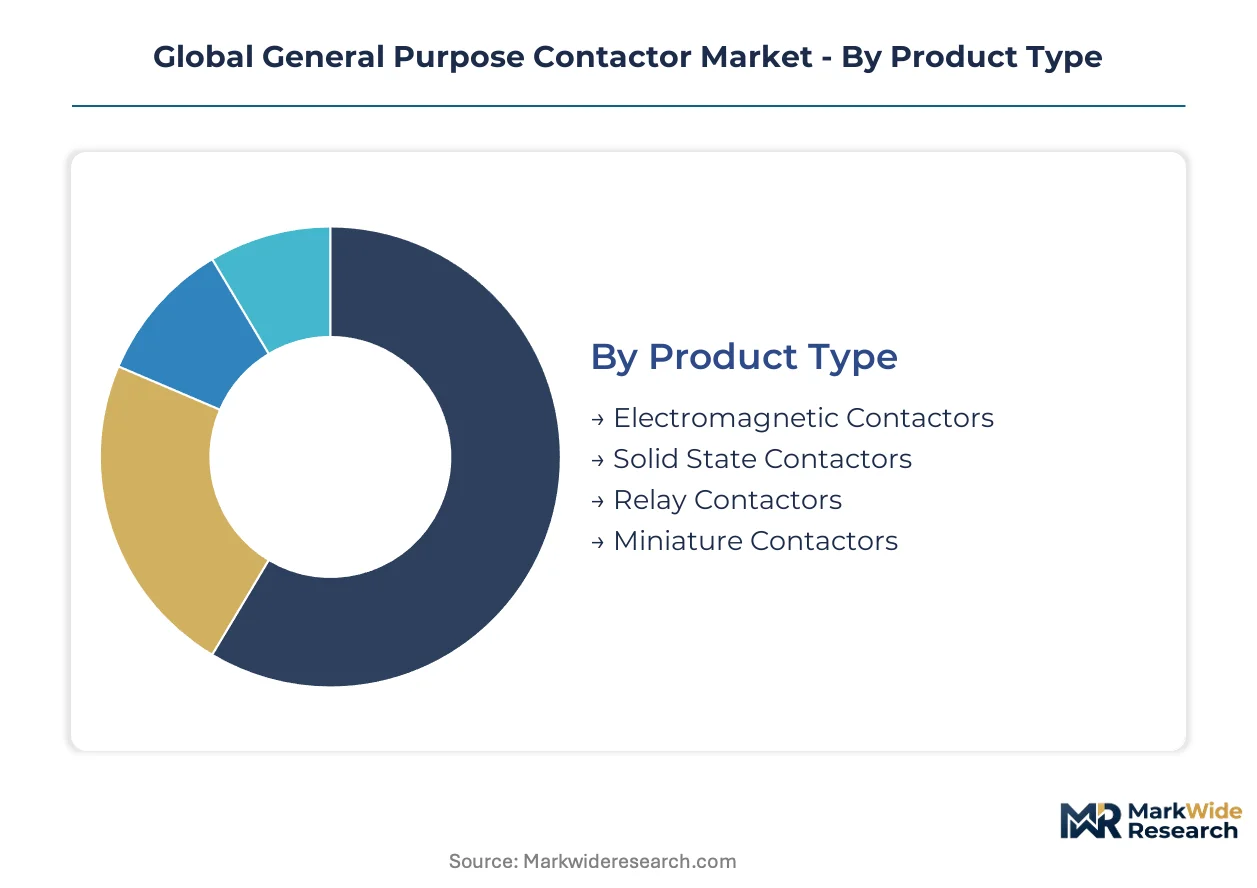
General purpose contactor procurement decisions hinge on switching frequency demands, arc tolerance thresholds, and integration complexity with existing motor control architectures. Segment boundaries blur as hybrid designs merge electromagnetic reliability with solid-state precision, forcing suppliers to position across multiple technical categories simultaneously.
Product Type:
Capital expenditure tiers separate buyers seeking field-service familiarity from those prioritizing maintenance elimination.
- Electromagnetic Contactors:Coil-actuated switching mechanisms using ferrous cores and silver-nickel contact alloys dominate automotive assembly plants across Germany and China. Procurement volume concentrates where technician training pools and replacement part inventories already exist.
- Solid State Contactors:Silicon carbide and IGBT-based modules enable arcless switching in semiconductor fabrication cleanrooms and precision HVAC systems across Japan and South Korea. Medical device manufacturers specify these for particulate-sensitive environments.
- Relay Contactors:Lower-current variants bridge control logic and power circuits in building automation panels.
- Miniature Contactors:Compact DIN-rail units serve space-constrained machine tool control cabinets.
Electromagnetic contactors lead on scale; solid state contactors lead on momentum.
Application:
Operating environment severity determines contact material specification and enclosure rating requirements.
- Industrial Automation:Repetitive motor starting cycles in automotive welding robots and conveyor systems demand AC-4 utilization category ratings with enhanced mechanical endurance. China's eastern manufacturing corridor accounts for concentrated procurement volume.
- HVAC Systems:Compressor and fan motor control in commercial buildings drives specification of arc-suppressed contactors with extended electrical life. Data center cooling infrastructure across the US and UAE represents expanding demand.
- Power Distribution:Utility-scale switchgear integration requires fault-current withstand certification.
- Motor Control:Pump and compressor applications in oil extraction facilities specify explosion-rated enclosures.
Industrial automation leads on scale; HVAC systems lead on momentum.
End User:
Project financing structures and maintenance capability gaps shape procurement channel preferences.
- Manufacturing:Discrete and process industries specify contactors bundled with variable frequency drives for integrated motor control. German automotive OEMs and Chinese smart factory operators drive specification authority.
- Construction:Temporary power distribution and crane motor control demand ruggedized portable units with rapid field replacement protocols.
- Transportation:Railway traction and electric vehicle charging infrastructure require high-voltage DC switching capability.
- Oil & Gas:Offshore platform and refinery applications mandate IECEx and ATEX hazardous area certification.
Manufacturing leads on scale; transportation leads on momentum.
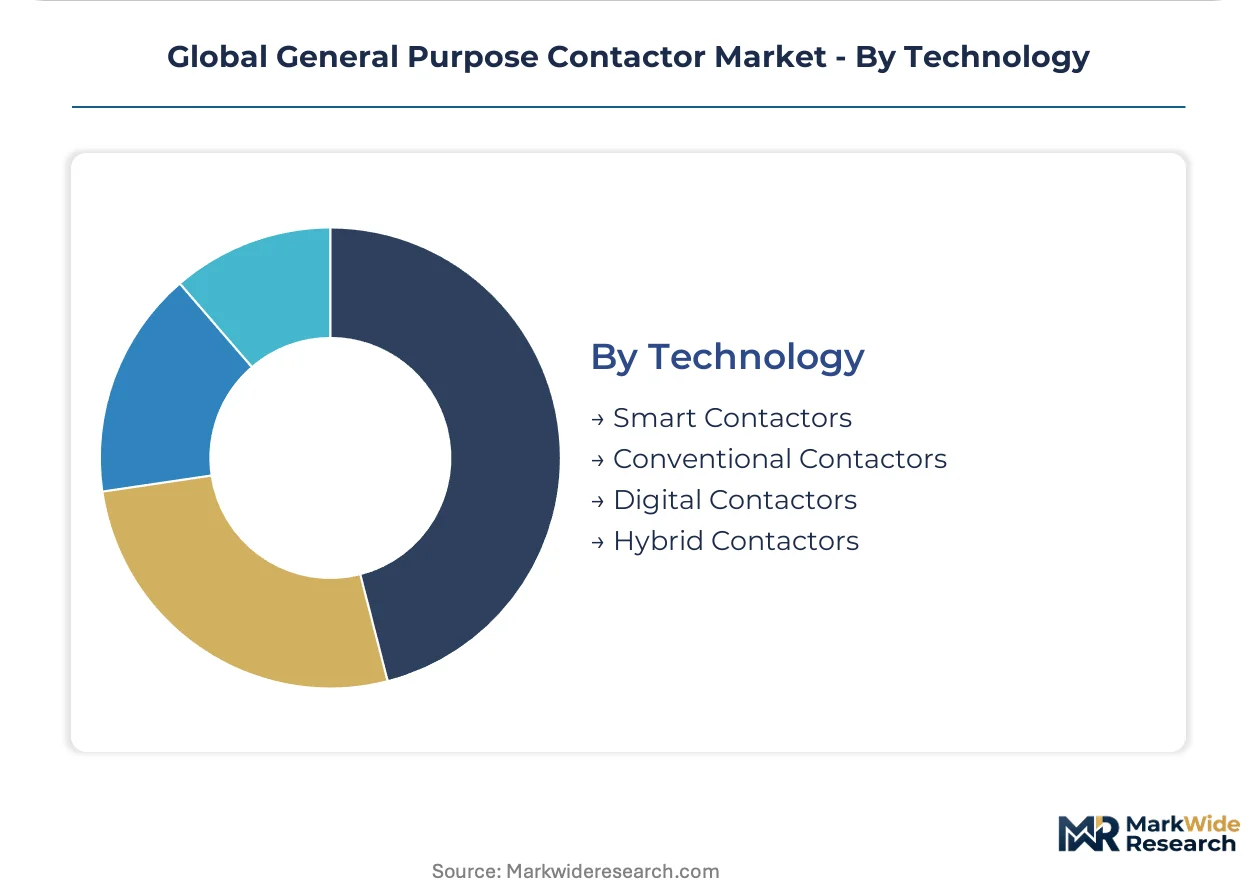
Technology:
Digital interoperability mandates and predictive maintenance service contracts are restructuring competitive positioning.
- Smart Contactors:IoT-enabled thermal monitoring and predictive diagnostics integrate with SCADA architectures for condition-based asset management. European utilities and Australian mining operations specify performance guarantees tied to sensor data.
- Conventional Contactors:Electromechanical designs without embedded electronics retain cost advantage in price-sensitive replacement markets.
- Digital Contactors:Embedded communication protocols enable IEC 61850 integration in European smart grid deployments.
- Hybrid Contactors:Combined electromagnetic and solid-state switching merges arc suppression with mechanical isolation.
Conventional contactors lead on scale; smart contactors lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electrical engineering workforces in Germany, China, and the United States anchor the highest concentrations of contactor specification authority and manufacturing capability.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify IEC-rated contactors for robotic welding lines at scale. The EU Ecodesign Directive's 2027 efficiency thresholds force coil redesigns across Baden-Württemberg's industrial supply base. Bavarian machine builders bundle contactors with drives for export-bound packaging equipment.
China
State-backed smart factory investments in Jiangsu and Zhejiang provinces require millions of motor control contactors annually. GB standards and NMPA-adjacent quality certifications enforce dielectric testing benchmarks for domestic production. Shanghai's eastern manufacturing corridor concentrates procurement volume for automated assembly systems.
United States
Data center cooling infrastructure across Virginia and Texas drives specification of arc-suppressed contactors with extended electrical life. The NFPA-administered National Electrical Code shapes enclosure ratings and fault-current withstand requirements. Gulf Coast oil-and-gas facilities mandate explosion-rated contactor assemblies for offshore platforms.
Japan
Semiconductor fabrication cleanrooms in Kyushu and Kansai specify silicon carbide-based solid-state contactors for particulate-sensitive environments. METI efficiency guidelines accelerate replacement of legacy electromechanical switchgear. Nagoya's precision HVAC sector adopts arcless switching modules fastest.
India
The PLI scheme for industrial automation creates procurement windows as domestic motor control component production scales. BIS certification requirements consolidate supplier qualification processes for multinational OEMs. Gujarat and Maharashtra host emerging clusters of contactor assembly operations serving automotive tier-1 suppliers.
Global General Purpose Contactor Market Vendor Landscape
The competitive structure tilts toward diversified electrical conglomerates with captive semiconductor supply and deep IEC-standard channel presence. Tiered positioning separates premium system integrators from mid-scale electromagnetic specialists and emerging solid-state module producers. Dominant competitive moves include backward integration into silicon carbide foundry capacity and strategic bundling of contactors with variable frequency drives to control project specification authority.
Among diversified European-based electrical conglomerates, Schneider Electric, Siemens, and ABB exemplify the three prevailing competitive archetypes. Schneider Electric occupies a position anchored in premium electromagnetic lines across IEC-standard markets. Siemens represents the captive semiconductor supply model for solid-state contactor modules. ABB sits within the system integration tier, bundling contactors with drives to capture specification authority in process industries.
| Leading Market Players |
|---|
| Eaton |
| Mitsubishi Electric |
| ABB |
| Fuji Electric |
| Rockwell Automation |
| Schneider Electric |
| TE Connectivity |
| LS Electric |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Silicon carbide module adoption in precision HVAC and semiconductor fabrication is simultaneously compressing electromechanical contactor margins and concentrating procurement leverage among East Asian foundry operators. This technology transition forces Western OEMs to absorb premium input costs or cede specification authority to competitors with captive semiconductor supply.
Pricing Analysis
The bundled-vs-unbundled service split separates conventional hardware sales from condition-based maintenance subscriptions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service intensity. Pricing pressure stems from copper and silver alloy volatility compressing margins in electromagnetic lines. Small-scale industrial buyers in India's emerging manufacturing base exhibit highest price sensitivity, while German automotive OEMs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Freight cost escalation from East Asian semiconductor foundries to European assembly plants is reshaping regional sourcing strategies. Supply concentrates in China for electromagnetic coil assemblies, Germany for precision electromechanical components, and Japan for silicon carbide substrates. Raw material dependencies span silver-nickel contact alloys, copper windings, and silicon carbide wafers. Single-source vulnerability in silicon carbide foundry capacity creates procurement risk for solid-state contactor producers. Distribution runs through authorized industrial distributors and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive's 2027 efficiency thresholds function as a regulatory compounder, forcing coil redesigns while accelerating solid-state substitution in premium segments.
For Market Incumbents: Extend backward integration into silicon carbide foundry capacity to secure solid-state module supply against East Asian concentration. Absorb multi-standard certification costs for IEC 60947-4-1, UL 508, and GB compliance to defend specification authority against emerging competitors lacking notified body relationships.
For New Entrants and Emerging Players: Begin with India's PLI-backed industrial automation sector, where domestic motor control component production creates procurement windows without entrenched supplier relationships. Target smart contactor retrofit opportunities in brownfield European utilities seeking IEC 61850 interoperability without full system replacement.
For Investors and Strategic Acquirers: Roll-up economics work for regional electromagnetic specialists with established channel presence because EU Ecodesign compliance costs are forcing portfolio consolidation among sub-scale manufacturers. Monitor silicon carbide substrate pricing as the inflection signal for solid-state contactor margin expansion versus electromechanical decline.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Foundry Capacity | Captive semiconductor supply secures solid-state contactor production against East Asian foundry concentration. |
| Multi-Standard Certification Investment | Simultaneous IEC, UL, and GB compliance opens specification channels across German, US, and Chinese industrial markets. |
| Smart Contactor Platform Development | IoT-enabled thermal monitoring enables condition-based service subscriptions in European utility and Australian mining sectors. |
| VFD-Contactor System Bundling | Integrated motor control solutions capture specification authority in German process industries and Chinese smart factories. |
| India Manufacturing Base Establishment | PLI scheme incentives support domestic assembly operations serving automotive tier-1 suppliers in Gujarat and Maharashtra. |
Methodological Framework
Bottom-up industrial automation modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and industrial distributors combined with secondary validation from IEC standard documentation, customs trade data, SEC filings, and notified body certification registries. Cross-referencing bottom-up installation data against top-down production volumes from East Asian foundries and European electromagnetic component manufacturers ensures triangulation integrity.
The input-output matrix maps contactor unit demand across product type, application severity, end-user industry, and technology tier against supply-side capacity from major manufacturing clusters. CAGRs derive from segmented growth rate reconciliation across the projection horizon, incorporating industrial electrification intensity, regulatory compliance deadlines, and substitution elasticity between electromagnetic and solid-state architectures. Forecast inputs include automotive production schedules from German and Chinese OEMs, smart factory investment flows from China's eastern manufacturing corridor, and HVAC equipment shipment data from US and UAE data center operators.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions beyond current Ecodesign Directive timelines, geopolitical disruptions to semiconductor supply chains, and breakthrough solid-state technologies eliminating electromechanical alternatives entirely. Forecasts reflect documented assumptions about substitution rates and compliance cost absorption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
HID Ballast Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
China DC Motor Market
Electrical Equipment
Heat Shrink Terminations Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Vacuum Circuit Breaker Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
United States Busbar Market
Electrical Equipment
Low Voltage Motor Control Centers Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
Middle East and Africa Electric Drives Market