
 North America Syndicated Loans Market | 2026-2036
North America Syndicated Loans Market Size, Share, and Industry Trends Forecast 2026-2036
North America Syndicated Loans Market Insights
The SEC's climate disclosure mandate is repositioning syndicated loan underwriting standards across North America. J.P. Morgan anchors its leadership through proprietary ESG scoring integration into credit facilities. Citi differentiates via sustainability-linked pricing structures that tie borrowing costs to emissions benchmarks. Goldman Sachs competes aggressively for mega-cap energy transition financing in the Permian Basin and Alberta oil sands.
A syndicated loan is a debt facility underwritten by a group of lenders and structured across multiple tranches with varying maturity profiles, security packages, and pricing grids. Term loans dominate transaction volume in North America, reflecting corporate preference for fixed-amortization structures over revolving commitments. Revolving credit facilities command premium pricing in technology and healthcare verticals due to working-capital volatility and covenant flexibility requirements. Bridge loans represent the fastest-expanding segment, fueled by private equity sponsors pursuing time-sensitive acquisition financing.
The Office of the Comptroller of the Currency and Federal Reserve jointly govern bank capital reserves and leveraged lending guidance, directly constraining arranger capacity and pricing floors. The SEC's enhanced disclosure framework is forcing borrowers to standardize climate risk reporting before syndication, extending due diligence timelines. Stakeholders must monitor how regional Federal Reserve banks calibrate stress-testing scenarios for commercial real estate exposure, as office-sector distress threatens collateral values across multi-bank facilities.
Market Dynamics
The SEC's climate disclosure mandate is compressing due diligence timelines and forcing borrowers to standardize emissions reporting before syndication. Arrangers now embed ESG scoring directly into credit facilities, reshaping underwriting workflows across the United States and Canada.
Growth Catalysts
- Healthcare capital expenditure:Hospital networks and pharmaceutical modernization programs are expanding borrowing for facility upgrades and equipment procurement across the United States.
- Energy transition financing:The Inflation Reduction Act is channeling capital into Permian Basin and Alberta oil sands decarbonization projects, creating specialized credit demand.
- Private equity acquisition activity:Sponsor-driven M&A is accelerating demand for bridge loans and time-sensitive acquisition facilities in technology and healthcare verticals.
Market Restraints
- Basel III capital reserve requirements:The Federal Reserve and Office of the Comptroller of the Currency are constraining arranger capacity through leveraged lending guidance and tiered capital buffers.
- Commercial real estate collateral erosion:Office-sector distress in urban cores is threatening collateral values across multi-bank facilities, particularly in downtown Chicago and Manhattan submarkets.
- Interest rate volatility:Federal Reserve policy uncertainty is widening pricing grids and compressing commitment periods for revolving credit facilities.
Strategic Opportunities
- Sustainability-linked pricing structures:Borrowing costs tied to emissions benchmarks are creating differentiation for arrangers targeting ESG-mandated institutional investors.
- Texas energy corridor specialization:Concentrated drilling and carbon capture investment in the Permian Basin is generating demand for project-specific term loan tranches.
- Technology hub revolving facilities:California SaaS and semiconductor firms require covenant-flexible working capital structures with volatility-adjusted pricing grids.
Industry Challenges
- Climate risk data standardization:Borrowers face extended documentation timelines as the SEC's enhanced disclosure framework forces emissions reporting alignment before syndication closes.
- Multi-tranche coordination complexity:Structuring facilities across term loans, revolving commitments, and bridge components requires specialized legal expertise that remains concentrated among top-tier arrangers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Syndicated Loans Market |
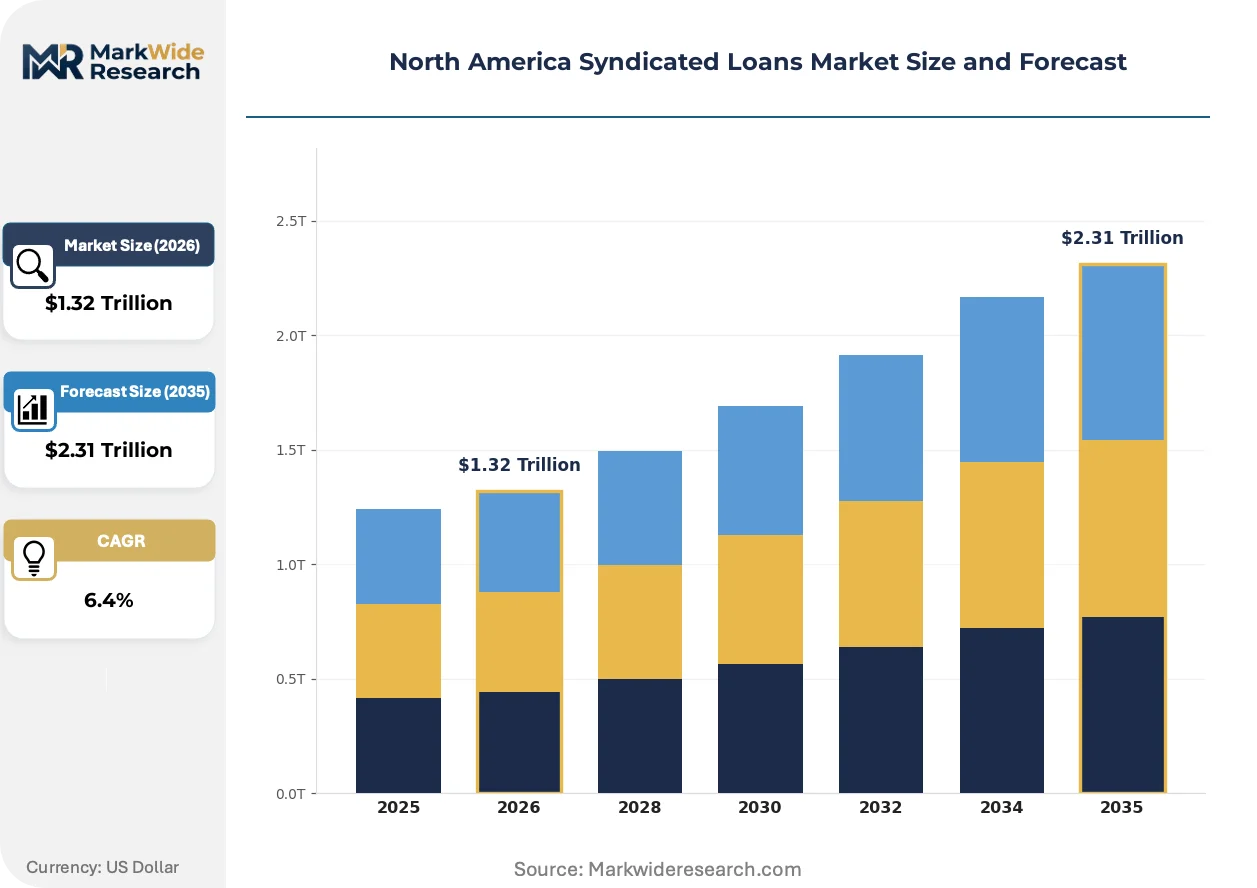
| Market Size in 2026 | $1.32 Trillion |
| Market Size in 2035 | $2.31 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Term Loans, Revolving Credit, Bridge Loans, Other Facilities Industry Vertical: Healthcare, Technology, Real Estate, Energy Borrower Type: Corporations, Financial Institutions, Governments, Private Equity Transaction Size: Small Cap, Mid Cap, Large Cap, Mega Cap |
| Companies Covered | Citi, BNP Paribas, J.P. Morgan, Scotiabank, SMBC, Wells Fargo, HSBC, Goldman Sachs, Bank of America, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Syndicated Loans Market Trends and Innovations
Digital workflow platforms are compressing syndication timelines from documentation to close. Climate risk analytics and API-based lender communication tools are becoming standard infrastructure for competitive arrangers.
Artificial intelligence-driven credit scoring is consolidating loan origination workflows across major arrangers. Regional banks and specialty lenders are adopting machine learning models for covenant monitoring and early default detection. The technology is consolidating due diligence functions previously fragmented across legal, financial, and sustainability workstreams.
The SEC's climate disclosure rules are mandating standardized emissions reporting for publicly traded borrowers before syndication. Industrial consequence includes extended legal review periods and new representation requirements in credit agreements. Energy and materials borrowers in Texas and Alberta are responding by pre-positioning third-party verification to accelerate timeline-sensitive facilities.
Buyers are unbundling after-sales advisory from primary credit facilities, purchasing covenant compliance monitoring and restructuring advisory as separate service lines. Traditional relationship banking models are losing share to specialized advisory boutiques in technology and healthcare verticals. This pattern is most visible among mid-cap borrowers in California's semiconductor and SaaS clusters.
North America Syndicated Loans Market Segmentation
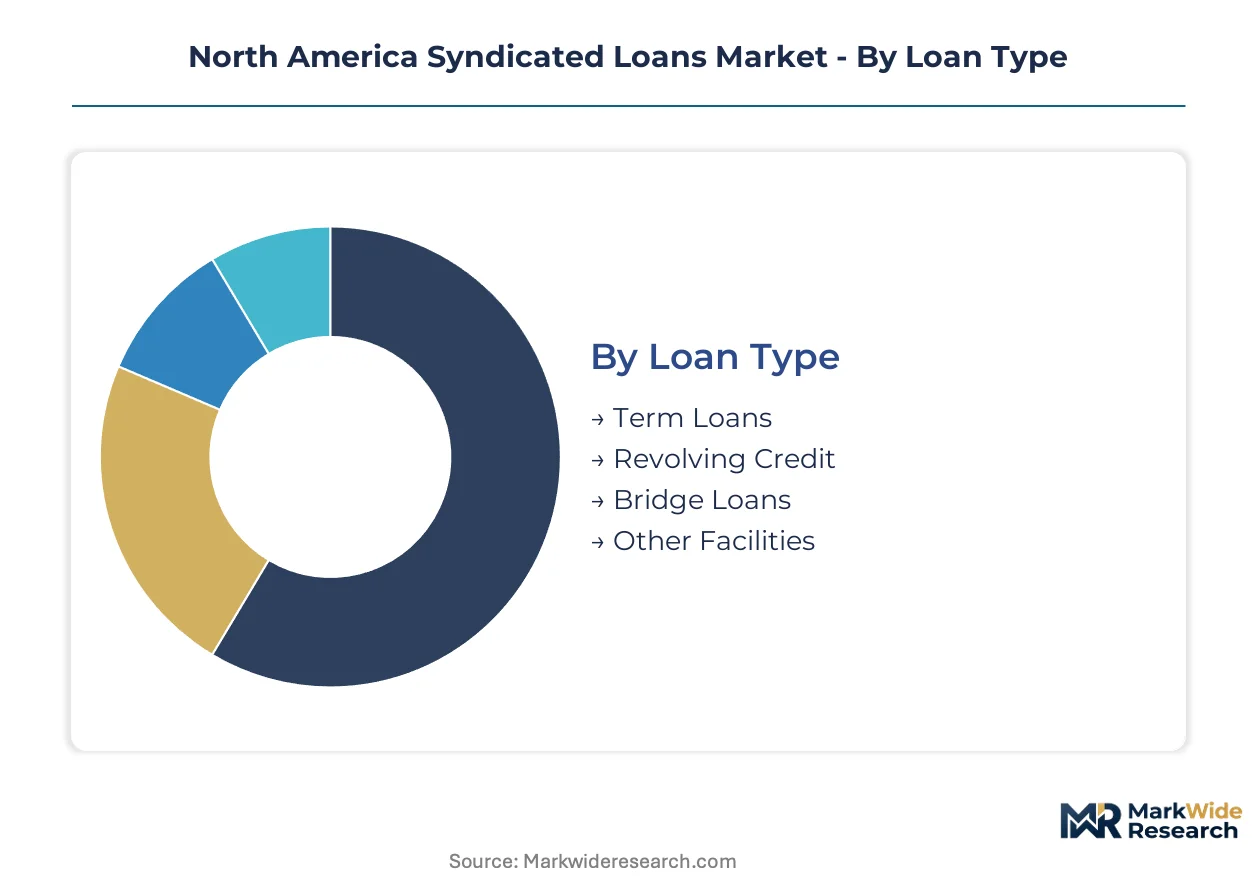
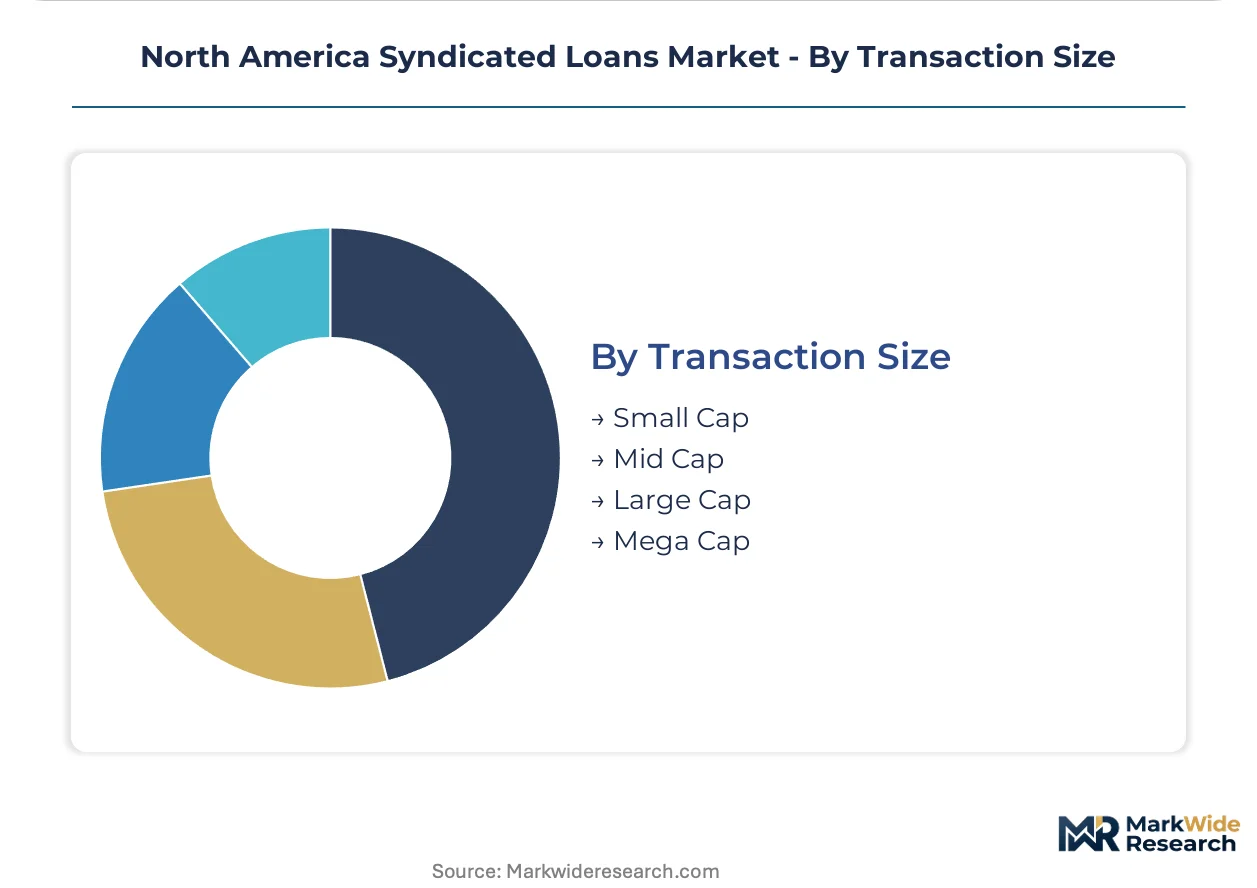
Segmentation in syndicated lending determines arranger specialization, pricing grid calibration, and distribution strategy. Borrower risk profiles, facility structures, and regulatory treatment vary sharply across dimensions, forcing banks to build distinct underwriting capabilities for each slice.
Loan Type:
Borrowers select facility structures based on cash flow predictability, deployment timing, and covenant flexibility requirements.
- Term Loans:Fixed-amortization debt with bullet or scheduled principal repayments, typically secured by asset liens or cash flow pledges. Corporate borrowers in Texas energy corridors favor term loans for drilling program capitalization, drawn by rate certainty and predictable deleveraging schedules.
- Revolving Credit:Commitment-based facilities allowing repeated drawdown and repayment within tenor limits, priced on utilization tiers. California technology firms and healthcare networks dominate demand, requiring liquidity buffers for working capital volatility and acquisition optionality.
- Bridge Loans:Short-term acquisition financing with mandatory takeout provisions, commanding premium pricing for speed-to-close. Private equity sponsors deploy these for time-sensitive M&A in technology and healthcare verticals.
- Other Facilities:Letter of credit tranches, swingline commitments, and delayed-draw term loans addressing specialized liquidity needs.
Term loans lead on scale; bridge loans lead on momentum.
Industry Vertical:
Vertical concentration shapes collateral valuation methodologies, covenant intensity, and arranger domain expertise.
- Healthcare:Hospital networks and pharmaceutical manufacturers borrow for facility modernization, equipment procurement, and vertical integration into specialty pharmacy services. Demand concentrates in United States metropolitan markets with aging demographics and Medicare reimbursement expansion.
- Technology:SaaS providers and semiconductor firms require covenant-flexible structures with EBITDA add-backs for stock compensation. California clusters drive volume, with pricing grids adjusting for recurring revenue quality and customer concentration.
- Real Estate:Office, industrial, and multifamily developers access construction and permanent financing through multi-bank facilities. Collateral stress in downtown Chicago and Manhattan submarkets is compressing loan-to-value thresholds.
- Energy:Permian Basin drilling programs and Alberta oil sands decarbonization projects generate specialized term loan demand with reserve-based borrowing bases.
Healthcare leads on scale; technology leads on momentum.
Borrower Type:
Entity classification determines regulatory capital treatment, disclosure requirements, and arranger relationship depth.
- Corporations:Investment-grade and leveraged issuers accessing syndicated markets for general corporate purposes, capital expenditure, and liability management. SEC climate disclosure mandates are extending due diligence timelines for public filers.
- Private Equity:Sponsor-backed portfolio companies driving bridge loan and leveraged term loan volume through acquisition financing. Sponsor reputation and equity cushion depth drive pricing and covenant flexibility.
- Financial Institutions:Regional banks and specialty lenders accessing syndicated facilities for regulatory capital relief and liquidity management.
- Governments:Municipal and state entities financing infrastructure through tax-exempt or taxable syndicated structures with sovereign immunity considerations.
Corporations lead on scale; private equity leads on momentum.
Transaction Size:
Deal scale dictates arranger tier participation, investor distribution strategy, and documentation standardization.
- Mega Cap:Facilities exceeding institutional thresholds requiring global coordinator appointment and multi-tranche execution across term loan and bond markets. Energy transition financing in the Permian Basin and Alberta oil sands dominates recent issuance.
- Large Cap:Established corporate borrowers with investment-grade or strong leveraged profiles, accessing relationship-driven syndication with regional bank participation.
- Mid Cap:Growing companies requiring boutique arranger expertise for covenant negotiation and investor education, particularly in California technology clusters.
- Small Cap:Regional borrowers and specialty situations accessing club deals or unitranche structures with limited syndication depth.
Mega cap leads on scale; mid cap leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Syndicated lending originated in the United States during the 1970s oil boom, when multiple banks pooled capital to finance energy extraction projects too large for single balance sheets. The practice spread to Canada and Mexico as cross-border corporate borrowing accelerated through NAFTA-era integration.
United States
Hospital networks in Texas and pharmaceutical manufacturers in New Jersey are expanding borrowing for facility modernization and equipment procurement. The SEC's climate disclosure mandate is extending due diligence timelines for public filers before syndication closes. Dallas-Fort Worth energy corridors and California's semiconductor clusters in San Jose drive concentrated demand for term loans and revolving credit facilities.
Canada
Alberta oil sands operators and Toronto-based mining conglomerates are accessing multi-bank facilities for decarbonization capital expenditure. The Office of the Superintendent of Financial Institutions governs bank capital reserves and leveraged lending guidance, constraining arranger capacity. Calgary's energy transition financing and Vancouver's mining headquarters anchor specialized credit demand with reserve-based borrowing structures.
Mexico
Monterrey manufacturing conglomerates and Mexico City infrastructure developers are tapping cross-border syndicated markets for peso and dollar-denominated facilities. The central bank calibrates macroprudential buffers for foreign currency exposure in multi-bank lending. Bajío Region automotive suppliers and Northern Border States maquiladoras generate working-capital facility demand with volatility-adjusted pricing grids.
North America Syndicated Loans Market Competitive Landscape
Capital-heavy universal banks compete with relationship-driven regional specialists in syndicated loan arrangement. The United States and Canadian markets concentrate around money-center institutions with balance-sheet depth for mega-cap underwriting, while mid-market share fragments across specialty boutiques. Three archetypes dominate: global coordinators with proprietary distribution networks, sustainability-focused arrangers embedding ESG pricing structures, and sector-specialist boutiques targeting technology and healthcare verticals. Competitive intensity manifests through M&A advisory bundling and sustainability-linked pricing differentiation.
Among North American-based arrangers, J.P. Morgan, Citi, and Goldman Sachs exemplify the tier-one coordinator archetype. J.P. Morgan anchors leadership through ESG scoring integration into credit facilities. Citi occupies a position defined by sustainability-linked pricing structures that tie borrowing costs to emissions benchmarks. Goldman Sachs represents aggressive competition for energy transition financing in the Permian Basin and Alberta oil sands.
| Leading Market Players |
|---|
| Citi |
| BNP Paribas |
| J.P. Morgan |
| Scotiabank |
| SMBC |
| Wells Fargo |
| HSBC |
| Goldman Sachs |
| Bank of America |
| Others |
Pricing and Supply Chain Analysis
ESG-credentialed credit analysts concentrated in New York and London command compensation premiums that compress pricing spreads between sustainability-linked and conventional facilities. Labor-cost differentials between these specialized underwriting teams and generalist arrangers in regional banking centers directly widen the premium-to-standard pricing tier spread across North American syndicated lending.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ESG-integrated facilities from relationship-driven conventional structures from commoditized club deals. Price differentiation rests on sustainability certification depth and arranger balance-sheet commitment scale. Pricing pressure stems from Federal Reserve rate uncertainty widening commitment-period spreads. Private equity sponsors show highest price sensitivity due to leverage covenant tightness, while investment-grade corporate borrowers prioritize certainty over basis points.
Supply Chain Analysis
Domestic-content mandates in the Inflation Reduction Act are reshaping lender sourcing toward US-based institutional investors and regional bank participants. Capital provision concentrates in the United States, Canada, and select Caribbean financial centers. Raw material dependencies include commercial real estate collateral pools, energy reserve bases, and technology recurring revenue streams. Single-source vulnerability sits with mega-cap global coordinators controlling distribution networks. Distribution runs through primary syndication to institutional investors, with secondary trading via loan assignment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America syndicated loans market functions as a stable compounder, with healthcare capital expenditure and energy transition financing providing durable demand floors across economic cycles.
For Market Incumbents: Cement leadership by embedding proprietary climate risk analytics into credit facilities before SEC disclosure mandates harden into standard documentation. Deepen balance-sheet commitment to Texas energy corridor term loans to defend against regional specialist encroachment. Prioritize ESG scoring integration as the primary differentiation lever against sustainability-focused competitors.
For New Entrants and Emerging Players: API-based lender communication platforms offer the most penetrable entry vector for mid-market technology borrowers in California semiconductor clusters. Target healthcare network revolving facilities in secondary US metropolitan markets where relationship banking gaps persist. Lead with covenant compliance monitoring sold as standalone advisory to unbundle from primary credit relationships.
For Investors and Strategic Acquirers: Regional banks with energy transition lending expertise are the most active acquirer in this space, consolidating boutique arrangers for sector specialization. The five-to-ten year viability window favors platforms with proprietary distribution networks over balance-sheet-dependent originators. Watch Federal Reserve stress-testing scenario adjustments for commercial real estate as the inflection signal for collateral value compression across multi-bank facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| ESG Scoring Integration | J.P. Morgan's proprietary framework embeds emissions benchmarks directly into credit facility pricing grids. |
| Sustainability-Linked Pricing Structure | Citi ties borrowing costs to verified emissions reductions, attracting institutional ESG-mandated capital. |
| Energy Transition Financing Specialization | Goldman Sachs concentrates mega-cap underwriting capacity on Permian Basin decarbonization projects. |
| Digital Workflow Platform Deployment | AI-driven credit scoring compresses syndication timelines from documentation through lender allocation. |
| Vertical Advisory Unbundling | Boutique arrangers sell covenant monitoring and restructuring advisory separate from primary facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged syndicated loan originators at global coordinators, credit portfolio managers at institutional investors, legal counsel specializing in multi-tranche documentation, and regulatory affairs officers at the SEC and Federal Reserve. Secondary validation drew from SEC filing databases, Loan Syndications and Trading Association transaction records, Federal Reserve Senior Loan Officer Opinion Surveys, and Office of the Comptroller of the Currency leveraged lending guidance. Bottom-up facility-level aggregation and top-down macro credit flow analysis were cross-checked for triangulation.
Historical reference periods anchored the projection horizon to post-2010 regulatory regime shifts including Basel III implementation and leveraged lending guidance evolution. Segmentation dimensions modeled encompass facility structure, industry vertical, borrower type, and transaction size tier. CAGRs were derived from trend extrapolation adjusted for regulatory capital constraint scenarios and sector-specific demand elasticity. Forecast inputs include healthcare capital expenditure cycles, energy transition investment flows, and private equity dry powder deployment rates.
The model assumes a particular technology adoption path; alternative pathways for AI-driven credit scoring and digital syndication platforms would alter the outlook. Forecasts reflect assumptions around Federal Reserve policy calibration, SEC disclosure rule enforcement timing, and commercial real estate collateral stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
UK Car Loan Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Qatar Mortgage/Loan Brokers Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
Debt Financing Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
China Mortgage/Loan Brokers Market