
 Debt Financing Market | 2026-2036
Debt Financing Market Size, Share, and Industry Trends Forecast 2026-2036
Debt Financing Market Analysis
Infrastructure and clean energy project finance is repositioning capital flows away from traditional corporate lending toward asset-backed structures. JPMorgan Chase and Co. leverages its balance sheet scale to anchor syndicated loan markets for utility-scale renewables. Deutsche Bank AG specializes in European green bond underwriting, while Morgan Stanley competes through sustainability-linked structuring capabilities.
Debt financing encompasses the provision of capital through fixed-income instruments or credit facilities where borrowers retain ownership while obligating repayment with interest, typically governed by covenants specifying leverage ratios, collateral coverage, and maturity schedules. Its commercial purpose centers on enabling capital formation without equity dilution across corporate, municipal, and sovereign balance sheets. Corporate bonds command the deepest liquidity pools among instrument types, while acquisition funding generates the widest fee margins for arrangers. Institutional investors dominate primary allocations, though private equity co-investment vehicles are capturing share in leveraged finance.
The Federal Reserve's stress testing regime, the European Central Bank's targeted longer-term refinancing operations, and the Basel Committee's net stable funding ratio collectively shape lender capacity and pricing discipline across jurisdictions. These frameworks constrain maturity transformation and elevate capital charges for riskier exposures. Stakeholders must monitor how central bank quantitative tightening and evolving climate risk disclosure mandates recalibrate both supply availability and investor appetite across credit tiers.
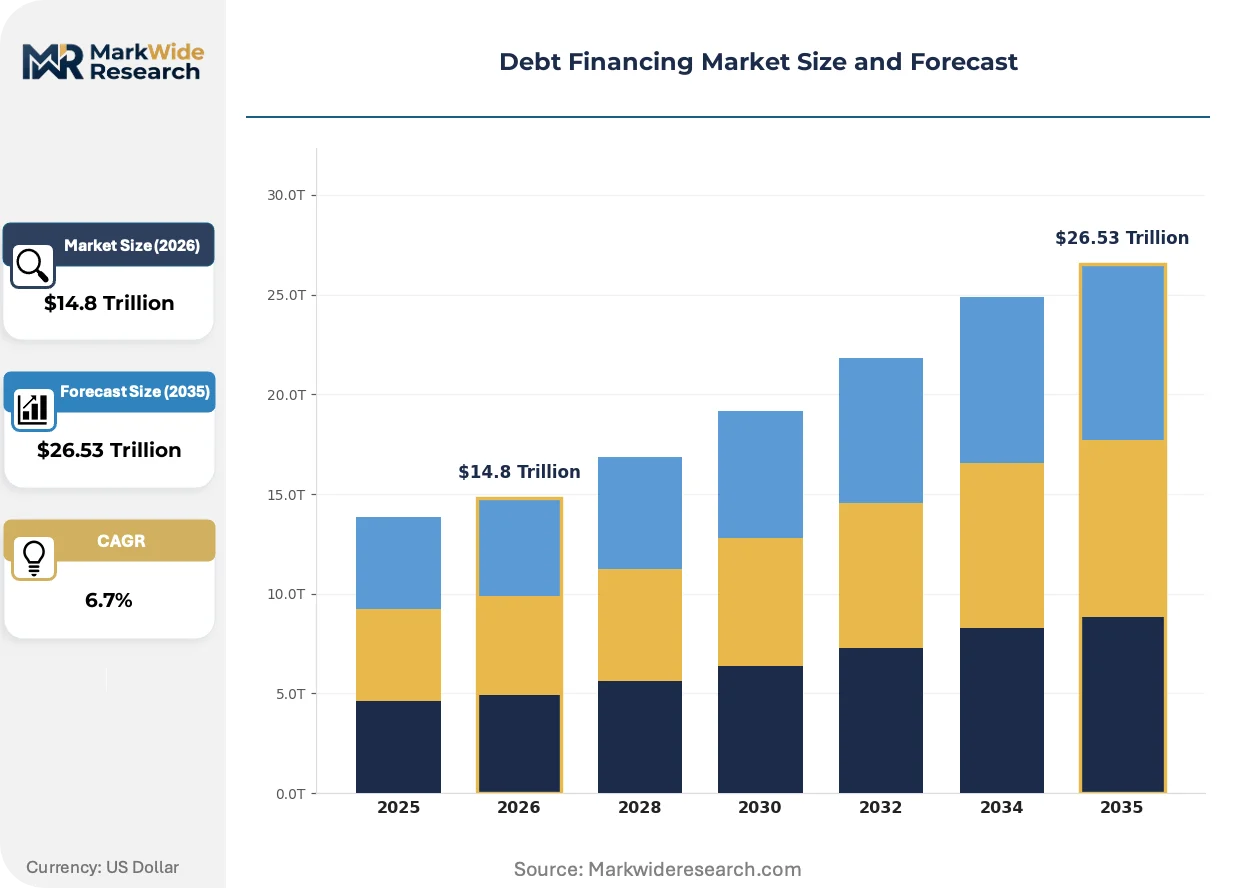
Market Dynamics
Basel III net stable funding ratio requirements and Federal Reserve stress testing are compressing maturity transformation capacity across commercial banking, forcing lenders toward shorter-tenor structures and accelerating private credit market expansion.
Growth Catalysts
- Green bond issuance frameworks:EU Green Deal taxonomy alignment and SEC climate disclosure rules are channeling institutional capital into labeled debt instruments for renewable energy and sustainable infrastructure projects.
- Private credit fund formation:Limited partner allocations to direct lending strategies are expanding non-bank capacity for middle-market leveraged finance and asset-backed opportunities.
- China's dual carbon goals:Policy mandates for peak emissions by 2030 and carbon neutrality by 2060 are driving state-backed financial institutions to expand green loan portfolios for solar and wind developers.
Market Restraints
- Central bank quantitative tightening:Federal Reserve balance sheet reduction and ECB asset purchase program unwinding are draining systemic liquidity and widening credit spreads for sub-investment-grade issuers.
- Basel III output floor implementation:Standardized approach capital requirements are elevating risk-weighted asset charges for internal ratings-based banks, constraining syndicated loan appetite for speculative-grade corporates.
- Interest rate volatility transmission:SOFR transition complexity and embedded floor provisions in floating-rate structures are creating hedging cost inflation for rate-sensitive borrowers in commercial real estate.
Strategic Opportunities
- Sustainability-linked loan structuring:Margin ratchet mechanisms tied to science-based targets are opening fee generation for arrangers serving ESG-mandated institutional investors.
- India infrastructure debt funds:RBI regulatory forbearance for long-term financing vehicles and National Investment and Infrastructure Fund capital commitments are creating dedicated pools for transport and energy assets.
- Tokenized private placement platforms:Distributed ledger settlement infrastructure is compressing settlement cycles and expanding retail access to previously institutional-only credit exposures.
Industry Challenges
- Climate risk modeling capability gaps:Transition scenario analysis and physical risk quantification for loan portfolios require specialized data science talent scarce in traditional credit functions.
- Legacy covenant monitoring systems:Manual financial reporting collection and EBITDA adjustment verification create operational drag as leveraged loan documentation grows more complex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Debt Financing Market |
| Market Size in 2026 | $14.8 Trillion |
| Market Size in 2035 | $26.53 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Instrument Type: Corporate Bonds, Government Bonds, Bank Loans, Debentures Investor Type: Institutional Investors, Retail Investors, Hedge Funds, Private Equity Purpose: Expansion Financing, Debt Restructuring, Working Capital, Acquisition Funding Risk Level: High Risk, Medium Risk, Low Risk, Investment Grade |
| Companies Covered | Banco Santander SA, Bank of America Corp., Barclays PLC, Citigroup Inc., Deutsche Bank AG, JPMorgan Chase and Co., Morgan Stanley, The Goldman Sachs Group Inc., European Investment Bank, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Debt Financing Market Emerging Trajectories
Digital origination platforms and algorithmic credit decisioning are compressing underwriting timelines while ESG data integration is reshaping pricing frameworks across primary and secondary debt markets.
Blockchain-based settlement infrastructure is modularizing primary issuance workflows for corporate bonds and private placements. Investment banks and arranger platforms are piloting smart contract-enabled coupon payments and automated covenant compliance verification. This architecture is compressing settlement cycles from T+2 to near-instantaneous while reducing reconciliation costs for trustee and paying agent functions.
EU Corporate Sustainability Reporting Directive disclosure mandates are forcing granular ESG metric attestation into loan documentation and bond prospectuses. Issuers face expanded liability for forward-looking climate statements while investors demand third-party verification of sustainability claims. European leveraged finance and high-yield segments are experiencing the most pronounced documentation inflation as borrowers adapt to CSRD-aligned due diligence protocols.
Direct lending funds are disintermediating traditional bank-led syndication for middle-market acquisition financing. Institutional limited partners are accepting longer lock-up periods and reduced liquidity in exchange for yield pickup over broadly syndicated loan benchmarks. North American private equity sponsors have accelerated this channel shift, with direct lenders capturing majority share of sub-$500 million enterprise value buyout debt packages.
Debt Financing Market Segmentation
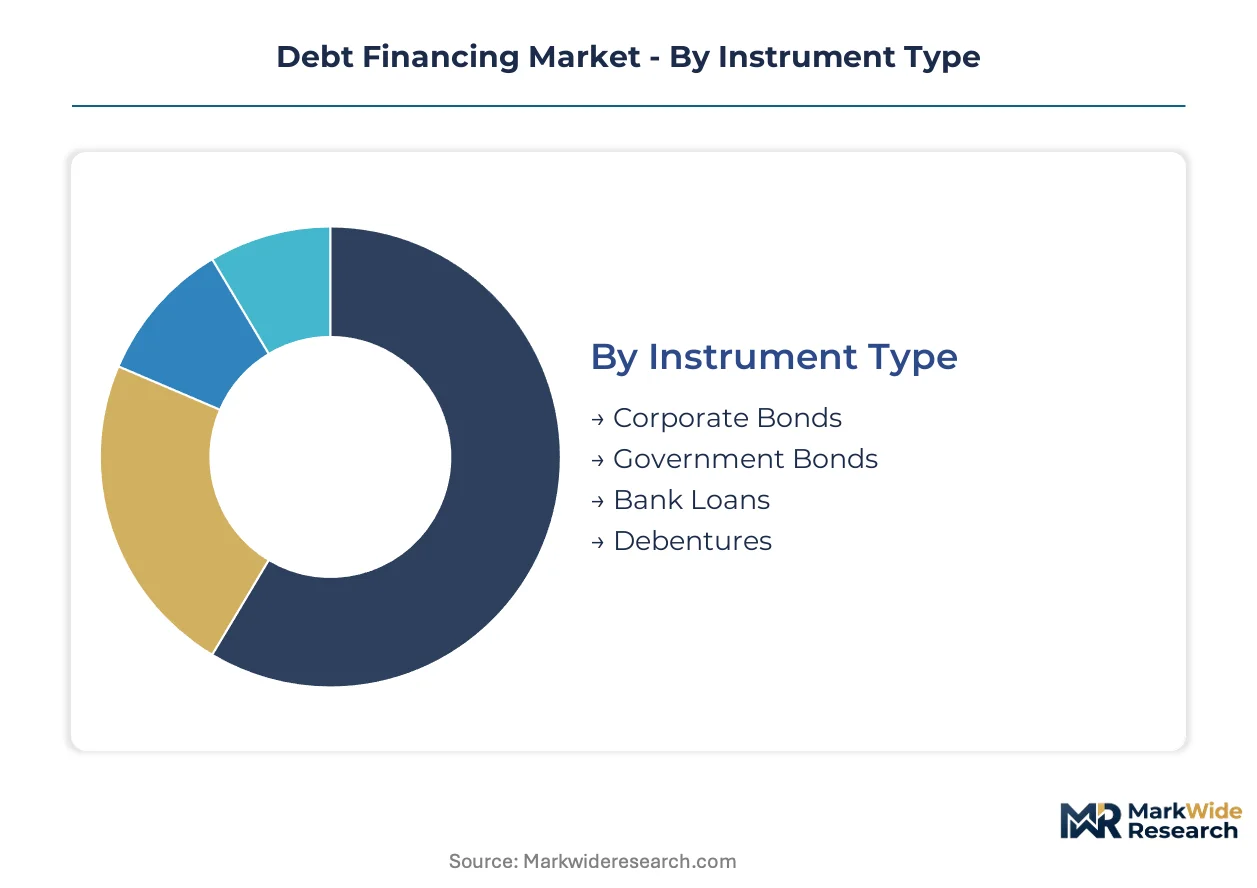
Debt financing instruments serve distinct capital formation objectives across borrower risk profiles and investor liquidity preferences. Structural variation in covenants, collateral requirements, and maturity schedules creates natural segmentation boundaries that dictate pricing frameworks and distribution channels.
Instrument Type:
Refinancing cycles and maturity wall pressures drive rotation between bank and capital market channels as borrowers optimize all-in cost structures.
- Corporate Bonds:Unsecured fixed-income securities with investment-grade and high-yield tranches trade in deep secondary markets. Demand concentrates among US insurance companies and pension funds seeking duration-matched assets; liquidity premiums compress for frequent issuers with established shelf registration programs.
- Government Bonds:Sovereign debt instruments carry explicit or implicit central government guarantees with zero or near-zero risk weighting under Basel frameworks. Germany and China dominate issuance volumes; institutional allocations surge during flight-to-quality episodes when corporate credit spreads widen.
- Bank Loans:Bilateral or syndicated credit facilities with floating-rate structures tied to SOFR or EURIBOR benchmarks. Revolving credit lines support working capital cycles for middle-market corporates across industrial clusters.
- Debentures:Long-dated unsecured obligations issued by corporations or municipalities without specific asset collateralization. Indian infrastructure developers and US municipal utilities deploy these structures for project-specific capital raises.
Volume placements concentrate in corporate bonds; the faster expansion belongs to bank loans as private credit funds disintermediate traditional syndication.
Investor Type:
Regulatory capital treatment and liability duration matching shape allocation discipline across investor categories with divergent liquidity requirements.
- Institutional Investors:Insurance companies, pension funds, and asset managers with long-dated liabilities dominate primary market subscriptions. Life insurers in Japan and Germany anchor demand for long-tenor investment-grade paper to match annuity obligations.
- Retail Investors:Individual households access debt markets through mutual funds, exchange-traded funds, and direct brokerage platforms. China's wealth management product distribution channels channel household savings into corporate credit exposures.
- Hedge Funds:Absolute return vehicles exploit relative value dislocations and distressed situations through long-short credit strategies. Event-driven funds concentrate in stressed loan and high-yield special situations with covenant negotiation leverage.
- Private Equity:Sponsor balance sheets and co-investment vehicles provide junior capital for leveraged buyout financing. North American buyout firms deploy preferred equity and mezzanine structures beneath senior loan stacks.
Institutional investors command primary allocation priority; private equity is climbing the fastest as direct lending strategies capture middle-market share.
Purpose:
Capital deployment intent determines structural flexibility, covenant intensity, and pricing negotiation leverage between borrowers and arrangers.
- Expansion Financing:Greenfield project funding and capacity expansion capex require long-dated commitments with construction risk phase transitions. Renewable energy developers in the United States structure tax equity partnerships alongside term debt for utility-scale solar installations.
- Debt Restructuring:Liability management exercises including tender offers, exchange offers, and amendment negotiations to extend maturities or reduce coupons. Distressed borrowers in commercial real estate sectors pursue covenant relief and maturity extensions.
- Working Capital:Revolving credit facilities and trade finance instruments support inventory cycles and accounts receivable conversion. Seasonal agribusiness operators in Brazil and India draw on committed lines during harvest financing windows.
- Acquisition Funding:Leveraged finance packages backing corporate mergers and sponsor buyouts with senior secured, second lien, and mezzanine tranches. Private equity sponsors in Europe and North America drive volume with public-to-private transactions.
Acquisition funding generates widest fee margins for arrangers; expansion financing is gaining share fastest as infrastructure decarbonization accelerates capital deployment.
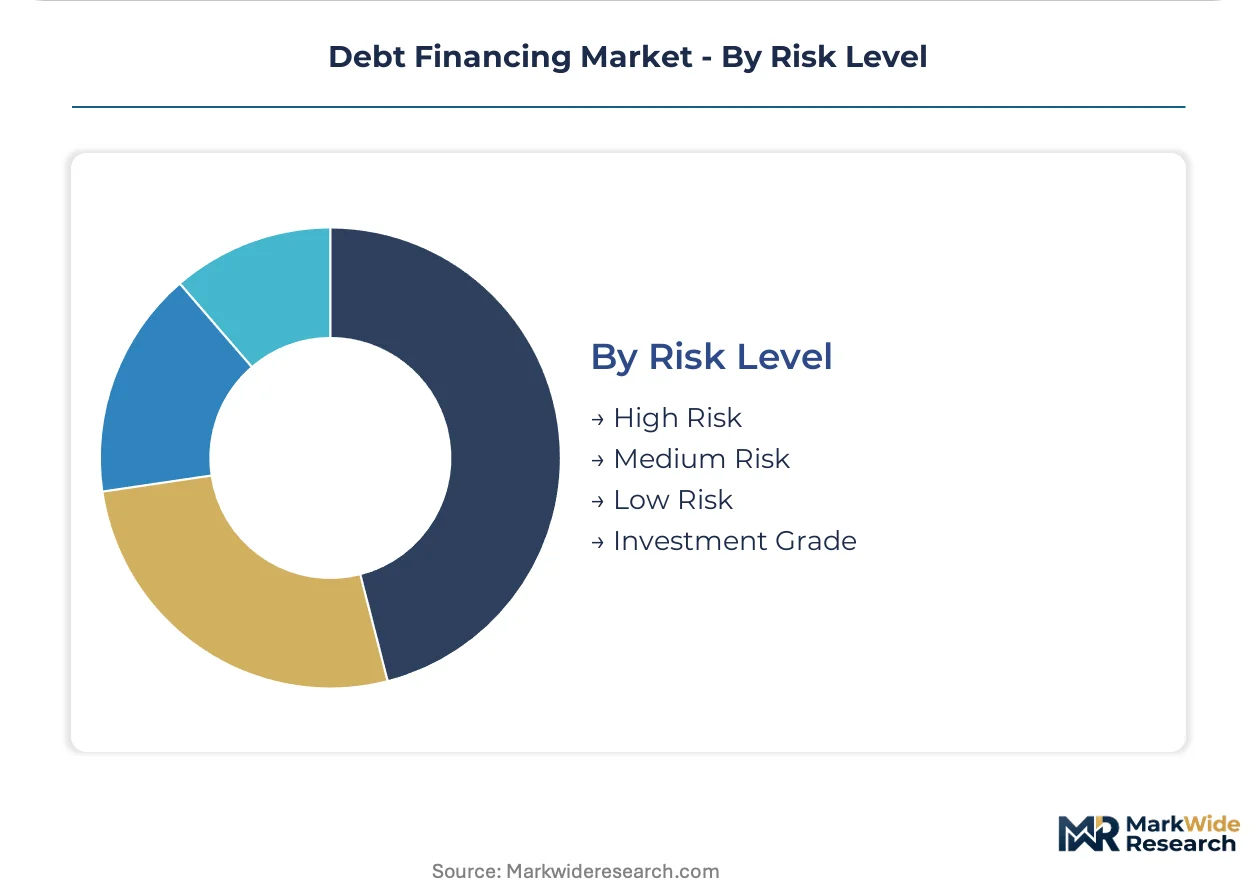
Risk Level:
Credit rating assignments and internal risk scoring systems segment pricing grids with nonlinear spread escalation at rating threshold boundaries.
- High Risk:Speculative-grade and distressed exposures with elevated default probability and recovery rate uncertainty. CCC-rated issuers in US shale oil and European retail sectors trade at significant yield premiums to compensate volatility.
- Medium Risk:BB-rated and split-rated credits with stable cash flows but limited financial flexibility or competitive positioning concerns. European telecommunications operators and US healthcare services companies populate this tier.
- Low Risk:Investment-grade ratings with strong coverage ratios and diversified revenue bases. Utilities in Germany and consumer staples multinationals access compressed spreads through benchmark issuance programs.
- Investment Grade:BBB-minus and above ratings qualifying for central bank purchase programs and regulated institutional mandates. Sovereign wealth funds and central banks concentrate allocations in this tier for liquidity and capital preservation.
Investment grade captures placement volume dominance; high risk is expanding most quickly as private credit funds assume bank-disintermediated exposures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delaware's corporate law framework and tax-efficient domicile structures attract debt issuance headquarters, concentrating legal and administrative functions for capital markets activity in the United States.
United States
Utility-scale renewable developers and technology buyout sponsors drive syndicated loan volume. SEC climate disclosure rules and Federal Reserve stress testing reshape lender capital allocation. New York City's financial district anchors primary market underwriting for investment-grade corporate bonds.
China
State-backed solar manufacturers and wind farm operators expand green loan portfolios. Dual carbon goals and PBoC targeted lending facilities direct credit toward decarbonization infrastructure. Yangtze River Delta industrial clusters absorb term debt for battery and EV supply chain expansion.
Germany
Automotive suppliers and industrial Mittelstand borrowers access Schuldschein private placement markets. EU Green Deal taxonomy alignment and Bundesbank collateral eligibility criteria elevate green bond demand. Frankfurt's banking quarter concentrates sustainable finance structuring expertise.
India
Infrastructure debt funds channel institutional capital toward transport and energy assets. RBI regulatory forbearance for long-term financing vehicles and NIIF capital commitments expand non-bank lending capacity. Mumbai's financial centers host primary issuance for rupee-denominated corporate bonds.
United Kingdom
Private equity sponsors and real estate investment trusts drive leveraged finance activity. FCA consumer duty rules and BoE macroprudential policy constrain riskier lending segments. London's City district maintains dominance in cross-border syndicated loan arrangement and high-yield bond underwriting.
Debt Financing Market Vendor Landscape
Top-tier universal banks anchor primary market underwriting, while regional specialists and direct lending funds capture middle-market share. The vendor base stratifies across balance-sheet scale, geographic coverage, and product specialization archetypes. Strategic differentiation centers on sustainability-linked structuring capabilities and private credit fund formation. Competitive moves concentrate on green bond franchise expansion and direct lending platform acquisitions.
Among US-based banking groups, JPMorgan Chase and Co., Bank of America Corp., and Morgan Stanley occupy positions across investment-grade and leveraged finance segments. Deutsche Bank AG exemplifies European green bond underwriting specialization. Banco Santander SA represents Iberian and Latin American market coverage. Barclays PLC and Citigroup Inc. anchor transatlantic syndication capabilities. The Goldman Sachs Group Inc. and European Investment Bank sit within distinct archetypes—commercial investment banking versus supranational development finance.
| Leading Market Players |
|---|
| Banco Santander SA |
| Bank of America Corp. |
| Barclays PLC |
| Citigroup Inc. |
| Deutsche Bank AG |
| JPMorgan Chase and Co. |
| Morgan Stanley |
| The Goldman Sachs Group Inc. |
| European Investment Bank |
| Others |
Supply Flow & Price Mechanics
EU Green Deal taxonomy alignment gates qualified supply for green bond underwriting mandates and premium-tier pricing access for sustainability-linked loan arrangers. Borrowers lacking verified ESG data infrastructure face spread penalties of 15-25 basis points while certified green frameworks command institutional allocation priority.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid execution capacity with premium fees. Debt arrangers price short-fuse syndications at 15-30 basis point premiums over standard-timeline mandates. Spread differentiation hinges on credit rating tier and sustainability certification level. Pricing pressure stems from private credit fund competition compressing arrangement fees in middle-market leveraged finance. Sponsor-backed borrowers show lowest price sensitivity; municipal utilities exhibit highest spread negotiation leverage.
Supply Chain Analysis
Single-source vulnerability sits with New York-based primary dealer networks for investment-grade corporate bond distribution. Capital formation infrastructure concentrates in the United States, United Kingdom, and Germany. Arranger capacity draws from balance-sheet scale, regulatory licensing, and institutional investor relationships. Supply chain risk centers on Basel III output floor implementation constraining syndicated loan appetite. Distribution runs through bookrunner-led syndication with institutional allocation priority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. SEC climate disclosure rules and EU CSRD mandates erect barrier-to-entry moats for arrangers with verified ESG data infrastructure and third-party attestation capabilities.
For Market Incumbents: Deepen sustainability-linked structuring capabilities to defend against private credit fund disintermediation. Expand green bond franchise through EU taxonomy-aligned underwriting. Invest in climate risk modeling talent to maintain pricing power as ESG data integration reshapes loan documentation. For New Entrants and Emerging Players: Begin with tokenized private placement platforms targeting retail-accessible credit exposures. India's infrastructure debt fund ecosystem offers the most penetrable geography for non-bank lending vehicles. Pursue RBI regulatory forbearance partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Direct lending fund formation velocity is the leading indicator that private credit capacity will sustain middle-market share capture. Target direct lending platforms with established LP relationships and construction-to-term debt transition expertise. Watch for ECB targeted longer-term refinancing operation tapering as the signal for bank-lending capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Green Bond Franchise Expansion | EU taxonomy alignment unlocks institutional capital from ESG-mandated investors in Germany and Netherlands. |
| Direct Lending Platform Acquisition | Private credit fund formation captures middle-market share as Basel III constrains bank syndication capacity. |
| Sustainability-Linked Structuring Capability Buildout | Science-based target margin ratchets generate recurring fee income from corporate borrower relationships. |
| Climate Risk Data Infrastructure Investment | Transition scenario modeling addresses CSRD disclosure mandates and reduces portfolio concentration risk. |
| Tokenized Settlement Infrastructure Pilot | Distributed ledger compression of T+2 cycles reduces trustee reconciliation costs for private placements. |
Methodological Framework
Multi-period observation of syndicated loan volume, green bond issuance flows, and private credit fundraising anchored the trend analysis, supplemented by interviews with debt capital markets heads, ESG structuring specialists, institutional portfolio managers, and regulatory policy officers. Primary fieldwork triangulated against SEC filings, ECB statistical releases, ICMA green bond database records, and AFME primary market reports. Bottom-up instrument-level tracking converged with top-down macro credit flow analysis.
Input-output matrix modeling linked borrower demand segmentation to arranger capacity constraints and investor allocation shifts across the projection horizon. Segmentation dimensions spanned instrument type, investor category, financing purpose, and risk rating tier. CAGRs derived from fitted trend extrapolation with regime-switch adjustments for regulatory implementation phases. Forecast inputs incorporated Federal Reserve stress test scenario evolution and PBoC green lending facility expansion trajectories.
Central bank quantitative tightening acceleration, Basel III output floor implementation delays, and climate disclosure mandate enforcement variance are the dominant revision risks to modeled trajectories. Forecasts embed assumptions about regulatory timeline adherence and institutional ESG mandate penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
Global Mortgage Lender Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Global Healthcare Equipment Leasing Market