
 China Mortgage/Loan Brokers Market | 2026-2036
China Mortgage/Loan Brokers Market Size, Share, and Industry Trends Forecast 2026-2036
China Mortgage/Loan Brokers Market Insights
China's shadow banking sector is restructuring its intermediary role as formal mortgage brokerage gains legitimacy under tighter SAMR oversight. Lianjia (Beijing) Technology Co., Ltd. leverages its nationwide storefront network to anchor physical presence in Beijing and Shanghai. Ke Holdings Inc. competes through proprietary transaction data layers that streamline borrower-lender matching. FangDD differentiates by specializing in developer-linked commercial loan origination across southern provincial hubs.
Mortgage and loan brokers function as licensed intermediaries that aggregate borrower credit profiles, assess debt-service ratios against property valuations, and submit packaged applications to multiple lending institutions for rate optimization. Their primary commercial purpose is reducing information asymmetry between retail borrowers and capital providers while accelerating approval timelines. Online brokers are capturing the fastest expansion as mobile-first platforms displace traditional branch-dependent consultation, while bank-affiliated brokers retain the deepest margin pools through captive referral arrangements with state-owned lenders. Independent brokers occupy a structurally pressured position as regulatory capital requirements and technology investment needs escalate.
The People's Bank of China shapes demand through loan prime rate adjustments and mortgage quota allocations to state banks, while SAMR enforces anti-competitive practice prohibitions across digital brokerage platforms. NMPA-aligned consumer protection standards for financial intermediaries are tightening disclosure obligations on fee structures and product suitability. Stakeholders must monitor how property sector deleveraging mandates reshape broker commission structures and whether online platforms face new licensing tiers that favor incumbents with existing banking partnerships.
Market Dynamics
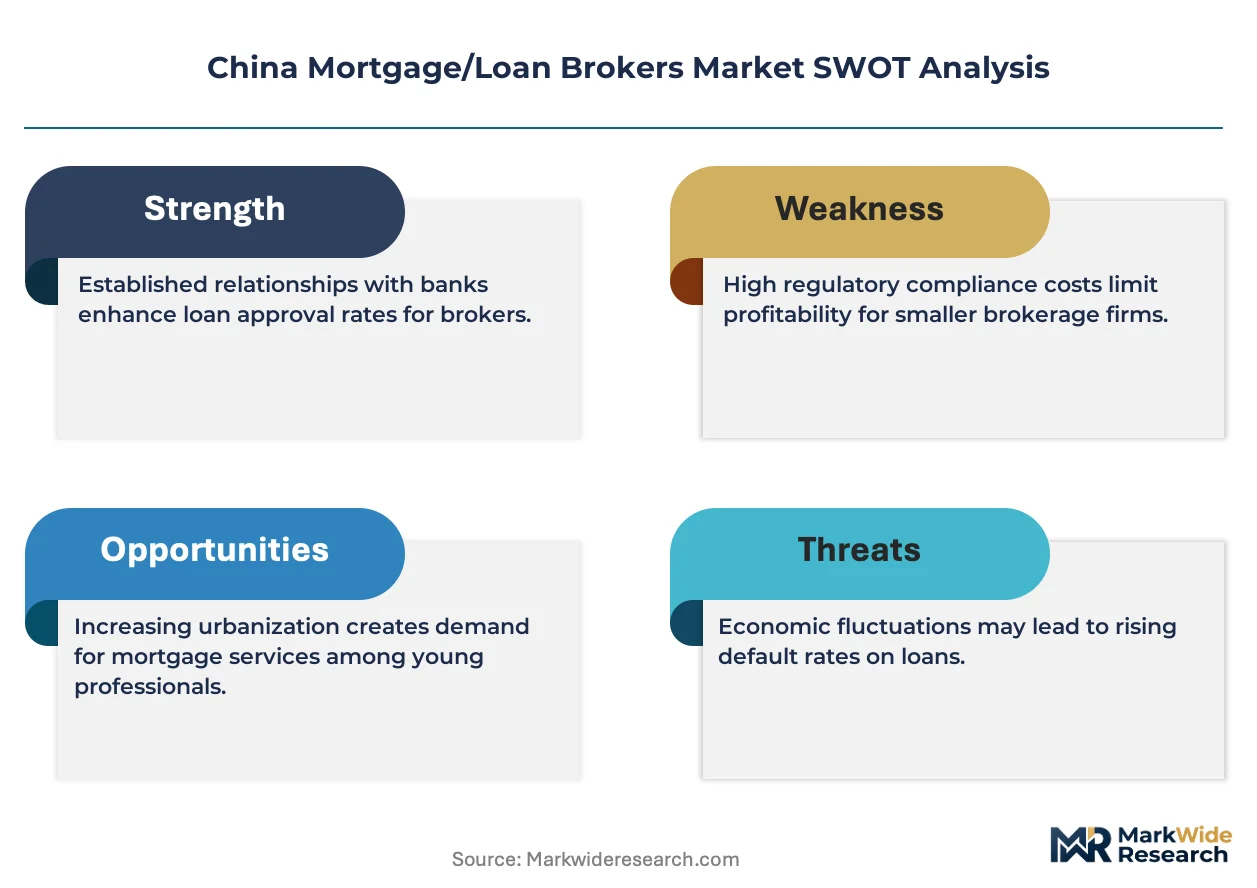
The People's Bank of China's loan prime rate recalibration is compressing broker commission spreads while forcing intermediaries to migrate from transaction volume models toward advisory fee structures. SAMR's platform governance rules are simultaneously elevating compliance costs for independent operators.
Growth Catalysts
- Policy Rate Adjustment:The People's Bank of China's mortgage quota allocations to state-owned banks are channeling credit toward tier-two city first-time buyers, expanding broker addressable demand in Chengdu, Wuhan, and Xi'an metropolitan clusters.
- Mobile Platform Migration:Smartphone-native loan comparison interfaces are collapsing borrower search costs and aggregating fragmented lender rate data into real-time competitive bidding environments.
- Shadow Banking Formalization:SAMR licensing requirements for financial intermediaries are displacing unregulated credit matchmakers and consolidating legitimate volume toward licensed brokerage networks.
Market Restraints
- Capital Reserve Requirements:SAMR-mandated operational capital thresholds for brokerage licensing are excluding smaller independent operators from formal market participation.
- State Bank Captive Networks:Bank-affiliated brokers maintain exclusive referral arrangements with Agricultural Bank of China and Industrial and Commercial Bank of China, constraining independent broker access to prime borrower segments.
- Property Valuation Compression:Collateral appraisal methodology revisions by housing administration bureaus in Beijing and Shanghai are elongating loan approval timelines and compressing broker transaction velocity.
Strategic Opportunities
- Yangtze River Delta Digital Hubs:Suzhou and Hangzhou satellite cities exhibit concentrated demand for online broker platforms serving technology sector employees with non-standard income documentation.
- Developer-Linked Commercial Origination:Southern provincial construction finance pipelines in Guangdong and Fujian present origination volume for brokers specializing in presale mortgage packaging and construction-to-permanent loan transitions.
- NMPA Consumer Protection Alignment:Enhanced disclosure mandates for fee structures and product suitability are creating competitive differentiation for brokers with transparent pricing architectures.
Industry Challenges
- Data Science Talent Scarcity:Proprietary credit scoring algorithm development requires machine learning specialists whose compensation demands exceed traditional brokerage margin structures.
- Legacy System Integration:Bank core banking system interfaces demand expensive API development and maintenance contracts that strain independent broker technology budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Mortgage/Loan Brokers Market |
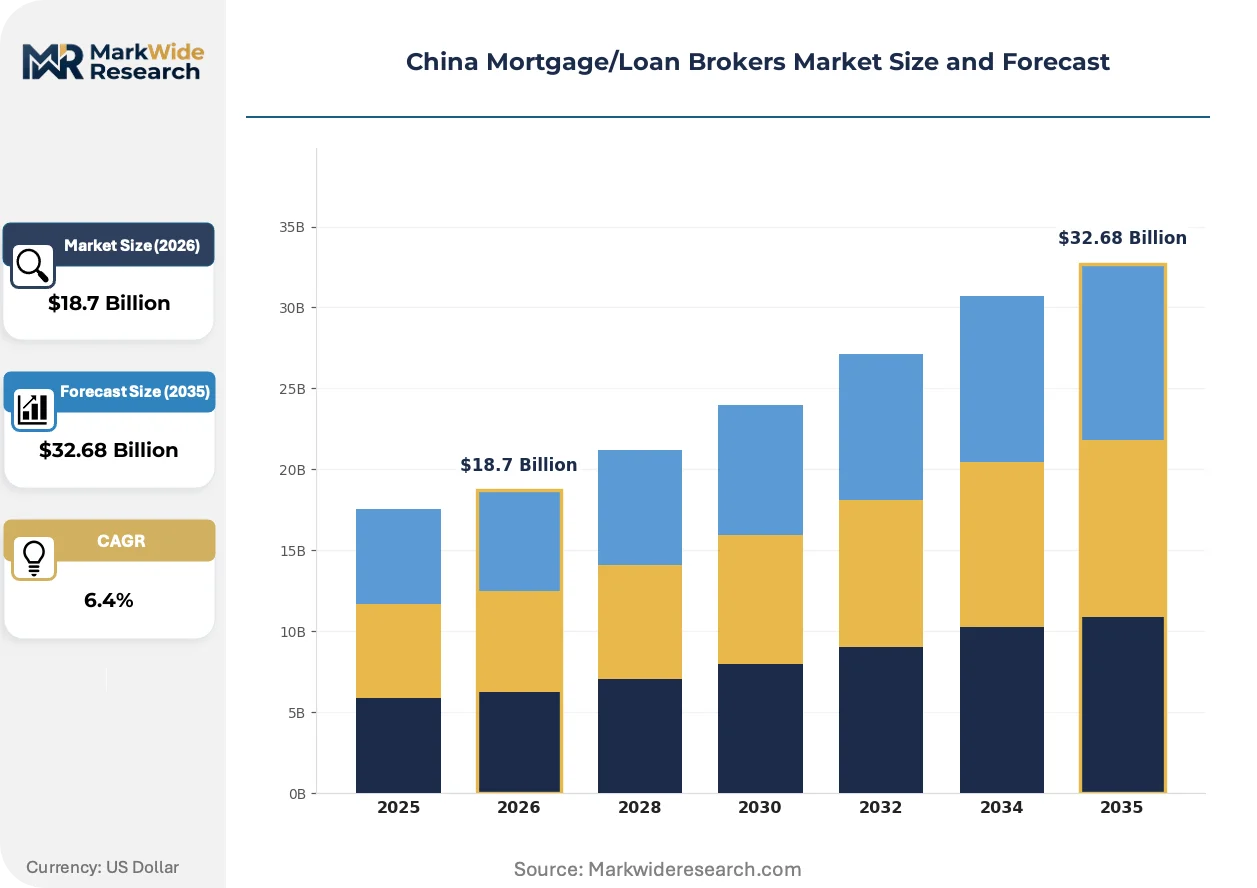
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Broker Type: Independent Brokers, Bank-affiliated Brokers, Online Brokers, Full-service Brokers Loan Type: Home Loans, Personal Loans, Commercial Loans, Refinancing Loans Client Type: First-time Buyers, Investors, Homeowners, Real Estate Developers Service Model: Mortgage Advisory, Loan Processing, Rate Negotiation, Application Support |
| Companies Covered | Lianjia (Beijing) Technology Co., Ltd., E-House (China) Enterprise Holdings Limited, Ke Holdings Inc., 58.com Inc., FangDD, Zhaohui Group, Fangtianxia, Lufax Holding Ltd., Yixin Group Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Mortgage/Loan Brokers Market Trends and Innovations
Artificial intelligence underwriting engines and blockchain-secured property title verification are restructuring how Chinese mortgage intermediaries authenticate borrower creditworthiness and accelerate collateral clearance timelines.
Machine learning risk scoring is rewriting the economics of borrower-lender matching in China's mortgage brokerage sector. Tier-one city digital platforms are deploying these engines to pre-approve loan applications within minutes rather than days. The compression of approval timelines is eliminating traditional branch-based consultation as the default channel for affluent borrowers.
SAMR's anti-competitive practice prohibitions for digital brokerage platforms are mandating data portability and restricting exclusive lender partnerships. Independent brokers in Shenzhen and Guangzhou are leveraging these rules to access previously captive lender rate feeds. The regulatory friction is most acute for incumbent platforms with historical banking exclusivity arrangements.
First-time buyers in tier-two cities are abandoning branch-dependent consultation for mobile-first loan comparison interfaces. Younger demographic cohorts in Xi'an and Changsha are completing entire mortgage applications through smartphone platforms without physical broker meetings. This behavioral pivot is most visible among technology sector employees with standardized digital income documentation and high credit literacy.
China Mortgage/Loan Brokers Market Segmentation
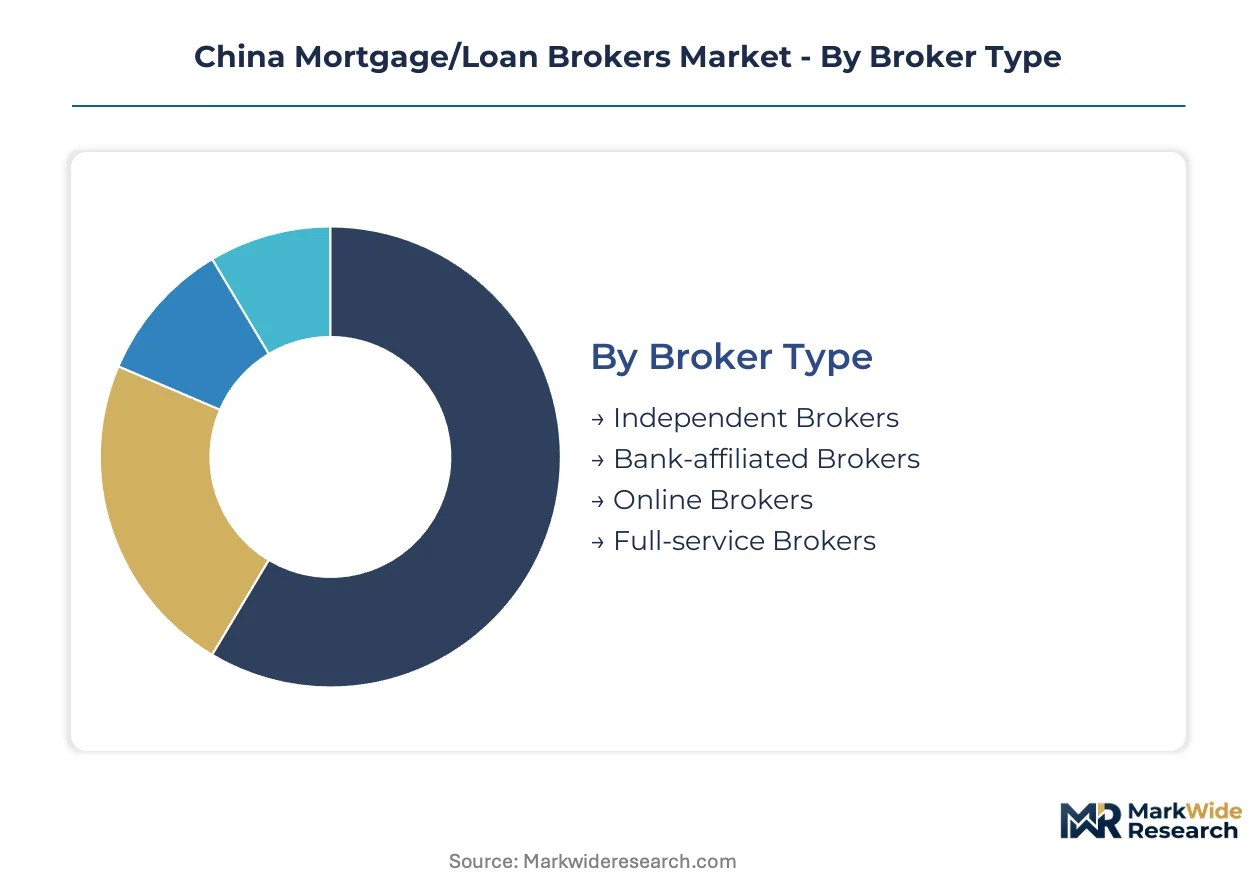
Brokerage type and service delivery channel determine commission structures, regulatory exposure, and technology investment requirements across China's mortgage intermediary landscape. Borrower sophistication and property transaction complexity shape which segmentation dimension carries greatest weight in tier-one versus tier-two city markets.
Broker Type:
Capital intensity and regulatory licensing thresholds drive buyer selection between affiliation models.
- Independent Brokers:These operators maintain no exclusive lender relationships and source rate quotes across competing banks. First-time buyers in Chengdu and Wuhan favor independent brokers for comparison transparency as SAMR licensing requirements displace unregulated matchmakers. Margin pressure intensifies from technology investment mandates and operational capital thresholds.
- Bank-affiliated Brokers:Captive referral arrangements with Agricultural Bank of China and Industrial and Commercial Bank of China deliver prime borrower segments. Exclusive rate feeds from state-owned lenders constrain competitive positioning for independent rivals. Commission pools remain deepest where banking partnerships lock in affluent mortgage demand.
- Online Brokers:Mobile-first platforms aggregate fragmented lender rate data into real-time bidding environments. Smartphone-native interfaces collapse borrower search costs among technology sector employees with standardized digital income documentation.
- Full-service Brokers:These operators combine mortgage advisory with property search and legal documentation services. Developer-linked commercial origination in Guangdong and Fujian construction finance pipelines sustains revenue diversification.
Bank-affiliated brokers lead on scale; online brokers lead on momentum.
Loan Type:
Collateral risk profiles and regulatory quota allocations shape origination economics across product categories.
- Home Loans:Residential mortgage packaging dominates broker transaction volume through first-time buyer programs in tier-two cities. People's Bank of China loan prime rate adjustments directly compress spreads on standardized 20-30 year amortization products.
- Personal Loans:Unsecured consumer credit intermediation requires alternative data scoring for income verification outside formal payroll systems. Younger demographic cohorts in Xi'an complete applications through smartphone platforms without physical meetings.
- Commercial Loans:Developer-linked construction finance and presale mortgage packaging demand specialized collateral appraisal expertise. Southern provincial hubs in Guangdong present concentrated origination volume for brokers with construction-to-permanent transition capabilities.
- Refinancing Loans:Rate arbitrage opportunities emerge when People's Bank of China recalibrations create spreads between existing and prevailing mortgage rates. Transaction velocity fluctuates with policy cycle timing.
Home loans anchor volume concentration; commercial loans command premium pricing.
Client Type:
Credit documentation standardization and transaction frequency differentiate service requirements across borrower segments.
- First-time Buyers:Tier-two city metropolitan clusters in Chengdu, Wuhan, and Xi'an exhibit expanding broker engagement as mortgage quotas channel credit toward this demographic. High credit literacy among technology sector employees accelerates mobile platform adoption.
- Investors:Multiple property holding structures demand complex debt-service ratio optimization across leveraged portfolios. Regulatory property sector deleveraging mandates reshape commission structures for speculative acquisition financing.
- Homeowners:Existing mortgage holders generate refinancing demand and home equity extraction requests. Collateral appraisal methodology revisions in Beijing and Shanghai elongate approval timelines.
- Real Estate Developers:Construction finance pipelines and presale mortgage packaging require broker specialization in commercial loan origination. Southern provincial hubs concentrate this demand.
First-time buyers expand addressable market breadth; developers concentrate value per transaction.
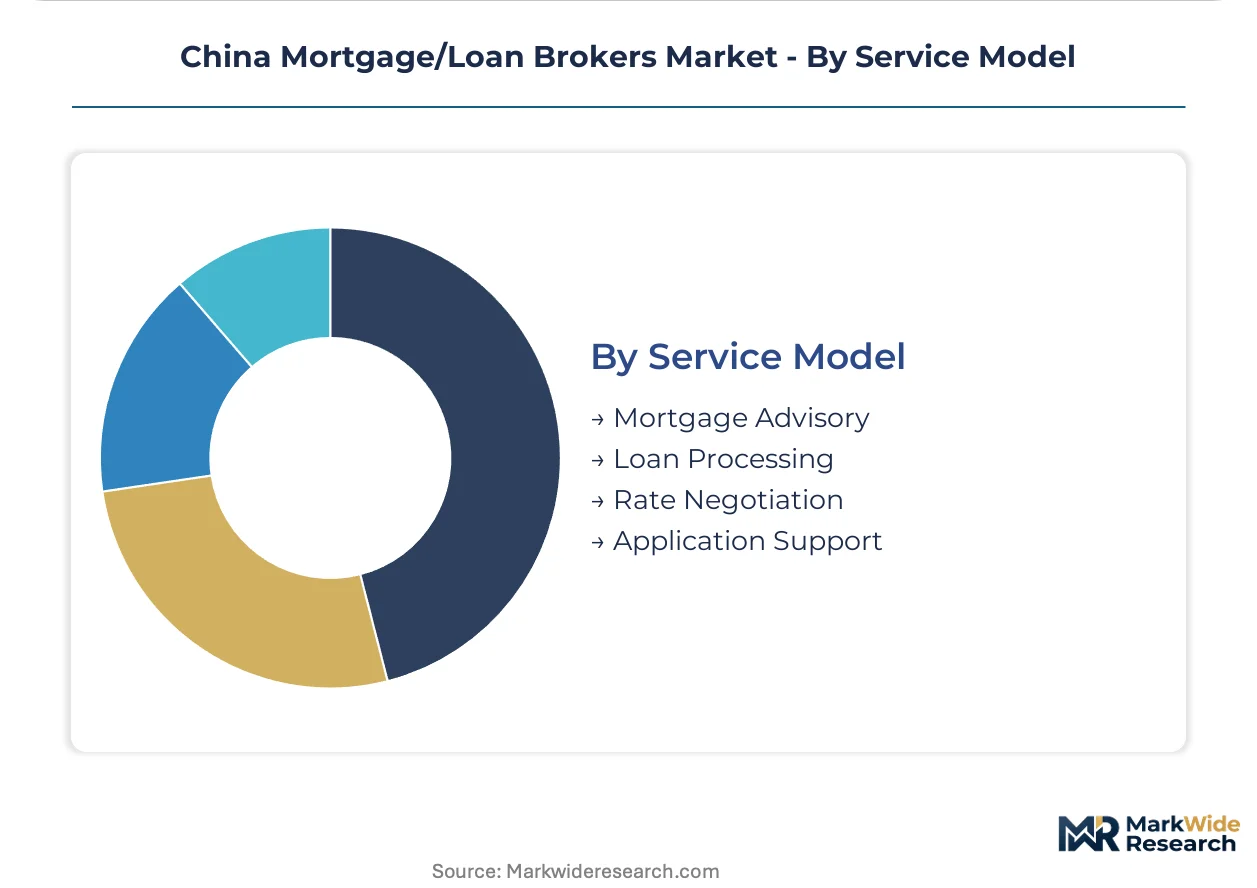
Service Model:
Fee structure transparency and regulatory disclosure obligations differentiate competitive positioning across advisory depth levels.
- Mortgage Advisory:Comprehensive borrower financial profiling and product suitability assessment command advisory fee structures. NMPA-aligned consumer protection standards tighten disclosure obligations on fee transparency.
- Loan Processing:Documentation compilation and lender submission logistics accelerate approval timelines. Machine learning risk scoring compresses processing intervals from days to minutes on digital platforms.
- Rate Negotiation:Multi-lender quote aggregation and term optimization reduce information asymmetry between retail borrowers and capital providers. SAMR anti-competitive practice prohibitions mandate data portability.
- Application Support:End-to-end submission management through approval and closing reduces borrower administrative burden. Legacy system integration with bank core banking interfaces strains independent broker technology budgets.
Loan processing captures highest transaction frequency; mortgage advisory commands fee premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between provincial licensing regimes is channeling broker formation toward jurisdictions with lower SAMR operational capital thresholds. Cost-of-compliance gaps between tier-one and tier-two city bureaus are accelerating this migration pattern.
Yangtze River Delta
Technology sector employees with non-standard income documentation drive concentrated demand for mobile-first platforms. SAMR platform governance rules elevate compliance costs for independent operators throughout Suzhou and Hangzhou satellite cities. Shanghai anchors the corridor's deepest commission pools through captive banking partnerships.
Pearl River Delta
Developer-linked commercial loan origination sustains broker specialization in construction finance pipelines. SAMR anti-competitive practice prohibitions mandate data portability for digital platforms across Shenzhen and Guangzhou. Southern provincial hubs in Guangdong present concentrated origination volume for presale mortgage packaging.
Beijing-Tianjin-Hebei
First-time buyer programs expand broker engagement as mortgage quotas channel credit toward qualifying borrowers. NMPA-aligned consumer protection standards tighten disclosure obligations on fee structures throughout the capital region. Collateral appraisal methodology revisions elongate approval timelines in Beijing municipal jurisdiction.
Sichuan-Chongqing
High credit literacy among younger demographic cohorts accelerates smartphone-native platform adoption. SAMR licensing requirements for financial intermediaries displace unregulated credit matchmakers across Chengdu metropolitan cluster. Independent brokers capture comparison-transparent demand from price-sensitive first-time buyers.
Central China Corridor
Wuhan and Xi'an metropolitan clusters exhibit expanding broker addressable demand from policy-directed credit flows. The People's Bank of China loan prime rate adjustments directly compress spreads on standardized amortization products throughout Hubei and Shaanxi provinces. Mobile platform migration collapses borrower search costs in these emerging tier-two markets.
China Mortgage/Loan Brokers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue advisory fee structures beyond transaction volume models. The market structures around three distinct player tiers: bank-affiliated incumbents with captive lender relationships, technology-enabled platforms aggregating fragmented rate data, and independent operators facing escalating capital reserve requirements. Strategic archetypes include storefront-network incumbents, mobile-first aggregators, and developer-linked commercial specialists. Dominant competitive moves center on proprietary data layer investments and multi-lender API integration partnerships.
Within the technology-enabled tier, Ke Holdings Inc. and Lianjia (Beijing) Technology Co., Ltd. exemplify divergent platform architectures. Ke Holdings occupies a position emphasizing data-driven borrower-lender matching capabilities. Lianjia anchors the physical-digital hybrid model through nationwide storefront presence. FangDD represents the developer-linked commercial origination archetype with southern provincial concentration. These three entities collectively illustrate the market's segmentation across digital aggregation, omnichannel coverage, and construction finance specialization.
| Leading Market Players |
|---|
| Lianjia (Beijing) Technology Co., Ltd. |
| E-House (China) Enterprise Holdings Limited |
| Ke Holdings Inc. |
| 58.com Inc. |
| FangDD |
| Zhaohui Group |
| Fangtianxia |
| Lufax Holding Ltd. |
| Yixin Group Limited |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals mandate operational energy efficiency standards that gate qualified supply access for brokerage technology vendors and premium-tier pricing for platforms with verified green data center credentials. SAMR licensing thresholds further stratify market access, concentrating pricing power among incumbents with compliant infrastructure while independent operators absorb compliance-driven cost escalation.
Pricing Analysis
Commission spreads anchor the dominant pricing structure across China's mortgage brokerage sector, with advisory fee overlays gaining traction as rate compression forces migration from pure transaction volume models. Price differentiation stems from SAMR licensing tier and proprietary data layer depth, with bank-affiliated brokers commanding premium positioning through exclusive lender rate feeds. Cost compression in the independent broker tier is intensifying because capital reserve requirements and API integration expenses erode margin structures. First-time buyers in tier-two cities exhibit highest price sensitivity, while technology sector employees with non-standard income documentation demonstrate lowest sensitivity due to limited alternative service options.
Supply Chain Analysis
Dual-sourcing requirements for core banking system interfaces mandate that major brokerage platforms qualify multiple API integration partners beyond single-state-bank dependencies. Technology supply concentrates in China, with specialized machine learning talent pools anchored in Beijing and Shenzhen, while cloud infrastructure draws from domestic hyperscalers and regional data center operators. Raw material dependencies center on proprietary credit scoring algorithms, mobile application frameworks, and blockchain verification protocols. Single-source vulnerability persists where Agricultural Bank of China and Industrial and Commercial Bank of China maintain exclusive referral arrangements with captive broker networks. Distribution runs through mobile-first platforms displacing traditional branch-dependent consultation, with developer-linked commercial origination channels sustaining parallel physical presence in southern provincial hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's mortgage brokerage sector represents a late-cycle quality story as first-time buyers in tier-two cities pivot toward transparent fee structures and NMPA-aligned consumer protection standards reshape competitive positioning toward premium advisory specifications.
For Market Incumbents: To counter SAMR-mandated data portability rules eroding exclusive lender partnerships, Ke Holdings Inc. and Lianjia must deepen proprietary transaction data layers through multi-lender API integration partnerships and expand advisory fee revenue streams beyond transaction-dependent commissions. Certification investment in NMPA-aligned disclosure architectures will defend positioning against emerging digital entrants. For New Entrants and Emerging Players: Mobile-native loan comparison interfaces offer the most penetrable white-space target among technology sector employees in Suzhou and Hangzhou satellite cities with standardized digital income documentation and high credit literacy. A go-to-market angle centered on real-time competitive bidding environments for non-standard borrower profiles can circumvent incumbent captive banking relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional independent broker networks because SAMR capital reserve requirements are accelerating consolidation toward licensed operators with compliant infrastructure. Long-term viability favors platforms with demonstrated API integration capabilities and advisory fee revenue diversification. The signal to watch is People's Bank of China loan prime rate recalibration frequency as an indicator of commission spread compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Data Layer Investment | Machine learning risk scoring engines compress approval timelines from days to minutes for affluent borrowers. |
| Multi-Lender API Integration | SAMR data portability mandates enable access to previously captive Agricultural Bank of China rate feeds. |
| Advisory Fee Structure Migration | NMPA disclosure obligations create competitive differentiation through transparent pricing architectures. |
| Developer-Linked Commercial Origination | Construction finance pipelines in Guangdong and Fujian sustain revenue diversification beyond residential mortgages. |
| Mobile-First Platform Expansion | Smartphone-native interfaces collapse borrower search costs among technology sector employees in tier-two cities. |
Research Methodology
Coverage spans China's tier-one and tier-two city metropolitan clusters, with primary inputs from each region's distinct regulatory and demand environments. The analysis combines primary interviews with mortgage brokerage executives, SAMR compliance officers, state bank lending desk managers, and property developer finance directors with secondary validation from People's Bank of China policy circulars, SAMR licensing registries, NMPA consumer protection guidelines, and provincial housing administration bureau collateral appraisal methodologies. Bottom-up transaction volume modeling and top-down macroeconomic scenario triangulation anchor market size estimation.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with segmentation dimensions spanning broker type, loan category, client archetype, and service delivery model. CAGRs were derived through regression analysis of historical loan origination trends against People's Bank of China policy rate cycles and property sector deleveraging mandate intensity. Industry-specific forecast inputs include mobile platform penetration rates among technology sector employees and SAMR licensing approval velocity for financial intermediaries.
The model assumes a particular technology adoption path; alternative pathways for artificial intelligence underwriting engines or blockchain title verification would alter the outlook through accelerated timeline compression or regulatory friction. Forecasts reflect assumptions regarding SAMR enforcement consistency and state bank quota allocation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
South Korea Auto Loan Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Australia Education Student Loans Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
UK Mortgage / Loan Broker Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Asset-Based Lending Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
Payday Loans Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market